
 Billing and Revenue Management Market | 2026-2036
Billing and Revenue Management Market Size, Share, and Industry Trends Forecast 2026-2036
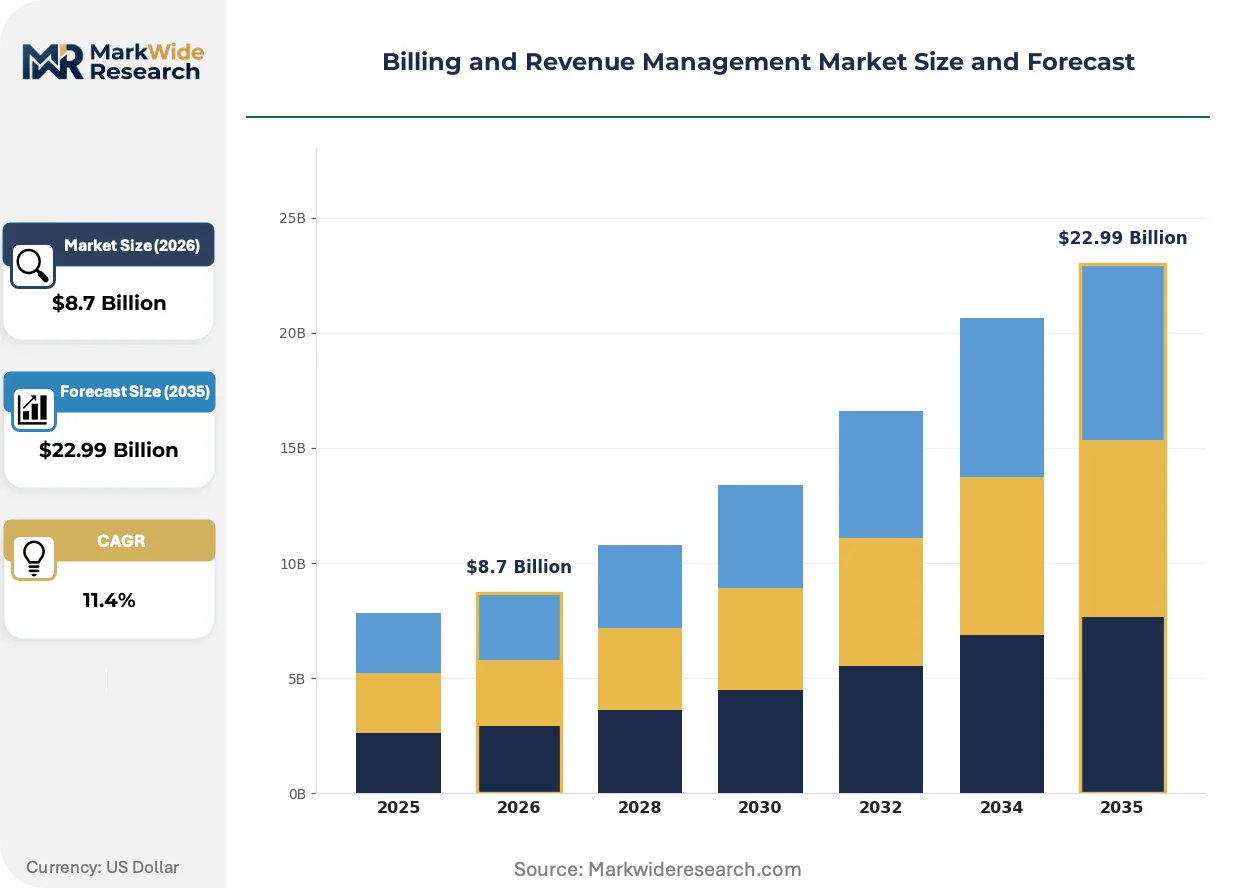
Billing and Revenue Management Market Outlook
Platform licensing revenue is fragmenting away from perpetual software contracts toward recurring SaaS arrangements. Amdocs leverages its installed base across tier-one telecom operators to sustain long-term service contracts. Oracle anchors enterprise billing through deep database integration, while Zuora specializes in subscription monetization tools for recurring-revenue business models.
Billing and revenue management encompasses software systems that automate customer invoicing, payment collection, revenue recognition, and financial reporting across complex pricing structures and contract terms. These platforms typically process millions of transactions daily while enforcing tax jurisdiction rules, discount policies, and usage-based rating engines for metered services. Cloud-based deployment models now capture the fastest expansion as enterprises abandon capital-intensive on-premise infrastructure for elastic consumption models. Payment processing solutions command concentrated margin pools due to embedded fintech partnerships and interchange economics, whereas billing analytics remains nascent but gains traction as finance teams demand real-time revenue intelligence.
FCC regulations in the United States mandate accurate billing disclosure and cramming prevention for telecom subscribers, directly shaping platform compliance requirements. EMA and national telecom regulators across Europe enforce GDPR-aligned customer data handling within billing systems, raising architectural standards for cross-border operators. Stakeholders must monitor how AI-augmented rating engines alter audit trails and regulatory scrutiny before committing to platform modernization roadmaps.
Market Dynamics
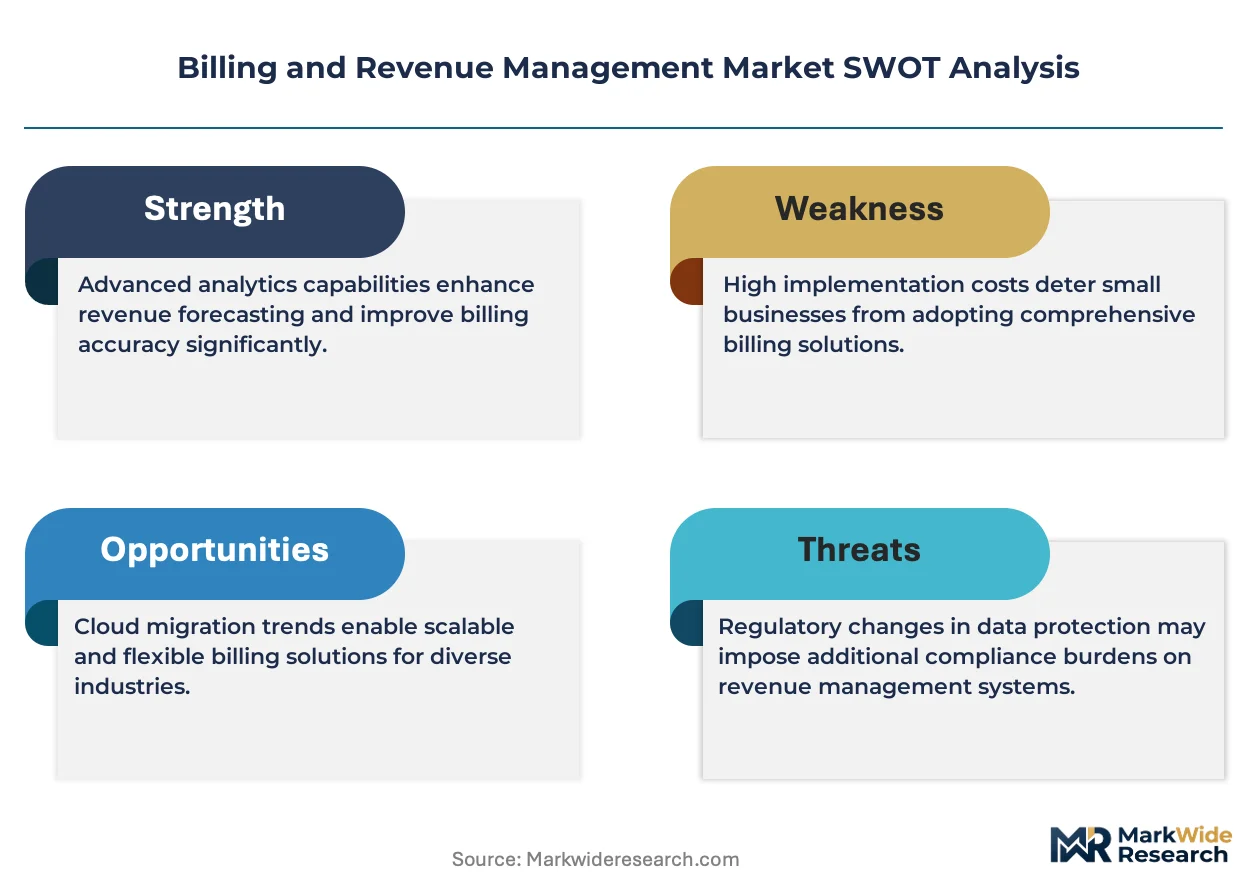
Cloud-native billing platforms are virtualizing core revenue operations, forcing incumbent vendors to rearchitect monolithic systems into microservices or risk displacement by API-first challengers. TRAI's digital compliance mandates in India and FCC disclosure requirements in the United States are accelerating this infrastructure turnover.
Growth Catalysts
- GDPR-aligned data handling:EMA enforcement across European telecom operators mandates encrypted billing records and cross-border data sovereignty, compelling platform upgrades.
- Usage-based rating engines:Metered 5G and IoT services require real-time consumption tracking, pulling investment into scalable cloud rating architectures.
- India's cloud migration:Reliance Jio and Bharti Airtel are replacing legacy on-premise billing with elastic SaaS deployments to meet TRAI's evolving digital KYC integration rules.
Market Restraints
- Interchange economics concentration:Embedded fintech partnerships lock margin pools within three dominant payment processors, squeezing standalone billing vendors.
- Legacy system entrenchment:Tier-one telecom operators in Germany and Japan carry decades of custom rating logic that resists API abstraction.
- Revenue recognition complexity:Multi-element subscription bundles trigger ASC 606 and IFRS 15 audit scrutiny, extending sales cycles for new platform adoption.
Strategic Opportunities
- AI-augmented audit trails:Machine learning rating engines can automate compliance documentation for FCC and TRAI examinations, creating differentiation.
- Brazilian telecom modernization:ANATEL's convergence rules are pushing regional carriers toward cloud billing, opening Latin America's largest market.
- Real-time revenue intelligence:Finance teams in SaaS enterprises now demand embedded analytics, expanding billing platforms into CFO workflow tools.
Industry Challenges
- Microservices integration complexity:Enterprises struggle to reconcile containerized billing modules with existing ERP systems, delaying go-live dates.
- Revenue operations talent scarcity:Shortage of engineers fluent in both telecommunications rating and cloud-native architecture constrains deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Billing and Revenue Management Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Invoicing Software, Revenue Recognition, Payment Processing, Billing Analytics Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS End User: Telecom, Utilities, Healthcare, E-Commerce Service Type: Consulting, Integration, Managed Services, Support |
| Companies Covered | Amdocs, Netcracker, SAP SE, Oracle, Huawei Technologies, Comviva, CSG Systems, Optiva, Zuora, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Billing and Revenue Management Market Strategic Shifts
Embedded finance partnerships are rewiring how billing platforms capture value, with payment processing and lending services integrating directly into invoicing workflows. Three developments are compressing competitive timelines.
Containerized rating engines are virtualizing core billing infrastructure. Telecom operators in South Korea and Australia are adopting Kubernetes-orchestrated microservices to process millions of daily usage events. This architecture is virtualizing the traditional hardware-software boundary, collapsing capital requirements while scaling transaction throughput.
CSRD disclosure mandates in the European Union now require granular revenue attribution across product lines and geographies. Billing platforms must embed carbon-accounting tags and sustainability metrics directly into invoice generation. Financial services and industrial equipment leasing segments are rebuilding reporting stacks to meet these granular traceability requirements.
Subscription unbundling is fragmenting traditional contract structures. Enterprise buyers now procure billing capabilities as discrete API calls rather than platform licenses, compressing vendor switching costs. This pattern is most pronounced among mid-market SaaS companies in the United States, where finance teams assemble best-of-breed revenue stacks through marketplace integrations.
Billing and Revenue Management Market Segmentation
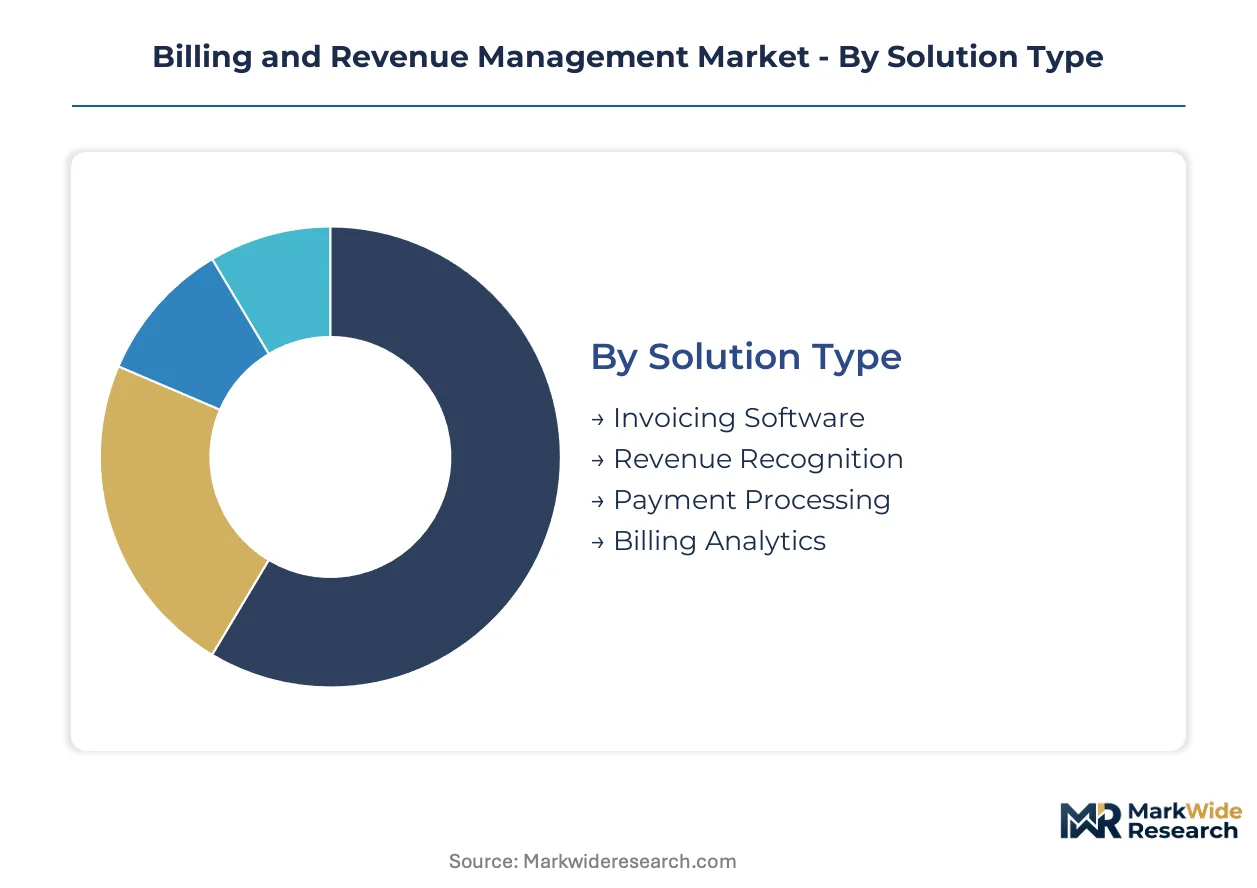
Billing and revenue management platforms serve heterogeneous operational requirements across solution architectures, infrastructure models, industry verticals, and service engagement types. Segmentation reveals how vendor capabilities align with customer complexity thresholds and compliance burdens. Procurement patterns diverge sharply between regulated utilities seeking on-premise control and SaaS-native retailers demanding API elasticity.
Solution Type:
Cost tier differentiation separates commodity transaction processing from high-margin compliance automation layers. Each solution category carries distinct implementation complexity and recurring revenue profiles.
- Invoicing Software:Core modules generate itemized bills, apply tax jurisdiction rules, and manage discount workflows across millions of customer accounts. Telecom operators in India deploy these systems to meet TRAI's digital disclosure mandates while processing prepaid and postpaid hybrid structures.
- Revenue Recognition:Engines automate ASC 606 and IFRS 15 compliance for multi-element contracts, unbundling subscription bundles into performance obligations. SaaS enterprises in the United States concentrate demand here as audit scrutiny intensifies for recurring-revenue business models.
- Payment Processing:Embedded fintech partnerships capture interchange economics through direct ACH, card, and digital wallet integration.
- Billing Analytics:Real-time revenue intelligence tools remain nascent but gain traction among CFO teams seeking consumption pattern visibility.
Invoicing Software holds installed capacity. Revenue Recognition is rotating up the share rankings.
Deployment Model:
Application architecture determines capital intensity, data sovereignty compliance, and integration flexibility with existing ERP ecosystems.
- Cloud-Based:Elastic infrastructure scales transaction throughput for metered 5G and IoT services without hardware procurement cycles. South Korean telecom operators adopt Kubernetes-orchestrated microservices to process usage events in real time.
- SaaS:Subscription licensing eliminates upfront capital expenditure while embedding automatic compliance updates for evolving FCC and GDPR mandates. Mid-market enterprises in North America favor this model for rapid deployment timelines.
- On-Premise:Legacy installations persist among tier-one operators with decades of custom rating logic.
- Hybrid:Split architectures keep sensitive customer data on-premise while bursting compute-intensive rating to public cloud.
Cloud-Based deployments are expanding most quickly. SaaS is climbing the fastest among net-new commitments.
End User:
Customer type segmentation maps regulatory complexity, transaction volume profiles, and pricing structure heterogeneity.
- Telecom:Carriers process billions of usage events daily across voice, data, and content bundles while navigating FCC disclosure rules and TRAI digital KYC integration. This vertical demands the highest rating engine throughput and real-time charging capabilities.
- Utilities:Smart metering infrastructure drives time-of-use billing and demand response programs. European water and electricity distributors embed CSRD-aligned carbon accounting tags directly into invoice generation.
- Healthcare:HIPAA-compliant platforms manage patient billing, insurance adjudication, and revenue cycle workflows.
- E-Commerce:Marketplace operators require split payment routing, seller settlement automation, and cross-border tax calculation.
Telecom retains the deepest legacy footprint. E-Commerce is gaining share fastest as marketplace transaction volumes compound.
Service Type:
Engagement model segmentation reflects customer maturity and internal technical capacity for platform ownership.
- Integration:Professional services reconcile containerized billing modules with SAP, Oracle, and Salesforce ERP ecosystems. German industrial manufacturers drive demand here as they modernize decades-old mainframe connections.
- Managed Services:Outsourced operations handle rating, invoicing, and collections for operators lacking RevOps engineering talent. Bharti Airtel and Reliance Jio leverage these arrangements to accelerate cloud migration timelines.
- Consulting:Advisory engagements map ASC 606 compliance gaps and design target-state revenue architectures.
- Support:Tiered maintenance contracts ensure platform uptime for mission-critical billing cycles.
Integration commands premium pricing. Managed Services is rotating up the share rankings as talent scarcity constrains in-house deployment velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India exhibit the highest price sensitivity, driving aggressive SaaS procurement negotiations, while German operators prioritize system reliability over licensing costs. Demand elasticity varies sharply by regulatory maturity and legacy infrastructure burden.
United States
Enterprise SaaS vendors and tier-one telecom operators anchor North American demand, with finance teams demanding real-time revenue intelligence. FCC disclosure mandates and cramming prevention rules shape platform compliance roadmaps. Silicon Valley clusters host the densest concentration of subscription monetization specialists.
Germany
Industrial manufacturers and utility operators drive hybrid cloud deployments, balancing data sovereignty with elastic scalability. EMA-aligned GDPR enforcement mandates encrypted billing records and cross-border data handling protocols. The Rhine-Ruhr industrial corridor concentrates legacy system modernization projects.
India
Reliance Jio and Bharti Airtel are accelerating cloud-native replacements of on-premise billing infrastructure. TRAI's evolving digital KYC integration rules and compliance mandates force platform turnover. Mumbai and Bangalore clusters host the fastest-growing managed services partnerships.
South Korea
Telecom operators adopt Kubernetes-orchestrated microservices for 5G usage-based rating at massive scale. National regulators enforce strict data localization for customer billing records. Seoul's digital infrastructure hub concentrates containerized rating engine deployments.
Brazil
Regional carriers respond to ANATEL convergence rules by migrating toward cloud billing platforms. National telecom modernization programs unlock Latin America's largest addressable market. São Paulo's financial services corridor drives demand for subscription revenue automation tools.
Billing and Revenue Management Market Competitive Environment
Enterprise software conglomerates and vertical-specialist vendors split the market through divergent integration strategies. Tier-one telecom operators favor end-to-end suites with deep ERP connectivity, while mid-market SaaS buyers assemble best-of-breed API stacks. Two archetypes dominate: database-anchored platforms leveraging existing enterprise data infrastructure, and cloud-native specialists monetizing subscription billing workflows. Competitive moves concentrate on embedded finance partnerships and microservices rearchitecture.
Within the enterprise software tier, Oracle and SAP SE exemplify database-anchored positioning, while Zuora occupies the subscription-specialist vector. Amdocs represents the telecom-vertical incumbent archetype with sustained service contract relationships. These three anchors illustrate how vendor selection maps to customer complexity thresholds and existing technology commitments.
| Leading Market Players |
|---|
| Amdocs |
| Netcracker |
| SAP SE |
| Oracle |
| Huawei Technologies |
| Comviva |
| CSG Systems |
| Optiva |
| Zuora |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on hyperscaler cloud infrastructure determines both SaaS pricing tier spreads and supply chain configuration across the billing and revenue management ecosystem. Platform vendors anchoring in AWS, Azure, or GCP face concentrated cost pass-through risk that compresses margin pools at the economy tier while premium deployments absorb elasticity premiums.
Pricing Analysis
Managed service and integration revenue tiers drive lifetime customer value beyond initial platform licensing. Three-tier pricing structure across premium, standard, and economy levels reflects deployment complexity, with premium tiers bundling dedicated solution architects and custom rating engine development. Cost compression in the economy tier intensifies because API-first challengers commoditize core invoicing modules. Mid-market SaaS buyers in North America exhibit highest price sensitivity, while tier-one telecom operators in Germany prioritize reliability over licensing costs.
Supply Chain Analysis
Upstream feedstock from semiconductor fabrication in Taiwan, South Korea, and the United States underpins cloud infrastructure scaling for billing platform operators. Kubernetes orchestration software, high-memory server clusters, and encrypted storage arrays constitute critical component dependencies. Tariff exposure on advanced compute hardware threatens margin stability for vendors dependent on just-in-time capacity expansion. Distribution runs through direct enterprise sales teams and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-first billing modules threaten incumbent platform vendors with disintermediation, forcing substitution defense through embedded finance integration and vertical workflow expansion.
For Market Incumbents: Build switching cost moats through deep ERP system integration and proprietary data lake architectures. Incumbents should accelerate backward integration into payment processing capabilities to capture interchange economics currently flowing to fintech partners. Cloud-native rating engine investments must outpace challenger innovation cycles. For New Entrants and Emerging Players: Build out white-space presence in Brazilian telecom modernization and mid-market healthcare revenue cycle automation. ANATEL convergence rules create the most penetrable regulatory entry point in Latin America. A channel partnership strategy with regional systems integrators accelerates credibility without direct enterprise sales overhead. For Investors and Strategic Acquirers: TRAI's evolving digital KYC mandates reshape the acquisition landscape toward India-facing managed services capabilities. Long-term viability centers on platforms demonstrating compliance automation at scale rather than pure transaction processing volume. Acquisition targets should show embedded analytics traction with CFO workflows. The signal to watch is consolidation of standalone billing vendors into broader revenue operations suites.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance Integration | Payment processing partnerships with Stripe or Adyen capture interchange revenue pools previously lost to standalone processors. |
| Microservices Rearchitecture | Kubernetes-orchestrated rating engines enable South Korean telecom operators to scale 5G usage billing without hardware procurement cycles. |
| Compliance Automation Layer | AI-augmented audit trail documentation satisfies FCC disclosure mandates and TRAI examination requirements with reduced manual overhead. |
| Vertical Workflow Expansion | Revenue intelligence modules embed directly into CFO dashboards, transforming billing platforms into strategic finance tools. |
| Geographic Managed Services | Regional delivery centers in Mumbai and Bangalore accelerate cloud migration timelines for Reliance Jio and Bharti Airtel. |
Study Parameters
Cross-validation between primary executive interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Conversations with CIOs at tier-one telecom operators, RevOps directors at SaaS enterprises, fintech partnership leads, and systems integration specialists were triangulated against TRAI circulars, FCC rulemaking dockets, and EMA guidance documents. Bottom-up deployment sizing and top-down market aggregation were reconciled to constrain estimate variance.
Calibration against historical platform adoption curves and elasticity responses to prior regulatory mandates shaped the projection framework. Segmentation dimensions modeled include solution architecture type, deployment model, end-user vertical, and geographic regulatory cluster. CAGRs were derived from fitted growth curves adjusted for compliance-driven replacement cycles and cloud infrastructure penetration rates. Inputs incorporated hyperscaler capex disclosures and telecom operator opex reallocation patterns.
Stress conditions across interest rate sensitivity, regulatory enforcement intensity, and talent availability scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about compliance timeline adherence and cloud migration velocity. Cross-checking against disclosed vendor contract values and enterprise software spending surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Latin America Factoring Services Market
Financial Services
Spain E-Brokerage Market
Financial Services
LAMEA Financial Services Software Market
Financial Services
E-KYC Market
Financial Services
Banknote Counters Market
Financial Services
Power Bank Sharing Services Market
Financial Services
ATM Outsourcing Services Market
Financial Services
Global Trust and Corporate Service Market
Financial Services
Back-Office Outsourcing in Financial Services Market
Financial Services
Hyperinflation System Market
Financial Services
Intellectual Property Valuation Market
Financial Services
Outsource Debt Collection Services Market
Financial Services
Europe E-Invoicing Market
Financial Services
Silver Economy Market
Financial Services
Qatar Analysis of Key Sectors and Investment Opportunities Market
Financial Services
Global Management Consulting Services Market