
 Saas Escrow Services Market | 2026-2036
Saas Escrow Services Market Size, Share, and Industry Trends Forecast 2026-2036
Saas Escrow Services Market Analysis
Recurring verification and release testing revenue is tilting toward automated platform models. NCC Group plc leverages its cybersecurity heritage to anchor premium escrow tiers in European financial services. Iron Mountain Incorporated sustains institutional trust through physical-digital hybrid vault infrastructure. PRAXIS Technology Escrow, LLC specializes in legal-framework customization for complex licensing arrangements.
SaaS escrow services constitute third-party custody arrangements where source code, data, or payment flows are held under conditional release protocols, typically requiring AES-256 encryption, multi-factor authentication, and geographically distributed replication. These mechanisms protect licensees against vendor insolvency, service discontinuation, or contractual breach in subscription software relationships. Source code escrow commands the deepest margin pools due to legal complexity and bespoke drafting requirements, while data escrow grows fastest as healthcare and financial services verticals face intensified continuity mandates. Cloud-based deployment dominates transaction volume though hybrid architectures capture premium pricing from enterprises with legacy on-premises footprints.
The EU Digital Operational Resilience Act mandates financial institutions to maintain access continuity for critical third-party SaaS, directly expanding escrow verification requirements across member states. In the United States, the SEC's vendor oversight guidelines for investment advisers and state-level insurance commissioner mandates collectively elevate escrow adoption in regulated sectors. Stakeholders must monitor whether emerging AI-generated code clauses trigger new escrow categories or reshape existing release-condition frameworks.
Market Dynamics
Enterprise procurement teams now mandate escrow protection for mission-critical SaaS applications, driven by the EU Digital Operational Resilience Act's continuity requirements and Fortune 500 contract renegotiations demanding vendor failure safeguards.
Growth Catalysts
- EU Digital Operational Resilience Act:Financial institutions across member states must maintain access continuity for critical third-party SaaS, directly expanding escrow verification requirements and audit frequency.
- Healthcare data escrow:HIPAA-covered entities facing intensified continuity mandates are driving rapid adoption of encrypted data custody arrangements with conditional release protocols.
- Fortune 500 contract renegotiation:United States-based enterprise procurement teams are embedding source code escrow clauses into standard SaaS vendor agreements as non-negotiable terms.
Market Restraints
- Bespoke legal drafting costs:Source code escrow commands premium pricing due to complex contractual customization requirements that resist automation and standardization.
- Encryption key management concentration:Geographically distributed replication with AES-256 encryption creates operational dependency on specialized cybersecurity infrastructure providers.
- Legacy on-premises integration friction:Hybrid architectures capturing premium pricing face technical limitations bridging cloud-native escrow platforms with existing enterprise vault systems.
Strategic Opportunities
- AI-generated code escrow:Emerging clauses for machine-learning model weights and training data represent uncharted white space requiring new release-condition frameworks.
- Automated verification platforms:Recurring testing revenue is migrating toward platform models that reduce manual legal review and accelerate deployment cycles.
- State insurance commissioner mandates:United States regulatory tailwinds at the state level are elevating escrow adoption beyond federal financial services into broader regulated sectors.
Industry Challenges
- Multi-factor authentication integration:Escrow providers face execution complexity embedding biometric and hardware-token requirements into legacy client authentication workflows.
- Release-condition trigger standardization:Absence of industry-wide definitions for vendor insolvency versus service discontinuation creates contractual disputes and delayed access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saas Escrow Services Market |
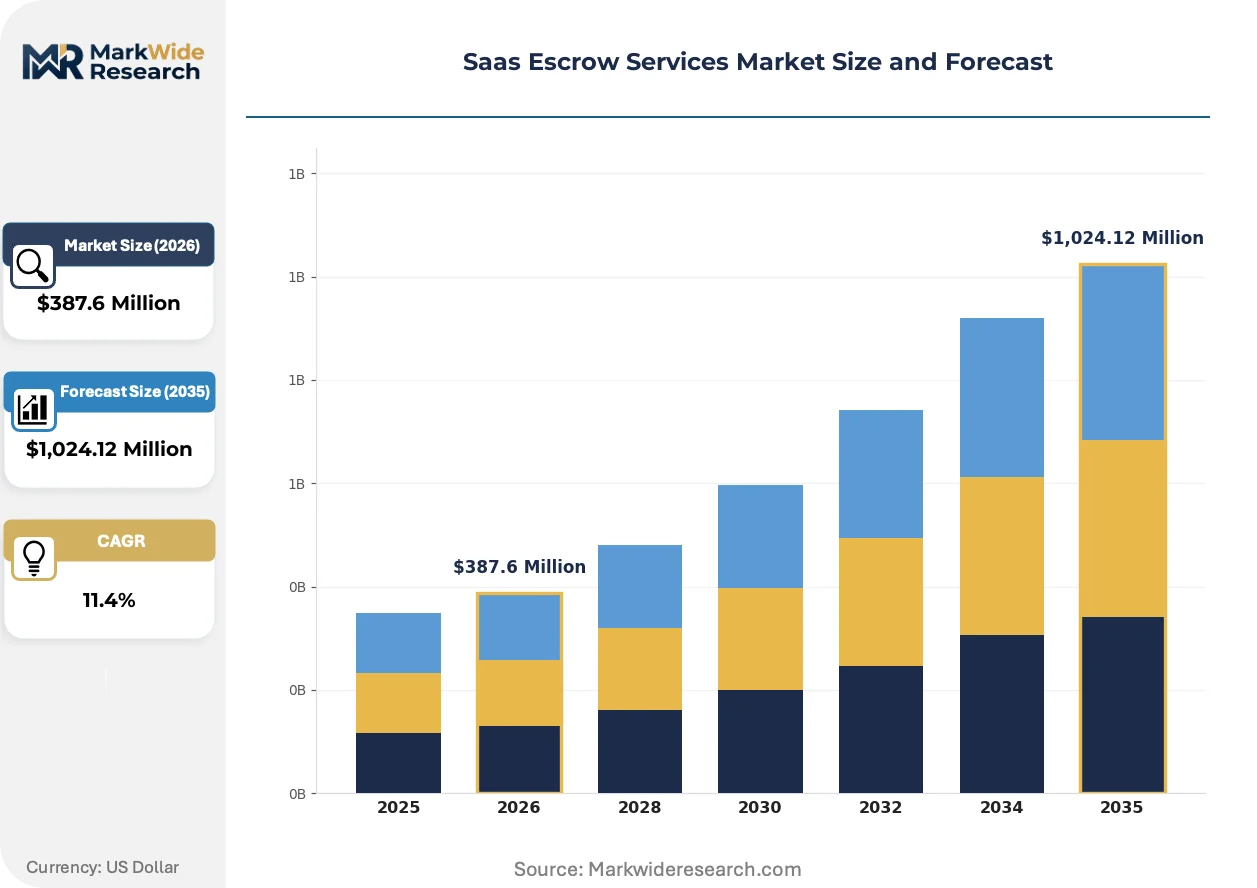
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Escrow, Source Code Escrow, Data Escrow, Software Escrow End User: Startups, Enterprises, Software Developers, Investors Deployment: Cloud-based, On-premises, Hybrid, Managed Industry Vertical: Technology, Financial Services, Healthcare, Retail |
| Companies Covered | Iron Mountain Incorporated, Escrowtech International, Inc., NCC Group plc, PRAXIS Technology Escrow, LLC, Codekeeper, The Escrow Company, Escode, Ardas International, Inc., Harbinger Group Pty Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saas Escrow Services Market Emerging Trajectories
Automation is compressing verification timelines while regulatory mandates harden encryption standards. Platform architectures are displacing manual legal processes across custody and release functions.
Containerized escrow vaults are virtualizing physical-digital hybrid infrastructure. Financial services buyers in London and Frankfurt are adopting these architectures fastest, compressing deployment cycles from months to weeks while maintaining geographically distributed replication requirements.
The SEC's vendor oversight guidelines for investment advisers are tightening third-party risk management protocols. United States investment firms must now document escrow arrangements for critical SaaS dependencies, pushing verification toward continuous monitoring rather than annual attestation.
Enterprise buyers are unbundling escrow from bundled SaaS contracts. Procurement teams in healthcare and insurance verticals now negotiate standalone custody agreements with direct provider relationships, bypassing vendor-mediated arrangements to ensure independent access continuity.
Saas Escrow Services Market Segmentation
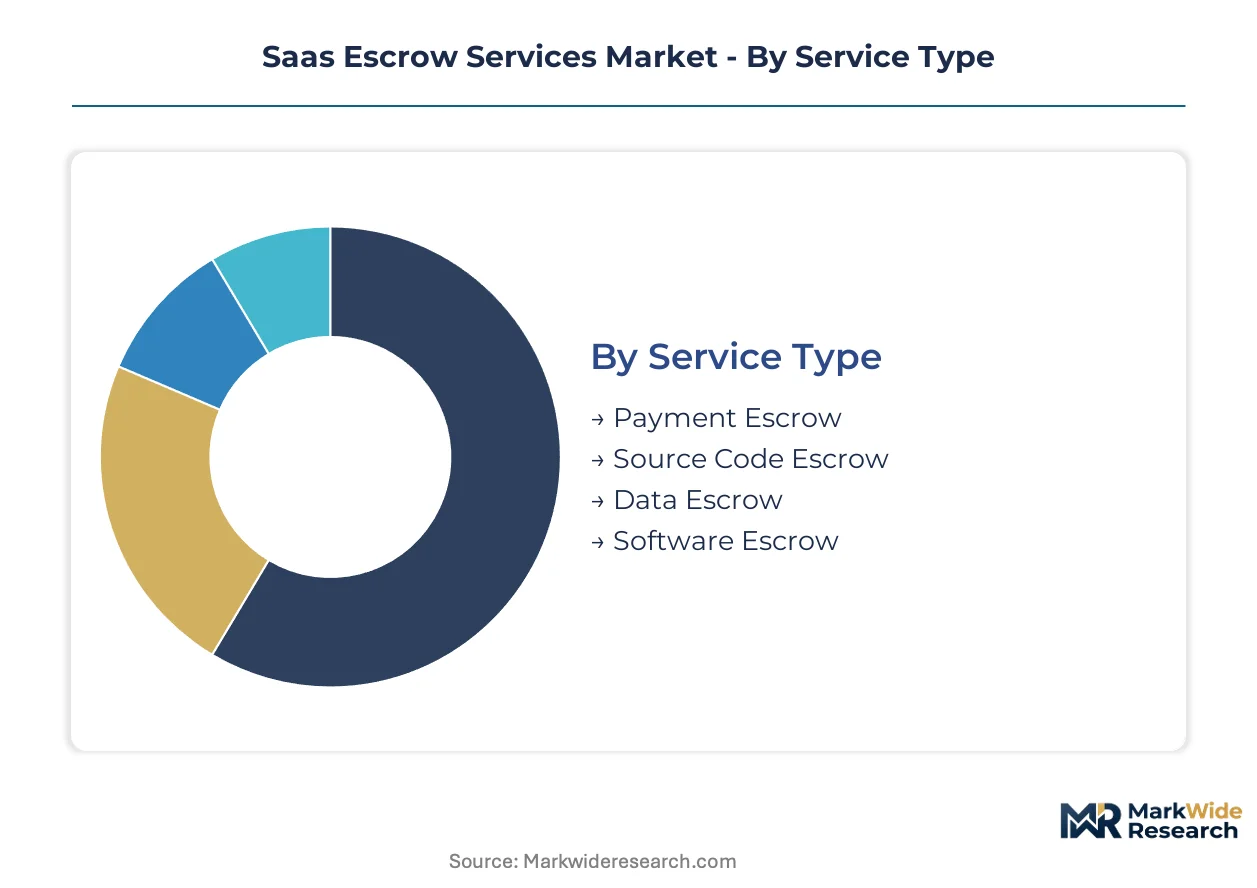
SaaS escrow services fragment across four distinct dimensions that shape procurement priorities and provider capabilities. Service type determines margin structure and legal complexity, while end-user scale dictates automation requirements and support intensity.
Service Type:
Cost tier stratification separates commodity custody from premium legal-engineering services, with encryption standards and verification frequency scaling accordingly.
- Source Code Escrow:Custody arrangements for proprietary software repositories, build environments, and deployment scripts under conditional release protocols. Financial services procurement teams in London and Frankfurt mandate these clauses for critical trading infrastructure, driving premium pricing through bespoke legal drafting and quarterly verification cycles.
- Data Escrow:Encrypted custody of structured databases, unstructured files, and metadata schemas with HIPAA-grade access controls. Healthcare systems in the United States facing intensified continuity mandates are expanding encrypted data custody arrangements fastest among all service tiers.
- Software Escrow:Binary distribution packages and license management systems held under vendor failure triggers. Technology sector licensees prioritize these arrangements for productivity suites and development tools.
- Payment Escrow:Conditional holding of subscription revenue streams and transaction processing flows. Investor-backed SaaS platforms use these mechanisms to secure runway financing against recurring revenue collateral.
Source code escrow holds installed capacity. Data escrow is rotating up the share rankings.
End User:
Customer type determines contract velocity, with enterprise procurement cycles spanning quarters while startup engagements close in weeks.
- Enterprises:Fortune 500 procurement teams embedding escrow clauses as non-negotiable terms in SaaS vendor renegotiations. These buyers demand source code verification with AES-256 encryption, multi-factor authentication, and geographically distributed replication across three or more jurisdictions.
- Startups:Venture-backed companies seeking escrow protection for mission-critical dependencies without dedicated legal infrastructure. These users favor automated platform models with standardized release conditions and rapid deployment timelines.
- Software Developers:Engineering teams requiring custody of third-party libraries, APIs, and development dependencies. This segment concentrates in technology hubs with dense SaaS vendor ecosystems.
- Investors:Private equity and venture capital firms mandating escrow arrangements as diligence requirements for portfolio company acquisitions. These stakeholders prioritize payment flow custody and revenue continuity verification.
Enterprise contracts anchor provider revenue. Startup adoption is climbing fastest as platform automation compresses sales cycles.
Deployment:
Architecture choice reflects legacy infrastructure exposure and regulatory jurisdiction requirements.
- Cloud-based:Native SaaS delivery with API-integrated verification and automated release testing. This architecture dominates transaction volume through containerized vault deployment and compressed implementation timelines.
- Hybrid:Bridging cloud-native platforms with on-premises key management and local replication nodes. Enterprises with legacy vault investments pay premium pricing for these configurations despite technical integration friction.
- On-premises:Dedicated hardware appliances with air-gapped encryption modules. Regulated financial institutions in Germany and Switzerland maintain these deployments for sovereign data requirements.
- Managed:Fully outsourced custody with provider-operated infrastructure and legal administration. Mid-market buyers lacking internal cybersecurity expertise favor this hands-off model.
Cloud-based deployment commands volume leadership. Hybrid configurations are gaining traction among legacy-rich enterprises.
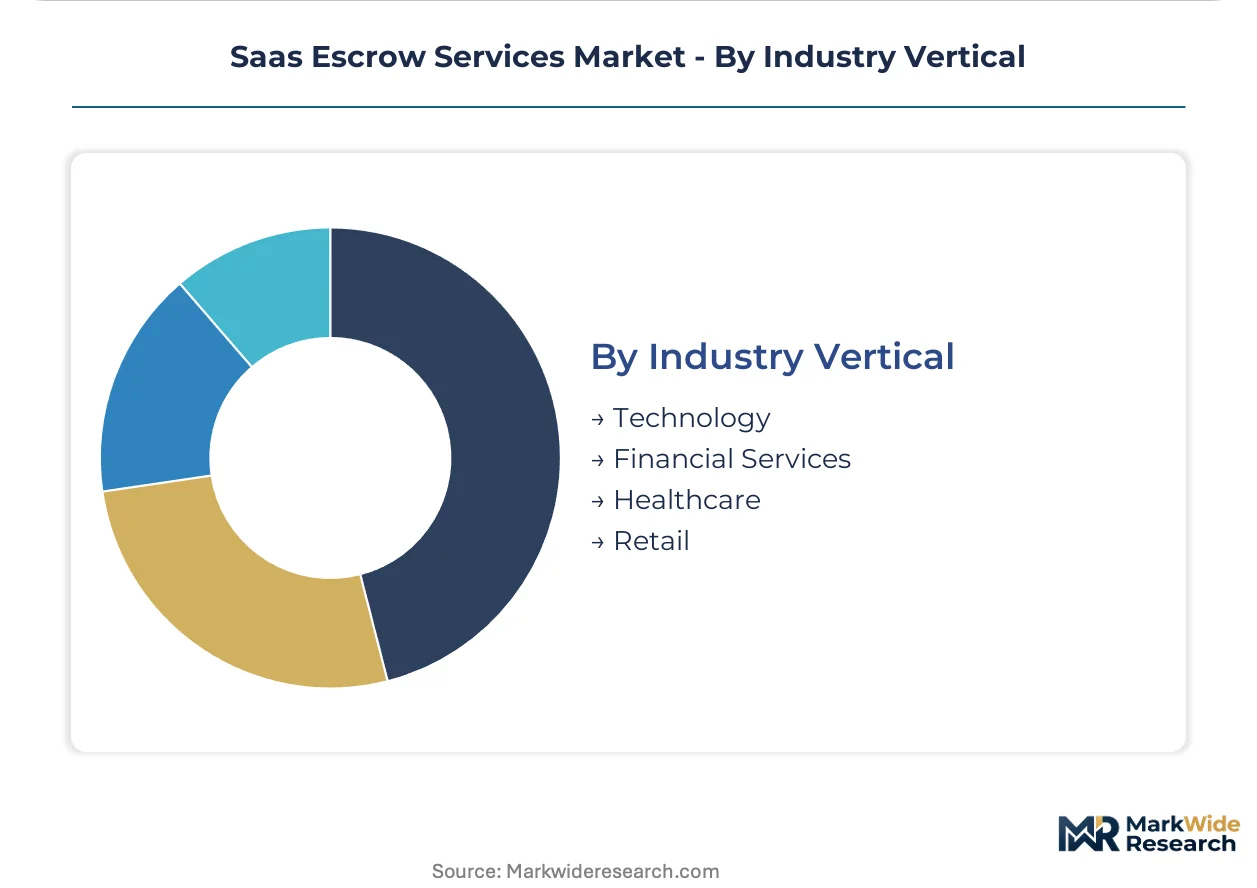
Industry Vertical:
Application context shapes encryption standards, verification frequency, and regulator engagement protocols.
- Financial Services:Banks, insurers, and asset managers subject to the EU Digital Operational Resilience Act and SEC vendor oversight guidelines. These institutions require continuous monitoring rather than annual attestation for critical SaaS dependencies.
- Healthcare:HIPAA-covered entities with intensified continuity mandates for electronic health records and telemedicine platforms. This vertical drives rapid adoption of encrypted data custody with conditional release protocols.
- Technology:SaaS vendors, cloud providers, and software development firms using escrow for supply chain risk management. These buyers concentrate in United States technology corridors and European fintech clusters.
- Retail:E-commerce platforms and omnichannel merchants protecting payment processing and inventory management dependencies. This segment shows rising interest following high-profile vendor insolvencies in the sector.
Financial services maintains the deepest contract values. Healthcare is expanding most quickly as continuity mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprises embed source code escrow as standard contract terms, while European financial institutions prioritize continuous verification under operational resilience mandates. German and Swiss buyers favor sovereign on-premises deployments. Asian markets concentrate adoption in fintech clusters with compressed implementation timelines.
United States
Fortune 500 procurement teams in New York and Chicago are renegotiating SaaS contracts with mandatory escrow clauses. The SEC's vendor oversight guidelines for investment advisers require documented continuity arrangements for critical third-party dependencies. Silicon Valley technology corridors host dense concentrations of escrow providers serving venture-backed startups seeking rapid deployment.
Germany
Frankfurt-based banks and insurers face expanded verification requirements under the EU Digital Operational Resilience Act's continuity mandates. BaFin supervisory expectations reinforce escrow adoption for critical SaaS infrastructure. Bavarian manufacturing conglomerates in Munich are extending escrow protection to supply chain software dependencies.
United Kingdom
London financial services buyers are adopting containerized escrow vaults that compress deployment from months to weeks. The Financial Conduct Authority's operational resilience rules align with EU DORA timelines for third-party risk management. The City of London and Canary Wharf clusters drive premium pricing for bespoke legal-engineering services.
Switzerland
Zurich and Geneva private banks maintain air-gapped on-premises escrow deployments for sovereign data requirements. FINMA guidelines on outsourcing risk management elevate escrow verification frequency for critical systems. Basel pharmaceutical headquarters are expanding data escrow arrangements for clinical trial platform continuity.
India
Bangalore and Hyderabad fintech clusters are driving cloud-native escrow adoption with API-integrated verification. RBI guidelines on information technology governance for regulated entities are elevating third-party risk management standards. Mumbai financial institutions are negotiating standalone custody agreements bypassing vendor-mediated arrangements.
Saas Escrow Services Market Vendor Landscape
Capability concentration sits with cybersecurity heritage players; scale advantage sits with institutional infrastructure incumbents. The market structures around three tiers: premium legal-engineering specialists, automated platform operators, and hybrid physical-digital vault providers. Dominant competitive moves include M&A to acquire encryption key management expertise and strategic partnerships bridging cloud-native platforms with legacy enterprise systems.
Within the premium-tier vector, NCC Group plc and Iron Mountain Incorporated exemplify divergent capability anchoring. NCC Group plc occupies a position leveraging cybersecurity heritage for financial services verification. Iron Mountain Incorporated represents institutional trust through physical-digital hybrid infrastructure. PRAXIS Technology Escrow, LLC sits within the legal-framework customization niche for complex licensing arrangements.
| Leading Market Players |
|---|
| Iron Mountain Incorporated |
| Escrowtech International, Inc. |
| NCC Group plc |
| PRAXIS Technology Escrow, LLC |
| Codekeeper |
| The Escrow Company |
| Escode |
| Ardas International, Inc. |
| Harbinger Group Pty Ltd. |
| Others |
Supply Flow & Price Mechanics
Specialized cybersecurity infrastructure providers in the United Kingdom and United States anchor upstream capacity for AES-256 encryption and geographically distributed replication, directing margin pools toward legal-engineering services and automated verification platforms rather than commodity custody.
Pricing Analysis
Long-term contractual offtake structures dominate enterprise procurement, with Fortune 500 buyers negotiating multi-year source code escrow agreements featuring quarterly verification cycles. Price differentiation rests on legal customization depth and encryption certification tiers, with bespoke drafting commanding substantial premiums over standardized platform offerings. Cost compression in automated verification tiers is intensifying as Codekeeper and Escode displace manual legal review. Startups exhibit highest price sensitivity, while financial services institutions in Frankfurt and London show lowest sensitivity due to regulatory mandates.
Supply Chain Analysis
Iron Mountain Incorporated and NCC Group plc hold concentrated contract-manufacturing capacity for hybrid physical-digital vault infrastructure across the United States, United Kingdom, and Germany. The supply chain draws from specialized cryptographic hardware manufacturers, certified legal engineering talent pools, and cloud-native platform development centers. Single-source vulnerability in encryption key management infrastructure presents structural risk. Distribution runs through direct enterprise sales teams, strategic partnerships with law firms, and API-integrated platform marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent escrow providers face substitution pressure from automated platform operators commoditizing verification services, requiring defensive repositioning around irreplaceable legal-engineering capabilities.
For Market Incumbents: Build switching-cost moats through deep integration with Fortune 500 procurement systems and proprietary legal-framework libraries. Incumbents must acquire machine-learning engineering talent to counter automated platform substitution threats. Capacity addition in Frankfurt and Singapore addresses regulatory jurisdiction requirements. Certification investment in EU DORA compliance creates competitive separation from cloud-native challengers. For New Entrants and Emerging Players: Mid-market healthcare systems in the United States represent the most penetrable entry point for standalone data escrow offerings bypassing vendor-mediated arrangements. AI-generated code escrow for machine-learning model weights constitutes uncharted white space requiring new release-condition frameworks. API-first go-to-market strategies compress sales cycles from quarters to weeks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cybersecurity firms possessing encryption key management expertise but lacking legal-engineering scale. Long-term viability favors platforms combining automated verification with bespoke customization capabilities. Watch for state insurance commissioner mandate expansions as inflection indicators for regulated sector adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Verification Platform Launch | Codekeeper and Escode compress deployment timelines from months to weeks for venture-backed startups. |
| EU DORA Compliance Certification | NCC Group plc anchors premium positioning in Frankfurt and London financial services procurement. |
| Healthcare Data Escrow Expansion | HIPAA-covered entities in the United States drive fastest-growing service tier adoption. |
| AI-Generated Code Escrow Development | New release-condition frameworks for machine-learning model weights address emerging white space. |
| Hybrid Infrastructure Partnership | Iron Mountain bridges cloud-native platforms with legacy enterprise vault systems for premium pricing. |
Methodological Framework
A spread of perspectives from enterprise procurement officers, cybersecurity infrastructure directors, legal engineering specialists, and financial services compliance leads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC vendor oversight filings, EU DORA regulatory texts, HIPAA continuity mandate documentation, and escrow provider technical specifications. Bottom-up triangulation across service type deployments and top-down reconciliation against end-user spending patterns anchored the analytical framework.
Demand-supply-balance modeling across the analysis window integrated enterprise contract velocity, startup adoption curves, and regulatory mandate implementation timelines. Segmentation dimensions included service type, end-user scale, deployment architecture, and industry vertical. CAGRs were derived from weighted projections across these dimensions, with specific inputs from Fortune 500 contract renegotiation patterns and state insurance commissioner mandate expansion trajectories.
Practitioners should monitor AI-generated code clause emergence, automated platform pricing compression, and regulatory mandate geographic expansion for early signals of forecast revision. Quarterly review of escrow verification automation rates and legal-engineering talent availability is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Capital Restructuring Services Market
Financial Services
Source to Pay Market
Financial Services
ATM Management Service Market
Financial Services
Asia-Pacific Factoring Services Market
Financial Services
Silver Economy Market
Financial Services
India Payroll Services Market
Financial Services
Online Investment Platform Market
Financial Services
Banknote Counters Market
Financial Services
Global Alternative Data Market
Financial Services
ATM Outsourcing Services Market
Financial Services
Treasury Management Market
Financial Services
Europe B2B Legal Services Market
Financial Services
US Healthcare Finance Solutions Market
Financial Services
Europe E-Brokerages Market
Financial Services
China Financial Services Software Market
Financial Services
India Security Brokerage Market