
 Global Smart Contracts Market | 2026-2036
Global Smart Contracts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Contracts Market Outlook
Enterprise software distribution is fragmenting as blockchain-native vendors bypass traditional IT procurement channels. Antier Solutions leverages its tokenization expertise to anchor institutional DeFi deployments across Southeast Asia. LeewayHertz competes through specialized healthcare smart contract modules that sustain recurring revenue from hospital networks. PixelPlex differentiates by controlling full-stack development for real estate tokenization platforms.
Smart contracts are self-executing protocols with terms encoded directly into immutable blockchain ledger entries, typically deployed on Ethereum Virtual Machine-compatible networks using Solidity or Vyper programming languages. Their primary commercial purpose is automating trust-dependent transactions without intermediary enforcement, reducing settlement latency from days to minutes. Supply chain management applications lead current enterprise deployment volume, while insurance claim automation represents the fastest-growing segment as carriers seek to eliminate manual adjudication costs. Public cloud deployment dominates accessibility for mid-market buyers, though private cloud configurations capture the highest margin pools from regulated financial institutions requiring node sovereignty.
The EU AI Act and MiCA framework impose algorithmic transparency obligations on automated contract systems deployed within European member states. The SEC in the United States scrutinizes smart contract-governed token offerings under existing securities registration requirements, creating jurisdictional friction for cross-border protocols. ISO 27001 and SOC 2 certifications increasingly function as de facto market access filters for enterprise buyers evaluating vendor risk profiles. Stakeholders must monitor evolving enforcement patterns across the Federal Reserve's digital dollar exploration and the Bank for International Settlements' unified ledger initiatives to anticipate infrastructure investment priorities.
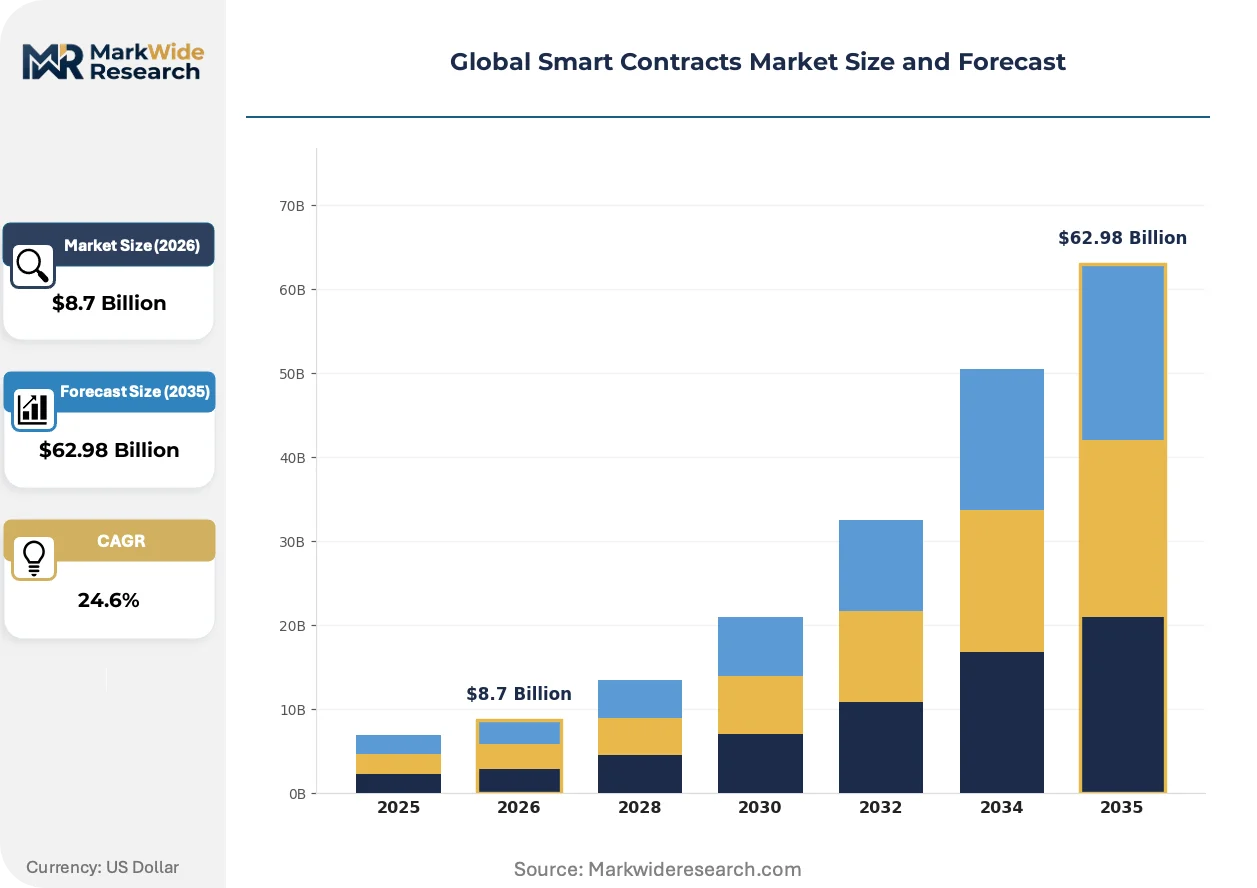
Market Dynamics
The EU AI Act and MiCA framework are compressing deployment timelines for automated contract systems, forcing vendors to rearchitect compliance layers before European market entry. This regulatory acceleration is redistributing competitive advantage toward firms with pre-existing ISO 27001 and SOC 2 certifications.
Growth Catalysts
- MiCA Framework Compliance:The EU's Markets in Crypto-Assets regulation creates uniform licensing pathways for tokenized financial instruments, reducing jurisdictional fragmentation for cross-border DeFi protocols.
- Supply Chain Automation:Enterprise logistics operators in Singapore are deploying self-executing settlement layers to compress invoice reconciliation from weeks to hours.
- Solidity Developer Density:Switzerland's Crypto Valley cluster around Zug concentrates specialized engineering talent that anchors institutional protocol development.
Market Restraints
- Oracle Infrastructure Concentration:Price feed dependencies on centralized oracle networks create single-point-of-failure risks for decentralized applications.
- Gas Fee Volatility:Ethereum base layer transaction costs fluctuate unpredictably, complicating enterprise budgeting for high-frequency contract execution.
- SEC Enforcement Uncertainty:The United States securities regulator's case-by-case approach to token classification prolongs legal risk for protocol developers.
Strategic Opportunities
- Insurance Claim Automation:Parametric payout structures for catastrophe coverage remain underdeployed across European and Asian markets.
- Real Estate Tokenization:Fractional ownership registries for commercial property are gaining regulatory clarity in Switzerland and Singapore.
- AI-Contract Convergence:Natural language processing integration with code generation tools is lowering deployment barriers for non-technical legal teams.
Industry Challenges
- Formal Verification Expertise:Mathematical proof engineering for contract security audits commands premium salaries that mid-size development shops cannot sustain.
- Legacy System Integration:Enterprise ERP connectivity requires custom middleware that extends deployment timelines and inflates implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Contracts Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Supply Chain Management, Insurance, Real Estate, Healthcare Technology: Blockchain, Ethereum, Hyperledger, Corda Industry Vertical: Finance, Legal, Retail, Government Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises |
| Companies Covered | Antier Solutions, ilink, Wildnet Edge, Vention, MetaLamp, LeewayHertz, PixelPlex, SotaTek JSC, SoluLab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Contracts Market Strategic Shifts
Zero-knowledge proof architectures are compressing verification costs while expanding privacy-preserving use cases. Cross-chain interoperability protocols are dissolving liquidity fragmentation. Institutional custody solutions are maturing to satisfy fiduciary requirements for pension and endowment allocators.
Zero-knowledge rollups are virtualizing execution environments by batching thousands of transactions off-chain before cryptographic settlement on Ethereum mainnet. Major derivatives exchanges are migrating clearing operations to these layers to reduce capital requirements. The structural compression of verification costs is virtualizing competitive dynamics between layer-1 and layer-2 infrastructure providers.
The EU AI Act mandates algorithmic transparency documentation for automated decision systems deployed within member states. Smart contract vendors must now maintain technical files demonstrating human oversight capabilities. Financial services protocols targeting European institutional clients are restructuring governance modules to satisfy these conformity assessment obligations.
Enterprise procurement of blockchain infrastructure is consolidating around managed service providers with bundled compliance certifications. Hospital networks and logistics operators are abandoning self-hosted node operations in favor of SOC 2-certified platform subscriptions. Switzerland and Singapore exhibit the fastest migration toward outsourced infrastructure management among regulated institutional adopters.
Global Smart Contracts Market Segmentation
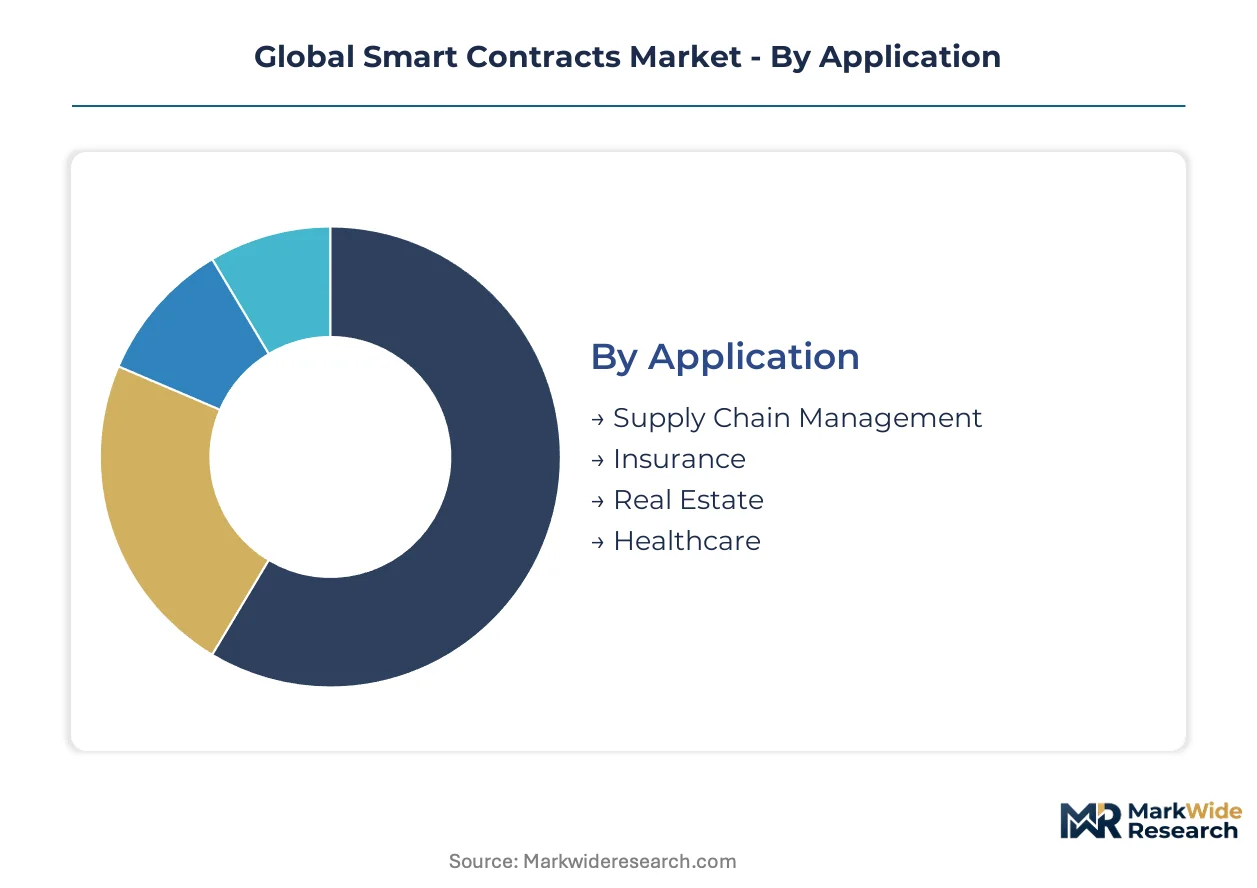
Smart contract deployment patterns diverge sharply across technical architectures and institutional readiness levels. Understanding these segment boundaries clarifies where infrastructure investments concentrate versus where standardization lags.
Application:
Use-case maturity spans from invoice automation to parametric catastrophe payouts, with each application carrying distinct oracle and settlement requirements.
- Supply Chain Management:Self-executing settlement layers encode delivery confirmation triggers from IoT sensors directly into payment release. Singapore's logistics operators compress invoice reconciliation cycles from weeks to hours through automated reconciliation protocols.
- Insurance:Parametric smart contracts trigger automatic payouts when predefined data thresholds verify loss events, eliminating manual claims adjudication. European carriers under Solvency II pressure seek to strip administrative overhead from catastrophe coverage products.
- Real Estate:Fractional ownership registries automate dividend distribution and voting rights for tokenized commercial property.
- Healthcare:Patient consent management and clinical trial data integrity applications face HIPAA and GDPR cross-border compliance friction.
Established volume favors Supply Chain Management; emerging adoption favors Insurance.
Technology:
Protocol selection determines developer talent access, transaction cost predictability, and enterprise integration complexity.
- Blockchain:Distributed ledger foundations enable immutable record-keeping across permissioned and permissionless network topologies. Financial institutions in Switzerland's Crypto Valley cluster prioritize blockchain substrates that support formal verification for regulatory audit trails.
- Ethereum:The Ethereum Virtual Machine dominates smart contract instruction sets, though base-layer gas fee volatility complicates enterprise budgeting. Layer-2 rollup migration is redistributing execution economics toward more predictable cost structures.
- Hyperledger:Modular permissioned frameworks serve consortia requiring node sovereignty and identity-managed participation.
- Corda:Point-to-point transaction privacy architectures appeal to interbank settlement networks seeking regulatory confidentiality.
Developer density concentrates on Ethereum; institutional compliance requirements are accelerating Hyperledger and Corda deployments.
Industry Vertical:
Regulatory intensity and legacy system replacement incentives vary dramatically across buyer categories.
- Finance:Capital markets infrastructure demands sub-second finality and custody-grade key management. Singapore's Monetary Authority has issued sandbox licenses to DeFi protocols targeting institutional foreign exchange settlement.
- Legal:Contract lifecycle automation displaces escrow and notarization intermediaries in cross-border trade documentation.
- Retail:Loyalty program interoperability and supply chain provenance tracking drive mid-market adoption.
- Government:Land registries and procurement transparency applications face procurement cycle timelines that stretch 24-36 months.
Finance captures the deepest contract values; Government exhibits the longest sales cycles.
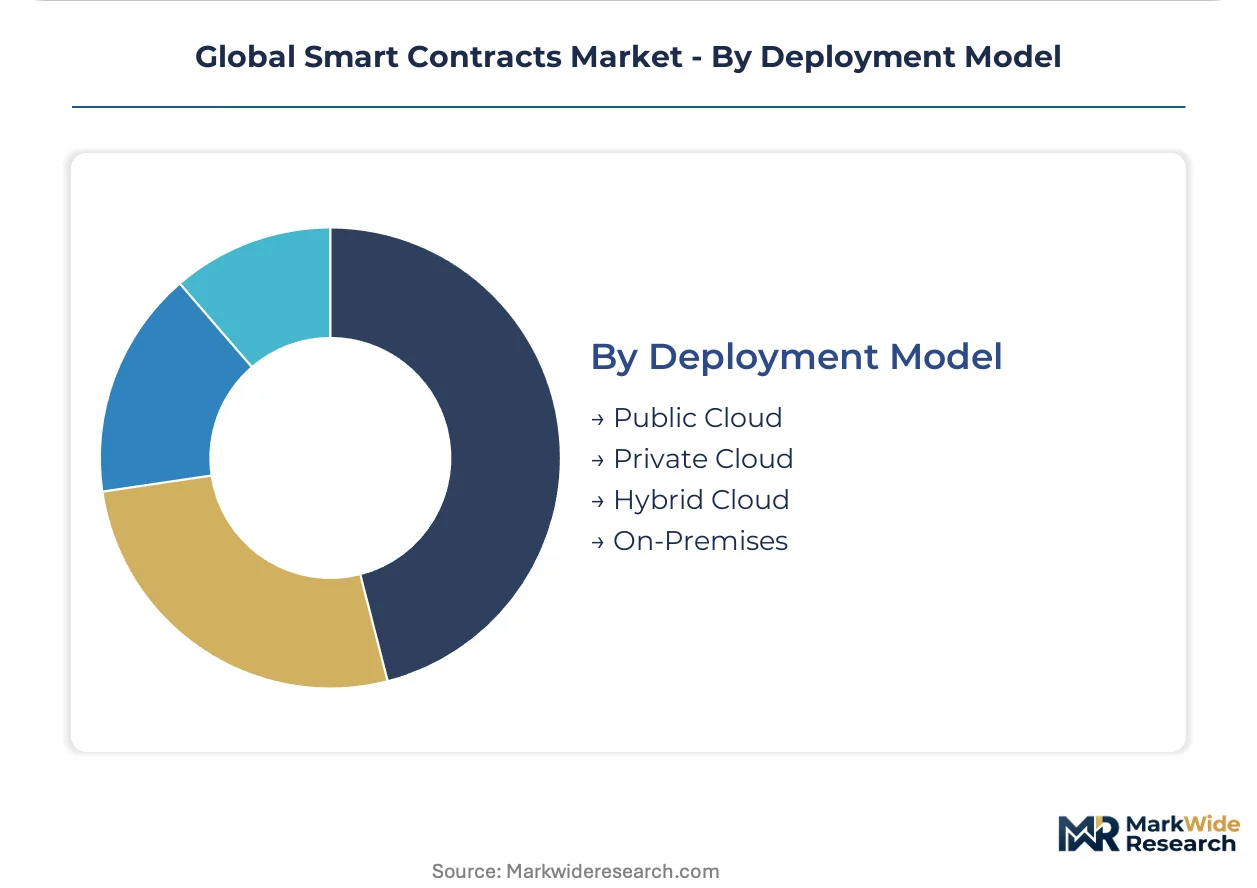
Deployment Model:
Infrastructure control trade-offs separate regulated institutions from cost-sensitive adopters.
- Public Cloud:Managed node services from AWS and Azure lower operational barriers for mid-market buyers lacking dedicated DevOps capacity. SOC 2 certification has become a non-negotiable filter for healthcare and financial services procurement teams.
- Private Cloud:Isolated validator networks satisfy data residency mandates from EU financial regulators and Swiss banking supervisors. These configurations command premium pricing but capture the highest-margin enterprise contracts.
- Hybrid Cloud:Sensitive transaction execution on private infrastructure with public chain anchoring for notarization.
- On-Premises:Full node sovereignty for central banks and defense contractors with air-gapped security requirements.
Public Cloud dominates accessibility; Private Cloud dominates margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Tuas Mega Port anchors Southeast Asian smart contract deployment by compressing maritime settlement timelines through automated bill-of-lading protocols. The facility's blockchain-integrated logistics corridors demonstrate how physical infrastructure underwrites digital automation adoption.
United States
Wall Street clearinghouses drive institutional DeFi demand as they migrate derivatives settlement to self-executing protocols. The SEC's enforcement posture under Chairman Gary Gensler creates compliance uncertainty that delays protocol launches. New York's financial district concentrates legal engineering talent that rearchitects token structures for securities law compatibility.
Switzerland
Private banking clients in Geneva and Zurich demand custody-grade smart contract infrastructure for wealth management automation. FINMA's DLT Act provides a federal framework for ledger-based securities that reduces cantonal regulatory friction. Zug's Crypto Valley cluster houses over 1,000 blockchain entities that anchor European protocol development.
Singapore
Monetary Authority of Singapore sandbox licenses attract foreign exchange protocols seeking institutional settlement finality. Project Guardian tests tokenized asset applications across banking consortia with regulatory cover. The city-state's port automation corridors compress supply chain invoice cycles from weeks to hours through IoT-triggered payments.
Germany
Industrial Mittelstand manufacturers in Baden-Württemberg pilot smart contract procurement for automotive supply chains. BaFin's crypto custody licensing creates supervised pathways for institutional DeFi participation. Frankfurt's banking quarter hosts compliance engineering teams that map MiCA obligations to protocol architectures.
United Kingdom
London's reinsurance market explores parametric catastrophe contracts that trigger automatic payouts from verified weather data. The Financial Conduct Authority's digital sandbox accommodates controlled testing of automated agreement systems. The City's legal technology cluster develops smart contract templates for cross-border trade finance documentation.
Global Smart Contracts Market Competitive Environment
On the supply side, the industry is fragmented across specialized development boutiques and platform-scale service providers. No single vendor commands dominant share; instead, capability clusters form around vertical expertise and geographic regulatory knowledge. Two strategic archetypes predominate: tokenization specialists who anchor institutional DeFi deployments, and sector-specific module builders who capture recurring revenue from hospital networks and logistics operators. Competitive moves concentrate on ISO 27001 certification acquisition and SOC 2 attestation to satisfy enterprise procurement filters.
Within the tokenization specialist tier, Antier Solutions and PixelPlex exemplify firms that leverage full-stack development control to capture real estate and financial instrument deployment contracts. LeewayHertz occupies a position among healthcare-focused module builders, sustaining recurring relationships through specialized hospital network applications. These three entities represent distinct competitive vectors: geographic anchoring in Southeast Asia, vertical integration across development layers, and sector-specific recurring revenue capture.
| Leading Market Players |
|---|
| Antier Solutions |
| ilink |
| Wildnet Edge |
| Vention |
| MetaLamp |
| LeewayHertz |
| PixelPlex |
| SotaTek JSC |
| SoluLab |
| Others |
Value Chain & Pricing Dynamics
Singapore's Tuas Mega Port freight corridors compress maritime settlement timelines while amplifying cost differentials between ISO-certified vendors and uncertified competitors. These logistics dynamics concentrate pricing power among firms with pre-existing SOC 2 attestations, forcing mid-tier developers toward volume-discount structures or vertical specialization.
Pricing Analysis
Volume-discount tiering structures dominate enterprise procurement, with three-tier pricing separating certified premium deployments from standard SaaS subscriptions and economy self-hosted configurations. Price differentiation rests on ISO 27001 certification grade and after-sales service bundling, where Swiss banking supervisors mandate node sovereignty premiums. Cost compression in the economy tier is intensifying because gas fee volatility complicates fixed-price contracting. Hospital networks exhibit the highest price sensitivity, while Geneva private banking clients tolerate premium markups for custody-grade infrastructure.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Singapore's Project Guardian banking consortia are stabilizing cash flow for protocol developers facing 18-24 month enterprise sales cycles. Developer talent concentrates in Switzerland, Singapore, and Germany, with formal verification expertise drawing from mathematical proof engineering pools anchored in Zug's Crypto Valley cluster. Single-source vulnerability persists around centralized oracle networks for price feed dependencies. Distribution runs through managed service providers with bundled compliance certifications rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formal verification engineering talent scarcity constrains mid-size development shops from competing for institutional audit contracts, compressing viable competitive strategies toward either certification accumulation or vertical niche capture.
For Market Incumbents: Build switching-cost moats through embedded ERP middleware integrations that extend replacement timelines beyond procurement review windows. Deepen backward integration into Layer-2 rollup infrastructure to capture execution economics from migrating derivatives exchanges. Threat substitution from AI-native code generation tools demands defensive patent positioning around natural language-to-Solidity compilation pipelines. For New Entrants and Emerging Players: Build out parametric insurance claim automation modules for European carriers under Solvency II administrative cost pressure, the most penetrable segment given incumbent neglect of catastrophe payout workflows. Target Switzerland's Crypto Valley cluster for talent acquisition density advantages. Go-to-market traction requires FINMA DLT Act compliance pre-certification before institutional sales engagement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-scale service providers with recurring revenue from hospital networks over project-based tokenization boutiques. Long-term viability hinges on regulatory clarity convergence across SEC enforcement patterns and MiCA implementation timelines. Watch the Federal Reserve's digital dollar exploration as infrastructure investment priority signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Acquisition | Enterprise procurement filters now treat SOC 2 attestation as non-negotiable market access threshold. |
| Layer-2 Rollup Infrastructure Migration | Derivatives exchanges reduce capital requirements through zero-knowledge proof verification cost compression. |
| Healthcare Module Specialization | HIPAA-compliant patient consent management sustains recurring revenue from hospital network subscriptions. |
| MiCA Compliance Pre-Architecture | EU algorithmic transparency obligations force governance module restructuring before European market entry. |
| Oracle Infrastructure Diversification | Price feed single-point-of-failure risks demand multi-source data aggregation for institutional DeFi protocols. |
Study Parameters
Cross-validation between primary executive interviews and secondary regulatory filings anchors the qualitative findings throughout this study. Conversations with smart contract protocol architects, enterprise IT procurement officers, FINMA compliance engineers, and hospital system CIOs informed demand-side segmentation. Secondary sources include SEC enforcement releases, EU AI Act technical documentation, MAS sandbox license records, and ISO certification databases. Bottom-up deployment volume estimates triangulate against top-down addressable market calculations across the analysis window.
Calibration against historical adoption curves for comparable automation technologies shapes the projection framework. Segmentation dimensions span application type, protocol architecture, deployment model, and regional regulatory cluster. CAGRs derive from elasticity-adjusted penetration rates applied to baseline enterprise software spending patterns. Industry-specific inputs incorporate Layer-2 transaction cost trajectories and formal verification talent supply constraints throughout the modeling period.
Stress conditions across Ethereum gas fee volatility bands, SEC enforcement intensity scenarios, and MiCA implementation timeline variations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about institutional DeFi adoption thresholds and legacy system replacement incentives. Macroeconomic contraction, regulatory fragmentation, or zero-knowledge proof breakthrough adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Music NFT Market
Digital Assets and Cryptocurrency Finance
Digital Currency Wallet Market
Digital Assets and Cryptocurrency Finance
Germany Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Blockchain Distributed Ledger Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Market
Digital Assets and Cryptocurrency Finance
Global Bitcoin and Cryptocurrency Wallets Market
Digital Assets and Cryptocurrency Finance
Asset Tokenization Software Market
Digital Assets and Cryptocurrency Finance
US Cryptocurrency Payment Apps Market
Digital Assets and Cryptocurrency Finance
Crypto Wallet Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchange Platform Market
Digital Assets and Cryptocurrency Finance
United States Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
GCC Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Automated Trading Market
Digital Assets and Cryptocurrency Finance
Spain Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Online Microtransaction Market