
 Credit Rating Software Market | 2026-2036
Credit Rating Software Market Size, Share, and Industry Trends Forecast 2026-2036
Credit Rating Software Market Analysis
ISO 9001 certification for quality management systems is rotating as a baseline qualifier for vendors serving tier-one financial institutions. Moody's Corporation leverages its proprietary analytics heritage to sustain premium positioning among institutional clients. Fair Isaac Corporation anchors the North American market through its FICO scoring ecosystem. Experian plc competes aggressively across European and Asia-Pacific markets with localized data integration capabilities.
Credit rating software encompasses algorithmic platforms that ingest borrower financial data, behavioral metrics, and macroeconomic indicators to generate quantitative default probability scores and credit grade assignments. These systems typically process structured and unstructured data through machine learning models with refresh cycles ranging from real-time streaming to quarterly batch updates, serving lenders, asset managers, and regulators in capital allocation and risk-weighting decisions. Cloud-based deployments are capturing the fastest expansion as banks exit fixed-capital data center commitments, while on-premises installations retain dominance among sovereign wealth funds and central banks with data sovereignty requirements. The regulatory compliance feature set commands the highest margin pools as Basel III and SEC disclosure rules force continuous model validation and audit trail documentation.
The SEC, the European Banking Authority, and the Basel Committee on Banking Supervision collectively dictate minimum standards for model risk management, stress testing frequency, and rating transparency that directly shape procurement specifications. Compliance with these frameworks now requires vendors to maintain explainable AI architectures and independent model validation workflows as table-stakes for contract eligibility. Stakeholders must monitor evolving algorithmic accountability legislation across multiple jurisdictions to anticipate retrofit obligations and competitive displacement risks.
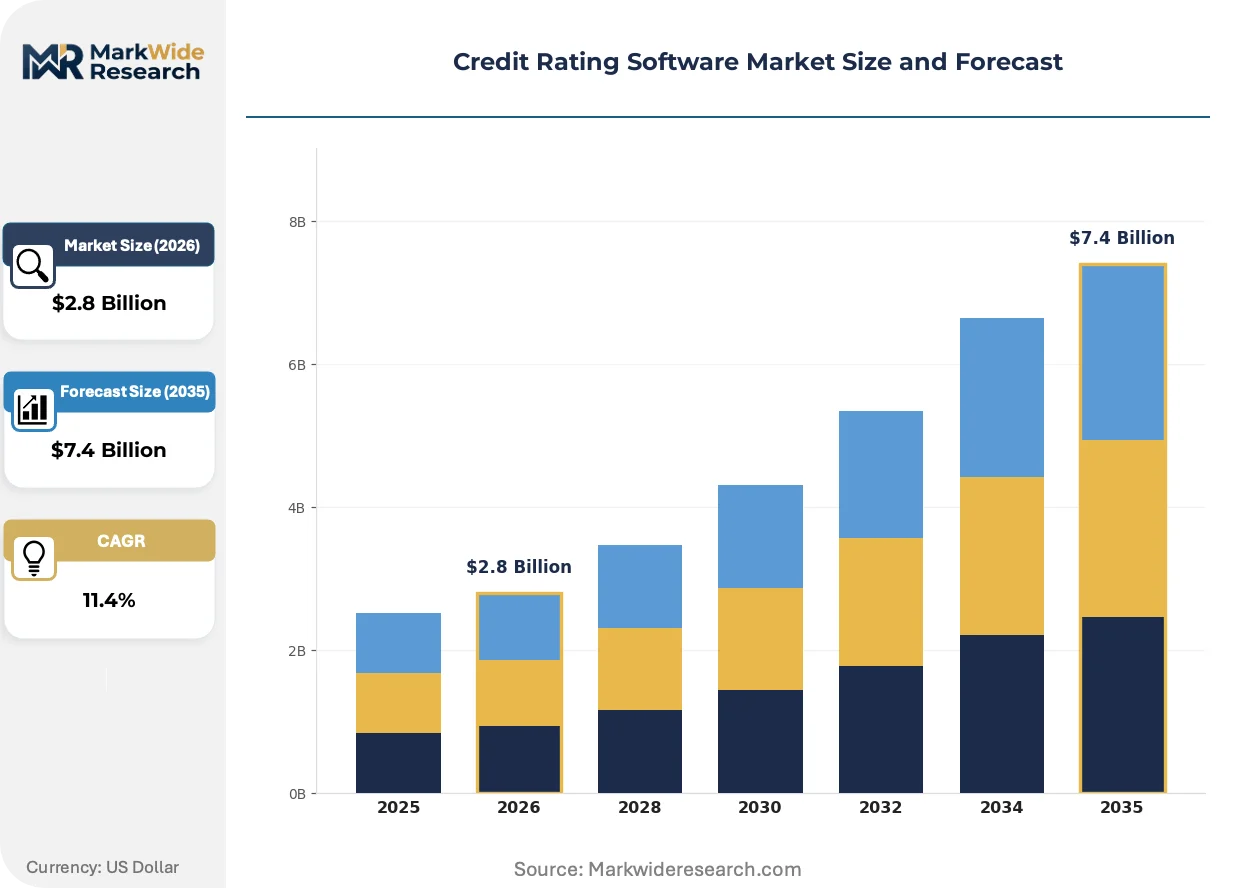
Market Dynamics
Cloud-native credit rating architectures are displacing legacy on-premises deployments as banks accelerate exit from fixed-capital data center commitments, compressing vendor switching costs and reshaping procurement specifications toward subscription-based delivery models.
Growth Catalysts
- SEC disclosure mandates:The Securities and Exchange Commission's credit risk transparency rules are forcing institutional investors to deploy automated rating platforms for real-time portfolio monitoring and audit trail documentation.
- Basel III model risk management:The Basel Committee's stress testing frequency requirements are compelling banks to refresh credit models quarterly rather than annually, driving software upgrade cycles.
- Behavioral data integration:Alternative data streams from payment processors and digital wallets are expanding rating accuracy for thin-file borrowers, opening new addressable segments for lenders.
Market Restraints
- Data sovereignty requirements:Central banks and sovereign wealth funds in Germany, Japan, and Saudi Arabia mandate on-premises deployment, fragmenting vendor scale economies and inflating implementation costs.
- Explainable AI compliance:The EU AI Act's algorithmic accountability provisions require vendors to maintain interpretable model architectures, constraining black-box machine learning adoption.
- Legacy system entrenchment:Core banking platforms from the 1990s lack API compatibility, forcing expensive middleware development for rating software integration.
Strategic Opportunities
- India SME lending digitization:The Reserve Bank of India's account aggregator framework is enabling consent-based financial data sharing, creating greenfield demand for localized rating engines.
- Climate risk scoring modules:The EU Green Deal's sustainability disclosure requirements are opening premium feature sets that embed carbon exposure into corporate credit assessments.
- Embedded finance convergence:API-first rating engines that integrate with e-commerce checkout flows and buy-now-pay-later platforms are capturing origination volume outside traditional banking channels.
Industry Challenges
- Quantitative risk modeling talent scarcity:PhD-level expertise in stochastic calculus and machine learning engineering commands compensation premiums that strain mid-tier vendor margins.
- ISO 9001 certification timelines:Tier-one bank procurement gates require 12-18 month quality management audits, delaying revenue recognition for emerging vendors.
- Model validation workflow complexity:Independent validation teams must reproduce rating outputs across divergent data environments, creating deployment friction and client-specific engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Credit Rating Software Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premises, Cloud-Based, Hybrid, Customized End User: Investment Firms, Credit Bureaus, Banks, Financial Institutions Feature: Risk Assessment, Portfolio Management, Regulatory Compliance, Reporting Deployment: Public Cloud, Private Cloud, Multi-Tenant, Single-Tenant |
| Companies Covered | Equifax Inc., The Dun And Bradstreet Corporation, Oracle Corporation, Pegasystems Inc., Fair Isaac Corporation, Experian plc, SAS Institute Inc., CRIF S.p.A., Moody's Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Credit Rating Software Market Emerging Trajectories
Real-time streaming analytics and explainable AI architectures are compressing refresh cycles from quarterly batches to continuous monitoring, while regulatory pressure on algorithmic accountability is forcing vendors to sacrifice predictive accuracy for interpretability.
Machine learning model ensembles are bifurcating the vendor landscape between explainable linear models for regulatory compliance and black-box neural networks for internal risk optimization. Regional banks and credit unions are adopting the former under examiner pressure, while hedge funds and private credit funds retain the latter for proprietary alpha generation. This technological split is compressing pricing power for generalist platforms that cannot serve both constituencies.
The EU AI Act's risk-based classification system is mandating human-in-the-loop review for high-stakes credit decisions, forcing vendors to build audit interfaces and override workflows. This regulatory architecture is inflating development costs for European deployments and creating compliance moats for incumbent platforms with existing validation infrastructure. Asset managers with cross-border operations are consolidating procurement around vendors with pre-certified EU compliance modules.
Subscription pricing for cloud-native platforms is displacing perpetual license models as the dominant procurement structure, particularly among mid-market lenders seeking to convert capex to opex. Channel partners and system integrators are capturing implementation revenue that previously accrued to software vendors directly. This shift is most visible in the United States, where regional banks undergoing digital transformation are consolidating vendor relationships around platform ecosystems rather than point solutions.
Credit Rating Software Market Segmentation
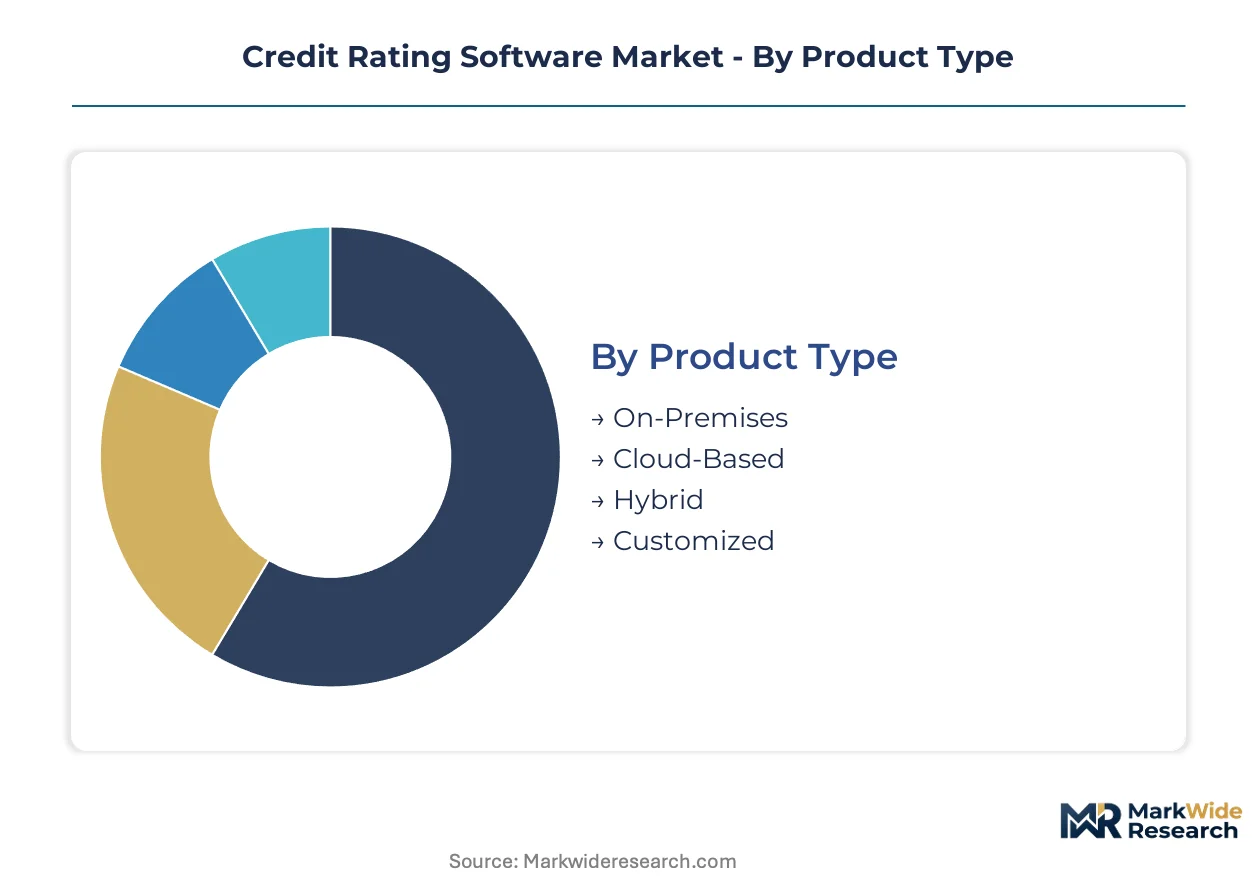
Segmentation in credit rating software reveals divergent margin architectures across deployment modes and compliance feature sets. Vendors optimize pricing power by aligning product configurations with regulatory intensity and data sovereignty requirements.
Product Type:
Premium margins concentrate in deployment modes that balance customization depth with recurring revenue predictability.
- On-Premises:Installations run on client-owned infrastructure with full data custody, serving central banks and sovereign wealth funds in Germany, Japan, and Saudi Arabia under strict data localization mandates. Tier-one financial institutions in the United States and Switzerland pay implementation premiums exceeding subscription equivalents by 40-60% for air-gapped environments with independent validation workflows.
- Cloud-Based:Multi-tenant SaaS architectures compress customer acquisition costs and enable real-time model updates. Regional banks across the United States and mid-market lenders in India favor this mode for Basel III compliance without capital-intensive infrastructure commitments.
- Hybrid:Split configurations process sensitive borrower data on-premises while pushing anonymized analytics to cloud environments. European banks navigating GDPR and EU AI Act requirements deploy hybrid stacks to satisfy cross-border data transfer restrictions.
- Customized:Bespoke model development for specialized asset classes or proprietary scoring methodologies commands project-based fees. Private credit funds and hedge funds in the United Kingdom and Singapore commission custom builds for alpha-generating risk signals outside standardized vendor offerings.
The dominant share belongs to Cloud-Based deployments, while Hybrid configurations are closing the gap fastest as regulatory fragmentation intensifies.
End User:
Procurement specifications diverge sharply between prudentially regulated deposit-takers and lightly supervised non-bank lenders.
- Banks:Commercial and retail banking divisions require comprehensive model risk management suites with quarterly validation cycles and stress testing automation. United States regional banks modernizing legacy core systems drive replacement demand for API-first rating engines.
- Investment Firms:Asset managers and hedge funds prioritize predictive accuracy over explainability, deploying ensemble machine learning models for portfolio construction. Firms with cross-border European operations consolidate around vendors with pre-certified EU AI Act compliance modules.
- Credit Bureaus:National credit registries in India and Brazil integrate alternative data streams from payment processors and digital wallets, expanding scoring coverage for thin-file borrowers under central bank financial inclusion mandates.
- Financial Institutions:Insurance companies and pension funds apply credit rating modules to fixed-income portfolio management and counterparty exposure monitoring. Japanese insurers embed climate risk scoring for corporate bond holdings under METI sustainability disclosure guidance.
Banks command the largest addressable spend, though Investment Firms are expanding procurement fastest as private credit markets deepen.
Feature:
Compliance functionality captures pricing premiums that offset development costs for explainable AI architectures.
- Regulatory Compliance:Automated audit trails, model documentation, and Basel III validation workflows constitute mandatory procurement criteria for regulated lenders. Vendors with pre-built SEC disclosure modules and European Banking Authority stress testing templates extract 25-35% price premiums over baseline risk assessment tools.
- Risk Assessment:Core default probability engines ingest structured financial statements and behavioral data to generate quantitative credit grades. Machine learning ensembles now dominate over legacy logistic regression for consumer and SME segments in the United States and United Kingdom.
- Portfolio Management:Concentration risk monitoring and scenario analysis tools serve asset managers with complex multi-issuer exposures. Real-time streaming analytics compress refresh cycles from quarterly batches to continuous monitoring for liquid credit portfolios.
- Reporting:Standardized and ad-hoc visualization layers feed internal risk committees and external regulators. Indian banks under RBI account aggregator frameworks require consent-based data sharing reports for SME lending digitization initiatives.
Regulatory Compliance features hold the dominant revenue share, while Portfolio Management capabilities are climbing the fastest as real-time analytics mature.
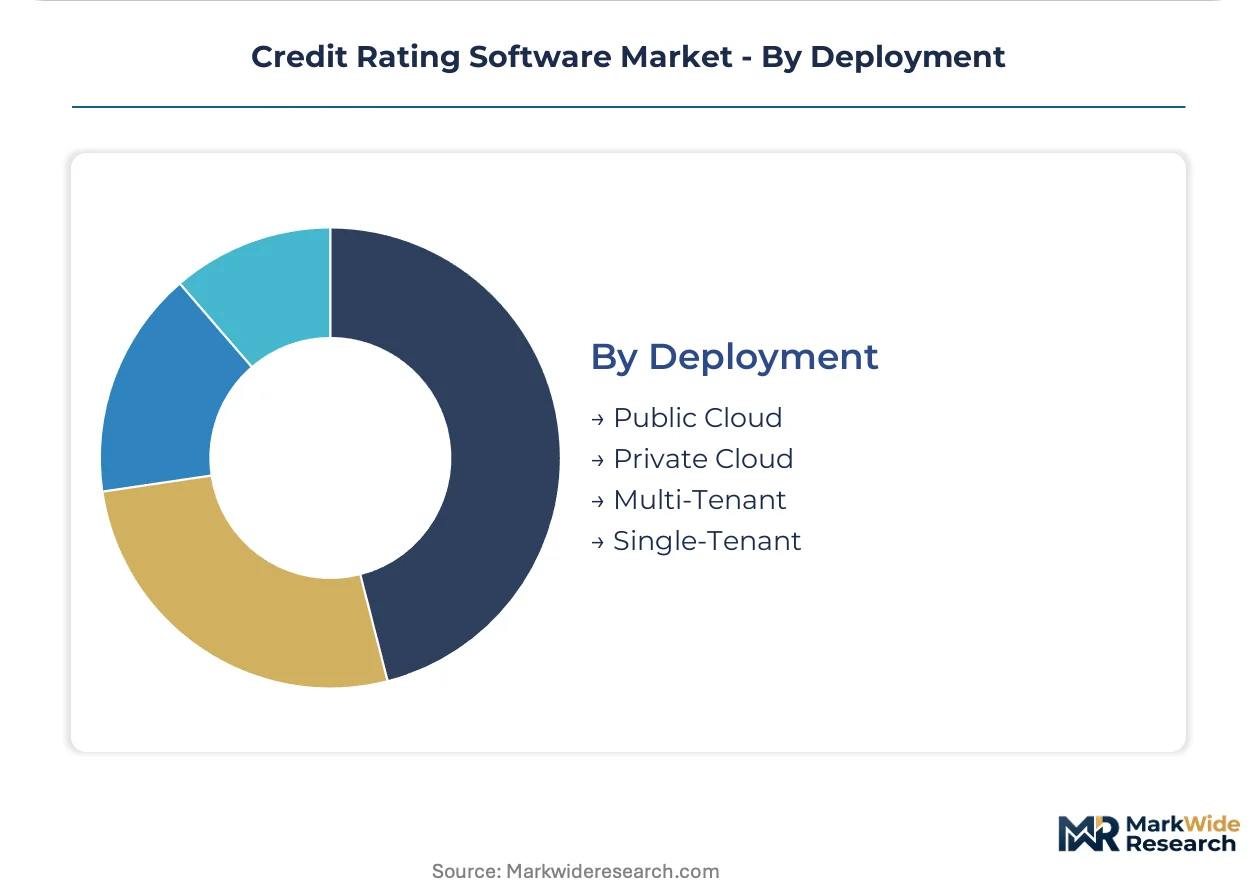
Deployment:
Infrastructure tenancy decisions reflect trade-offs between operational flexibility and information security certification burdens.
- Public Cloud:Shared infrastructure from hyperscale providers enables rapid scaling and geographic expansion without data center capital commitments. Mid-market United States lenders favor public deployments for digital transformation initiatives converting capex to opex.
- Private Cloud:Dedicated virtualized environments isolate tenant data while retaining cloud operational models. German and French banks under national data sovereignty requirements deploy private clouds to satisfy CNIL and BSI compliance without full on-premises retrogression.
- Multi-Tenant:Shared application instances with logical data separation minimize per-customer infrastructure costs. Standardized rating engines for retail credit and small business lending run predominantly on multi-tenant architectures.
- Single-Tenant:Isolated software stacks for individual clients support customized model configurations and independent security auditing. Sovereign wealth funds and military banking operations mandate single-tenant isolation for national security classification requirements.
Multi-Tenant deployments dominate volume, though Private Cloud is gaining share fastest as European data localization rules proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes concentrate heavily among United States regional banks modernizing legacy infrastructure, European institutions navigating algorithmic accountability mandates, and Asia-Pacific lenders digitizing SME credit origination.
United States
Regional banks in the Southeast and Midwest drive replacement demand for API-first rating engines as they exit fixed-capital data center commitments. The SEC's credit risk transparency disclosure rules force institutional investors toward automated platforms with real-time portfolio monitoring and audit trail documentation. Dallas and Charlotte banking clusters see concentrated procurement activity as mid-market lenders consolidate vendor relationships around cloud-native platform ecosystems.
Germany
Commercial banks and Landesbanken require hybrid deployment configurations to satisfy BSI data sovereignty mandates while retaining cloud operational flexibility. The EU AI Act's algorithmic accountability provisions mandate human-in-the-loop review workflows, inflating development costs for European deployments. Frankfurt's financial center anchors vendor certification activity, with institutions prioritizing pre-built European Banking Authority stress testing templates.
India
Non-bank financial companies and fintech lenders exploit the RBI's account aggregator framework for consent-based financial data sharing, creating greenfield demand for localized scoring engines. Central bank financial inclusion mandates push credit bureaus to integrate alternative data streams from payment processors. Mumbai and Bangalore technology corridors host the densest concentration of indigenous rating platform development for thin-file borrower segments.
United Kingdom
Asset managers and private credit funds prioritize predictive accuracy over explainability, deploying ensemble machine learning models for portfolio construction. Firms with cross-border European operations consolidate procurement around vendors with pre-certified EU AI Act compliance modules. The City of London and Edinburgh fund clusters drive demand for customized model development outside standardized vendor offerings.
Japan
Insurance companies and pension funds embed climate risk scoring modules into corporate bond holdings under METI sustainability disclosure guidance. Megabanks maintain on-premises installations for data sovereignty despite cloud migration pressure elsewhere. Tokyo's financial district concentrates procurement for air-gapped environments with independent validation workflows serving sovereign wealth fund requirements.
Credit Rating Software Market Vendor Landscape
Player mix skews toward diversified analytics conglomerates with heritage credit data assets and specialized software vendors with regulatory compliance expertise. Market structure exhibits tiered concentration, with a handful of legacy data bureaus commanding premium positioning among tier-one financial institutions while mid-tier vendors compete on implementation speed and sector-specific customization. Two strategic archetypes dominate: integrated credit data-and-analytics platforms leveraging proprietary information reservoirs, and modular software specialists offering API-first deployment flexibility. Competitive moves center on M&A activity targeting alternative data integration capabilities and strategic partnerships with cloud hyperscalers to accelerate multi-tenant infrastructure scaling.
Within the integrated analytics tier, Moody's Corporation and Fair Isaac Corporation exemplify heritage-dependent positioning that sustains pricing power through proprietary model ecosystems and institutional client entrenchment. Experian plc occupies a transnational position bridging European data integration requirements with Asia-Pacific localization capabilities. These three entities anchor the competitive landscape without exhausting its diversity, as specialized vendors continue penetrating mid-market segments where implementation agility outweighs brand prestige.
| Leading Market Players |
|---|
| Equifax Inc. |
| The Dun And Bradstreet Corporation |
| Oracle Corporation |
| Pegasystems Inc. |
| Fair Isaac Corporation |
| Experian plc |
| SAS Institute Inc. |
| CRIF S.p.A. |
| Moody's Corporation |
| Others |
Supply Flow & Price Mechanics
Subscription-based SaaS contracts with annual indexation clauses lock in recurring revenue streams for cloud-native vendors while guaranteeing tier-one banks predictable opex conversion from legacy perpetual licenses. This contract structure concentrates pricing power among vendors with pre-certified Basel III compliance modules and ISO 9001 quality management credentials.
Pricing Analysis
Cost-plus arrangements with cloud infrastructure indexation anchor enterprise pricing for multi-tenant deployments. Three-tier pricing structure across premium, standard, and economy levels separates regulatory compliance bundles from baseline risk assessment tools. Pricing pressure stems from mid-tier vendors competing on implementation speed for regional bank modernization projects. Regional banks in the United States exhibit highest price sensitivity due to constrained IT budgets, while sovereign wealth funds accept 40-60% premiums for air-gapped on-premises configurations.
Supply Chain Analysis
Inbound logistics costs from hyperscale cloud provider data centers in Virginia, Dublin, and Singapore determine marginal delivery economics for SaaS deployments. Software development draws from machine learning engineering talent pools concentrated in Bangalore, London, and the San Francisco Bay Area. Single-source vulnerability rests on proprietary alternative data feeds from payment processors. Distribution runs through system integrators and channel partners capturing implementation revenue previously accruing to vendors directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable barriers. Switching costs compound through model validation workflows and examiner familiarity with incumbent platforms.
For Market Incumbents: Compound regulatory moats by deepening EU AI Act pre-certification investments and extending independent validation infrastructure into emerging markets. Emerging API-first specialists threaten margin compression in mid-market segments. Vertical integration into alternative data streams from payment processors and digital wallets reinforces data reservoir differentiation. For New Entrants and Emerging Players: Differentiate on embedded finance integration velocity for e-commerce checkout flows and buy-now-pay-later platforms. India's SME lending digitization under RBI account aggregator frameworks offers the most penetrable geography. Climate risk scoring modules for EU Green Deal compliance provide a distinct go-to-market wedge. For Investors and Strategic Acquirers: Capital is best deployed toward specialized vendors with pre-built regulatory compliance modules and established channel partner ecosystems. Long-term viability favors platforms with explainable AI architectures that satisfy evolving algorithmic accountability mandates. Watch for SEC disclosure rule expansion into private credit markets as an inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Alternative Data Specialist | Proprietary payment processor feeds differentiate thin-file borrower scoring accuracy. |
| EU AI Act Pre-Certification Investment | Human-in-the-loop audit interfaces create compliance moats for European deployments. |
| Cloud Hyperscaler Partnership | Multi-tenant infrastructure scaling accelerates customer acquisition cost compression. |
| Climate Risk Module Development | Carbon exposure scoring captures premium feature demand under EU Green Deal rules. |
| API-First Platform Launch | Embedded finance convergence opens origination volume outside traditional banking channels. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with chief risk officers, model validation leads, regulatory affairs directors, and procurement officers at tier-one banks and asset managers. Secondary validation drew from SEC disclosure filings, European Banking Authority stress testing guidelines, Basel Committee technical standards, and cloud hyperscaler infrastructure expansion announcements. Bottom-up deployment mode sizing and top-down regulatory spend estimates were triangulated to anchor market boundaries.
Across the analysis window, forecasts segment by deployment mode, end-user institution type, compliance feature intensity, and regional regulatory cluster. CAGRs derive from modeled upgrade cycle compression and cloud migration velocity. Model inputs include Basel III validation frequency mandates, SEC credit risk transparency rule implementation timelines, and RBI account aggregator framework adoption curves.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory tightening and continued cloud infrastructure cost decline; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Benefits Consulting Service Market
Financial Services
US Healthcare Finance Solutions Market
Financial Services
Debt Collection Software and Service Market
Financial Services
Commodity Trade Finance Market
Financial Services
Financial Services Operational Risk Management Solution Market
Financial Services
Africa Lottery Market
Financial Services
Trade Finance Market
Financial Services
Global P2P Fundraising Tool Market
Financial Services
CFD Trading Affiliate Programs Market
Financial Services
Peer-To-Peer (P2P) Market
Financial Services
Mobile Notary Service Market
Financial Services
Banknote Counters Market
Financial Services
China Trade Finance Market
Financial Services
Europe Insurance Brokerage Market
Financial Services
Currency Exchange Software Market
Financial Services
South Korea Trade Finance Market