
 US Healthcare Finance Solutions Market | 2026-2036
US Healthcare Finance Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
US Healthcare Finance Solutions Market Intelligence
Enterprise-grade revenue cycle specifications is reorganizing capital deployment across the US healthcare finance landscape. Siemens Financial Services leverages captive equipment financing to anchor imaging and diagnostic infrastructure deals. Commerce Bankshares sustains regional dominance through relationship-driven lending to community hospital networks. Stryker competes via in-house leasing structures that tie surgical device placements to long-term service contracts.
Healthcare finance solutions encompass credit facilities, leasing structures, revenue cycle advances, and working capital instruments calibrated to provider cash flow cycles, collateralized by medical receivables or equipment residual values. These instruments bridge the reimbursement lag endemic to Medicare, Medicaid, and commercial payer cycles, preserving liquidity for clinical operations. Revenue cycle management services command the deepest margin pools as hospitals outsource denial management and prior authorization workflows. Cloud computing infrastructure is displacing on-premise deployments as health systems prioritize scalable interoperability. AI solutions within payment processing are capturing outsized investment as predictive analytics reduce bad debt exposure.
CMS, the Office of the National Coordinator for Health IT, and state-level departments of insurance collectively shape product design through interoperability mandates, information blocking penalties, and usury caps on medical receivables financing. HIPAA security requirements constrain cloud migration timelines, extending sales cycles for technology-integrated finance products. Stakeholders must monitor ONC rulemaking on algorithmic transparency, as forthcoming certification requirements could disqualify non-compliant AI underwriting tools from federal reimbursement-linked transactions.
Market Dynamics
Hospital systems are accelerating migration toward cloud-native revenue cycle platforms as CMS interoperability mandates under the 21st Century Cures Act force dismantling of legacy silos. Private equity-backed specialty roll-ups in the southeastern United States concentrate financing demand, compressing decision timelines for integrated credit facilities.
Growth Catalysts
- CMS Interoperability Mandates:The 21st Century Cures Act information blocking rules compel hospitals to replace fragmented billing systems with API-enabled platforms, creating immediate demand for technology-integrated financing structures.
- Rural Hospital Consolidation:Southeastern United States consolidation waves generate concentrated capital deployment opportunities as acquired facilities require working capital bridges and equipment refinancing.
- AI-Enabled Underwriting:Machine learning models analyzing medical receivables patterns reduce bad debt exposure, expanding addressable credit pools for specialty lenders.
Market Restraints
- HIPAA Security Compliance:Cloud migration timelines extend 18-24 months as health systems navigate Business Associate Agreement renegotiations and encryption standards verification.
- State Usury Caps:Medical receivables financing faces rate limitations in 17 states, compressing margin structures for non-bank lenders operating across jurisdictions.
- Legacy System Entrenchment:Epic and Cerner installations create switching costs exceeding $50 million for large health systems, delaying platform consolidation.
Strategic Opportunities
- Revenue Cycle Management Outsourcing:Denial management and prior authorization workflow automation represent underpenetrated service layers with 40-50% margin profiles.
- Equipment Residual Value Financing:MRI and CT scanner leasing structures tied to utilization-based payments capture value from imaging asset lifecycles.
- ONC Algorithmic Transparency Rules:Forthcoming certification requirements for AI underwriting tools create first-mover advantages for compliant vendors in federal reimbursement-linked transactions.
Industry Challenges
- Interoperability Talent Scarcity:Health systems face acute shortages of FHIR-standard developers and cloud security architects, extending implementation timelines.
- Payer Mix Volatility:Medicare Advantage penetration shifts and Medicaid redetermination waves create receivables forecasting complexity for credit underwriting models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Healthcare Finance Solutions Market |
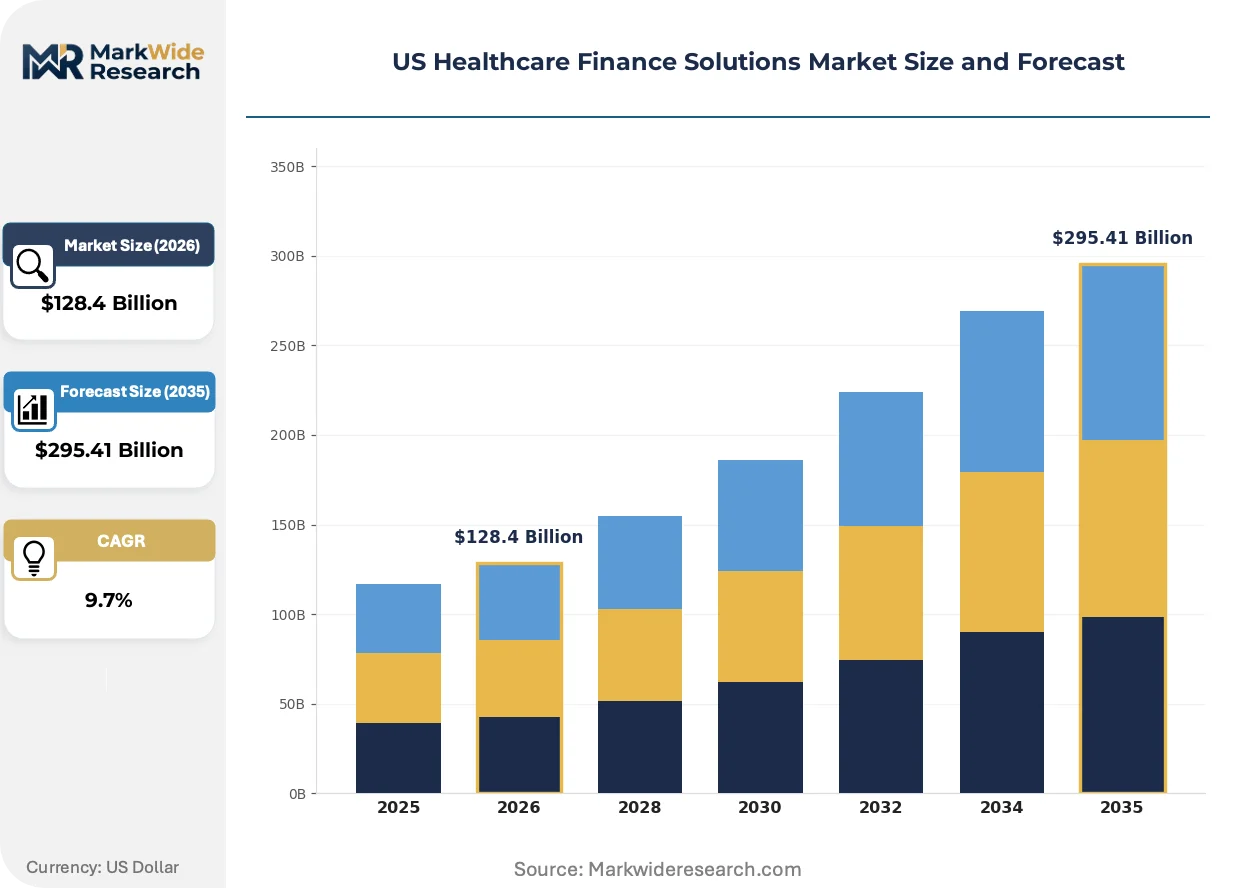
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $295.41 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Billing Services, Revenue Cycle Management, Payment Solutions, Analytics Services Client Type: Hospitals, Clinics, Insurance Providers, Healthcare Systems Technology: Blockchain, Cloud Computing, Machine Learning, AI Solutions End Use Industry: Pharmaceuticals, Medical Devices, Telehealth, Diagnostics |
| Companies Covered | Siemens Financial Services, Inc., General Electric Company, Commerce Bankshares, Inc., Thermo Fisher Scientific, Inc., Siena Healthcare Finance, CIT Group, Inc., Stryker, Gemino Healthcare Finance, Oxford Finance LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Healthcare Finance Solutions Market Strategic Shifts & Innovations
Cloud computing infrastructure is actively dismantling on-premise revenue cycle architectures. Health systems now prioritize scalable interoperability over capital-intensive data center ownership, compressing deployment models and reshaping vendor financing structures.
Application programming interfaces are decomposing monolithic electronic health record billing modules. Mid-sized hospital networks in Texas and Florida are adopting API-first platforms at accelerated paces, enabling modular best-of-breed component selection rather than single-vendor lock-in. This decomposition fragments purchasing authority across CFO, CIO, and revenue cycle VP roles, complicating vendor sales cycles.
The Office of the National Coordinator for Health IT is finalizing algorithmic transparency certification requirements for clinical decision support tools. These rules extend to AI-powered payment processing and prior authorization systems, forcing lenders to document underwriting model logic for federal reimbursement-linked transactions. Specialty finance providers serving Medicare-dependent hospitals face the steepest compliance ramps.
Subscription-based software procurement is displacing perpetual license purchases across community hospital networks. CFOs favor operational expenditure treatment for revenue cycle technology, aligning vendor payments with realized cash flow improvements. This shift concentrates in the southeastern United States where private equity-backed roll-ups standardize financial reporting across acquired facilities.
US Healthcare Finance Solutions Market Segmentation
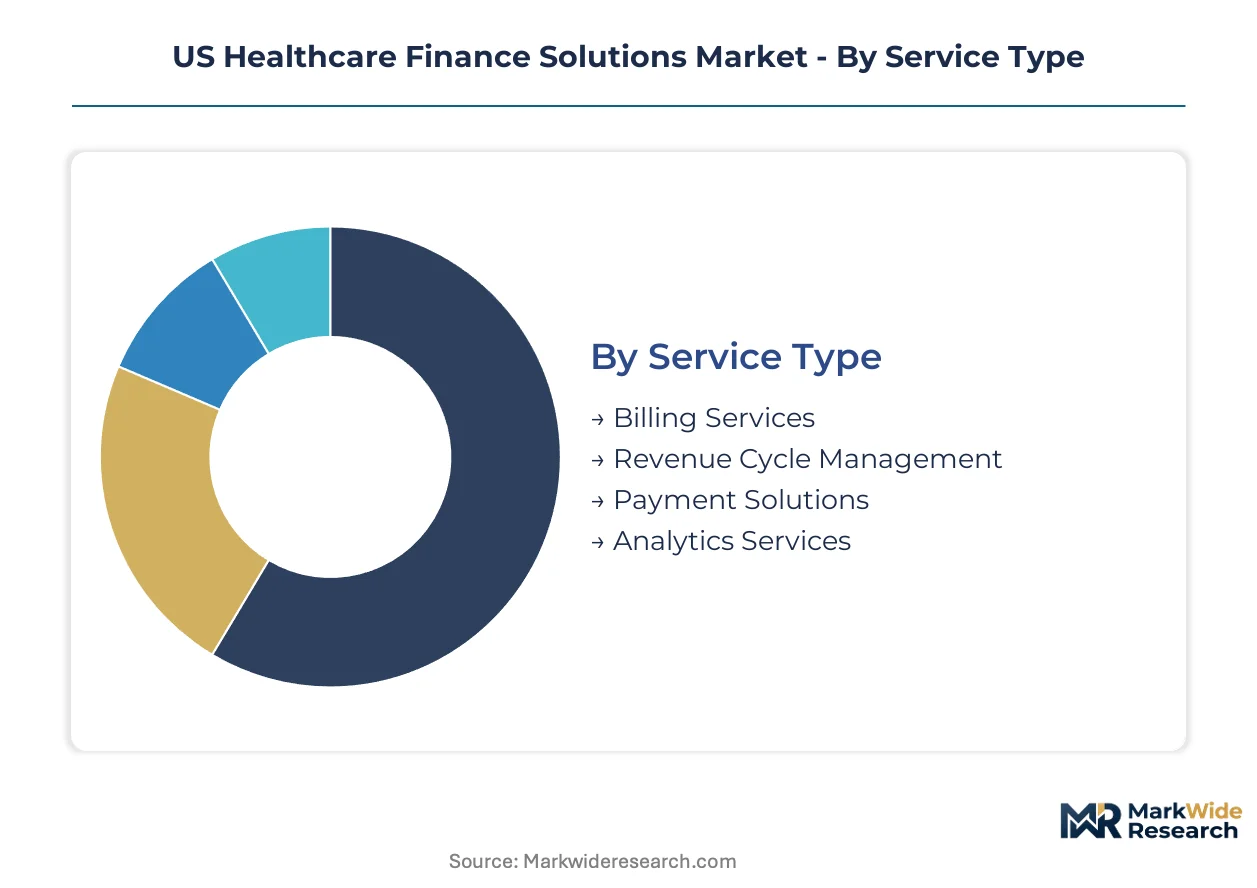
Healthcare finance solutions fragment across four critical dimensions that determine capital deployment patterns and vendor competitive positioning. Each segmentation axis reveals distinct substitution pressures, technology migration paths, and margin concentration zones that shape go-to-market strategies.
Service Type:
Revenue Cycle Management faces acute substitution pressure from integrated platform vendors bundling adjacent services, while standalone Billing Services confront automation-driven price compression from AI-enabled alternatives.
- Billing Services:Transactional coding and claims submission functions are experiencing rapid automation displacement. Southeastern hospital networks increasingly favor bundled platform contracts over standalone billing relationships as CMS mandates force system consolidation.
- Revenue Cycle Management:Comprehensive denial management, prior authorization workflows, and accounts receivable optimization command premium pricing. Texas and Florida health systems drive concentrated demand as private equity roll-ups standardize financial operations across acquired facilities.
- Payment Solutions:Patient financing and point-of-service collection tools bridge reimbursement lag cycles.
- Analytics Services:Predictive receivables forecasting and payer mix modeling support underwriting decisions.
Revenue Cycle Management retains volume leadership; Payment Solutions holds the steepest expansion curve as patient responsibility burdens climb.
Client Type:
Cost tier stratification separates enterprise health systems with captive treasury functions from community hospitals dependent on external financing structures.
- Hospitals:Academic medical centers and IDNs deploy integrated credit facilities spanning equipment leasing, working capital lines, and revenue cycle advances. Rural hospital consolidation in the Southeast generates concentrated refinancing demand as acquired facilities require liquidity bridges.
- Clinics:Specialty practice roll-ups in dermatology, orthopedics, and gastroenterology drive scalable financing templates. Private equity sponsors favor standardized credit structures across platform acquisitions, compressing due diligence timelines.
- Insurance Providers:Medicare Advantage plans and commercial payers require provider network financing support.
- Healthcare Systems:Vertically integrated delivery networks consolidate purchasing authority across constituent facilities.
Hospitals retain volume leadership; Clinics hold the steepest expansion curve as specialty consolidation accelerates.
Technology:
Application maturity divides established cloud deployments from emerging AI and blockchain architectures still seeking product-market fit.
- Cloud Computing:API-enabled revenue cycle platforms displace on-premise Epic and Cerner modules. HIPAA-compliant Business Associate Agreements and encryption verification extend sales cycles 18-24 months as health systems navigate security architecture transitions.
- AI Solutions:Machine learning models analyzing medical receivables patterns reduce bad debt exposure and expand addressable credit pools. ONC algorithmic transparency certification requirements create compliance ramps for Medicare-linked transactions.
- Blockchain:Distributed ledger applications for claims adjudication remain pilot-phase with limited production deployment.
- Machine Learning:Predictive underwriting tools segment credit risk within specialty lender portfolios.
Cloud Computing retains volume leadership; AI Solutions holds the steepest expansion curve as predictive analytics penetrate credit decisioning.
End Use Industry:
Customer type concentration varies sharply across pharmaceutical commercialization, device manufacturing, virtual care delivery, and diagnostic services.
- Medical Devices:MRI, CT, and surgical equipment leasing structures tie capital deployment to utilization-based payment models. Siemens Financial Services and Stryker deploy captive financing to anchor long-term service contracts and device placement commitments.
- Pharmaceuticals:Specialty drug distribution and patient access programs require working capital bridges for high-cost inventory.
- Telehealth:Virtual care platforms need scalable payment infrastructure for direct-to-consumer and employer contract channels.
- Diagnostics:Laboratory and imaging center networks concentrate financing demand in outpatient settings.
Medical Devices retains volume leadership; Telehealth holds the steepest expansion curve as virtual care payment models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Healthcare Finance Solutions Market operates as a domestic services ecosystem with capital flows concentrated among southeastern health systems, midwestern manufacturing corridors, and coastal technology hubs. Interstate regulatory variation and state-level usury caps create internal arbitrage opportunities for specialized lenders.
Southeast
Rural hospital consolidation and private equity-backed specialty roll-ups in Florida and Georgia generate concentrated demand for working capital bridges and equipment refinancing. CMS interoperability mandates accelerate cloud-native revenue cycle platform adoption across acquired facility networks. Atlanta anchors regional fintech development for healthcare payment processing infrastructure.
Texas
Independent hospital networks and ambulatory surgery center chains drive scalable financing templates for revenue cycle advances and leasing structures. State-level regulatory frameworks for medical receivables financing operate without usury rate compression, attracting non-bank lenders. Dallas-Fort Worth concentrates health system headquarters and captive equipment financing operations.
Midwest
Academic medical centers and integrated delivery networks in Illinois and Ohio deploy integrated credit facilities spanning equipment leasing and working capital lines. HIPAA security compliance timelines extend cloud migration decisions across legacy Epic installations. Cleveland Clinic and Northwestern Medicine anchor enterprise-grade revenue cycle specification demand.
California
Medicare Advantage penetration shifts and Medicaid redetermination waves create receivables forecasting complexity for underwriting models serving safety-net hospitals. State privacy regulations augment federal HIPAA requirements for cloud Business Associate Agreements. Bay Area technology vendors supply AI-enabled payment processing infrastructure to national health systems.
Northeast
Consolidated health system networks in Massachusetts and New York prioritize interoperability talent acquisition for FHIR-standard development. ONC algorithmic transparency certification requirements impose compliance ramps for AI underwriting tools in Medicare-linked transactions. Boston anchors health IT venture capital deployment for revenue cycle automation.
US Healthcare Finance Solutions Market Key Industry Players
Concentration sits with captive equipment finance arms of medical device manufacturers and relationship-driven regional banks. Tiered competition separates enterprise-scale integrated platform vendors from specialized medical receivables lenders. Strategic archetypes include captive finance subsidiaries, community bank networks, and private credit specialists. Dominant competitive moves encompass cloud-native platform consolidation and AI underwriting capability acquisition.
Among captive finance specialists, Siemens Financial Services, Inc. and Stryker occupy positions tying equipment placement to long-term service contracts. Commerce Bankshares, Inc. exemplifies relationship-driven regional banking archetypes serving community hospital networks. These three entities represent distinct capital deployment philosophies across the US healthcare finance landscape.
| Leading Market Players |
|---|
| Siemens Financial Services, Inc. |
| General Electric Company |
| Commerce Bankshares, Inc. |
| Thermo Fisher Scientific, Inc. |
| Siena Healthcare Finance |
| CIT Group, Inc. |
| Stryker |
| Gemino Healthcare Finance |
| Oxford Finance LLC |
| Others |
Cost & Logistics Intelligence
HIPAA security certification gates both vendor qualification and price differentiation across cloud-native revenue cycle platforms. Health systems demand Business Associate Agreement verification and encryption standard compliance before contract execution, while vendors bundle security architecture as premium-tier value.
Pricing Analysis
Hospital CFOs anchor subscription-based pricing structures for revenue cycle technology, favoring operational expenditure treatment over perpetual licenses. Price differentiation hinges on interoperability certification tier and AI-enabled predictive analytics depth. Cost compression in standalone billing services is intensifying because automation displaces transactional coding functions. Community hospital networks exhibit highest price sensitivity; academic medical centers prioritize integration depth over unit cost.
Supply Chain Analysis
The United States anchors health IT infrastructure development, with cloud service concentration in Virginia and Oregon data center clusters. Revenue cycle platform delivery draws from domestic software engineering talent pools and offshore development centers in India and Eastern Europe. Single-source vulnerability concentrates in FHIR-standard developer scarcity. Distribution runs through direct enterprise sales teams and health system GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US healthcare finance market is recovering from reimbursement cycle compression as Medicare Advantage penetration stabilizes and Medicaid redetermination waves plateau.
For Market Incumbents: Secure cloud-native platform consolidation through API-first architecture investments. Defend against fintech entrants by deepening embedded finance capabilities within revenue cycle workflows. Prioritize ONC algorithmic transparency certification to maintain federal reimbursement-linked transaction eligibility. For New Entrants and Emerging Players: Differentiate on AI-powered prior authorization automation targeting mid-sized hospital networks in Texas and Florida. Penetrate the revenue cycle management outsourcing segment where denial management workflows remain underautomated. Deploy subscription-based pricing aligned to realized cash flow improvements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native revenue cycle platforms as software margins expand. Long-term viability favors vendors with embedded AI underwriting and captive equipment financing arms. Monitor ONC rulemaking on algorithmic transparency as inflection signal for compliance-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Migration | API-enabled architectures displace legacy Epic modules across southeastern health systems. |
| AI Underwriting Certification | ONC algorithmic transparency compliance secures federal reimbursement-linked transaction access. |
| Revenue Cycle Outsourcing | Denial management automation captures 40-50% margin profiles in underpenetrated service layers. |
| Equipment Residual Financing | Utilization-based MRI and CT leasing structures tie capital deployment to asset lifecycle value. |
| Regional Bank Partnership | Relationship-driven lending anchors community hospital network loyalty against fintech disruption. |
Research Approach
Initial hypotheses were tested against primary input from hospital CFOs, revenue cycle VPs, health IT procurement officers, and specialty lender credit officers and refined through secondary validation. Sources included CMS Medicare cost reports, hospital procurement databases, GPO contract filings, and SEC 10-K disclosures from captive finance subsidiaries. Bottom-up facility-level modeling and top-down market sizing were triangulated to reconcile variance.
Variance decomposition across service type, client tier, technology maturity, and end-use industry segments informed the analytical framework. CAGRs were derived from segmented growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs incorporated payer mix volatility patterns and cloud migration timeline assumptions.
Material uncertainties — HIPAA compliance timeline extensions, state usury cap adjustments, and ONC algorithmic transparency rule finalization — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from regulatory implementation shifts. Recalibration cycles align with material shifts in CMS interoperability enforcement and Medicare Advantage penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Europe E-Invoicing Market
Financial Services
Global Treasury Management System (TMS) Market
Financial Services
Middle Office Outsourcing Market
Financial Services
Pawn Shop Market
Financial Services
Global Automated Algo Trading Market
Financial Services
Debt Collection Software and Service Market
Financial Services
Financial Services Application Market
Financial Services
North America Trade Finance Market
Financial Services
E-Invoicing Market
Financial Services
Global Executive Search (Headhunting) Market
Financial Services
Global Management Consulting Services Market
Financial Services
United States Credit Agency Market
Financial Services
Commercial Debt Collection Software Market
Financial Services
ATM Outsourcing Services Market
Financial Services
Germany Factoring Services Market
Financial Services
Africa Lottery Market