
 BFSI A2P SMS Market | 2026-2036
BFSI A2P SMS Market Size, Share, and Industry Trends Forecast 2026-2036
BFSI A2P SMS Market Analysis
Platform bundling of SMS gateway, cloud messaging, and API integration into unified communication suites is hardening buyer expectations for single-vendor solutions. Twilio Inc. leverages its developer-first API ecosystem to anchor enterprise relationships across retail banking and insurance verticals. Infobip Limited sustains competitive density through direct carrier agreements spanning Europe, Asia-Pacific, and Latin America. Sinch dominates the high-volume transactional segment with specialized routing intelligence that optimizes delivery rates for time-critical financial alerts.
BFSI A2P SMS denotes application-to-person messaging infrastructure purpose-built for financial services, transmitting encrypted alphanumeric payloads over SS7 or IP-based signaling protocols to authenticate transactions, disburse alerts, and deliver promotional content. The technology serves as a regulated communication backbone where delivery latency below five seconds and carrier-grade reliability are non-negotiable operational parameters. Cloud messaging and API integration are capturing disproportionate growth momentum as institutions abandon on-premise SMS gateways for elastic, consumption-priced infrastructure. Notifications and alerts command the largest revenue pool within service type segmentation, while promotions face margin compression under stricter consent frameworks.
TRAI in India enforces template-based SMS registration and scrubbing through distributed ledger technology to curb financial fraud, directly elevating compliance costs for third-party aggregators and direct carriers. GDPR and the EU AI Act impose parallel constraints on European BFSI messaging, mandating granular consent audit trails and automated decision-making disclosures for AI-driven customer support bots. Stakeholders must monitor divergence between India's centralized scrubbing architecture and Europe's consent-layer approach, as this regulatory asymmetry will shape vendor localization strategies and technology stack investments without convergence on the horizon.
Market Dynamics
Cloud-native messaging infrastructure is compressing deployment cycles from months to days, forcing incumbent aggregators to abandon on-premise gateway licensing in favor of consumption-priced API models. This shift reconfigures vendor economics toward per-message margins and erodes traditional hardware maintenance revenue streams.
Growth Catalysts
- UPI-linked authentication surge:India's real-time payment rails generate massive transactional SMS volume for payment confirmations and OTP verification across tier-1 and tier-2 urban clusters.
- GDPR consent framework maturation:European financial institutions now treat SMS as a compliant first-factor channel, expanding alert volumes for balance notifications and fraud warnings.
- Template-based scrubbing mandates:TRAI's distributed ledger infrastructure for SMS registration elevates barriers for non-compliant aggregators, consolidating volume with certified carriers.
Market Restraints
- SS7 signaling vulnerability:Inter-carrier routing protocols remain susceptible to interception and spoofing attacks, exposing financial institutions to liability for authentication breaches.
- Carrier concentration in emerging markets:Three mobile network operators control over seventy percent of termination capacity in key African and Southeast Asian markets, inflating wholesale messaging costs.
- Rich Communication Services substitution:Google's RCS Business Messaging and Apple's Business Chat threaten to displace alphanumeric SMS for promotional and high-engagement use cases.
Strategic Opportunities
- Latin America underpenetration:Brazil and Mexico exhibit SMS banking adoption rates below fifteen percent despite high smartphone penetration, creating whitespace for authentication-as-a-service models.
- AI-driven personalization convergence:Natural language generation layered atop transactional SMS enables contextual cross-sell inserts without violating character limits or latency thresholds.
- EU AI Act disclosure requirements:Automated decision-making mandates for chatbot interactions create demand for hybrid SMS-human escalation workflows that vendors can productize.
Industry Challenges
- Telecom signaling expertise scarcity:Deep knowledge of SS7, SIGTRAN, and Diameter protocols concentrates among retiring carrier engineers, complicating in-house gateway development.
- Multi-jurisdiction template registration:Financial institutions operating across India, Europe, and Gulf states must maintain separate scrubbing registrations with divergent formatting rules.
- Legacy core banking integration:Mainframe-based transaction processing systems require custom middleware to trigger real-time SMS alerts, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BFSI A2P SMS Market |
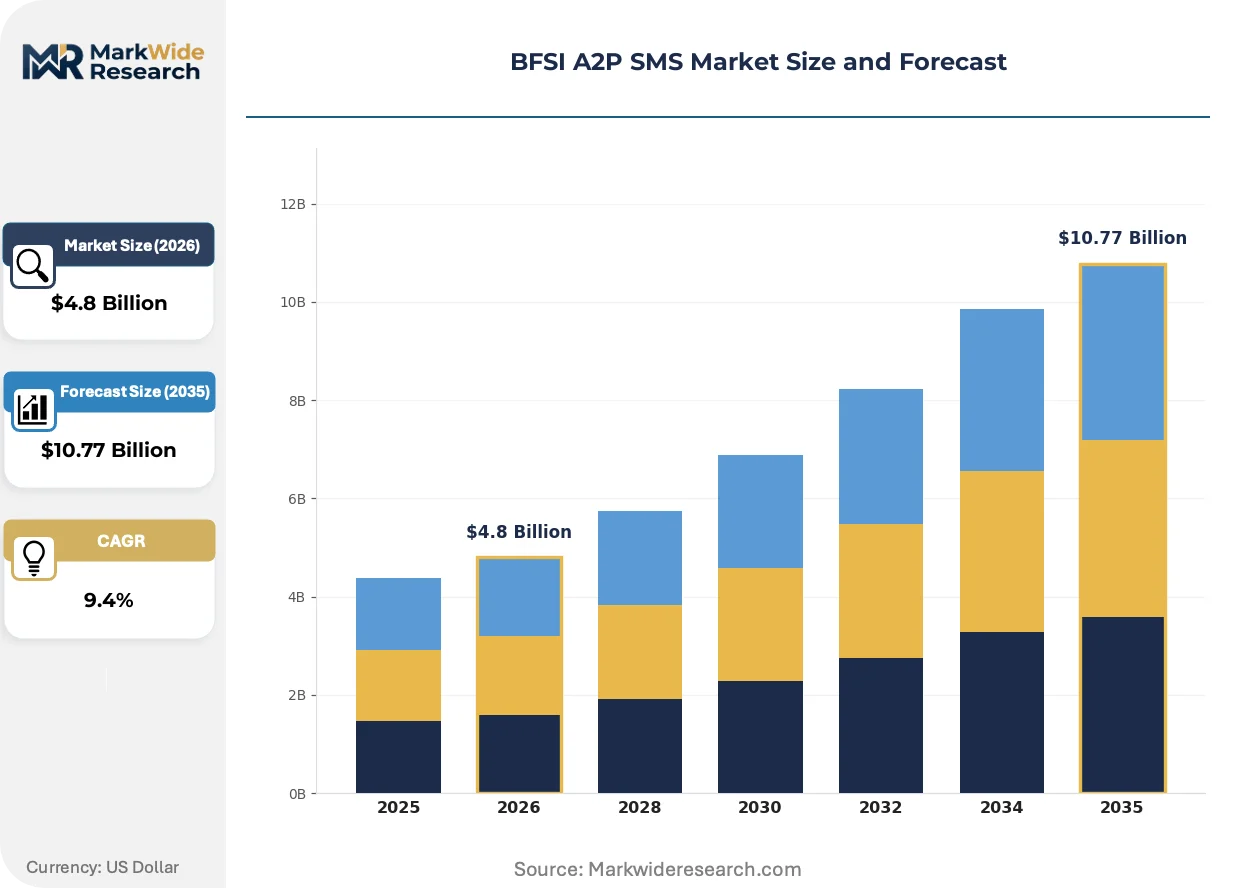
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.77 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Retail Banking, Insurance, Investment Firms, Credit Unions Service Type: Notifications, Promotions, Alerts, Customer Support Technology: SMS Gateway, Cloud Messaging, API Integration, Proximity Messaging Distribution Channel: Direct Carrier Billing, Mobile Wallets, Third-Party Aggregators, Premium SMS |
| Companies Covered | Sinch, Twilio Inc., Infobip Limited, Tata Communications Limited, Orange S.A., AT&T Intellectual Property, Vonage, Route Mobile Limited, China Mobile Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BFSI A2P SMS Market Emerging Trajectories
Hyper-personalized transactional content is displacing generic alerts, with institutions embedding dynamic account data and localized language variants within single SMS payloads. This evolution compresses the boundary between operational messaging and relationship marketing.
Rich Communication Services is rewriting competitive positioning in promotional and interactive banking use cases. European retail banks and fintech lenders are piloting RCS for credit pre-qualification flows and visual statement delivery. The technology is compressing SMS margins in customer acquisition while creating new revenue pools for verified sender identity and interactive call-to-action buttons.
GDPR's Article 7 consent documentation requirements and the EU AI Act's automated decision transparency mandates are tightening audit obligations for European BFSI messaging. Financial institutions must now maintain granular consent trails linking each SMS to explicit opt-in timestamps and purpose specifications. Insurance underwriters deploying algorithmic pricing via SMS notifications face heightened disclosure burdens, driving demand for compliance-integrated messaging platforms.
Buyer concentration among neobanks and digital lenders is shortening vendor selection cycles and compressing contract values. Monzo, N26, and similar institutions procure messaging infrastructure through developer-centric marketplaces rather than enterprise procurement processes. This pattern concentrates volume with API-first aggregators and marginalizes traditional carrier-direct relationships in Western European markets.
BFSI A2P SMS Market Segmentation
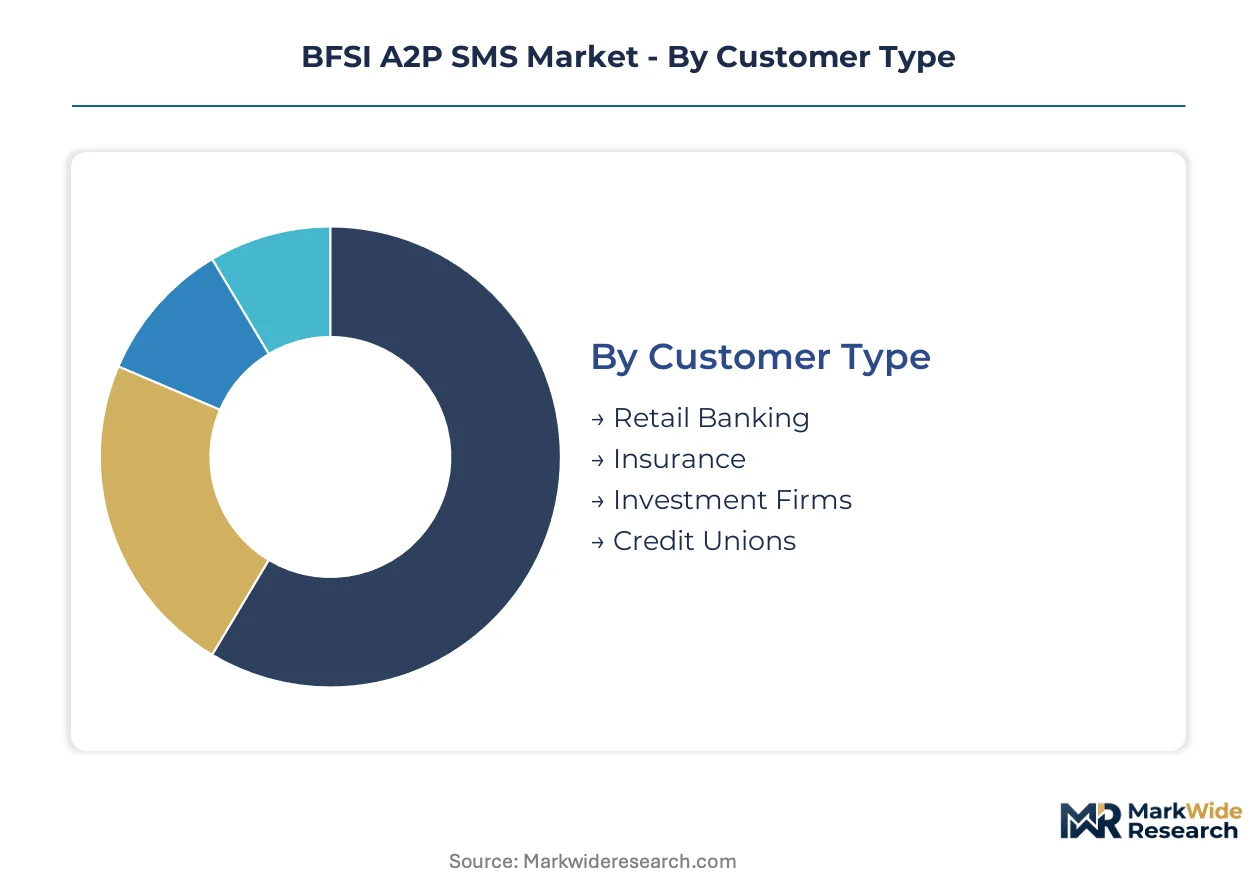
Segmentation in BFSI A2P SMS reveals how infrastructure choices, regulatory exposure, and customer sophistication create divergent margin profiles. Understanding these divides enables vendors to align routing intelligence, compliance tooling, and pricing models with specific demand pockets.
Customer Type:
Technology sophistication varies sharply across institutional categories, determining whether deployments prioritize latency optimization or template compliance automation.
- Retail Banking:Transactional volume dominance drives investment in sub-five-second delivery SLAs and SS7/SIGTRAN protocol redundancy. Indian public sector banks and European neobanks anchor demand, with UPI-linked OTP flows and PSD2 Strong Customer Authentication mandates forcing infrastructure upgrades.
- Insurance:Underwriters deploy A2P SMS for policy renewal alerts, claims status updates, and algorithmic pricing notifications. GDPR Article 7 consent trails and EU AI Act disclosure requirements complicate messaging workflows, elevating demand for audit-integrated platforms.
- Investment Firms:Trade execution confirmations and margin call alerts require encrypted payload transmission. Regulatory pressure from SEC and FCA concentrates volume with carriers offering end-to-end encryption certifications.
- Credit Unions:Member communication budgets constrain deployment to basic promotional and transactional use cases. Community-focused institutions in the US and Canada prioritize cost-per-message over routing intelligence.
Mature deployment sits with Retail Banking. Newer deployment is concentrated in Insurance.
Service Type:
Margin compression follows regulatory intensity, with consent-heavy categories facing cost inflation while operational messaging captures volume premiums.
- Notifications:Balance updates, payment confirmations, and account status alerts constitute the revenue foundation. Indian UPI ecosystem expansion and European PSD2 compliance are expanding addressable volume for time-critical operational messaging.
- Alerts:Fraud warnings and security breach notifications demand instantaneous delivery with read receipts. Financial institutions in Germany and Singapore treat this category as non-negotiable infrastructure, paying carrier premiums for guaranteed termination.
- Promotions:Cross-sell and upsell campaigns face TRAI template registration costs and GDPR consent documentation burdens. Margin erosion is accelerating as RCS Business Messaging captures visual engagement use cases.
- Customer Support:Two-factor authentication and chatbot escalation workflows require hybrid SMS-human handoff capabilities. EU AI Act automated decision transparency mandates are forcing disclosure-heavy implementations.
Alerts command the steepest expansion trajectory as fraud detection investments intensify. Promotions face structural headwinds from channel substitution.
Technology:
Deployment architecture choices determine capital efficiency, with cloud-native models displacing hardware-dependent alternatives.
- Cloud Messaging:Elastic infrastructure enables consumption-priced scaling for variable transaction volumes. Neobanks and digital lenders in Brazil and Mexico are bypassing on-premise gateways entirely, compressing procurement cycles from quarters to weeks.
- API Integration:Developer-first embedding into core banking and CRM systems anchors enterprise relationships. Twilio and similar platforms capture this segment through documentation quality and sandbox tooling.
- SMS Gateway:On-premise hardware persists among Tier-1 banks with legacy mainframe dependencies. Maintenance revenue streams are eroding as institutions migrate to cloud alternatives.
- Proximity Messaging:Geofenced branch alerts and ATM location services remain experimental. Pilots in South Korea and the UAE are testing beacon-triggered SMS for personalized in-branch engagement.
Established infrastructure concentrates in SMS Gateway. Cloud-native adoption is climbing the fastest among neobank entrants.
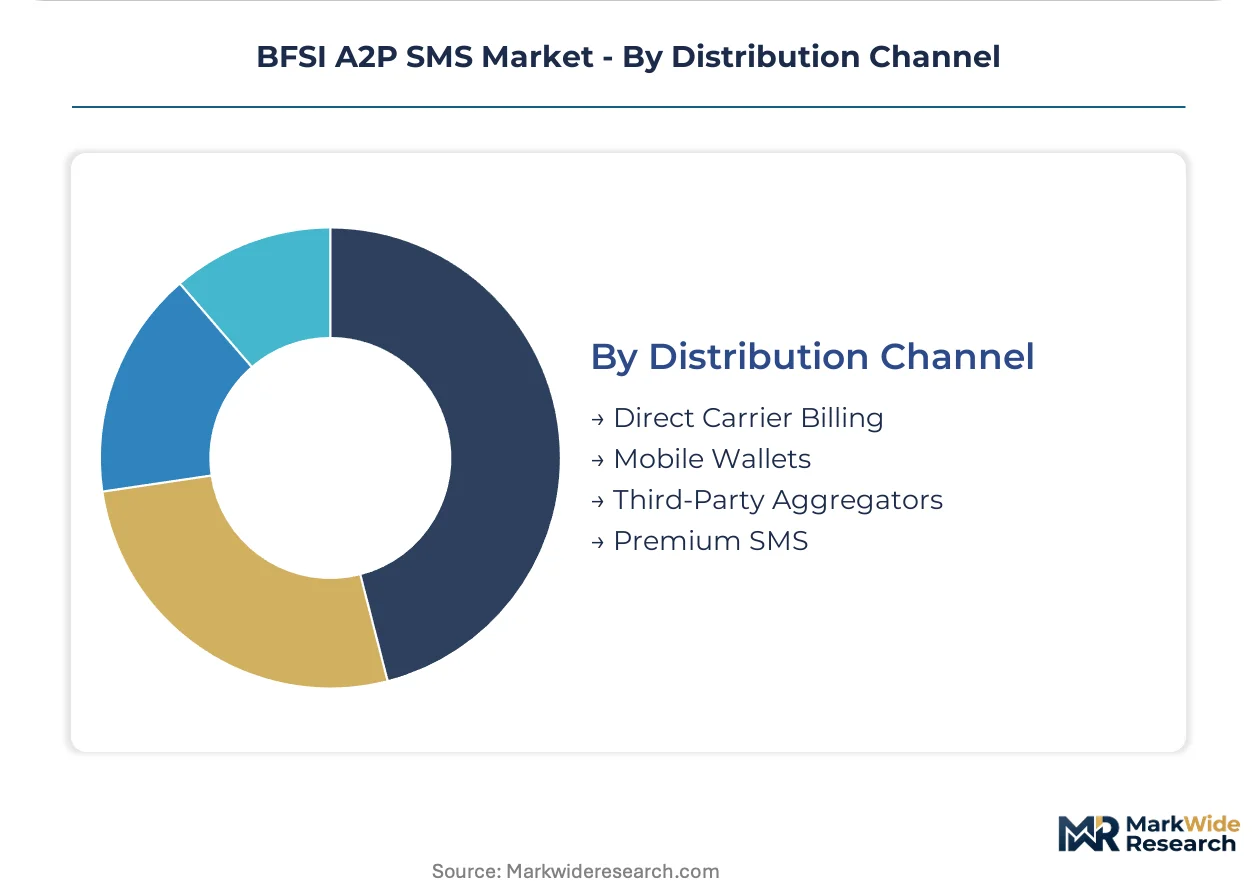
Distribution Channel:
Channel structure shapes pricing power, with direct carrier relationships offering termination control and aggregator models providing geographic reach.
- Third-Party Aggregators:Multi-carrier routing intelligence optimizes delivery rates across fragmented markets. Infobip and Sinch sustain competitive density through direct carrier agreements spanning India, Germany, and Brazil.
- Direct Carrier Billing:Mobile network operators in Nigeria and Indonesia capture premium pricing for authentication traffic where termination capacity concentrates among three providers.
- Mobile Wallets:Paytm, PhonePe, and similar platforms in India generate embedded SMS volume for KYC verification and transaction receipts. Wallet-integrated messaging bypasses traditional aggregator margins.
- Premium SMS:Shortcode-based services for banking subscriptions and insurance premium collection face regulatory scrutiny. TRAI and Ofcom have imposed rate caps and consent requirements, compressing profitability.
Volume concentrates with Third-Party Aggregators. Mobile Wallets are gaining share fastest as payment-app ecosystems deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes the largest share of BFSI A2P SMS volume while European carriers capture the highest termination margins. Regulatory divergence between these consumption poles is fragmenting vendor localization strategies.
India
UPI-linked authentication and digital payment proliferation drive massive transactional SMS volumes across tier-1 and tier-2 urban clusters. TRAI enforces template-based SMS registration through distributed ledger technology, elevating compliance costs for aggregators. Mumbai and Bangalore host the densest concentration of certified carriers scrubbing financial messages against fraud databases.
Germany
PSD2 Strong Customer Authentication mandates expand alert volumes for balance notifications and fraud warnings. GDPR Article 7 consent documentation requirements tighten audit obligations for every SMS dispatched. Frankfurt's fintech corridor anchors demand from neobanks procuring messaging infrastructure through developer-centric marketplaces.
United States
Retail banking institutions invest in sub-five-second delivery SLAs for OTP verification and payment confirmations. SEC and FCA regulatory pressure concentrates volume with carriers offering end-to-end encryption certifications. New York and San Francisco metropolitan areas generate the highest density of transactional messaging for investment firms and digital lenders.
Brazil
SMS banking adoption rates remain below fifteen percent despite high smartphone penetration, creating whitespace for authentication-as-a-service models. ANVISA and central bank regulations govern financial messaging compliance without mandating template scrubbing. São Paulo's neobank cluster is bypassing on-premise gateways entirely for cloud-native API integration.
United Arab Emirates
Geofenced branch alerts and beacon-triggered SMS pilots test personalized in-branch engagement in Dubai and Abu Dhabi. MOHAP and central bank frameworks regulate financial messaging without the granular consent requirements seen in Europe. The Dubai International Financial Centre concentrates demand from investment firms requiring encrypted payload transmission for trade execution confirmations.
BFSI A2P SMS Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across routing intelligence, API ecosystems, and carrier-direct relationships. Market structure tilts toward consolidation as template compliance mandates and cloud migration raise barriers for regional aggregators. Three strategic archetypes dominate: developer-first API platforms, carrier-integrated routing specialists, and telecom-owned messaging divisions. Competitive moves concentrate on M&A for geographic reach and strategic partnerships for scrubbing infrastructure access.
Among developer-first platforms, Twilio Inc. and Vonage occupy positions anchoring enterprise relationships through documentation quality and sandbox tooling. Sinch exemplifies the routing intelligence archetype with specialized optimization for time-critical financial alerts. Infobip Limited represents the carrier-integrated model through direct agreements spanning India, Germany, and Brazil. Tata Communications Limited and Route Mobile Limited sit within the Asia-Pacific carrier-affiliated tier, while Orange S.A. and AT&T Intellectual Property anchor telecom-owned messaging divisions in their respective domestic markets.
| Leading Market Players |
|---|
| Sinch |
| Twilio Inc. |
| Infobip Limited |
| Tata Communications Limited |
| Orange S.A. |
| AT&T Intellectual Property |
| Vonage |
| Route Mobile Limited |
| China Mobile Limited |
Supply Flow & Price Mechanics
Neobank and digital lender procurement concentration is compressing contract values and forcing consumption-priced API models over traditional hardware licensing. This buyer shift reconfigures vendor economics toward per-message margins and erodes maintenance revenue streams that once anchored carrier-direct relationships.
Pricing Analysis
Margin tightening in the transactional SMS tier reflects template registration cost inflation under TRAI's distributed ledger mandates. Pricing stratifies across premium guaranteed-delivery, standard routed, and economy bulk tiers, with latency SLAs and scrubbing certification as primary differentiation drivers. Cost-down pressure on promotional messaging accelerates because RCS Business Messaging captures visual engagement use cases. Credit unions and community banks exhibit the highest price sensitivity, while investment firms prioritize encryption certification over per-message cost.
Supply Chain Analysis
Dual-sourcing requirements for carrier termination capacity are mandating multi-vendor qualification across India, Germany, and Brazil. Infrastructure draws from SS7/SIGTRAN signaling hardware, cloud compute instances, and distributed ledger scrubbing nodes. Single-source vulnerability concentrates in Indian carrier markets where three operators control termination capacity. Distribution runs through third-party aggregators with direct carrier agreements, bypassing traditional hardware gateway vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where TRAI's template-based SMS registration creates a barrier-to-entry moat for certified aggregators. Regulatory certification investments now separate viable competitors from marginal players.
For Market Incumbents: Deploy scrubbing infrastructure partnerships to defend volume concentration against RCS substitution threats. Deepen API ecosystem documentation quality to anchor neobank relationships. Prioritize direct carrier agreements in India and Brazil where termination capacity concentrates. For New Entrants and Emerging Players: Launch via authentication-as-a-service models in Brazil and Mexico where SMS banking penetration remains below fifteen percent. Target credit unions in North America with cost-optimized promotional messaging bundles. Pursue cloud-native positioning to compress procurement cycles from quarters to weeks. For Investors and Strategic Acquirers: The window for entry favors carrier-integrated routing specialists with established scrubbing certifications. Long-term viability hinges on template compliance automation capabilities rather than raw delivery volume. Watch for divergence between India's centralized scrubbing architecture and Europe's consent-layer approach as the signal for regional vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Scrubbing Infrastructure Partnership | TRAI certification requirements elevate barriers for non-compliant aggregators in India. |
| API-First Platform Integration | Developer-centric embedding anchors enterprise relationships with neobanks and digital lenders. |
| Direct Carrier Agreement Expansion | Termination control in fragmented markets optimizes delivery rates for time-critical alerts. |
| RCS Business Messaging Pilot | Visual engagement capabilities capture promotional use cases displacing alphanumeric SMS. |
| Geographic Expansion into Latin America | Underpenetrated authentication markets in Brazil and Mexico offer whitespace for API-native entrants. |
Methodological Framework
Document review covered regulatory filings from TRAI, GDPR implementation guidance, and carrier tariff disclosures, complemented by interviews with SMS platform engineering directors, financial institution IT procurement officers, telecom signaling protocol specialists, and compliance officers at third-party aggregators. Secondary validation drew from SEC 10-K disclosures of listed messaging vendors, hyperscaler communication API documentation, and distributed ledger scrubbing infrastructure specifications. Bottom-up volume modeling and top-down market sizing were triangulated against carrier termination data.
Historical volume trajectories were cross-referenced against panel input from platform vendors and financial institution messaging budgets. Segmentation dimensions modeled include customer type, service type, deployment architecture, and distribution channel complexity. CAGRs were derived from regression analysis of transactional SMS volume growth against payment rail expansion and authentication mandate implementation. Industry-specific forecast inputs incorporated UPI transaction growth rates and PSD2 Strong Customer Authentication compliance timelines.
Regulatory enforcement intensity, RCS adoption velocity, and carrier consolidation patterns are the dominant revision risks to the outlook. Deviation in TRAI's template registration cost trajectory would shift vendor margin assumptions materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Smart Finance Services Market
Financial Services
Peer-To-Peer (P2P) Market
Financial Services
Digital Transformation in BFSI Market
Financial Services
Account Aggregators Market
Financial Services
Virtual Account Management Software Market
Financial Services
Global Automated Algo Trading Market
Financial Services
ATM Software Market
Financial Services
Cash Logistics Market
Financial Services
Capital Restructuring Services Market
Financial Services
Foreign Exchange Services Market
Financial Services
ATM Managed Services Market
Financial Services
US Healthcare Finance Solutions Market
Financial Services
BFSI Contact Center Analytics Market
Financial Services
Germany Factoring Services Market
Financial Services
E-Invoicing Market
Financial Services
ATM Management Service Market