
 Smart Cooling Systems Market | 2026-2036
Smart Cooling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Cooling Systems Market Analysis
Data center cooling is consolidating as the fastest-expanding end-use vertical within smart cooling systems. Carrier Global Corporation leverages its chiller technology leadership to anchor large-scale hyperscale contracts. Schneider Electric SE specializes in integrated rack-level cooling and thermal management software for edge facilities. Daikin Industries Ltd. competes through its inverter-driven precision units designed for server room density requirements.
Smart cooling systems integrate sensor networks, variable-speed compressors, and AI-driven control algorithms to modulate thermal output against real-time load conditions, typically achieving coefficient of performance ratings above seasonal energy efficiency ratio benchmarks for conventional equipment. Ductless mini-splits lead residential retrofit installations where centralized ductwork is impractical, while smart thermostats capture recurring software revenue streams through utility demand-response program integration. AI control systems represent the fastest-growing technology segment as machine learning models optimize setpoints across multi-zone commercial buildings.
The US Department of Energy enforces minimum energy conservation standards under federal appliance regulations, while the EU F-Gas Regulation mandates phasedown of hydrofluorocarbon refrigerants with high global warming potential. China's GB standards and MIIT directives shape domestic product certification requirements for connected HVAC equipment. Stakeholders must monitor refrigerant chemistry transitions, grid-interactive control mandates, and evolving data center power usage effectiveness thresholds that redefine competitive product specifications.
Market Dynamics
AI-driven control architectures are compressing thermal management cycles across data center and commercial building deployments, forcing incumbent equipment manufacturers to restructure software capabilities around predictive load algorithms rather than hardware-centric specifications.
Growth Catalysts
- Data center power density thresholds:Hyperscale operators in China and the United States are mandating liquid-cooled rack architectures for AI training clusters above 50kW per rack, pulling demand for precision cooling infrastructure.
- EU F-Gas Regulation phasedown:The European Union's hydrofluorocarbon reduction mandates are accelerating refrigerant chemistry transitions toward hydrofluoroolefins and natural refrigerants in commercial chiller replacements.
- Smart city thermal networks:Municipal district cooling projects in Singapore and the United Arab Emirates are integrating AI-optimized central plants with building-level demand response systems.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger and compressor manufacturers face margin compression from base metal price swings tied to Chilean and Indonesian supply disruptions.
- Refrigerant supply concentration:Hydrofluoroolefin production capacity clusters with Chinese chemical conglomerates, creating import dependency risks for European and North American equipment assemblers.
- Legacy control protocol fragmentation:BACnet, Modbus, and proprietary building automation systems resist seamless AI overlay integration, extending deployment timelines.
Strategic Opportunities
- Edge facility thermal management:Distributed AI inference nodes in Germany and Japan lack purpose-built compact cooling, opening white space for rack-integrated liquid cooling modules.
- Grid-interactive responsive assets:Utility demand-response programs in California and Texas are certifying smart cooling systems as virtual power plant resources, creating new revenue streams.
- Sensor-fusion predictive maintenance:Vibration, acoustic, and thermal imaging convergence enables condition-based service contracts displacing scheduled maintenance in commercial portfolios.
Industry Challenges
- Refrigerant handling certification bottlenecks:EPA Section 608 and EU F-Gas technician qualification requirements are constraining installation capacity during peak replacement seasons.
- Multi-protocol integration complexity:Data center operators struggle to unify legacy chiller controls with new AI orchestration layers without operational downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Cooling Systems Market |
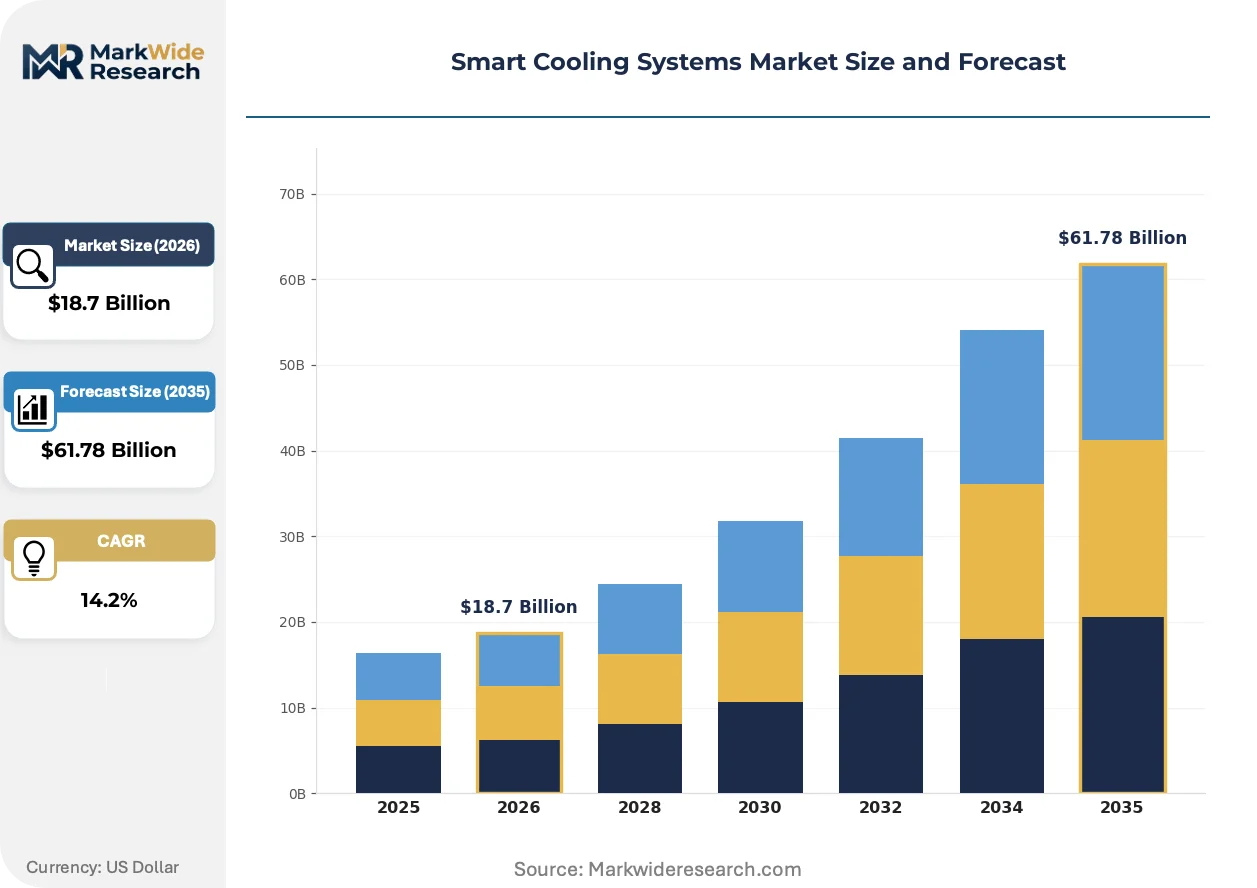
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Central Systems, Ductless Mini-Splits, Smart Thermostats Technology: Inverter Technology, Smart Sensors, Eco-Friendly Refrigerants, AI Control Systems End User: Residential, Commercial, Industrial, Data Centers Distribution Channel: Direct Sales, E-Commerce, Retail Outlets, Distributors |
| Companies Covered | Mitsubishi Electric Corporation, LG Electronics Ltd., Samsung Electronics Co. Ltd., Daikin Industries Ltd., Johnson Controls International plc, Schneider Electric SE, Carrier Global Corporation, Honeywell International Inc., Trane Technologies plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Cooling Systems Market Emerging Trajectories
Machine learning inference at the edge is compressing thermal response latency from minutes to seconds, enabling cooling systems to track compute load transients in real time rather than reacting to temperature excursions after they occur.
Liquid-to-chip cooling is consolidating as the dominant thermal architecture for high-density AI training infrastructure. Hyperscale operators in Nevada and Hebei Province are specifying direct-to-processor cold plates for racks exceeding 100kW. This technology is consolidating supplier relationships around specialized fluid management and leak detection capabilities that air-cooled incumbents lack.
The EU F-Gas Regulation is forcing refrigerant portfolio reconstitution across European chiller manufacturers. The phasedown schedule compresses hydrofluorocarbon availability for service and new equipment, pushing equipment buyers toward ammonia and carbon dioxide systems in industrial applications. German chemical facilities and Dutch greenhouse operators are piloting transcritical CO2 systems at scale.
Performance-based service contracting is displacing capital purchase models in commercial building portfolios. Facility managers in Australia and South Korea are procuring cooling-as-a-service agreements where providers guarantee thermal output per square meter. This shifts capex burden to vendors while binding contract duration to measured energy efficiency outcomes.
Smart Cooling Systems Market Segmentation
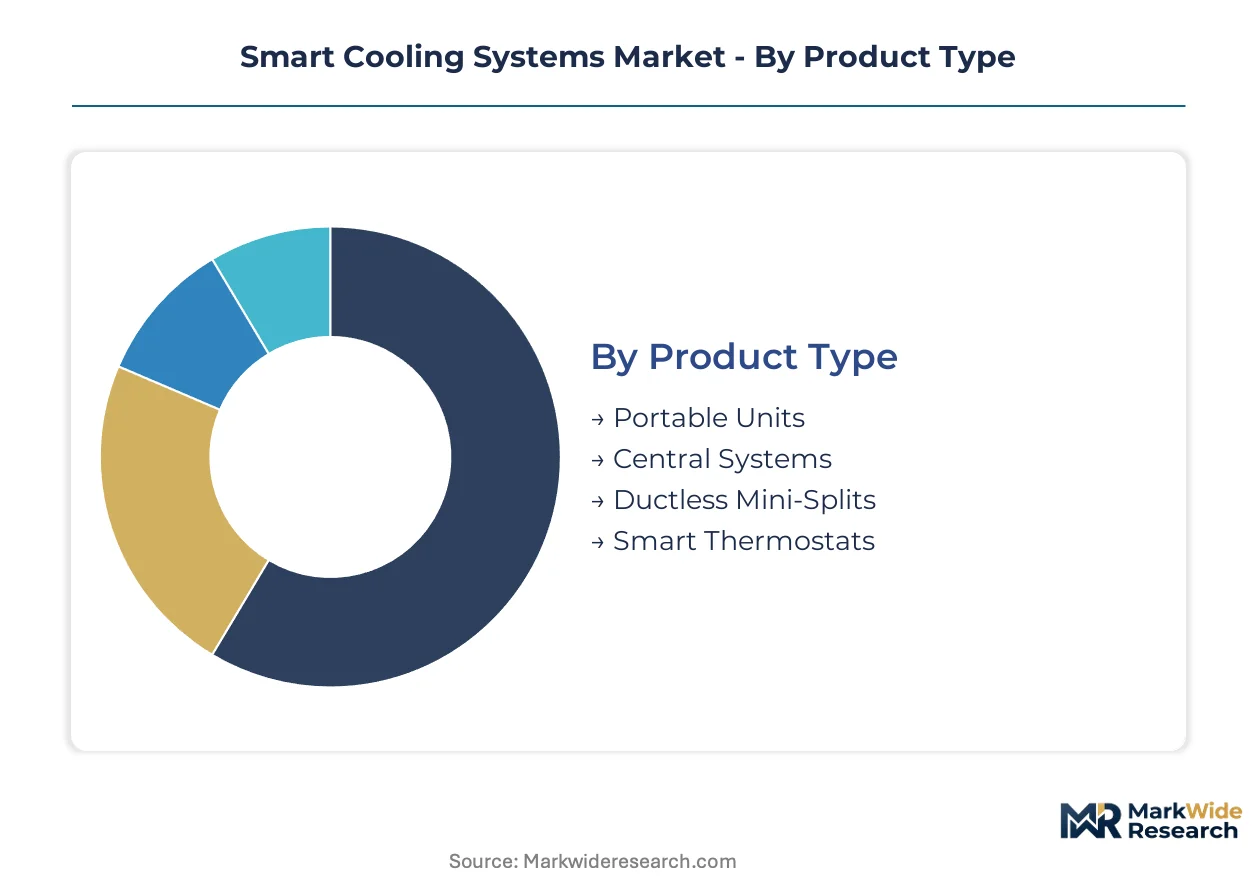
Smart cooling systems fragment across four critical dimensions that shape procurement patterns and vendor positioning. Product architecture determines installation complexity and upfront capital requirements. Technology stack differentiation separates hardware-centric suppliers from software-enabled platform providers. End-use concentration drives specification intensity, from residential comfort to industrial precision. Channel strategy dictates margin capture and customer relationship depth.
Product Type:
Buyers in this category separate by infrastructure constraints and ownership models rather than cooling capacity alone.
- Central Systems:Chiller and packaged rooftop units serve large commercial footprints and district cooling networks. Demand concentrates in China and the United Arab Emirates where municipal thermal infrastructure scales fastest, constrained by refrigerant handling certification bottlenecks during peak installation seasons.
- Smart Thermostats:Networked control devices capture recurring software revenue through utility demand-response integration. North American residential retrofits and European building automation upgrades drive procurement, pulled by FERC grid-interactive asset certification and EU energy performance mandates.
- Ductless Mini-Splits:Inverter-driven wall-mounted units dominate residential additions where ductwork retrofit proves impractical.
- Portable Units:Mobile cooling serves temporary and rental applications with minimal installation requirements.
Volume sits with Central Systems; growth tilts toward Smart Thermostats.
Technology:
Specification intensity in this category tracks end-use thermal precision requirements and regulatory compliance deadlines.
- AI Control Systems:Machine learning platforms optimize setpoints across multi-zone buildings and data center halls. Hyperscale operators in Nevada and Hebei Province mandate real-time load tracking for AI training clusters above 50kW per rack, compressing thermal response latency from minutes to seconds.
- Eco-Friendly Refrigerants:Hydrofluoroolefin and natural refrigerant formulations replace hydrofluorocarbons under phasedown schedules. European chiller replacements and Japanese commercial retrofits accelerate adoption, constrained by production concentration among Chinese chemical conglomerates.
- Inverter Technology:Variable-speed compressor modulation improves part-load efficiency in residential and light commercial applications.
- Smart Sensors:Temperature, humidity, and occupancy detection networks feed control algorithms with environmental data.
Revenue concentrates in AI Control Systems; specification intensity peaks with Eco-Friendly Refrigerants.
End User:
Customer type in this category determines capital deployment scale, operational uptime requirements, and service contracting preferences.
- Data Centers:Precision cooling infrastructure serves compute density thresholds exceeding 100kW per rack. Liquid-to-chip cold plate architectures consolidate in Nevada and Hebei Province hyperscale facilities, displacing air-cooled legacy systems unable to manage AI training cluster thermal loads.
- Commercial:Office, retail, and hospitality installations procure cooling-as-a-service agreements with guaranteed thermal output per square meter. Australian and South Korean facility managers shift capex burden to vendors through performance-based contracts tied to measured energy efficiency outcomes.
- Residential:Single-family and multi-family dwellings prioritize upfront cost and installation simplicity.
- Industrial:Manufacturing and process cooling demands ruggedized equipment with extended operational lifecycles.
Capital deployment scales highest in Data Centers; contract innovation emerges first in Commercial.
Distribution Channel:
Channel selection in this category reflects buyer technical sophistication and project scale fragmentation.
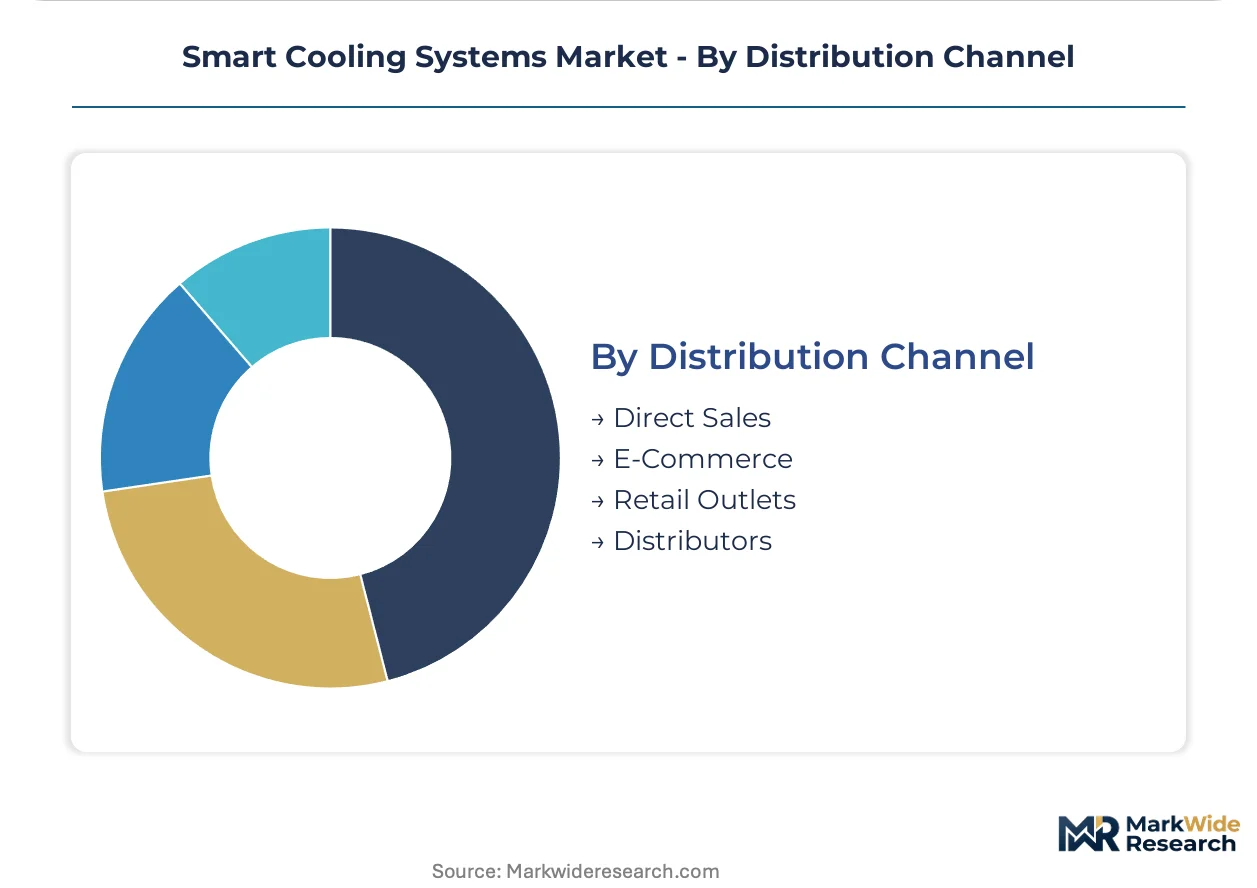
- Direct Sales:Manufacturer-led contracting serves large infrastructure projects and national account relationships. Data center operators in Singapore and Germany specify integrated thermal management packages directly with equipment providers to unify warranty and service accountability.
- E-Commerce:Online platforms capture residential thermostat and portable unit transactions. North American and European consumer procurement shifts toward digital channels for standardized products with minimal configuration requirements.
- Distributors:Wholesale networks stock inventory for contractor pull-through in fragmented commercial and residential markets.
- Retail Outlets:Big-box and specialty stores serve emergency replacement and consumer discretionary purchases.
Transaction volume flows through E-Commerce; project value concentrates in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port and Yangtze River Delta special economic zones concentrate smart cooling manufacturing and hyperscale data center deployment. Singapore's Jurong Innovation District anchors municipal district cooling networks. Germany's Ruhr industrial corridor drives commercial building retrofit demand.
United States
Hyperscale data center construction in Nevada and Virginia pulls precision liquid cooling infrastructure for AI training clusters exceeding 100kW per rack. The US Department of Energy enforces appliance efficiency standards under federal regulations. Northern Virginia's Data Center Alley hosts the world's densest concentration of cloud computing facilities, mandating thermal management upgrades.
China
Rapid data center construction in Hebei Province and smart city thermal networks in Shenzhen drive AI-controlled cooling deployment. MIIT directives and GB standards shape domestic certification requirements for connected HVAC equipment. Beijing-Tianjin-Hebei corridor operators specify liquid-cooled rack architectures for government-backed AI infrastructure projects.
Germany
Commercial building retrofits in Frankfurt and Munich accelerate demand-response-enabled cooling systems. The EU F-Gas Regulation mandates hydrofluorocarbon phasedown, pushing industrial buyers toward ammonia and transcritical CO2 systems. The Ruhr region's chemical facilities pilot natural refrigerant central plants at scale.
Singapore
Municipal district cooling projects in Jurong and Marina Bay integrate AI-optimized central plants with building-level thermal networks. The country's national environmental agency enforces strict energy performance standards for commercial developments. The tropical city-state's data center moratorium exemption process favors liquid-cooled efficiency certifications.
United Arab Emirates
Masdar City and Dubai South free zones anchor smart city thermal infrastructure deployments. MOHAP and local energy regulators mandate building efficiency codes for new commercial construction. Dubai's Mohammed bin Rashid Al Maktoum Solar Park powers district cooling networks serving Expo City redevelopment zones.
Smart Cooling Systems Market Vendor Landscape
Top-tier vendors anchor hyperscale data center contracts, while mid-tier specialists occupy commercial building automation niches. The vendor base stratifies across three tiers: integrated multinational conglomerates with chiller-to-software portfolios, regional equipment manufacturers with inverter technology specialization, and software-native control platform providers. Two dominant competitive moves reshape positioning: strategic partnerships between hardware OEMs and AI software vendors, and backward integration into refrigerant chemistry to secure supply chain control.
Within the integrated systems tier, Carrier Global Corporation, Schneider Electric SE, and Daikin Industries Ltd. exemplify contrasting strategic archetypes. Carrier anchors large-scale infrastructure through chiller technology leadership. Schneider Electric occupies the edge facility segment with rack-integrated thermal management positioning. Daikin represents precision unit specialization for high-density server room requirements. Each sits within distinct competitive vectors rather than direct overlap, creating tiered market segmentation rather than commodity price competition.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| LG Electronics Ltd. |
| Samsung Electronics Co. Ltd. |
| Daikin Industries Ltd. |
| Johnson Controls International plc |
| Schneider Electric SE |
| Carrier Global Corporation |
| Honeywell International Inc. |
| Trane Technologies plc |
| Others |
Supply Flow & Price Mechanics
Refrigerant chemistry transitions toward hydrofluoroolefins and natural alternatives simultaneously compress production economics and concentrate chemical supply among Chinese conglomerates. Data center operators and commercial building managers now face procurement trade-offs between compliance-driven specification premiums and extended lead times for qualified equipment.
Pricing Analysis
Short lead-time premiums for EPA Section 608-certified and EU F-Gas-compliant equipment run 15-25% above standard delivery schedules as installation capacity bottlenecks during peak replacement seasons. Project-based contract pricing dominates large infrastructure deployments, with price differentiation anchored in certification tier and geographic delivery cost. Pricing pressure intensifies in the residential thermostat segment as utility demand-response program standardization commoditizes hardware margins. Data center operators exhibit lowest price sensitivity given thermal uptime requirements, while commercial facility managers in Australia and South Korea prioritize cooling-as-a-service outcomes over capital expenditure.
Supply Chain Analysis
Dual-sourcing mandates from hyperscale operators in Nevada and Hebei Province require equipment assemblers to qualify compressor and heat exchanger suppliers across multiple jurisdictions. Manufacturing concentrates in China, Germany, and the United States for precision cooling infrastructure, with copper and aluminum feedstock drawing from Chilean and Indonesian mining operations. Supply chain risk centers on refrigerant import dependency as hydrofluoroolefin production clusters with Chinese chemical conglomerates. Distribution runs through direct manufacturer contracting for data center projects and wholesale distributor networks for fragmented commercial retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
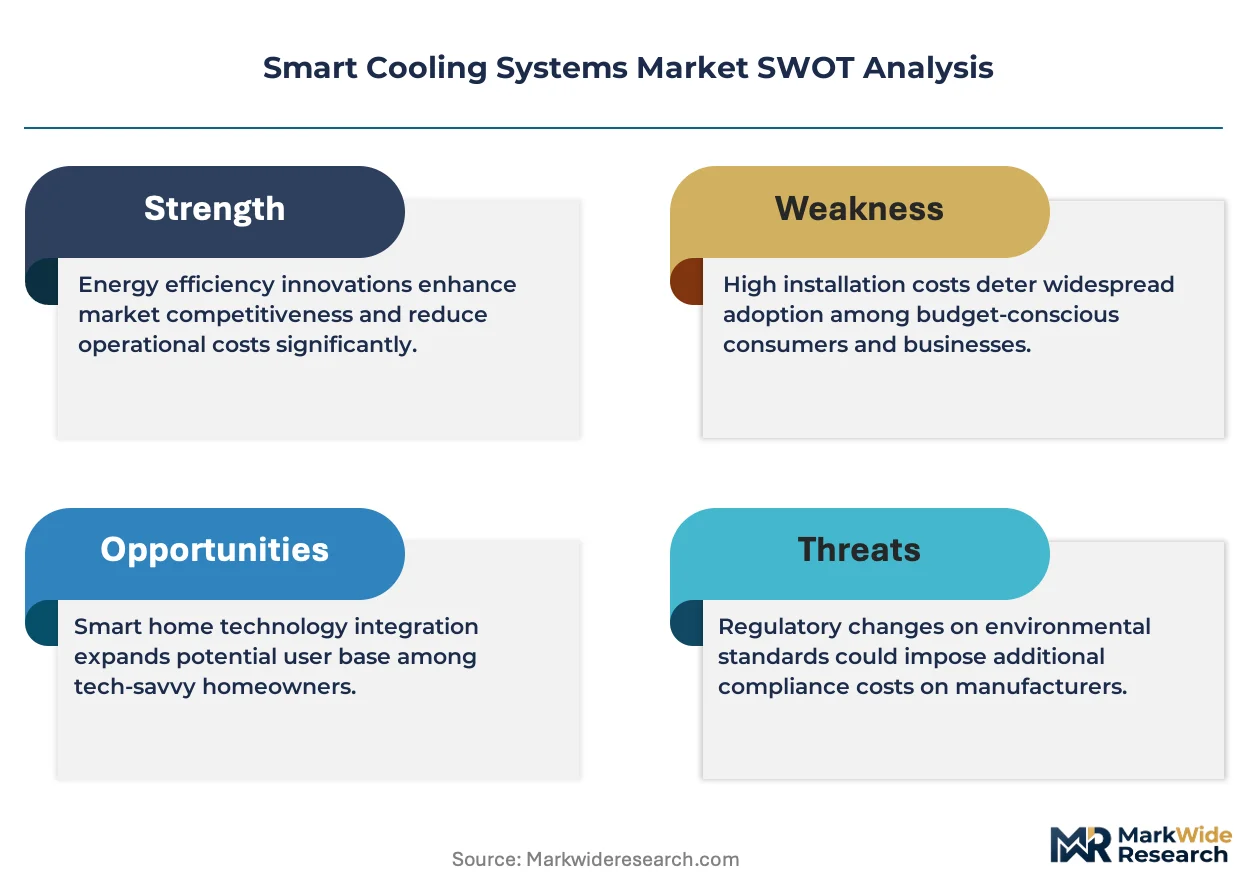
Smart cooling systems represent a consolidation play as refrigerant regulation compliance costs and AI control software development investments force sub-scale equipment manufacturers toward exit or acquisition. The EU F-Gas phasedown and US Department of Energy efficiency standards are accelerating this structural pressure.
For Market Incumbents: Acquire AI control software capabilities to unify hardware portfolios with predictive thermal management platforms. Carrier Global Corporation and Schneider Electric SE demonstrate this consolidation logic through integrated chiller-to-software offerings. Defensive positioning requires backward integration into refrigerant chemistry to secure supply chain control against Chinese import dependency risks. Capacity addition in Singapore and the United Arab Emirates district cooling markets captures municipal infrastructure growth. For New Entrants and Emerging Players: Begin with edge facility liquid cooling modules in Germany and Japan where distributed AI inference nodes lack purpose-built compact thermal management. White space concentrates in rack-integrated direct-to-chip systems for 50-100kW density thresholds that air-cooled incumbents cannot address. Go-to-market traction requires utility demand-response certification in California and Texas virtual power plant programs. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated multinational conglomerates seeking AI software overlay capabilities. Long-term viability favors vendors with captive refrigerant supply or exclusive hyperscale data center relationships. Acquisition target archetype: mid-tier control platform providers with FERC grid-interactive asset certification. The signal to watch is EPA Section 608 technician qualification expansion timelines that constrain installation capacity and favor scaled service organizations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refrigerant Chemistry | Captive hydrofluoroolefin supply secures margin control against Chinese import concentration. |
| AI Control Platform Acquisition | Machine learning thermal optimization compresses response latency for hyperscale data center contracts. |
| Utility Demand-Response Certification | FERC and state regulator approval enables virtual power plant revenue streams in Texas and California. |
| Edge Facility Liquid Cooling Module Launch | Rack-integrated direct-to-chip systems address 50-100kW density gaps in Germany and Japan. |
| Performance-Based Service Contract Expansion | Cooling-as-a-service agreements shift capex burden and bind duration to measured efficiency outcomes. |
Methodological Framework
SEC filings, EIA appliance efficiency databases, and EU F-Gas Regulation implementation reports formed the secondary backbone for market sizing and regulatory trajectory analysis. Primary interviews with data center infrastructure directors, HVAC contractor operations managers, utility demand-response program administrators, and refrigerant supply procurement leads validated equipment deployment patterns and pricing dynamics. Bottom-up triangulation across product type, technology stack, and end-use segmentation was cross-checked against top-down macroeconomic indicators and construction spending data.
Historical trendline analysis of data center power density evolution and commercial building energy retrofit cycles established baseline growth patterns across the projection horizon. The analytical framework modeled four segmentation dimensions: product architecture, technology differentiation, end-use concentration, and channel strategy. CAGRs were derived from regression analysis of installation volume against regulatory compliance deadlines and hyperscale construction pipelines. Industry-specific forecast inputs included AI training cluster thermal load projections and refrigerant phasedown supply constraints.
Underlying measurement precision varies by segment; data center cooling infrastructure carries tighter precision than residential thermostat shipments due to disclosed hyperscale contract values. Forecasts reflect documented assumptions regarding EPA and EU regulatory implementation timelines. Deviation in refrigerant chemistry transition speed or data center construction permit approval rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Peltier Chillers Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
Smart Water Cooler Market
Energy Management Systems
Bed Cooling System Market
Energy Management Systems
Global Vibration Control System Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
IoT Smart Gas Meter Market
Energy Management Systems
Smart Climate Control Market
Energy Management Systems
Energy Management in Data Centers Market
Energy Management Systems
Building Energy Management Systems (BEMS) Market
Energy Management Systems
Southeast Asia Cooling Systems Market
Energy Management Systems
AI Water Heater Market
Energy Management Systems
Airflow Management Market
Energy Management Systems
Data Center Power Management Market
Energy Management Systems
Chemical Control Systems Market
Energy Management Systems
AI-Driven Lighting Controls Market