
 Energy Management in Data Centers Market | 2026-2036
Energy Management in Data Centers Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Management in Data Centers Market Foresight
Buyer concentration among cloud service providers is expanding as hyperscalers consolidate procurement decisions across multi-gigawatt portfolios. Schneider Electric leverages its integrated power and cooling architecture to anchor large-scale deployments. Siemens competes through digital twin platforms that optimize thermal performance across heterogeneous server loads. Eaton specializes in intelligent power distribution units that extend visibility to the rack level.
Energy management in data centers encompasses the integrated hardware, software, and control systems that monitor, optimize, and automate electrical power and thermal infrastructure within mission-critical computing facilities, typically operating across voltage ranges from 480V distribution down to 12V server rails with power usage effectiveness targets below 1.2. Its primary commercial purpose is to minimize energy cost per compute unit while maintaining uptime adherence to Tier III and Tier IV reliability standards. Cooling systems applications dominate current spending as liquid cooling displaces air-based architectures under rising chip thermal design power. AI Analytics technology represents the fastest-expanding segment as machine learning models predict failure modes and autonomously shift workloads to off-peak rate periods.
The US EPA Energy Star program and the EU Energy Efficiency Directive establish mandatory disclosure and performance benchmarking that shapes product specifications and procurement criteria across jurisdictions. California's Title 24 building standards and Germany's KBA-adjacent efficiency frameworks for industrial facilities further fragment compliance requirements for multinational operators. Stakeholders must monitor how evolving grid interconnection tariffs and carbon intensity disclosure mandates reshape total cost of ownership calculations for new facility siting.
Market Dynamics
AI-driven power density requirements are compressing infrastructure refresh cycles and forcing hyperscalers to renegotiate utility interconnection agreements before planned capacity comes online.
Growth Catalysts
- Liquid Cooling Adoption:Thermal design power thresholds above 700W per processor are rendering air-based architectures economically unviable for AI training clusters.
- EU Energy Efficiency Directive:Mandatory disclosure regimes and performance benchmarking are accelerating replacement of legacy power distribution units in European facilities.
- Virginia-Texas Corridor Concentration:Cloud service providers are consolidating multi-gigawatt procurement decisions within renewable-rich grid zones to secure carbon-neutral compute capacity.
Market Restraints
- Copper and Rare Earth Input Costs:Power distribution equipment faces margin compression from volatile commodity pricing for busbar materials and permanent magnet components.
- Grid Interconnection Queues:Utility approval timelines extending 36-48 months in high-demand zones are delaying facility commissioning regardless of equipment readiness.
- Skilled Technician Scarcity:Specialized expertise in medium-voltage switchgear and direct liquid cooling manifold installation is concentrating among a limited contractor base.
Strategic Opportunities
- India Data Center Buildout:The country's central electricity regulator and state-level incentives are attracting hyperscaler investment in Mumbai and Chennai corridor projects.
- AI-Predictive Maintenance Convergence:Machine learning models trained on electrical signature analysis are converging with digital twin platforms to autonomously shift workloads off-peak.
- Carbon Border Adjustment Mechanism:The EU's emerging carbon intensity disclosure mandates are creating first-mover advantage for equipment vendors with embedded lifecycle certification.
Industry Challenges
- Tier III-IV Certification Timelines:Uptime Institute reliability audits for concurrent maintainability are extending 14-18 months for facilities deploying novel liquid cooling architectures.
- Legacy DCIM Integration:Proprietary protocols in existing data center infrastructure management platforms are forcing costly middleware development for unified control planes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Management in Data Centers Market |
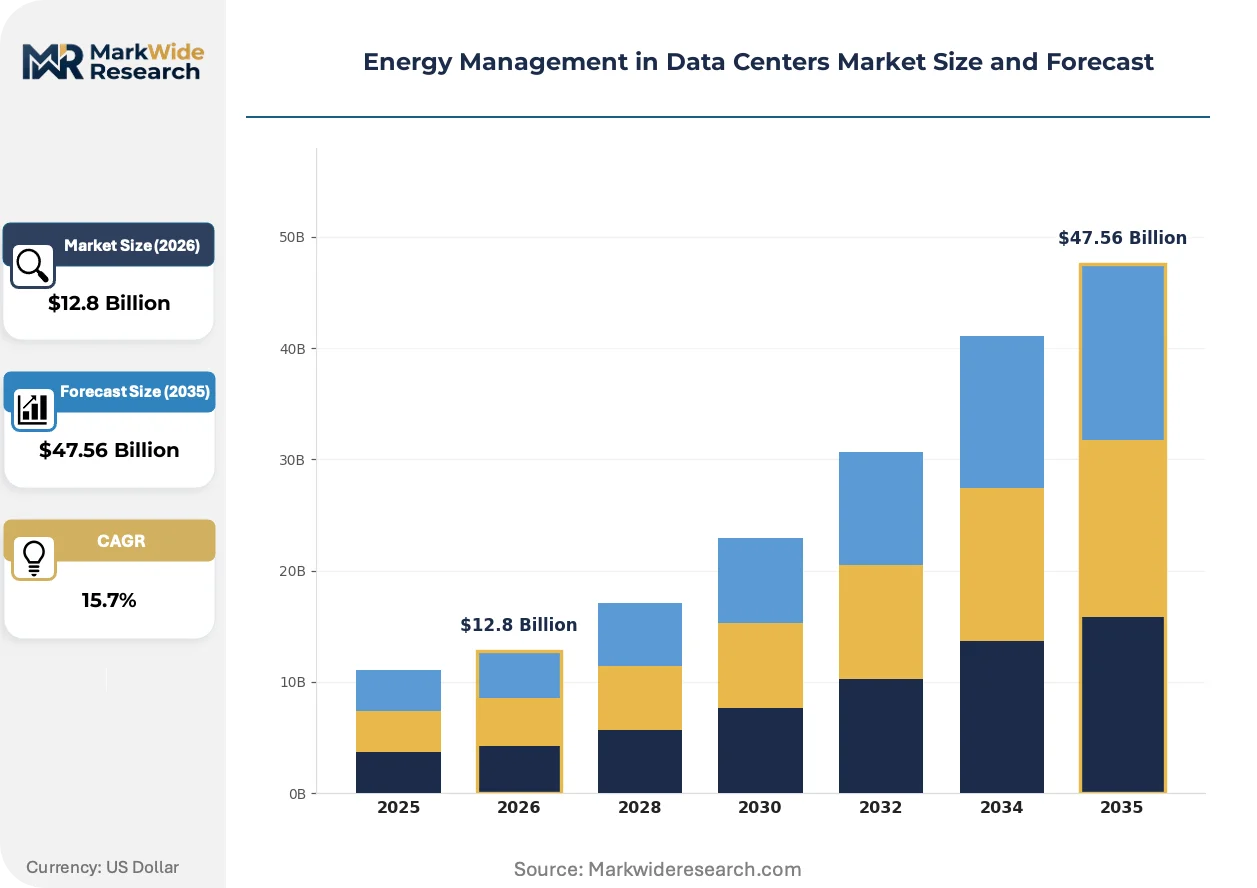
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $47.56 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Monitoring Tools, Optimization Software, Control Systems, Energy Storage Application Area: Cooling Systems, Power Distribution, Renewable Integration, Load Balancing End User: Enterprises, Colocation Providers, Cloud Service Providers, Government Facilities Technology: IoT Sensors, AI Analytics, Advanced Metering, Cloud Management |
| Companies Covered | ABB, Delta Electronics, Schneider Electric, Legrand, Huawei, Vertiv, Siemens, Rittal, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Management in Data Centers Market Shifts & Advancements
Electrification of thermal infrastructure and autonomous control systems are compressing the boundary between power and cooling disciplines, forcing vendor consolidation around integrated platform strategies.
Direct-to-chip liquid cooling is expanding into hyperscale AI training facilities as thermal design power thresholds render air-cooled architectures economically unviable for dense GPU deployments. Microsoft, Amazon Web Services, and Google are procuring manifold-and-cold-plate systems at scale for 2026-2027 facility commissioning. This technology is expanding into secondary markets as colocation providers retrofit existing white space to retain AI workload customers facing rack-level power constraints.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants with global warming potential above 150, forcing facility operators to specify natural refrigerant chillers or abandon mechanical cooling entirely. Industrial consequence includes accelerated deployment of water-side economization and geothermal exchange systems in Northern European facilities. German operators under KBA-adjacent industrial efficiency frameworks are most affected, with several Frankfurt-region facilities completing ammonia-based chiller conversions ahead of 2027 compliance deadlines.
Consolidated procurement among cloud service providers is compressing vendor margins and forcing equipment suppliers to unbundle hardware from software licensing. Traditional channel relationships through regional distributors are being displaced by direct enterprise sales teams co-located with hyperscaler engineering functions. This concentration is most visible in Northern Virginia's Loudoun County, where Amazon Web Services, Microsoft, and Google account for the majority of power distribution and cooling equipment orders placed through 2025-2026.
Energy Management in Data Centers Market Segmentation
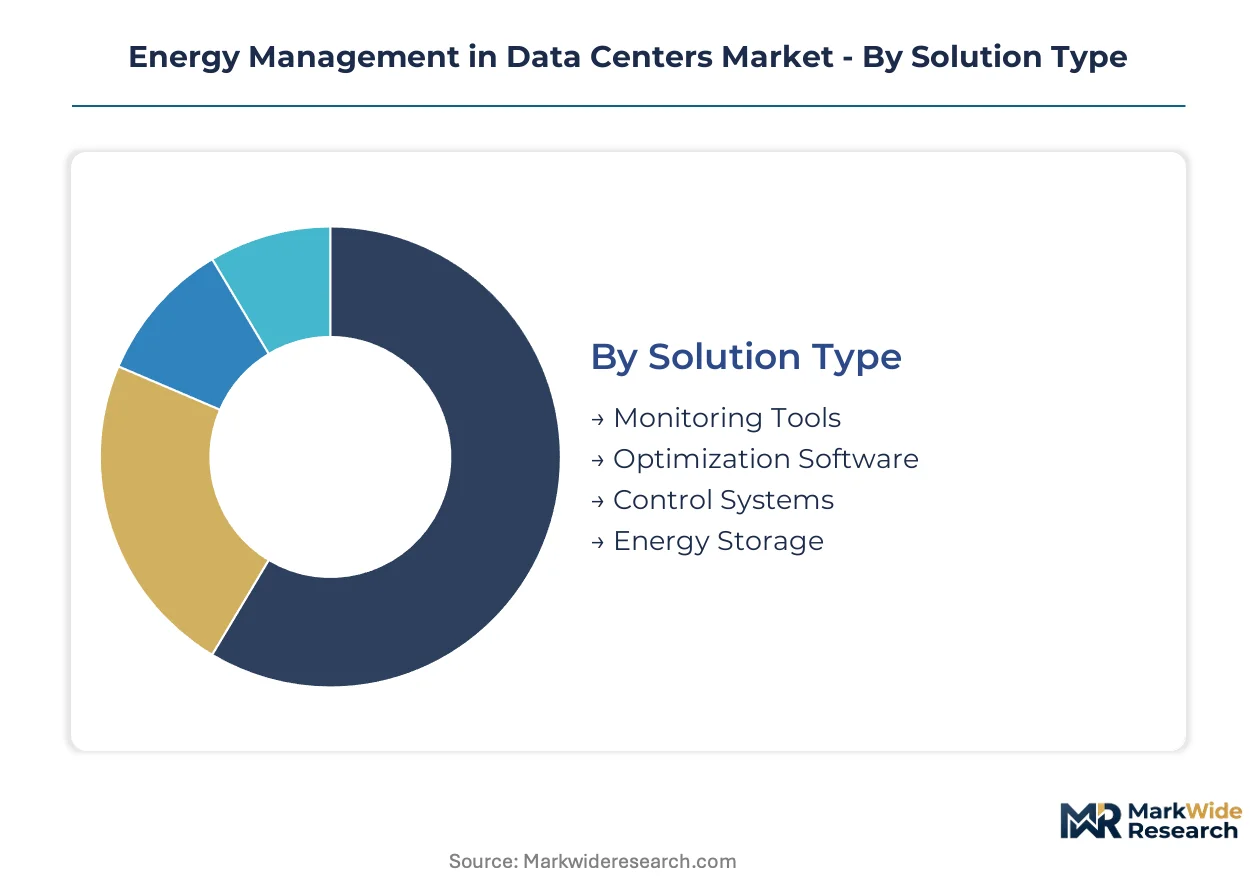
Segmentation in data center energy management reflects how procurement decisions cluster around workload density, compliance jurisdiction, and infrastructure refresh cycles. Buyers prioritize integrated platforms that collapse visibility across power and thermal domains rather than point solutions requiring middleware integration.
Solution Type:
Technology architecture determines integration depth and procurement economics across facility scales.
- Monitoring Tools:Real-time dashboards tracking power usage effectiveness, thermal gradients, and environmental conditions at rack and room levels. Demand concentrates in Virginia's Northern Virginia corridor where hyperscalers mandate sub-1.2 PUE verification for carbon-neutral compute claims.
- Optimization Software:Machine learning platforms predicting failure modes and autonomously shifting workloads to off-peak rate periods. Cloud service providers in Texas renewable-rich grid zones are deploying these systems to maximize carbon-free energy matching.
- Control Systems:Programmable logic controllers and building management interfaces governing chiller staging and uninterruptible power supply switching.
- Energy Storage:Lithium-ion and emerging solid-state battery systems providing ride-through capacity and peak shaving capabilities.
Mature deployment sits with Control Systems. Newer deployment is concentrated in Optimization Software.
Application Area:
Functional priority follows thermal design power trajectories and grid interconnection constraints.
- Cooling Systems:Direct-to-chip liquid cooling, rear-door heat exchangers, and precision air handlers managing processor thermal envelopes. AI training clusters above 700W per processor in Frankfurt-region facilities are rendering air-cooled architectures economically unviable under Germany's KBA-adjacent efficiency frameworks.
- Power Distribution:Medium-voltage switchgear, intelligent power distribution units, and busway systems stepping voltage from 480V facility feeds to 12V server rails. Northern Virginia's Loudoun County commands disproportionate capital deployment as Amazon Web Services, Microsoft, and Google consolidate multi-gigawatt procurement decisions.
- Renewable Integration:On-site solar, fuel cells, and grid-interactive battery systems enabling carbon-free energy matching.
- Load Balancing:Automated workload shifting and demand response participation optimizing energy cost per compute unit.
Mature deployment sits with Power Distribution. Newer deployment is concentrated in Cooling Systems.
End User:
Procurement concentration and technical specification authority vary sharply across customer archetypes.
- Cloud Service Providers:Hyperscalers operating multi-gigawatt portfolios with dedicated engineering teams co-located with vendor sales functions. These buyers unbundle hardware from software licensing and mandate API-first architectures for unified control planes.
- Colocation Providers:Multi-tenant facility operators retrofitting existing white space to retain AI workload customers facing rack-level power constraints. Secondary markets are expanding liquid cooling deployment to compete for GPU-intensive tenants.
- Enterprises:Corporate and institutional operators maintaining captive facilities for latency-sensitive or compliance-bound workloads.
- Government Facilities:Sovereign computing installations subject to national security procurement protocols and domestic content requirements.
Mature deployment sits with Enterprises. Newer deployment is concentrated in Cloud Service Providers.
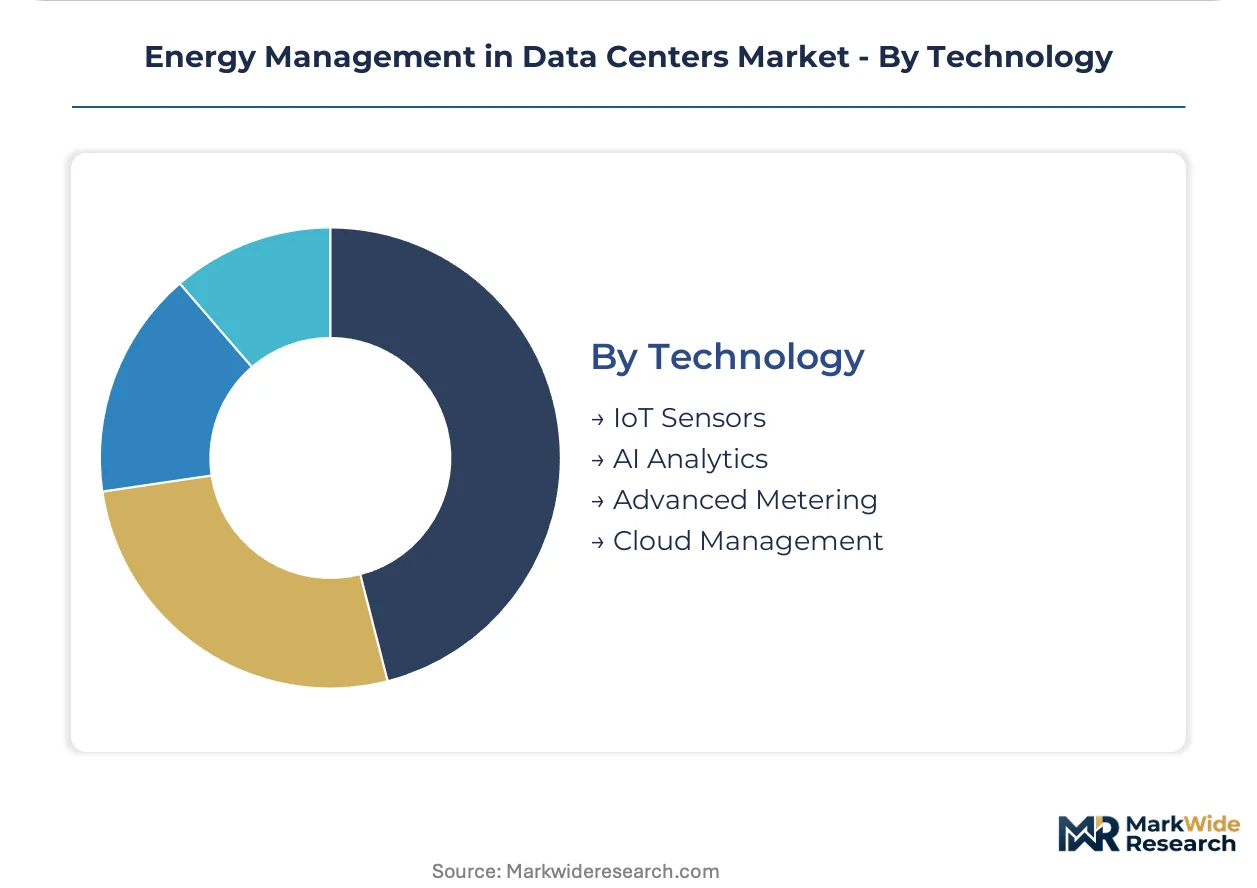
Technology:
Data architecture and inference capabilities define competitive differentiation in platform selection.
- AI Analytics:Machine learning models trained on electrical signature analysis converging with digital twin platforms. This segment is gaining share fastest as predictive maintenance capabilities compress mean time to repair and extend infrastructure refresh cycles.
- IoT Sensors:Distributed temperature, humidity, pressure, and current transducers feeding edge-computed telemetry streams. European facilities under the EU Energy Efficiency Directive's mandatory disclosure regimes are accelerating sensor density for performance benchmarking compliance.
- Advanced Metering:Sub-circuit revenue-grade meters enabling chargeback allocation and demand response verification.
- Cloud Management:SaaS-delivered control planes aggregating visibility across geographically distributed facility portfolios.
Mature deployment sits with Advanced Metering. Newer deployment is concentrated in AI Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper concentrate supply from Chilean smelters and rare earth processing capacity in China's Inner Mongolia anchor the upstream material flows feeding data center power distribution equipment manufacturing worldwide.
United States
Virginia's Northern Virginia corridor commands disproportionate capital deployment as Amazon Web Services, Microsoft, and Google consolidate multi-gigawatt procurement decisions. The EPA Energy Star program mandates disclosure thresholds that shape equipment specifications for facilities seeking carbon-neutral compute certification. Texas renewable-rich grid zones attract hyperscaler investment for 2026-2027 commissioning timelines.
Germany
Frankfurt-region facilities face accelerated ammonia-based chiller conversions ahead of 2027 deadlines under the EU F-Gas Regulation phase-down. KBA-adjacent industrial efficiency frameworks impose stringent performance benchmarking on power distribution equipment deployed in AI training clusters. Northern European operators are abandoning mechanical cooling entirely for water-side economization systems.
China
Beijing-Tianjin-Hebei corridor operators navigate MIIT efficiency standards while expanding liquid cooling deployment for domestic hyperscaler AI facilities. Dual carbon goals compress infrastructure refresh cycles for state-owned cloud providers building sovereign computing capacity. Yangtze River Delta manufacturers supply manifold-and-cold-plate systems for regional GPU-intensive deployments.
India
Mumbai and Chennai corridor projects attract hyperscaler investment under central electricity regulator incentives and state-level data center policies. CEA grid interconnection guidelines shape utility agreement timelines for facilities targeting 2026 commissioning. Domestic colocation providers retrofit existing white space to retain AI workload customers facing rack-level power constraints.
United Kingdom
London and Southeast England facilities deploy optimization software to maximize carbon-free energy matching under CSRD disclosure requirements. Ofgem grid tariffs reshape total cost of ownership calculations for new facility siting decisions. Midlands-based operators integrate AI analytics platforms with digital twin architectures for predictive maintenance capabilities.
Energy Management in Data Centers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-native control architectures and liquid cooling integration. The vendor base stratifies around three archetypes: integrated platform suppliers collapsing power and cooling visibility, digital twin specialists optimizing heterogeneous server loads, and rack-level hardware vendors extending telemetry density. Consolidated procurement among cloud service providers compresses margins and forces direct enterprise sales co-location with hyperscaler engineering functions. M&A activity concentrates on software-defined control plane capabilities and regional installation service networks.
Within the integrated platform tier, Schneider Electric and Siemens exemplify contrasting architectural approaches to unified infrastructure management. Schneider Electric leverages its power and cooling heritage to anchor large-scale deployments across multi-gigawatt portfolios. Siemens competes through digital twin platforms that optimize thermal performance across heterogeneous server loads. Eaton occupies a position within the rack-level visibility segment, specializing in intelligent power distribution units that extend telemetry to individual server rails.
| Leading Market Players |
|---|
| ABB |
| Delta Electronics |
| Schneider Electric |
| Legrand |
| Huawei |
| Vertiv |
| Siemens |
| Rittal |
| Eaton |
| Others |
Supply & Pricing Matrix
Captive integration into Chilean copper concentrate and Chinese rare earth processing anchors supply positioning for power distribution equipment manufacturers, compressing margin flexibility for vendors lacking upstream material control. Cloud service provider procurement concentration in Northern Virginia and Texas amplifies pricing power asymmetry toward hyperscale buyers unbundling hardware from software licensing.
Pricing Analysis
Warranty and lifecycle service bundling separates premium-tier integrated platform vendors from economy suppliers offering transactional hardware-only sales. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—Uptime Institute Tier IV concurrent maintainability commands substantial premiums over uncertified alternatives. Cost compression in standard-tier intelligent power distribution units is intensifying because hyperscalers mandate API-first architectures forcing proprietary middleware development. Cloud service providers exhibit lowest price sensitivity due to total cost of ownership calculations dominated by energy cost per compute unit, while colocation providers face acute margin pressure retrofitting existing facilities.
Supply Chain Analysis
Domestic-content requirements under India's CEA grid interconnection guidelines and China's MIIT efficiency standards are reshaping sourcing patterns for medium-voltage switchgear and liquid cooling manifold systems. Manufacturing concentrates in China, Germany, and the United States for precision power distribution equipment, while copper busbar and permanent magnet component supply draws from Chilean smelters and Chinese Inner Mongolia processing facilities. Single-source vulnerability in rare earth permanent magnet supply creates structural exposure to export restriction shocks. Distribution runs through direct enterprise sales teams co-located with hyperscaler engineering functions, displacing traditional regional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as direct-to-chip liquid cooling displaces air-based architectures rendered economically unviable by AI training cluster thermal design power thresholds above 700W per processor.
For Market Incumbents: Hedge against margin erosion from hyperscaler procurement consolidation by deepening backward integration into copper busbar and permanent magnet component supply. Acquire AI-native control software capabilities to defend platform positioning against digital twin specialists. Prioritize certification investment for Uptime Institute Tier IV concurrent maintainability to sustain premium pricing in Northern Virginia and Frankfurt-region deployments. For New Entrants and Emerging Players: Launch via direct sales partnerships with colocation providers retrofitting existing white space for AI workload tenants in secondary markets outside Northern Virginia and Texas. Target Mumbai and Chennai corridor projects where CEA grid interconnection guidelines create procurement windows for equipment vendors with embedded lifecycle certification. Pursue white-label liquid cooling manifold manufacturing for established power distribution vendors lacking thermal infrastructure expertise. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated platform suppliers seeking AI analytics and digital twin capabilities. Long-term viability favors vendors with unified power-cooling visibility architectures and regional installation service networks in renewable-rich grid zones. Monitor F-Gas Regulation compliance timelines as inflection indicator for natural refrigerant chiller and water-side economization system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Control Platform Development | Machine learning models trained on electrical signature analysis converge with digital twin architectures for predictive maintenance capabilities. |
| Liquid Cooling Integration Partnership | Direct-to-chip manifold-and-cold-plate systems address thermal design power thresholds rendering air-cooled architectures economically unviable. |
| Regional Installation Service Network Expansion | Skilled technician scarcity in medium-voltage switchgear and liquid cooling manifold installation concentrates among limited contractor bases. |
| Lifecycle Certification Embedded Design | EU carbon intensity disclosure mandates create first-mover advantage for equipment vendors with embedded environmental certification. |
| API-First Architecture Standardization | Hyperscaler procurement mandates for unified control planes force unbundling of hardware from proprietary software licensing. |
Research Methodology
Multi-period observation of hyperscaler capex disclosures, utility interconnection queue timelines, and thermal design power trajectories anchored the trend analysis, supplemented by interviews with data center engineering directors, utility planning officers, EPC contractors, and cooling system procurement leads. Secondary validation drew from EPA Energy Star program filings, EU Energy Efficiency Directive disclosure databases, FERC interconnection records, and Uptime Institute certification registries. Bottom-up facility-level buildout tracking and top-down equipment shipment analysis were triangulated to constrain estimate variance.
Input-output matrices modeled deployment across solution type, application area, end user archetype, and technology architecture dimensions over the projection horizon. CAGRs were derived from segmented adoption curves weighted by grid interconnection capacity additions and AI workload density trajectories. Forecast inputs incorporated copper and rare earth commodity price volatility bands alongside hyperscaler renewable energy matching commitments.
Grid interconnection approval delays, F-Gas Regulation compliance timeline acceleration, and AI chip thermal design power trajectory revisions are the dominant revision risks to facility commissioning assumptions. Forecasts reflect documented infrastructure investment announcements and regulatory filing commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Airflow Management Market
Energy Management Systems
Evaporative Air Cooler Market
Energy Management Systems
United Arab Emirates Portable Air Conditioning Market
Energy Management Systems
Grid Optimization Solution Market
Energy Management Systems
Europe Home Energy Management System Market
Energy Management Systems
Global Digital Utility Market
Energy Management Systems
Asia-Pacific Home Energy Management System Market
Energy Management Systems
Grid Operations Management Software Market
Energy Management Systems
Portable Air Cooler Market
Energy Management Systems
AI Water Heater Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
District Cooling Market
Energy Management Systems
IoT Energy Management Market
Energy Management Systems
Smart Water Cooler Market
Energy Management Systems
USA and Canada Portable Air Conditioner Market