
 Noise Mitigation System Market | 2026-2036
Noise Mitigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Noise Mitigation System Market Analysis
Multi-source procurement among tier-one contractors is pivoting as project owners seek risk distribution across acoustic engineering specialists. Eckel Industries leverages its anechoic chamber heritage to dominate high-precision testing facility contracts. Kinetics Noise Control anchors transportation infrastructure bids with vibration-isolation expertise. Armstrong World Industries sustains commercial building penetration through integrated ceiling-and-wall acoustic systems.
A noise mitigation system integrates sound-absorbing, blocking, or canceling technologies—typically mineral wool, mass-loaded vinyl, or active anti-noise circuitry operating across 20 Hz to 20 kHz—to reduce unwanted acoustic energy in built environments. Passive control technologies occupy the largest installed base due to lower capital requirements and minimal maintenance, while active noise cancellation is gaining share in aviation and automotive cabin applications where weight reduction matters. Acoustic panels lead product-type revenue pools because architects specify them for LEED-compliant commercial interiors, whereas retrofit solutions within installation-type segments carry above-average margins as building owners face mandatory decibel compliance deadlines.
OSHA's permissible exposure limit of 85 dBA over eight hours drives industrial hearing conservation program spending, while the EU Machinery Directive and CE marking require manufacturers to document noise emission values before market access. Japan's Ministry of Health sets stricter workplace thresholds than OSHA, pushing Japanese automotive and electronics factories toward hybrid active-passive systems. Stakeholders must monitor whether emerging building energy codes in North America and Europe integrate acoustic performance with thermal efficiency, potentially bundling insulation procurement and reshaping supplier qualification criteria.
Market Dynamics
Tighter occupational noise limits from OSHA, the EU Machinery Directive, and Japan's Ministry of Health are compelling factory retrofits and accelerating procurement of hybrid active-passive systems across manufacturing corridors.
Growth Catalysts
- EU Machinery Directive enforcement:CE marking requirements for documented noise emission values are pushing European manufacturers toward certified mitigation installations before market access.
- Mineral wool specification surge:Architects designing LEED-compliant commercial interiors in Germany and the United States are specifying acoustic panels as standard building envelope components.
- China's eastern manufacturing corridor:Provincial environmental bureaus enforcing stricter industrial noise ordinances are mandating retrofit timelines for existing facilities.
Market Restraints
- Mass-loaded vinyl cost volatility:Petrochemical input fluctuations compress margins for barrier membrane producers serving transportation infrastructure projects.
- Active noise circuitry technical limitations:Frequency response gaps above 1 kHz restrict aviation cabin applications where broadband attenuation remains critical.
- Specialized acoustic engineering talent scarcity:Concentration of qualified designers in Germany and Japan creates bidding bottlenecks for complex rail and industrial contracts.
Strategic Opportunities
- India's industrial noise ordinance gaps:State-level environmental authorities are beginning to replicate China's enforcement trajectory, opening retrofit demand in automotive and textile clusters.
- Active-passive hybrid convergence:Integration of microphone arrays with tuned mass dampers enables lighter-weight solutions for electric vehicle powertrain enclosures.
- Performance-based maintenance contracts:Rail operators in Japan are shifting from capital purchase to decibel-guaranteed service agreements with acoustic engineering specialists.
Industry Challenges
- ISO 3744 certification timelines:Third-party laboratory capacity constraints delay product validation for manufacturers targeting EU and Japanese markets simultaneously.
- Legacy HVAC integration friction:Acoustic retrofit projects in existing commercial buildings require coordination with mechanical systems that were not designed for simultaneous thermal and acoustic performance.
- Patent thickets in MEMS microphone arrays:Licensing complexity for active noise cancellation hardware slows product development cycles for automotive tier-one suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Noise Mitigation System Market |
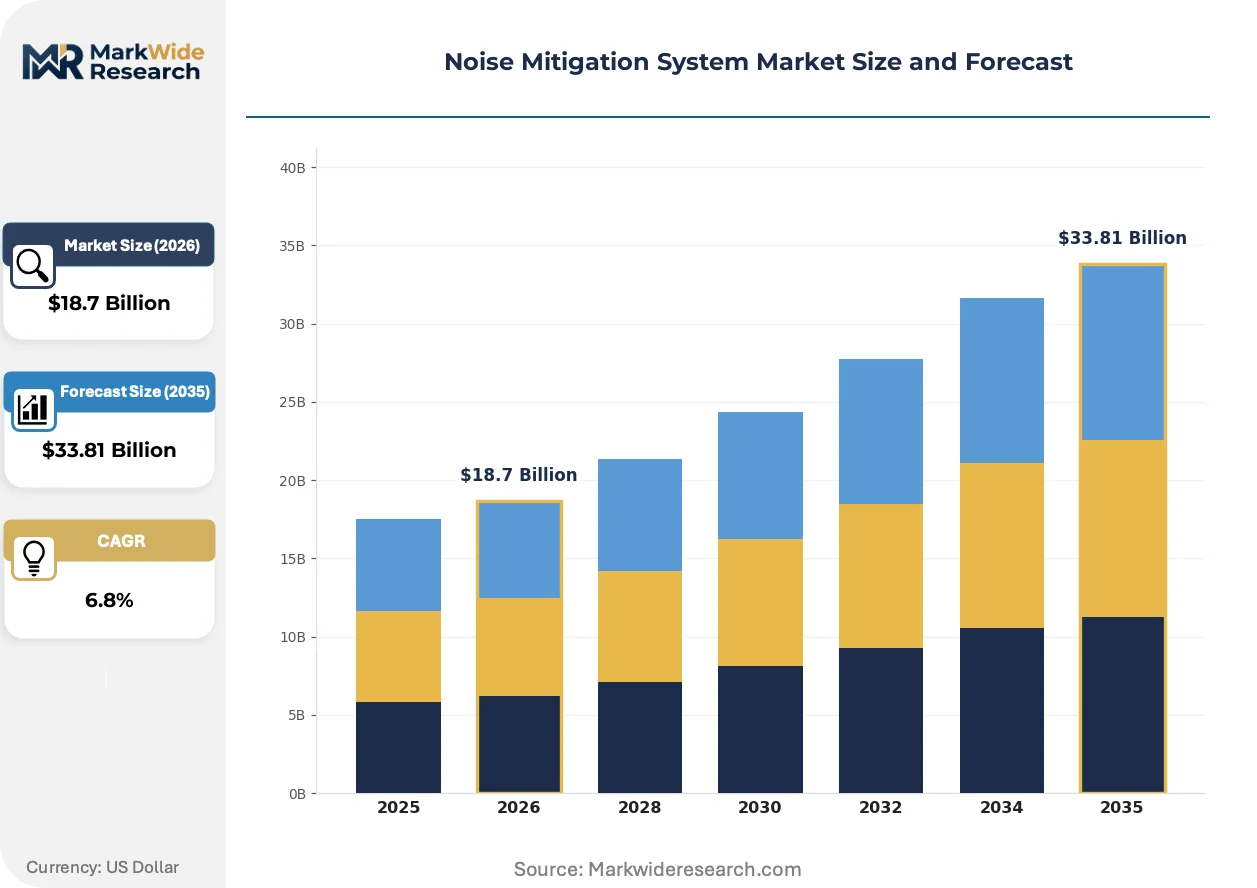
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Noise Cancellation, Sound Barriers, Acoustic Panels, Noise Absorbing Materials Installation Type: On-site Installation, Prefabricated Systems, Retrofit Solutions, Custom-built Designs Application: Residential Areas, Commercial Buildings, Transportation Systems, Industrial Facilities Technology: Passive Control, Active Control, Hybrid Systems, Soundproofing Techniques |
| Companies Covered | Eckel Industries, Inc., Armstrong World Industries Inc., Kinetics Noise Control, Inc., Fabreeka International, Acoustical Surfaces, Inc., Acoustiblok, Inc., Noise Barriers, LLC, FAIST Anlagenbau GmbH, IAC Acoustics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Noise Mitigation System Market Emerging Trajectories
Digital signal processing hardware miniaturization and material science advances are compressing the performance gap between passive mass barriers and active cancellation systems. Three developments are restructuring competitive positioning.
Metamaterial acoustic panels engineered with subwavelength resonator arrays are overtaking traditional mineral wool in precision testing facility contracts. Research laboratories and semiconductor cleanroom operators in Germany and Japan specify these structures for targeted absorption bands without the volume penalties of porous materials. The shift is compressing supplier qualification criteria toward physics-engineering capabilities rather than commodity manufacturing scale.
OSHA's pending update to permissible exposure limit enforcement protocols is tightening documentation requirements for industrial hearing conservation programs. American factory operators must now maintain continuous noise monitoring records rather than periodic sampling, driving demand for networked sensor installations. Food processing and metal fabrication facilities in the Midwest and Southeast are responding fastest due to higher baseline exposure profiles.
Urban rail authorities are consolidating vendor relationships around integrated platform-screen-door and trackside-barrier packages. Operators in Tokyo, Berlin, and New York are replacing discrete procurement of acoustic components with single-source responsibility for guaranteed decibel reduction at platform edges. This bundling is marginalizing pure-play material suppliers who lack vibration-isolation engineering capabilities.
Noise Mitigation System Market Segmentation
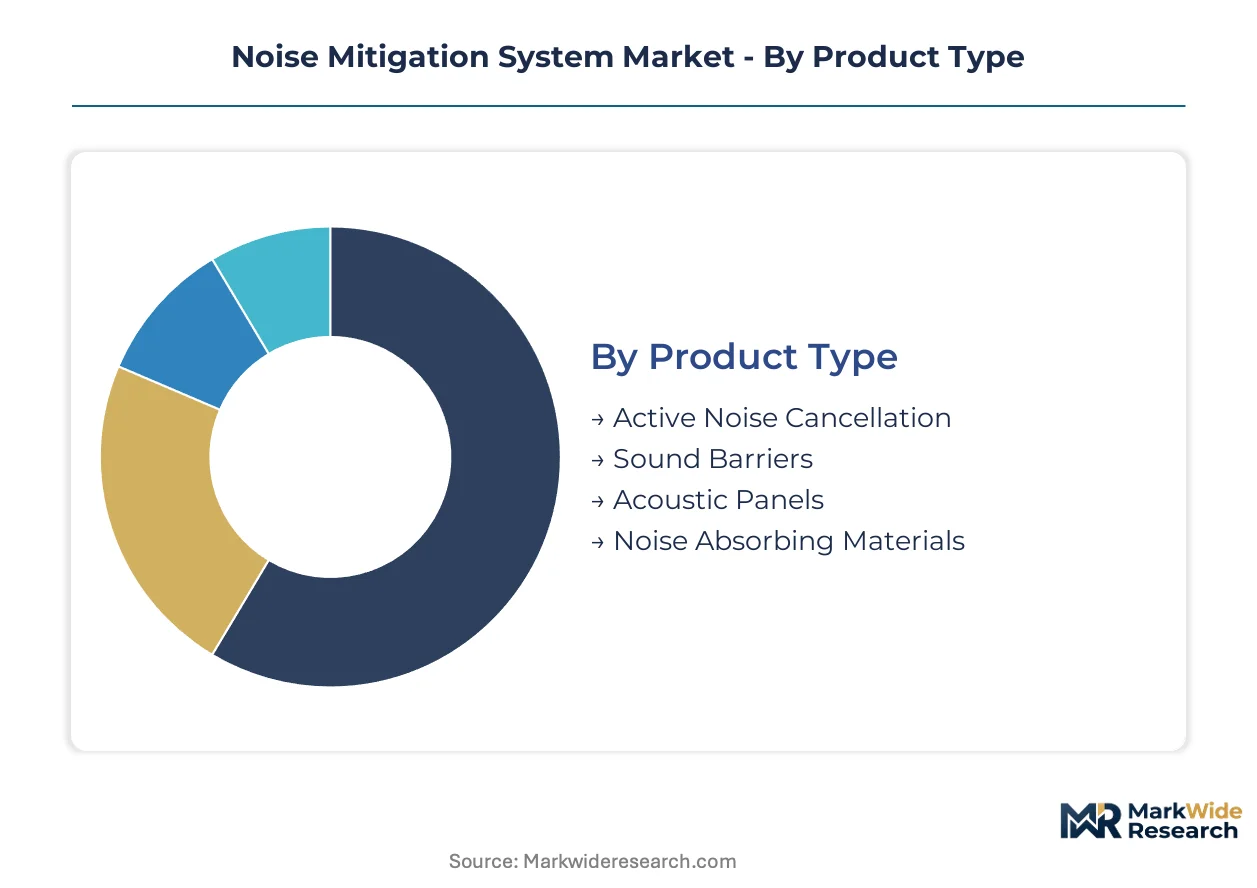
Noise mitigation procurement splits sharply between specification-driven new construction and compliance-driven retrofit, with certification requirements varying dramatically across product categories. Understanding these segment boundaries reveals where margin pools concentrate and which installation types face the steepest regulatory validation burdens.
Product Type:
CE marking under the EU Machinery Directive and OSHA 29 CFR compliance create divergent certification pathways: active systems require electromagnetic compatibility validation, while passive materials face ASTM E90 fire-acoustic dual testing.
- Acoustic Panels:Mineral wool and fiberglass composite boards engineered for 125-4000 Hz absorption coefficients dominate commercial interiors. Architects in Germany and the United States specify these for LEED-compliant office towers, with procurement concentrating in urban cores facing municipal noise ordinances.
- Active Noise Cancellation:Microphone-array-driven anti-phase circuitry operating 20-1000 Hz reduces mass penalties in aviation cabins. Japanese automotive suppliers integrate these into electric vehicle powertrain enclosures where weight reduction overrides capital cost premiums.
- Sound Barriers:Mass-loaded vinyl and concrete composite walls deployed along German and U.S. rail corridors.
- Noise Absorbing Materials:Porous foam and mineral wool batts specified for industrial machinery enclosures in China's eastern manufacturing belt.
Leading the category by volume: Acoustic Panels. Growing fastest: Active Noise Cancellation.
Installation Type:
Cost tier stratification separates capital-intensive custom engineering from commoditized on-site deployment, with retrofit solutions commanding 40-60% labor premiums due to structural adaptation requirements.
- Retrofit Solutions:Post-construction acoustic upgrades requiring structural assessment and HVAC coordination. Building owners in Japan and Germany facing mandatory decibel compliance deadlines drive demand, with above-average margins reflecting engineering complexity.
- Prefabricated Systems:Factory-assembled barrier modules with integrated vibration isolation. Urban rail operators in Tokyo, Berlin, and New York specify these for platform edge enclosures, compressing installation windows and reducing track possession time.
- On-site Installation:Field-assembled components deployed across commercial construction sites in the United States.
- Custom-built Designs:Bespoke anechoic chambers and precision testing facilities engineered for semiconductor cleanrooms in Germany and Japan.
Highest margin tier: Retrofit Solutions. Steepest volume expansion: Prefabricated Systems.
Application:
Customer type divergence separates owner-occupied industrial facilities with long payback horizons from speculative commercial developers prioritizing first-cost minimization.
- Transportation Systems:Trackside barriers, platform screen doors, and vehicle cabin treatments. Urban rail authorities in Germany, Japan, and the United States consolidate procurement around integrated packages with guaranteed decibel reduction, marginalizing pure-play material suppliers.
- Industrial Facilities:Factory-floor hearing conservation programs and machinery enclosures. OSHA's 85 dBA permissible exposure limit and Japan's stricter Ministry of Health thresholds compel continuous monitoring system deployment in metal fabrication and food processing.
- Commercial Buildings:Open-plan office acoustic treatments and HVAC noise control in LEED-targeting developments.
- Residential Areas:Highway noise barriers and construction-phase temporary mitigation in urban infill projects.
Deepest specification expertise required: Transportation Systems. Fastest regulatory pressure buildup: Industrial Facilities.
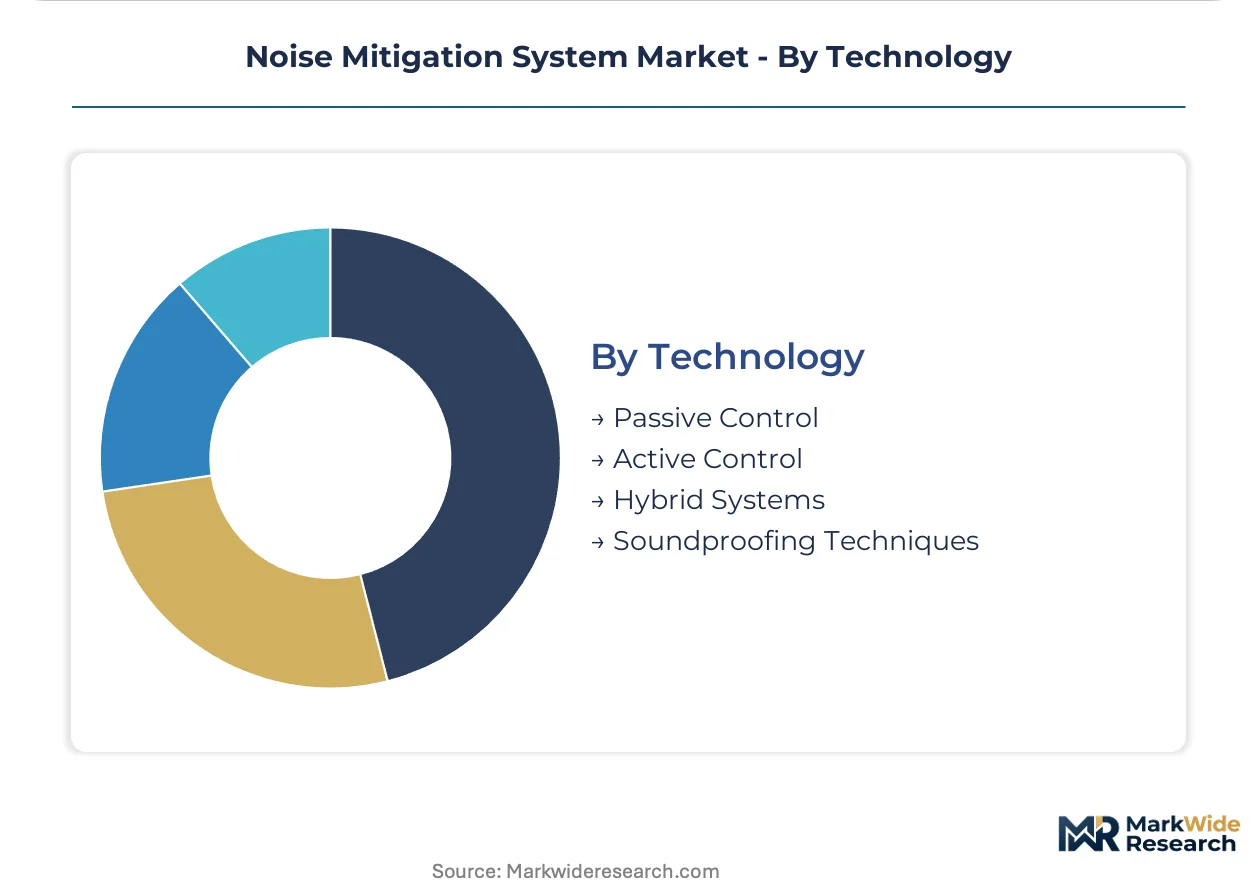
Technology:
Supply concentration clusters in Germany and Japan for hybrid system engineering, while passive control commoditization drives manufacturing scale toward China's eastern provinces.
- Hybrid Systems:Integrated microphone arrays with tuned mass dampers combining active cancellation below 500 Hz and passive absorption above. Electric vehicle manufacturers in Japan specify these for lightweight powertrain enclosures where broadband attenuation meets mass constraints.
- Passive Control:Mass-spring-damper assemblies and porous absorbers requiring no electrical infrastructure. Lowest capital requirements and minimal maintenance sustain dominant installed base across industrial and commercial applications.
- Active Control:Pure electronic cancellation limited by frequency response gaps above 1 kHz in aviation applications.
- Soundproofing Techniques:Multi-layer composite barriers and damping compounds deployed in architectural retrofits.
Widest deployment base: Passive Control. Steepest technology investment: Hybrid Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mineral wool deposits in Germany's Rhineland-Palatinate region anchor European supply chains for acoustic panel manufacturing, while petrochemical feedstocks along the US Gulf Coast sustain mass-loaded vinyl production for transportation barriers.
United States
Urban rail authorities in New York, Chicago, and Washington D.C. are consolidating platform-screen-door procurement into single-source contracts with guaranteed decibel reduction. OSHA's pending enforcement protocol updates for 85 dBA exposure limits are forcing Midwest food processing and metal fabrication facilities toward continuous noise monitoring retrofits. The Southeast manufacturing corridor spanning Georgia and the Carolinas is absorbing above-average engineering premiums for HVAC-integrated acoustic upgrades in legacy industrial buildings.
Germany
Metamaterial acoustic panel demand from semiconductor cleanroom operators in Dresden and Munich is displacing traditional mineral wool in precision testing facilities. CE marking requirements under the EU Machinery Directive are compelling machinery manufacturers in Baden-Württemberg to document noise emission values before market access. The Ruhr industrial belt's remaining steel and automotive plants are accelerating hybrid active-passive system deployment ahead of stricter federal workplace noise ordinances.
China
Provincial environmental bureaus in Jiangsu and Zhejiang provinces are enforcing mandatory retrofit timelines for textile and electronics factories along the eastern manufacturing corridor. The country's national environmental regulator is expanding industrial noise ordinance coverage to second-tier cities previously exempt from coastal enforcement standards. Shanghai and Suzhou-based rail operators are importing German vibration-isolation engineering expertise for metro expansion projects requiring platform edge noise containment.
Japan
Automotive suppliers in Toyota City and Yokohama are specifying hybrid microphone-array systems for electric vehicle powertrain enclosures where mass constraints override capital cost premiums. The Ministry of Health's stricter workplace thresholds than OSHA are pushing electronics factories toward continuous monitoring network installations. Tokyo Metro and Osaka Municipal Subway are pioneering performance-based maintenance contracts that shift acoustic barrier procurement from capital purchase to decibel-guaranteed service agreements.
India
State environmental authorities in Maharashtra and Tamil Nadu are beginning to replicate China's enforcement trajectory for industrial noise compliance in automotive and textile clusters. The Central Pollution Control Board's draft national noise standards are creating retrofit demand anticipation among Pune and Chennai factory operators. Delhi-NCR's metro expansion authority is evaluating platform screen door packages from Japanese and German engineering specialists for elevated corridor noise containment.
Noise Mitigation System Market Vendor Landscape
Strategic partnerships dominate the current landscape as acoustic engineering specialists align with transportation infrastructure contractors to bid integrated platform-barrier packages. The vendor base clusters around three distinct tiers: heritage anechoic chamber fabricators, vibration-isolation engineering houses, and integrated building systems suppliers. Two competitive moves are reshaping positioning: technology licensing agreements for MEMS microphone array patents, and backward integration into mineral wool manufacturing to secure panel supply chains.
Among heritage acoustic engineering specialists, Eckel Industries, Inc. and IAC Acoustics exemplify the anechoic chamber fabrication archetype with decades of precision testing facility heritage. Kinetics Noise Control, Inc. and Fabreeka International occupy positions within the vibration-isolation tier, anchoring transportation infrastructure bids with tuned mass damper expertise. Armstrong World Industries Inc. represents the integrated building systems archetype, sustaining commercial penetration through ceiling-and-wall acoustic system bundling that commoditized competitors cannot replicate.
| Leading Market Players |
|---|
| Eckel Industries, Inc. |
| Armstrong World Industries Inc. |
| Kinetics Noise Control, Inc. |
| Fabreeka International |
| Acoustical Surfaces, Inc. |
| Acoustiblok, Inc. |
| Noise Barriers, LLC |
| FAIST Anlagenbau GmbH |
| IAC Acoustics |
| Others |
Supply Flow & Price Mechanics
Polypropylene price indices on the US Gulf Coast cascade through mass-loaded vinyl membrane production, compressing margins for transportation barrier suppliers while elevating specification premiums for mineral wool acoustic panels sourced from Germany's Rhineland-Palatinate deposits.
Pricing Analysis
Warranty bundling separates capital-equipment tiers from pure-material supply, with decibel-guaranteed performance contracts in Japan's rail sector commanding substantial premiums over unbundled panel procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, where CE-marked and OSHA-compliant systems anchor the top tier. Pricing pressure stems from petrochemical input volatility in barrier membrane production, squeezing mid-tier producers serving infrastructure contractors. Commercial developers in speculative office construction exhibit highest price sensitivity, while owner-occupied industrial facilities with regulatory compliance deadlines accept premium positioning.
Supply Chain Analysis
Mineral wool feedstock rests on German and Belgian production clusters, while mass-loaded vinyl manufacturing draws from US Gulf Coast petrochemical complexes and Chinese eastern province chemical processors. Critical inputs span basalt and slag for mineral wool, polypropylene resins for barrier membranes, and MEMS microphone arrays for active cancellation hardware. Single-source vulnerability concentrates in German and Japanese acoustic engineering talent pools, creating bidding bottlenecks for complex rail contracts. Distribution runs through specification-influenced channels where architects and acoustic consultants direct procurement toward certified fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized acoustic engineering capacity constraints in Germany and Japan prop pricing power for hybrid system integrators, as qualified design talent scarcity outpaces training pipeline expansion.
For Market Incumbents: Anchor platform-screen-door and trackside-barrier integration capabilities to defend against transportation infrastructure contractors consolidating vendor relationships. Backward integration into mineral wool manufacturing secures panel supply chains against Rhineland-Palatinate deposit competition. Certification investment in ISO 3744 laboratory capacity accelerates product validation timelines for simultaneous EU and Japanese market entry. For New Entrants and Emerging Players: Direct-to-architect digital specification tools penetrate the commercial building segment where LEED compliance drives acoustic panel procurement but incumbent relationships remain shallow. India's state-level industrial noise ordinance enforcement gaps in Maharashtra and Tamil Nadu automotive clusters offer white-space retrofit demand. Target performance-based maintenance contract structures pioneered by Tokyo Metro to differentiate from capital-sale competition. For Investors and Strategic Acquirers: The window for entry favors vibration-isolation engineering houses with tuned mass damper heritage, as rail operator procurement consolidation privileges integrated solution providers over pure-play material suppliers. Long-term viability hinges on hybrid active-passive system capabilities where automotive electrification and aviation weight reduction converge. Watch for OSHA enforcement protocol finalization as inflection indicator for continuous monitoring network deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Wool | Captive supply of Rhineland-Palatinate basalt feedstock insulates margin from commodity volatility. |
| ISO 3744 Laboratory Certification | Third-party validation capacity unlocks simultaneous CE marking and OSHA compliance pathways. |
| Performance-Based Maintenance Contracts | Decibel-guaranteed service agreements shift Tokyo and Osaka rail procurement from capital to recurring revenue. |
| MEMS Microphone Array Licensing | Patent access from Japanese automotive suppliers accelerates active cancellation product development cycles. |
| Digital Specification Platform Launch | Architect-direct channels bypass incumbent distributor relationships in LEED-targeting commercial developments. |
Methodological Framework
Independent corroboration across acoustic engineering specialists, rail operator procurement directors, and industrial facility maintenance managers underwrites the qualitative findings. Primary fieldwork with mineral wool producers, mass-loaded vinyl compounders, and MEMS microphone array suppliers intersects with secondary validation from OSHA enforcement guidance documents, EU Machinery Directive compliance databases, and Japanese Ministry of Health workplace noise ordinance filings. Customs data on acoustic panel trade flows and SEC filings from integrated building systems suppliers enable bottom-up and top-down triangulation.
Rate-of-change decomposition across product type, installation method, application sector, and technology architecture structures the analytical framework. Segmentation dimensions span passive versus active versus hybrid control systems, retrofit versus new construction deployment, transportation infrastructure versus industrial versus commercial end-use, and regional regulatory cluster adoption patterns. CAGRs derive from installed base growth adjusted for replacement cycles and regulatory compliance deadline clustering. Forecast inputs incorporate mineral wool capacity expansion timelines and petrochemical price trajectory sensitivity.
The model holds under steady regulatory enforcement intensification; deviation in OSHA protocol implementation timing or EU Machinery Directive CE marking waiver provisions would shift retrofit demand timing. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
US Energy Management Systems Market
Energy Management Systems
Outage Management System (OMS) Market
Energy Management Systems
Smart Thermostat Market
Energy Management Systems
Asia-Pacific Home Energy Management System Market
Energy Management Systems
Meter Data Management System Market
Energy Management Systems
Building Energy Management Systems (BEMS) Market
Energy Management Systems
Smart Climate Control Market
Energy Management Systems
Global Data Center Energy Management Solution Market
Energy Management Systems
Smart Air Cleaners Market
Energy Management Systems
Energy Management Systems (EMS) Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
Africa Digital Showers Market
Energy Management Systems
Global Personal Cooling Device Market
Energy Management Systems
North America Home Energy Management System (HEMS) Market
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market