
 AI Water Heater Market | 2026-2036
AI Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
AI Water Heater Market Insights
The EU F-Gas Regulation is recalibrating refrigerant specifications for heat pump water heaters, compelling manufacturers to redesign thermal systems around lower-GWP working fluids. A.O.Smith leverages its North American manufacturing footprint to sustain distribution density across big-box retail channels. Rheem Manufacturing Company anchors its competitive stance through backward integration into heat exchanger production. Rinnai Corporation dominates the Japanese market with tankless gas-fired systems while navigating European decarbonization standards.
AI water heaters integrate machine learning algorithms, sensor arrays, and predictive maintenance protocols to optimize thermal output against usage patterns and energy pricing signals. These systems employ refrigerant-based heat pumps, electric resistance elements, or hybrid configurations with COP ratings that determine operational economics across climate zones. The heat pump product type captures the fastest expansion as electrification mandates displace fossil-fuel heating in commercial and residential installations. Smart controls and IoT-enabled technology segments concentrate margin pools through recurring software services and utility demand-response integration. The hospitality end user category shows concentrated procurement growth as hotel chains standardize on intelligent thermal systems for portfolio-wide energy management.
China's MIIT enforces GB standards for appliance efficiency and networked device security, shaping product certification requirements for domestic and export-bound manufacturers. The EPA in the United States regulates refrigerant transitions under SNAP program amendments, while the EU Ecodesign Directive sets minimum performance thresholds for water heating equipment placed on the European market. Stakeholders must monitor the divergence between regional refrigerant phase-down schedules and smart-grid interoperability standards when allocating R&D and certification budgets across production footprints.
Market Dynamics
The electrification of thermal systems is compressing product replacement cycles as building codes and utility incentives force fossil-fuel displacement across residential and commercial installations. This structural pressure is reshaping manufacturer R&D allocation toward heat pump architectures and IoT-native control systems.
Growth Catalysts
- EU F-Gas Regulation:The refrigerant phase-down mandate is accelerating heat pump water heater deployment across Germany, France, and Italy as installers stock compliant equipment ahead of supply constraints.
- Hospitality sector standardization:Southeast Asian hotel chains are consolidating thermal procurement under portfolio-wide energy management platforms, creating volume commitments for intelligent heat pump systems.
- Heat pump technology maturation:Compressor efficiency gains and variable-speed drives are extending operational range into colder climate zones, opening Nordic and Alpine markets previously served by gas-fired alternatives.
Market Restraints
- Copper and rare earth input volatility:Heat exchanger manufacturing and permanent magnet motors expose producers to commodity price swings that compress margin predictability on fixed-price contracts.
- Refrigerant supply concentration:Low-GWP working fluid production clusters among Chinese chemical manufacturers, creating single-source risk for European and North American heat pump assemblers.
- Grid interconnection standards fragmentation:Divergent smart-grid communication protocols between Germany, Japan, and the United States force redundant certification investments for multi-region product families.
Strategic Opportunities
- India building efficiency mandates:The Bureau of Energy Efficiency's updated commercial building codes create first-mover advantage for heat pump water heater suppliers establishing local assembly partnerships.
- Demand-response revenue stacking:Utility-controlled thermal storage enables AI water heaters to capture capacity payments and time-of-use arbitrage beyond energy savings alone.
- Hybrid system architecture:Combining heat pump efficiency with electric resistance backup addresses cold-climate performance anxiety while maintaining electrification compliance.
Industry Challenges
- Refrigerant handling certification:The transition to mildly flammable A2L working fluids requires technician retraining across installation networks, slowing field deployment velocity.
- Legacy control system integration:Building management system interoperability demands backward-compatible communication stacks that extend development timelines and testing overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Water Heater Market |
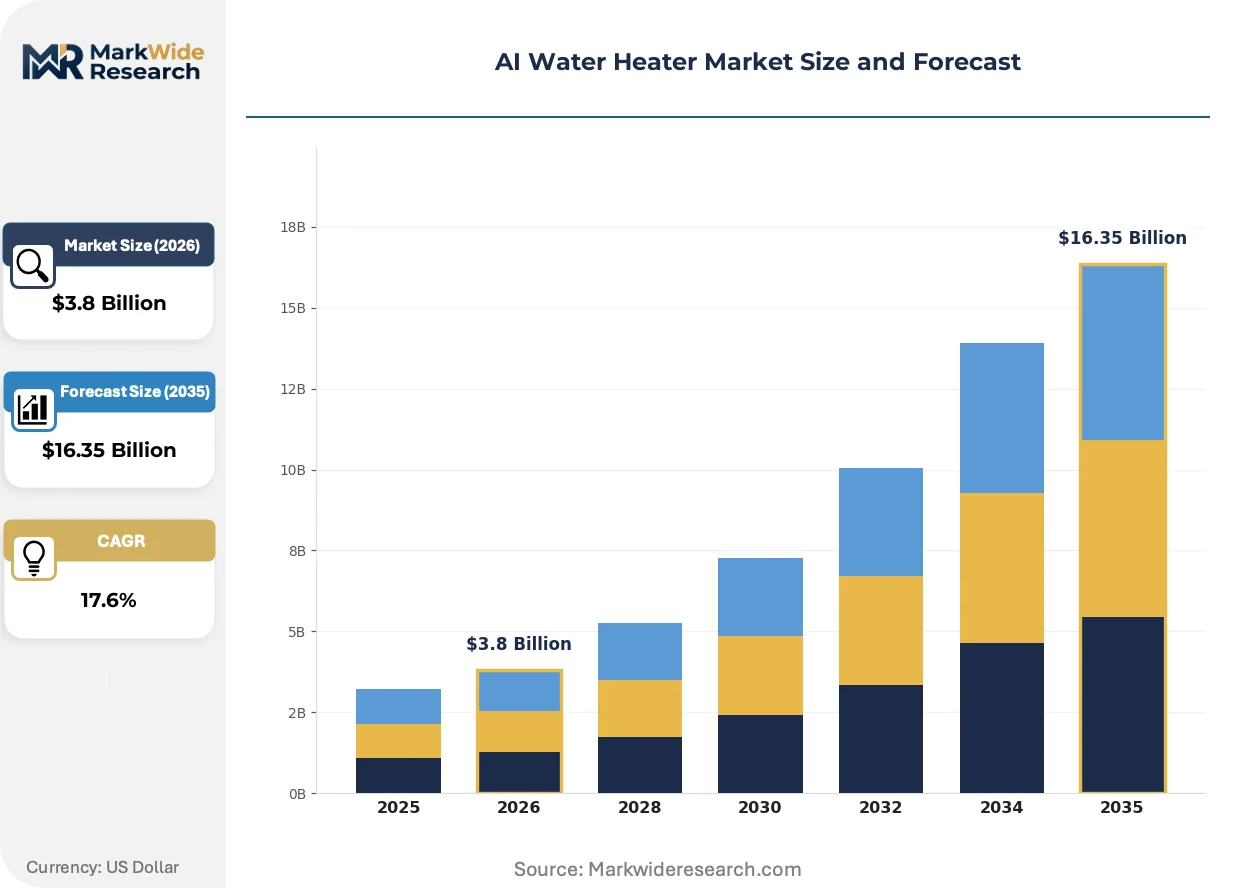
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant, Storage, Heat Pump, Solar End User: Residential, Commercial, Industrial, Hospitality Technology: Smart Controls, IoT Enabled, Machine Learning, Wireless Monitoring Distribution Channel: Retail, Online, Direct Sales, Distributors |
| Companies Covered | Viomi, A.O.Smith, Zhongshan Pake Electrical Technology, Aux, Colmo, Micoe, Guangdong Macro Gas Appliance, Rheem Manufacturing Company, Rinnai Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Water Heater Market Trends and Innovations
Predictive thermal management is shifting from reactive temperature control toward anticipatory load optimization, with machine learning models now processing occupancy sensors, weather feeds, and dynamic electricity pricing in real time.
Machine learning algorithms embedded in heat pump controllers are automating defrost cycles, setpoint adjustments, and compressor staging based on learned occupancy patterns. Hospitality operators in Singapore and Bangkok are deploying these systems across hundred-property portfolios within eighteen-month rollout windows. The technology is automating energy procurement decisions that previously required manual intervention by facility managers.
The EPA's SNAP program amendments are phasing down high-GWP refrigerants in stationary equipment, compelling manufacturers to redesign heat pump circuits around R-454B and R-1234yf alternatives. This transition is compressing product development timelines as engineering teams validate thermal performance and safety profiles under revised charge limits. The commercial segment bears the heaviest compliance burden, with certification delays most acute in California and Northeast corridor markets where state-level regulations run ahead of federal schedules.
Subscription-based thermal service models are displacing capital equipment sales in multi-family housing developments, with developers preferring performance guarantees over ownership risk. European property managers in Germany and the Netherlands are piloting heat-as-a-service contracts where vendors retain asset ownership and optimize operations remotely. This procurement transformation is most visible in social housing retrofit programs where public funding prioritizes operational expenditure structures over upfront capital allocations.
AI Water Heater Market Segmentation
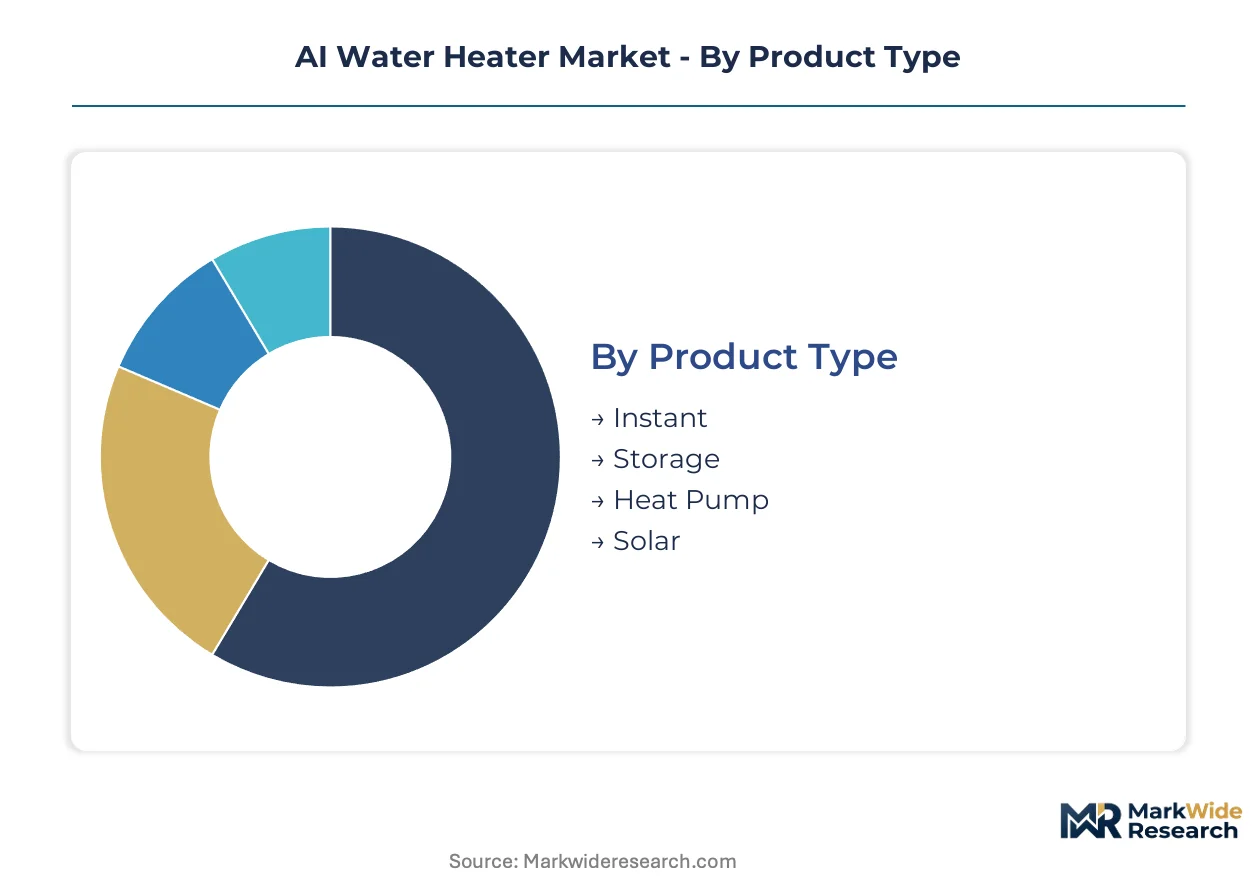
AI water heater segmentation reveals how certification requirements, distribution economics, and technology integration costs fragment procurement patterns across residential and commercial buyers. Understanding these divides clarifies where margin pools concentrate versus where volume commoditization pressures dominate.
Product Type:
Certification burdens vary sharply: heat pump systems face EPA SNAP refrigerant approvals and EU F-Gas compliance, while instant and storage units navigate simpler electrical safety standards. Solar thermal hybrids require additional renewable energy incentive eligibility verification in Germany and California.
- Heat Pump:Refrigerant-based thermal extraction achieves coefficient-of-performance ratings above 3.0 in moderate climates. Demand concentrates in Germany's commercial building retrofit sector where the federal building code mandates intelligent thermal management in new construction and major renovations. The EU F-Gas Regulation's phase-down schedule accelerates installer stocking of compliant equipment ahead of supply constraints.
- Instant:Tankless gas-fired and electric resistance systems deliver on-demand heating without storage losses. Procurement clusters in Japan's dense urban residential market where METI efficiency standards and space constraints favor compact wall-mounted units. Rinnai Corporation's domestic dominance reflects decades of installer network development around point-of-use thermal systems.
- Storage:Conventional tank-based systems with AI-optimized heating cycles and predictive maintenance protocols. Appeals to North American replacement markets where existing infrastructure and technician familiarity reduce installation friction.
- Solar:Photovoltaic-thermal hybrid configurations integrating AI-managed auxiliary heating for weather variability. Eligibility for Germany's BAFA subsidies and California's SGIP incentives shapes commercial adoption timelines.
Leading the category by volume: Storage. Growing fastest: Heat Pump.
End User:
Cost tiers separate these segments: industrial buyers negotiate long-term service contracts with performance guarantees, while residential purchasers face upfront capital constraints and financing dependency.
- Hospitality:Portfolio-wide energy management platforms standardize thermal procurement across hundred-property rollouts. Southeast Asian hotel chains in Singapore and Bangkok are deploying IoT-enabled heat pump systems within eighteen-month implementation windows, automating energy procurement decisions previously requiring manual facility manager intervention.
- Commercial:Office buildings, retail complexes, and institutional facilities prioritize demand-response revenue stacking and utility integration. Germany's KfW development bank financing programs and the Netherlands' social housing retrofit schemes favor heat-as-a-service contracting structures over capital equipment ownership.
- Residential:Single-family and multi-family housing developments balance upfront cost against operational savings. Subscription-based thermal service models are displacing direct sales in European social housing where public funding prioritizes operational expenditure structures.
- Industrial:Process heating applications with high thermal load consistency and integration into existing building management systems. Legacy control system interoperability demands extend development timelines and testing overhead for AI-native equipment suppliers.
Volume leader: Commercial. Steepest expansion trajectory: Hospitality.
Technology:
Application maturity separates these segments: smart controls represent baseline functionality, while machine learning integration demands higher hardware costs and cloud service infrastructure.
- Machine Learning:Embedded algorithms automate defrost cycles, compressor staging, and setpoint adjustments based on learned occupancy patterns and weather feeds. Hospitality operators leverage these systems for portfolio-wide thermal optimization without site-level engineering staff.
- IoT Enabled:Connected sensor arrays enabling remote monitoring, predictive maintenance alerts, and over-the-air firmware updates. Grid interconnection standards fragmentation between Germany, Japan, and the United States forces redundant certification investments for multi-region product families.
- Smart Controls:Programmable thermostats and mobile application interfaces providing user-facing energy management. Baseline expectation in premium product tiers across all geographies.
- Wireless Monitoring:Bluetooth and Wi-Fi connectivity for installation diagnostics and performance telemetry. Technician retraining requirements for A2L refrigerant handling certification slow field deployment velocity for connected systems.
Dominant by installed base: Smart Controls. Climbing the fastest: Machine Learning.
Distribution Channel:
Customer type and purchase scale determine channel selection: retail serves replacement demand, while direct sales capture new construction specification.
- Retail:Big-box home improvement chains and specialized HVAC distributors serving residential replacement markets. A.O.Smith leverages its North American manufacturing footprint to sustain distribution density across these channels.
- Direct Sales:Manufacturer-to-developer relationships for new construction and major retrofit projects. Procurement consolidation under portfolio-wide energy management platforms in Southeast Asian hospitality creates volume commitments bypassing traditional distribution.
- Distributors:Independent HVAC wholesalers maintaining local inventory and technician training relationships. Refrigerant handling certification requirements for A2L working fluids strain installer network capacity and slow equipment turnover.
- Online:E-commerce platforms and manufacturer direct-to-consumer channels. Limited penetration for heat pump systems due to installation complexity and warranty registration requirements.
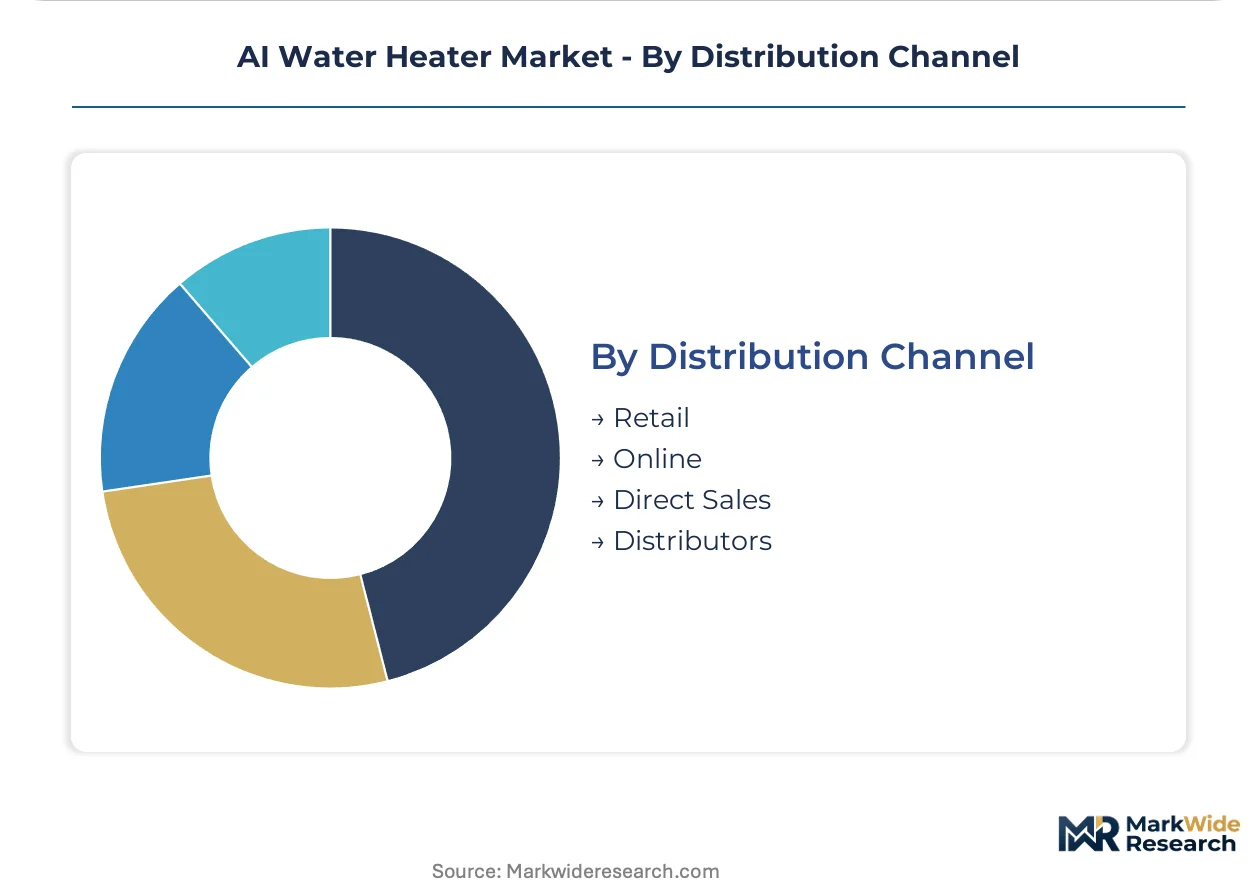
Highest volume: Retail. Gaining share fastest: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's hospitality corridor drives concentrated procurement of IoT-enabled thermal systems as Southeast Asian hotel chains consolidate portfolio-wide energy management. The analysis window tracks distinct regulatory and infrastructure maturity across five national markets where electrification mandates and building code revisions are compressing replacement cycles.
United States
Commercial building retrofits in California and the Northeast corridor accelerate heat pump deployment as state-level regulations outpace federal schedules. The EPA's SNAP program amendments phase down high-GWP refrigerants, compelling manufacturers to redesign circuits around R-454B alternatives. Texas and Florida residential markets show rising storage-system replacement demand tied to utility rebate programs.
Germany
The federal building code mandates intelligent thermal management in new construction and major renovations across Bavaria and North Rhine-Westphalia. KfW development bank financing programs favor heat-as-a-service contracting structures over capital equipment ownership in social housing retrofits. Berlin's commercial district hosts concentrated installer networks stocking EU F-Gas compliant equipment ahead of supply constraints.
China
MIIT enforces GB standards for appliance efficiency and networked device security, shaping certification requirements for domestic and export-bound manufacturers. The Yangtze River Delta and Pearl River Delta clusters concentrate heat exchanger production and permanent magnet motor assembly. Zhejiang and Guangdong provinces lead procurement of AI-optimized storage systems for multi-family housing developments.
Japan
METI efficiency standards and dense urban space constraints favor compact wall-mounted tankless units across Tokyo and Osaka metropolitan areas. The Kanto region maintains established installer networks around point-of-use thermal systems. Chubu and Kyushu industrial zones show emerging heat pump adoption as electrification mandates displace fossil-fuel heating in commercial facilities.
India
The Bureau of Energy Efficiency's updated commercial building codes create procurement windows for heat pump water heater suppliers establishing local assembly partnerships. Maharashtra and Gujarat lead pilot deployments in hospitality and healthcare facilities. Karnataka's technology corridor attracts IoT-native control system vendors targeting demand-response integration with state utility programs.
AI Water Heater Market Competitive Landscape
The competitive structure tilts toward diversified thermal equipment manufacturers with captive distribution networks. Market concentration remains moderate, with specialist heat pump vendors gaining share against legacy storage-system incumbents. Two strategic archetypes dominate: vertically integrated manufacturers controlling heat exchanger production, and IoT-native entrants bundling predictive maintenance software. Competitive moves center on backward integration into compressor manufacturing and strategic partnerships with hospitality energy management platforms.
Among North American diversified manufacturers, Rheem Manufacturing Company occupies a position exemplifying captive production of thermal system components. A.O.Smith represents the archetype of distribution density sustained through regional manufacturing footprints. Rinnai Corporation anchors the tankless-specialist tier with established installer network relationships. These three manufacturers illustrate divergent responses to refrigerant transitions and electrification mandates across their respective home markets.
| Leading Market Players |
|---|
| Viomi |
| A.O.Smith |
| Zhongshan Pake Electrical Technology |
| Aux |
| Colmo |
| Micoe |
| Guangdong Macro Gas Appliance |
| Rheem Manufacturing Company |
| Rinnai Corporation |
| Others |
Pricing and Supply Chain Analysis
Copper coil and rare earth magnet costs cascade from Yangtze River Delta refineries through three distinct pricing tiers, with hospitality buyers absorbing premium positioning for IoT-native systems while residential replacement markets face margin compression on standard storage units.
Pricing Analysis
Outcome-based thermal service contracts anchor premium pricing for commercial heat pump deployments, separating hospitality portfolio operators from cost-sensitive residential replacement buyers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—EU F-Gas compliant heat pumps command positioning above baseline storage systems. Pricing pressure stems from commodity volatility in copper and permanent magnet inputs, compressing margin predictability on fixed-price hospitality contracts. Residential segments exhibit highest price sensitivity, while commercial buyers prioritize demand-response revenue stacking over upfront capital expenditure.
Supply Chain Analysis
Permanent magnet motor production rests on Chinese rare earth processing capacity concentrated in Inner Mongolia and Jiangxi provinces, with heat exchanger fabrication clustering in Guangdong and Zhejiang. Compressor assembly draws from Japanese and South Korean precision manufacturing, while low-GWP refrigerant synthesis concentrates among select Chinese chemical producers. Single-source vulnerability in A2L working fluid supply creates exposure for European and North American assemblers facing phasedown deadlines. Distribution runs through captive HVAC wholesaler networks in developed markets, with direct manufacturer-to-developer channels gaining share in Southeast Asian hospitality procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around manufacturers with captive component production and certified refrigerant handling networks, as technician retraining requirements and compliance burdens force sub-scale competitors toward exit.
For Market Incumbents: Extend backward integration into compressor manufacturing and heat exchanger production to defend margin position against commodity volatility. Lock in multi-year refrigerant supply agreements with Chinese chemical producers before F-Gas phase-down constraints tighten. Prioritize certification investment for A2L handling protocols across installer networks to accelerate deployment velocity against emerging IoT-native entrants. For New Entrants and Emerging Players: HVAC distributors with established technician training relationships represent the most viable channel pathway for market entry. Target India's commercial building retrofit sector under Bureau of Energy Efficiency mandates, where local assembly partnerships create first-mover positioning ahead of incumbent manufacturing footprint expansion. Lead with demand-response software bundling rather than hardware margin capture to differentiate from established thermal equipment suppliers. For Investors and Strategic Acquirers: Accelerated hospitality procurement consolidation across Southeast Asian hotel chains is the leading indicator that portfolio-scale thermal service contracts will displace unit sales economics. Five-to-ten year viability favors manufacturers with integrated IoT platform development and captive refrigerant handling certification infrastructure. Watch for A2L refrigerant supply allocation disputes as the inflection signal for supply chain restructuring opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive production of variable-speed drives reduces exposure to rare earth price volatility from Chinese suppliers. |
| Refrigerant Handling Certification Program | EPA SNAP compliance and A2L technician training accelerate installer network capacity ahead of regulatory deadlines. |
| Portfolio Energy Management Platform Partnership | Singapore and Bangkok hospitality chains consolidate procurement under unified thermal optimization systems. |
| Local Assembly Partnership in India | Bureau of Energy Efficiency commercial building codes create procurement windows for heat pump suppliers establishing domestic manufacturing. |
| Demand-Response Software Development | Utility-controlled thermal storage enables revenue stacking beyond energy savings through capacity payment capture. |
Research Methodology
Multi-period observation of heat pump deployment rates, refrigerant transition timelines, and hospitality procurement consolidation anchored the trend analysis, supplemented by interviews with HVAC distributor procurement leads, commercial facility managers, heat pump system engineers, and utility demand-response program officers. Secondary validation drew from EPA SNAP program filings, EU F-Gas regulatory databases, MIIT GB standard publications, and customs trade data on compressor and heat exchanger imports. Bottom-up unit shipment estimates triangulated against top-down energy efficiency mandate penetration models.
Segment-weighting across product type, end user category, technology tier, and distribution channel structured the analytical framework, with heat pump, hospitality, machine learning, and direct sales segments receiving differentiated growth assumptions across the projection horizon. CAGRs derived from regression analysis of historical efficiency standard adoption curves and electrification mandate implementation schedules. Forecast inputs incorporated utility rebate program funding levels and building code revision timelines without specific year anchoring.
Several conditions sit outside the modeled scope, including unanticipated refrigerant supply disruptions, abrupt tariff restructuring on Chinese magnetic components, and state-level regulatory acceleration beyond federal schedules in the United States. Forecasts reflect documented assumptions regarding technician retraining velocity and hospitality capital expenditure continuity. A small set of named triggers warrants ongoing watch: A2L refrigerant allocation constraints, grid interconnection standard harmonization progress, and copper price volatility spikes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
Southeast Asia Cooling Systems Market
Energy Management Systems
Global Digital Utility Market
Energy Management Systems
Shared Power Bank Market
Energy Management Systems
Cooling Management System Market
Energy Management Systems
Building Energy Management Systems (BEMS) Market
Energy Management Systems
US Energy Management Systems Market
Energy Management Systems
IoT Smart Gas Meter Market
Energy Management Systems
Smart Air Cleaners Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
Energy Management Systems (EMS) Market
Energy Management Systems
Smart Programmable Thermostat Market
Energy Management Systems
Portable Air Cooler Market
Energy Management Systems
District Cooling Market
Energy Management Systems
Advanced Server Energy Monitoring Tools Market
Energy Management Systems
Airflow Management Market