
 Building Energy Management Systems (BEMS) Market | 2026-2036
Building Energy Management Systems (BEMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Building Energy Management Systems (BEMS) Market Intelligence
The shift toward cloud-based, IoT-enabled platforms is fragmenting the traditional, on-premise BEMS architecture. This transition allows for more modular and scalable deployments, opening the market to specialized software vendors. Legacy providers like Johnson Controls leverage their extensive HVAC installed base to push digital services. Schneider Electric competes with its open EcoStruxure architecture, while Siemens differentiates through its integrated building and industrial automation expertise.
Building Energy Management Systems are centralized platforms designed to monitor and control a building's mechanical and electrical equipment. These systems use a network of sensors and actuators to optimize energy consumption from HVAC, lighting, and power systems against predefined performance targets. The software component, particularly cloud-based platforms, is now the primary value driver over commoditizing hardware. While the commercial buildings segment remains the largest end-user, AI and IoT-enabled solutions represent the fastest-growing technology category.
Building performance standards, including the EU's Energy Performance of Buildings Directive and codes in the United States referencing ASHRAE 90.1, are key demand drivers. These regulations compel building owners to adopt BEMS for compliance monitoring and achieving energy efficiency targets. The critical strategic decision for asset owners now centers on selecting between integrated single-vendor ecosystems and more flexible, open-architecture platforms.
Market Dynamics
The fundamental dynamic shaping the BEMS market is the collision of stringent energy efficiency regulations with the digitalization of commercial real estate. Mandates like the EU Green Deal are forcing building owners to upgrade, while cloud-based platforms provide the tools for compliance and optimization.
Growth Catalysts
- Regulatory Mandates:Government policies, including the EU's Energy Performance of Buildings Directive and building codes in the United States that reference ASHRAE 90.1, compel the adoption of advanced energy monitoring and control systems for compliance.
- AI and IoT Integration:The fusion of Artificial Intelligence with IoT sensors enables predictive maintenance and autonomous optimization of HVAC and lighting systems, delivering verifiable energy savings that justify investment for commercial building operators.
- Portfolio-Level Optimization:Large real estate investment trusts and corporate occupiers in geographies like China and the US require centralized platforms to benchmark and manage energy performance across diverse, geographically dispersed building portfolios.
Market Restraints
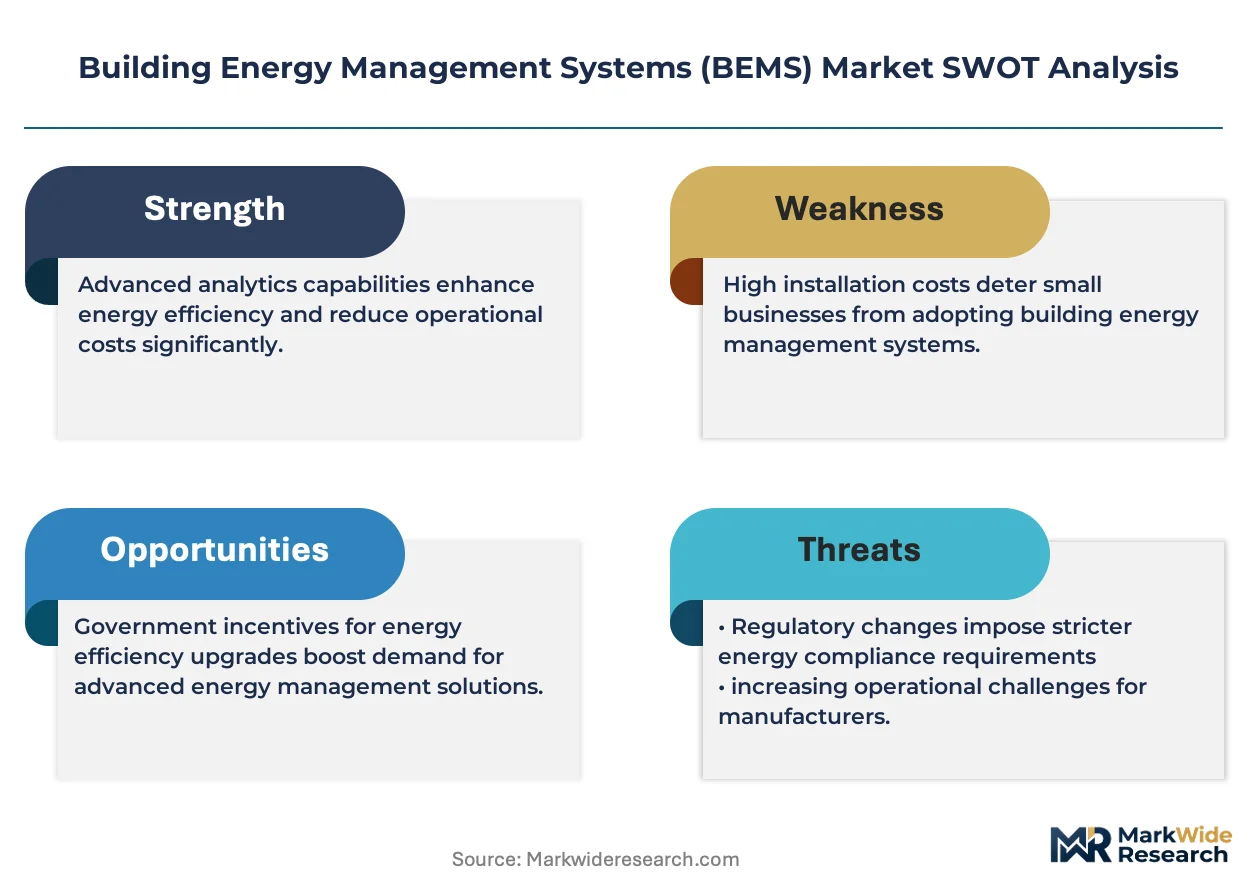
- High Retrofit Costs:The significant capital expenditure required to install or upgrade BEMS hardware and sensors in older, existing buildings presents a major barrier for owners, particularly in the small-to-medium commercial segment.
- Legacy System Integration:BEMS platforms often face technical hurdles when attempting to interface with a building's existing, proprietary, and often outdated HVAC, lighting, and security systems from multiple vendors, leading to costly custom integrations.
- Skilled Labor Scarcity:A shortage of technicians and engineers with the dual expertise in both traditional building mechanical systems and modern IT networking and data analytics hinders the effective deployment and maintenance of sophisticated BEMS solutions.
Strategic Opportunities
- Small-to-Medium Buildings (SMBs):The development of simplified, scalable, and lower-cost cloud-based BEMS solutions creates an opportunity to penetrate the largely underserved SMB market, which represents a vast number of buildings globally.
- Grid-Interactive Buildings:Integrating BEMS with electric vehicle charging infrastructure and onsite energy storage allows buildings to participate in utility demand-response programs, creating new revenue streams for building owners.
- Energy-as-a-Service (EaaS) Models:Offering BEMS through a service model, where vendors finance the upfront cost in exchange for a share of energy savings, lowers the adoption barrier for capital-constrained customers and creates recurring revenue.
Industry Challenges
- Interoperability and Standardization:The lack of a universal communication standard across BEMS hardware and software vendors creates significant integration challenges, leading to vendor lock-in and limiting the adoption of open-architecture systems.
- Cybersecurity Vulnerabilities:Connecting critical building operational technology (OT) like HVAC and access control to IT networks and the cloud introduces significant cybersecurity risks, requiring robust security protocols to prevent breaches.
- Data Ownership and Privacy:Ambiguity over the ownership and usage rights of the vast amounts of operational data generated by BEMS creates friction between building owners, tenants, and technology vendors, complicating data-driven service offerings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Energy Management Systems (BEMS) Market |
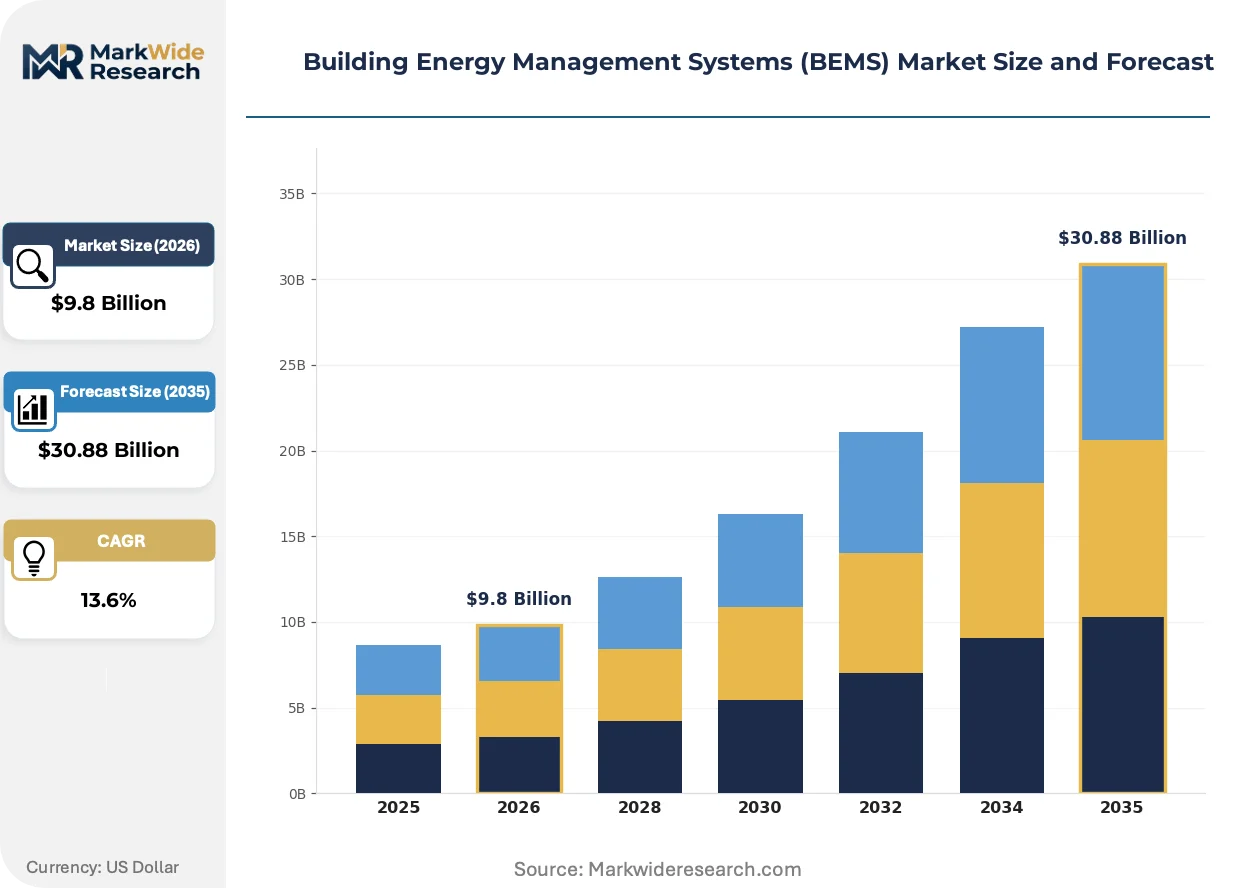
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $30.88 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Integration End User: Commercial Buildings, Industrial Facilities, Residential, Educational Institutes Deployment: On-Premise, Cloud-Based, Hybrid, Remote Technology: IOT, Artificial Intelligence, Machine Learning, Automation |
| Companies Covered | Johnson Controls, ABB, Schneider Electric, Verdigris, EnergyCAP, Siemens, IBM, BuildingIQ, Honeywell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Energy Management Systems (BEMS) Market Strategic Shifts & Innovations
The BEMS landscape is being redefined by the convergence of decarbonization goals and advanced digitalization. This forces a transition where buildings are no longer viewed as static assets but as dynamic, data-driven nodes within a larger energy ecosystem, demanding more intelligent and responsive management platforms.
Digital Twin technology creates a virtual, data-rich replica of a physical building, its systems, and its operational processes. Large-scale commercial portfolio managers and mission-critical facilities like data centers are the primary adopters. As a result, BEMS functionality is migrating from reactive monitoring to predictive, simulation-based optimization, allowing operators to test efficiency scenarios virtually before implementing them physically.
Building performance standards, such as California's Title 24, are becoming more stringent and prescriptive. These regulations now mandate not just energy efficiency but also demand-response capabilities, forcing buildings to be able to curtail energy use in response to grid signals. This primarily impacts HVAC and lighting control manufacturers, who must now engineer grid-interactive features directly into their core product offerings to remain compliant in key markets.
A clear shift in purchasing behavior is moving away from one-time capital purchases of hardware and perpetual software licenses. Buyers, especially in the corporate real estate sector, increasingly favor subscription-based models that bundle software, analytics, and continuous updates as a service. This trend is most visible across portfolios in the United States and Europe, where owners prioritize operational agility over long-term capital commitments.
Building Energy Management Systems (BEMS) Market Segmentation
Market segmentation provides a granular view of the BEMS industry, highlighting the distinct drivers and strategic imperatives across various product types, end-user applications, deployment models, and integrated technologies. Understanding these segments enables stakeholders to tailor solutions and allocate resources effectively within this evolving market.
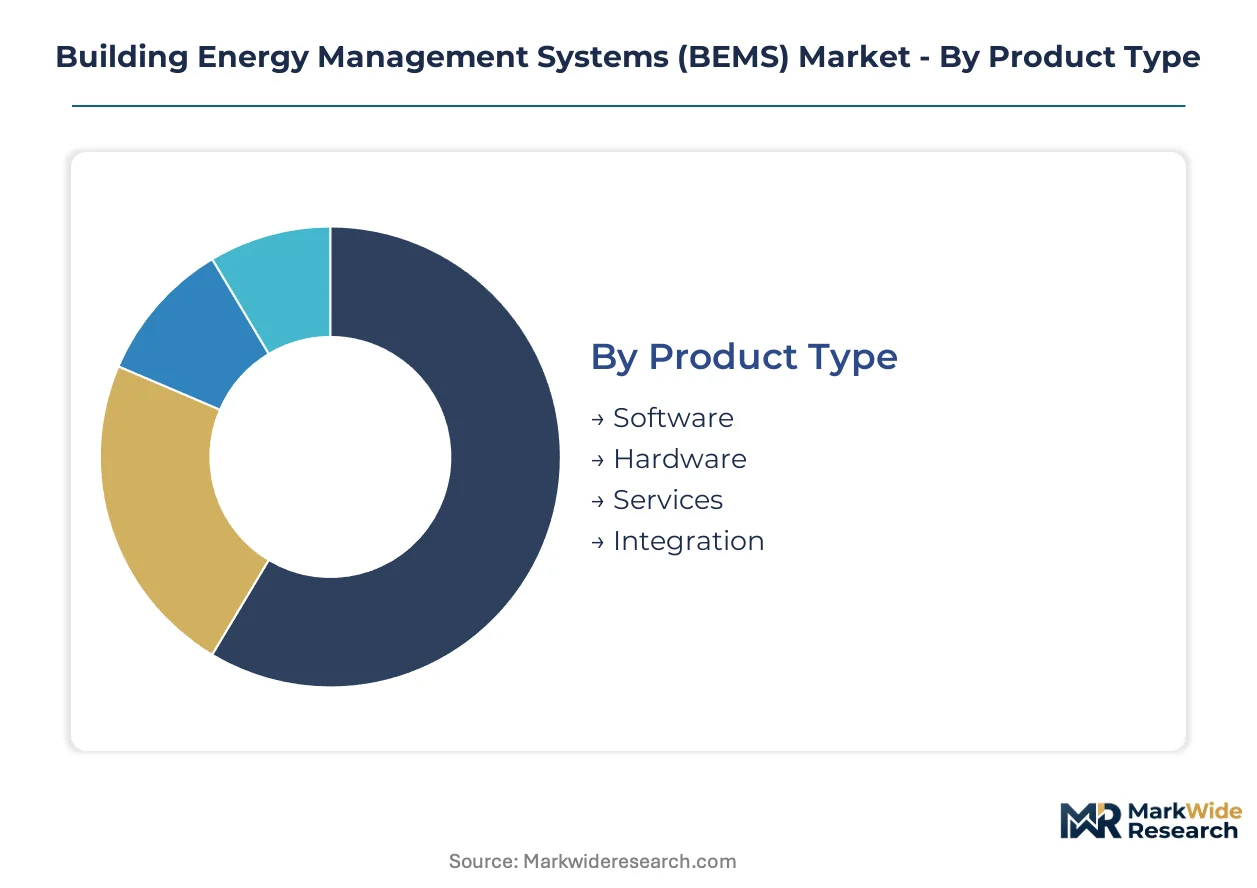
Product Type:
The BEMS market's product offerings span a maturity spectrum, from established physical components to rapidly evolving digital solutions.
- Software:Comprises the core intelligence and analytics platforms that process sensor data and control building systems. Demand concentrates in commercial real estate portfolios across the United States and Europe, driven by the need for advanced optimization.
- Hardware:Includes sensors, actuators, controllers, and gateways that form the physical layer of BEMS, collecting data and executing commands.
- Services:Encompasses installation, maintenance, energy auditing, and ongoing optimization support for BEMS deployments. Corporate occupiers in China and the US require these services for portfolio-level energy management and compliance.
- Integration:Focuses on connecting diverse building systems and data sources, ensuring seamless data flow and unified control within a BEMS platform.
Software handles the majority of throughput; Services is the fastest mover on share.
End User:
End-user segments define the application scope for BEMS, reflecting diverse operational needs and energy consumption patterns.
- Commercial Buildings:This segment includes offices, retail spaces, and hospitality venues, where BEMS optimizes HVAC, lighting, and power for occupant comfort and energy savings. Regulatory frameworks like the EU Green Deal compel advanced BEMS adoption in these structures.
- Industrial Facilities:Encompasses manufacturing plants, data centers, and warehouses, utilizing BEMS for critical process control, equipment monitoring, and energy-intensive operations. Mission-critical facilities are primary adopters of Digital Twin technology for predictive optimization.
- Residential:Focuses on energy management solutions for multi-family dwellings and smart homes, often integrated with broader home automation systems.
- Educational Institutes:Implements BEMS in universities and schools to manage energy consumption across diverse facilities, balancing comfort with operational costs.
Commercial Buildings demonstrate the most immediate demand for BEMS due to stringent regulations; Industrial Facilities seek BEMS for process optimization and critical asset management.
Deployment:
Deployment models reflect architectural preferences, influencing scalability, accessibility, and upfront capital expenditure for BEMS solutions.
- On-Premise:Refers to BEMS hardware and software installed directly within the building's infrastructure, providing localized control and data security. Legacy providers often leverage their installed base to push these traditional deployments.
- Cloud-Based:Involves BEMS software and data hosted on remote servers, offering scalability, remote access, and subscription-based service models. This model facilitates portfolio-level optimization for large real estate investment trusts.
- Hybrid:Combines elements of both on-premise and cloud-based systems, balancing local control with remote analytics and data storage.
- Remote:Enables offsite monitoring and control of building systems, often through web interfaces or mobile applications, enhancing operational flexibility.
Cloud-Based deployment offers superior flexibility and lower upfront costs, while On-Premise solutions provide maximum data control for specific use cases.
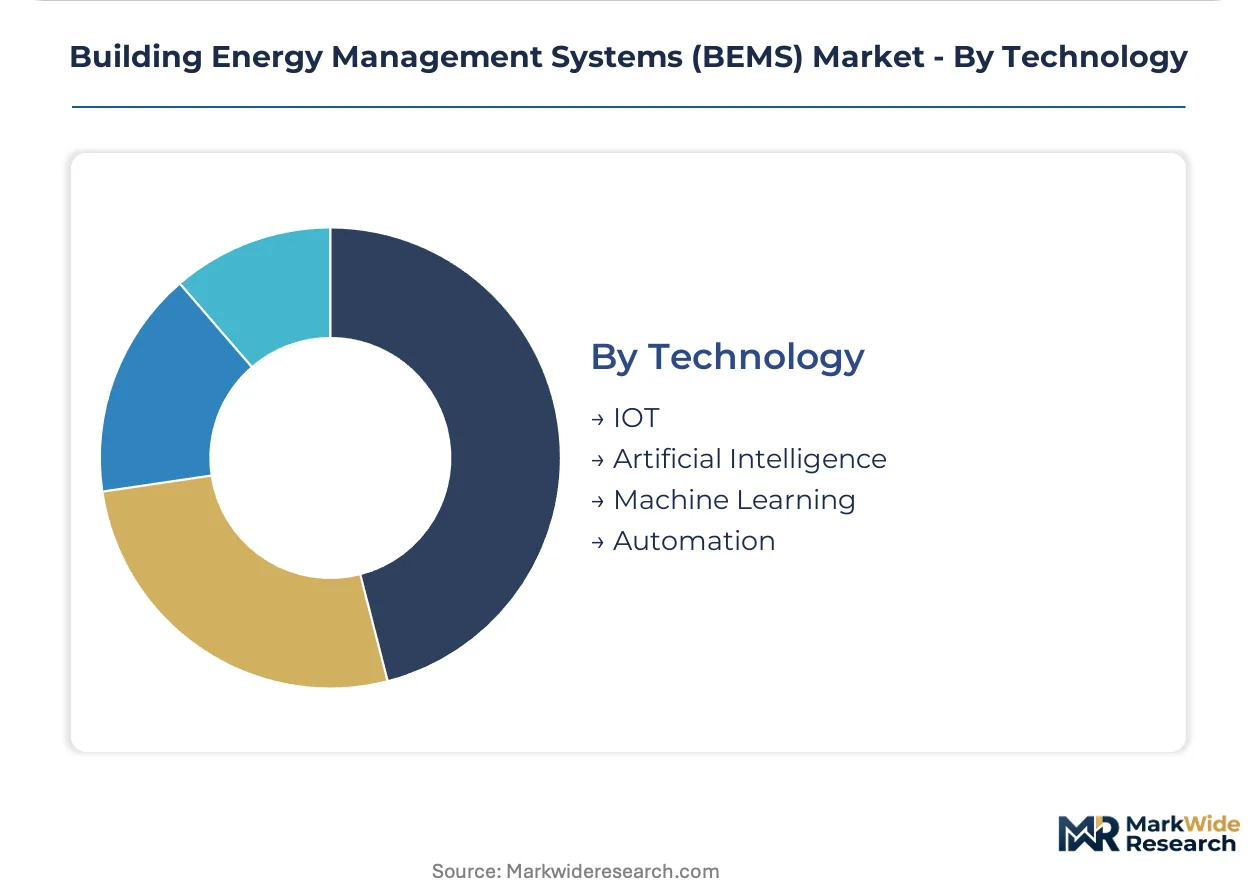
Technology:
Technology segments highlight the innovation and intelligence layers integrated into BEMS, dictating system capabilities and optimization potential.
- IOT:Involves networked sensors, actuators, and devices that collect real-time data from building equipment and environments. IOT integration enables predictive maintenance and autonomous optimization of HVAC and lighting systems.
- Artificial Intelligence:Utilizes algorithms to analyze BEMS data, identify patterns, and make autonomous decisions for energy optimization and predictive analytics. AI-driven optimization is particularly strong in commercial real estate portfolios across the United States and China.
- Machine Learning:A subset of AI, enabling BEMS to learn from historical data and adapt control strategies over time, continuously improving energy performance.
- Automation:Refers to programmed routines and rules that automatically control building systems based on predefined schedules, sensor inputs, or performance targets.
IOT forms the foundational data layer for BEMS; Artificial Intelligence and Machine Learning represent the future trajectory for advanced, autonomous building optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technology advancements from the United States influence BEMS adoption globally, while European regulatory frameworks like the EU Green Deal set a high bar for energy performance. This dynamic drives demand for sophisticated building management solutions across diverse international markets. Asian economies, particularly China, rapidly implement these technologies for large-scale urban development.
United States
United States demand for BEMS centers on AI-driven optimization within large commercial real estate portfolios. Federal and state regulations, including ASHRAE 90.1 and California's Title 24, mandate stringent energy efficiency standards. Technology hubs like Silicon Valley and New York City drive innovation in cloud-based BEMS solutions for smart buildings.
China
China's BEMS market experiences significant growth from large corporate occupiers and new urban developments. The country's dual carbon goals and national GB standards compel energy performance improvements across commercial structures. Major metropolitan areas like Shanghai and Beijing lead in deploying AI-enabled BEMS for extensive building portfolios.
Germany
Germany's BEMS adoption is driven by stringent EU Green Deal mandates and national sustainability goals for commercial properties. The Energy Performance of Buildings Directive (EPBD) necessitates advanced energy monitoring and control. Industrial centers like Munich and Frankfurt increasingly integrate BEMS with industrial automation systems for efficiency.
India
India's BEMS market expands with new commercial construction and smart city projects. The Energy Conservation Building Code (ECBC) promotes energy-efficient design and operation in large buildings. Major urban centers such as Bengaluru and Mumbai are adopting BEMS for optimizing energy use in IT parks and corporate campuses.
Japan
Japan focuses on BEMS to enhance energy conservation in existing buildings and new smart infrastructure. METI's energy policies encourage integration of advanced building management systems for efficiency and resilience. Major cities like Tokyo and Osaka are pioneering grid-interactive buildings and digital twin technologies.
Building Energy Management Systems (BEMS) Market Key Industry Players
On the supply side, the industry is characterized by a blend of established industrial conglomerates and emerging software specialists. Large legacy providers leverage their extensive hardware installed base to offer digital services, while pure-play software vendors focus on cloud-native, IoT-enabled platforms. Strategic archetypes include integrated building technology giants, dedicated BEMS software providers, and specialized analytics firms. Companies are pursuing strategic partnerships for interoperability and expanding their digital service portfolios.
Among integrated building technology giants, Johnson Controls leverages its deep expertise in HVAC systems to drive adoption of its BEMS platforms. Schneider Electric, a French multinational corporation, exemplifies the shift towards open architectures with its EcoStruxure platform, fostering broader ecosystem participation and integration with third-party solutions. German industrial powerhouse Siemens differentiates through its comprehensive portfolio spanning building automation and industrial control systems, offering robust integrated solutions for diverse facility types. These players anchor the market by providing end-to-end solutions, combining hardware, software, and services for complex commercial and industrial applications across global markets.
| Leading Market Players |
|---|
| Johnson Controls |
| ABB |
| Schneider Electric |
| Verdigris |
| EnergyCAP |
| Siemens |
| IBM |
| BuildingIQ |
| Honeywell |
Cost & Logistics Intelligence
Regulatory chokepoints, particularly those stemming from the EU Green Deal and US building codes, significantly determine both BEMS pricing tier spreads and the overall supply chain shape. These mandates compel adoption, influencing demand and the value placed on compliance-driven solutions.
Pricing Analysis
The technology-generation pricing gap differentiates between mature hardware components and advanced, AI-driven software solutions. Subscription-based models increasingly dominate software offerings, bundling analytics and continuous updates. Price differentiation stems from customization levels for specific building portfolios and the depth of integrated after-sales service. Pricing softness runs through commoditized hardware components due to intense competition among manufacturers. Small-to-medium building owners represent the most price-sensitive segment, while large commercial real estate operators prioritize value and long-term operational savings.
Supply Chain Analysis
Export-control regimes for advanced microelectronics could limit the flow of critical components for BEMS hardware. Geographic supply for BEMS components concentrates in East Asia for sensors and actuators, while software development clusters in North America and Europe. Raw material dependencies include specialized semiconductors, networking components, and various plastics for sensor casings. Single-source vulnerability for specific IoT modules presents a structural supply chain risk. Distribution runs through a blend of direct sales channels for large enterprises and a network of system integrators for broader market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a defensive-moat story, primarily justified by the high switching costs associated with integrated building management systems and the regulatory entrenchment of BEMS adoption.
For Market Incumbents: Build a comprehensive solution moat by leveraging existing installed bases of HVAC and control systems. Integrate advanced AI and IoT capabilities into legacy platforms to counter pure-play software vendor threats. Invest in R&D for interoperability standards to simplify integration with third-party systems. Pursue strategic partnerships with specialized software firms to expand digital service portfolios and maintain a competitive edge.
For New Entrants and Emerging Players: Establish a beachhead in the underserved small-to-medium building segment with simplified, cloud-based solutions. Focus on open-architecture platforms that offer flexible integration with diverse hardware. Develop Energy-as-a-Service models to lower upfront capital expenditure barriers for customers. Target specific niche applications like demand-response optimization or grid-interactive building capabilities as a go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized software vendors and integration specialists. Long-term viability hinges on continued regulatory enforcement and the accelerating digitalization of commercial real estate. Acquisition targets should possess strong intellectual property in AI/ML algorithms or deep expertise in specific vertical integration challenges. The signal to watch is the widespread adoption of open communication standards across hardware and software vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates diverse building systems, enhancing data flow and unified control for operators. |
| Strategic Partnership | Expands market reach and technology capabilities, addressing interoperability challenges with external vendors. |
| Acquisition of Specialist Firm | Accelerates entry into niche markets or strengthens AI/IoT expertise for advanced optimization. |
| Geographic Expansion | Captures demand in rapidly developing regions like China and India, driven by new urban projects. |
| Product Launch | Introduces innovative cloud-based solutions, targeting underserved segments like small-to-medium buildings. |
Research Approach
Desk research of government energy reports, building code databases, technology whitepapers, and financial disclosures preceded structured interviews with building owners, facility managers, BEMS software engineers, and regulatory compliance officers. This approach combined primary and secondary research, triangulating insights from both qualitative and quantitative sources to ensure robustness.
Assumptions regarding regulatory enforcement levels and technological adoption rates were held fixed across the analysis window, while market dynamics and competitive landscapes were varied. The analytical framework modeled segmentation dimensions including product type, end-user, deployment, technology, and regional regulations. Compound annual growth rates were derived from historical data analysis and projected future trends, incorporating inputs such as energy consumption trends and smart building investment forecasts.
Sensitivities concentrate around sudden policy shifts, unforeseen technological breakthroughs, or significant economic downturns. Forecasts reflect these assumptions, based on the current understanding of market forces. Material shifts in global energy policy or the pace of digitalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Bed Cooling System Market
Energy Management Systems
Advanced Server Energy Monitoring Tools Market
Energy Management Systems
Intelligent Digital Meter Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
Energy Management Systems (EMS) Market
Energy Management Systems
Europe Home Energy Management System Market
Energy Management Systems
Smart Water Cooler Market
Energy Management Systems
United Arab Emirates Portable Air Conditioning Market
Energy Management Systems
Evaporative Air Cooler Market
Energy Management Systems
Smart Thermostat Market
Energy Management Systems
Smart Utilities Management Market
Energy Management Systems
Cooling Management System Market
Energy Management Systems
North America Energy Management Systems Market
Energy Management Systems
Grid Optimization Solution Market
Energy Management Systems
Airflow Management Market
Energy Management Systems
Outage Management System (OMS) Market