
 Data Center Power Management Market | 2026-2036
Data Center Power Management Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Power Management Market Outlook
ISO 50001 energy management certification is collapsing the vendor pool to firms with verified audit trails and continuous efficiency protocols. Schneider Electric leverages its integrated EcoStruxure platform to anchor large-scale deployment contracts across European hyperscale campuses. Eaton competes through vertical integration into medium-voltage switchgear and UPS hardware, sustaining pricing power in enterprise segments. Vertiv specializes in thermal-electric co-optimization, dominating liquid-cooled power architectures for AI training clusters.
Data center power management encompasses the hardware, software, and services that monitor, distribute, condition, and backup electrical infrastructure within mission-critical IT facilities, typically operating at 480/277V three-phase distribution with redundancy tiers from N+1 to 2N+1. Its primary purpose is eliminating single points of failure while minimizing power usage effectiveness ratios below 1.4. UPS systems and power distribution units capture the bulk of current hardware spend as retrofit cycles accelerate in aging enterprise facilities. Hyperscale data centers represent the fastest-growing end user category, though colocation providers retain stronger margin pools through long-term service contracts and recurring maintenance revenue.
EPA Energy Star certification and EU Ecodesign requirements are forcing efficiency disclosures that reshape procurement criteria for enterprise buyers across North America and Europe. OSHA electrical safety standards and NFPA 70 National Electrical Code govern installation practices, creating compliance barriers for unqualified contractors. India's BIS efficiency labeling and China's GB 50174 data center design standards add further jurisdictional complexity for multinational operators. Stakeholders must monitor evolving carbon border adjustments and local content rules as these determine which vendor ecosystems qualify for public and regulated utility contracts.
Market Dynamics
AI training clusters are forcing power density thresholds past 50kW per rack, collapsing legacy air-cooled architectures and mandating liquid-cooled power distribution redesigns across hyperscale campuses.
Growth Catalysts
- EPA Energy Star Certification:Mandated efficiency disclosures are disqualifying uncertified vendors from federal procurement pools and enterprise RFP shortlists across the United States.
- Hyperscale Buildouts:Cloud operators in India, Germany, and the United States are commissioning multi-hundred-megawatt facilities requiring redundant 2N+1 power architectures.
- Liquid Cooling Convergence:Thermal-electric co-optimization is enabling power delivery systems to operate at higher ambient temperatures, reducing mechanical cooling loads.
Market Restraints
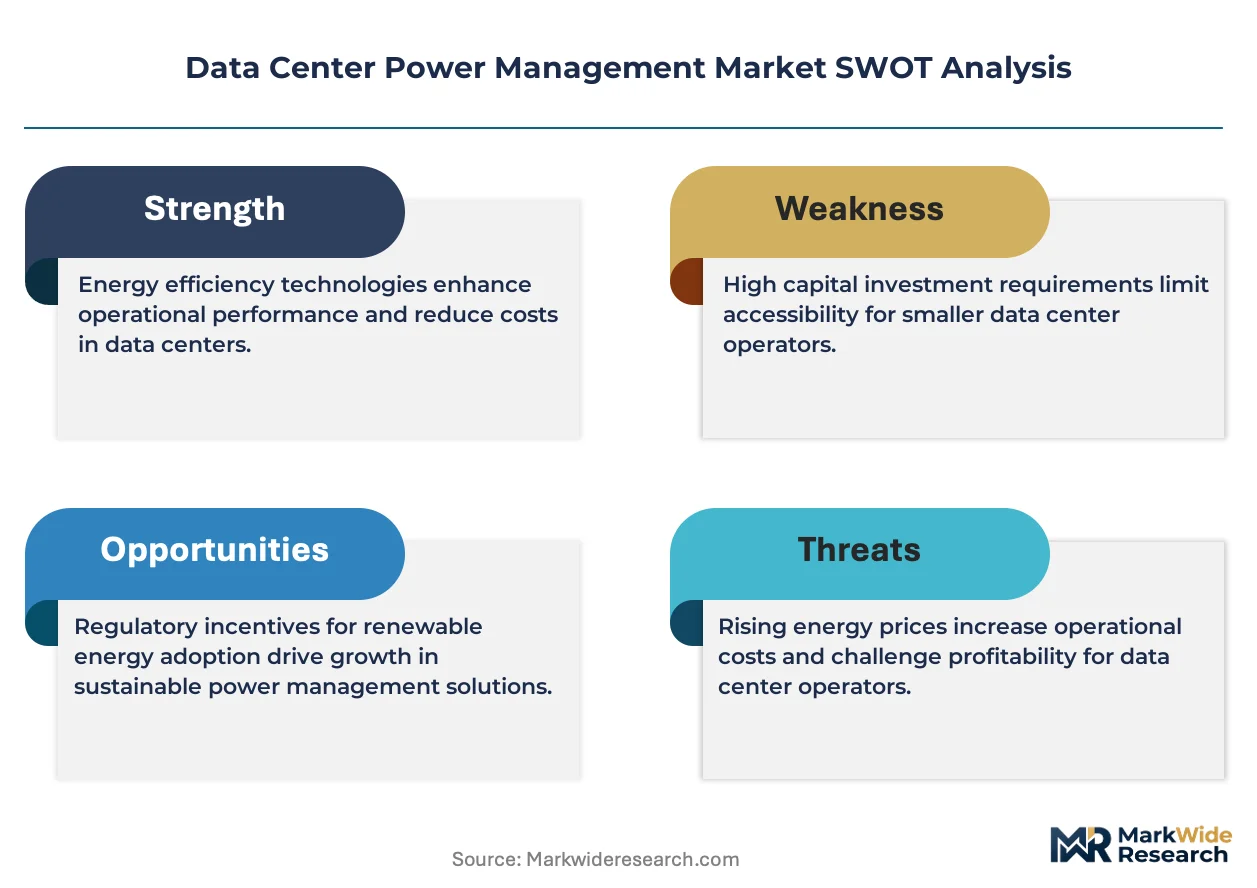
- Copper Price Volatility:Busbar and conductor raw material costs are compressing margins for switchgear manufacturers without long-term commodity hedging.
- Specialized Contractor Scarcity:Certified electricians trained in 480/277V three-phase mission-critical installation are concentrated in Germany, the United States, and Japan.
- NFPA 70 Compliance Friction:National Electrical Code updates are extending permitting timelines and disqualifying designs using pre-certified overseas equipment.
Strategic Opportunities
- India BIS Efficiency Labeling:Tiered certification schemes are creating first-mover advantages for vendors establishing local testing partnerships ahead of mandatory adoption.
- Edge Micro-Data Centers:Distributed 5G infrastructure and autonomous vehicle processing nodes require compact, containerized power conditioning units with integrated UPS and switchgear.
- EU Ecodesign Requirements:Standby loss limits and efficiency disclosure mandates are opening procurement pathways for vendors with verified lifecycle carbon footprints.
Industry Challenges
- ISO 50001 Audit Capacity:Certified energy management system assessors are backlogged 12-18 months, delaying facility commissioning and vendor qualification.
- Legacy Facility Retrofit Complexity:Aging enterprise data centers with 208/120V distribution require complete electrical infrastructure replacement to support AI GPU densities.
- Interoperability Fragmentation:Proprietary power management software protocols are preventing unified monitoring across multi-vendor UPS, PDU, and switchgear fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Power Management Market |
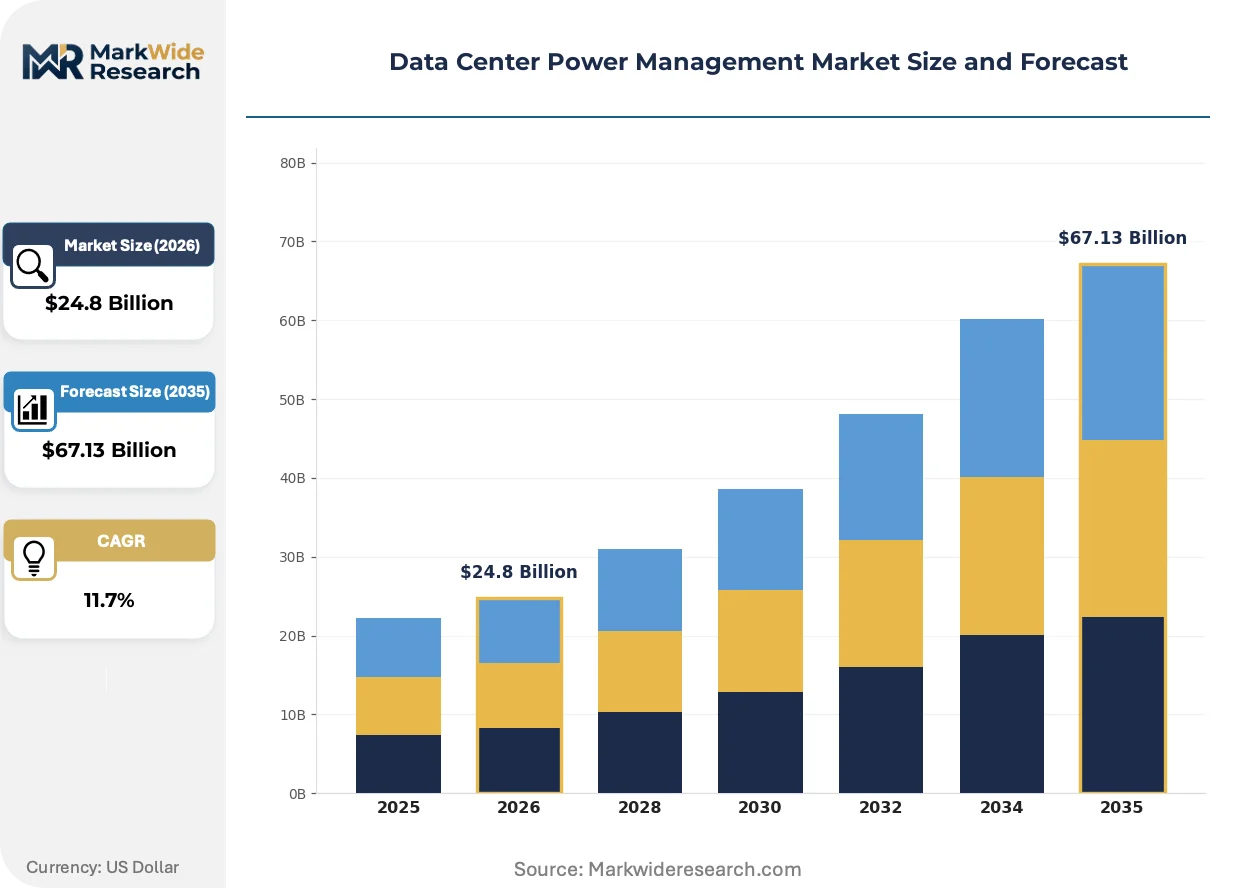
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $67.13 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
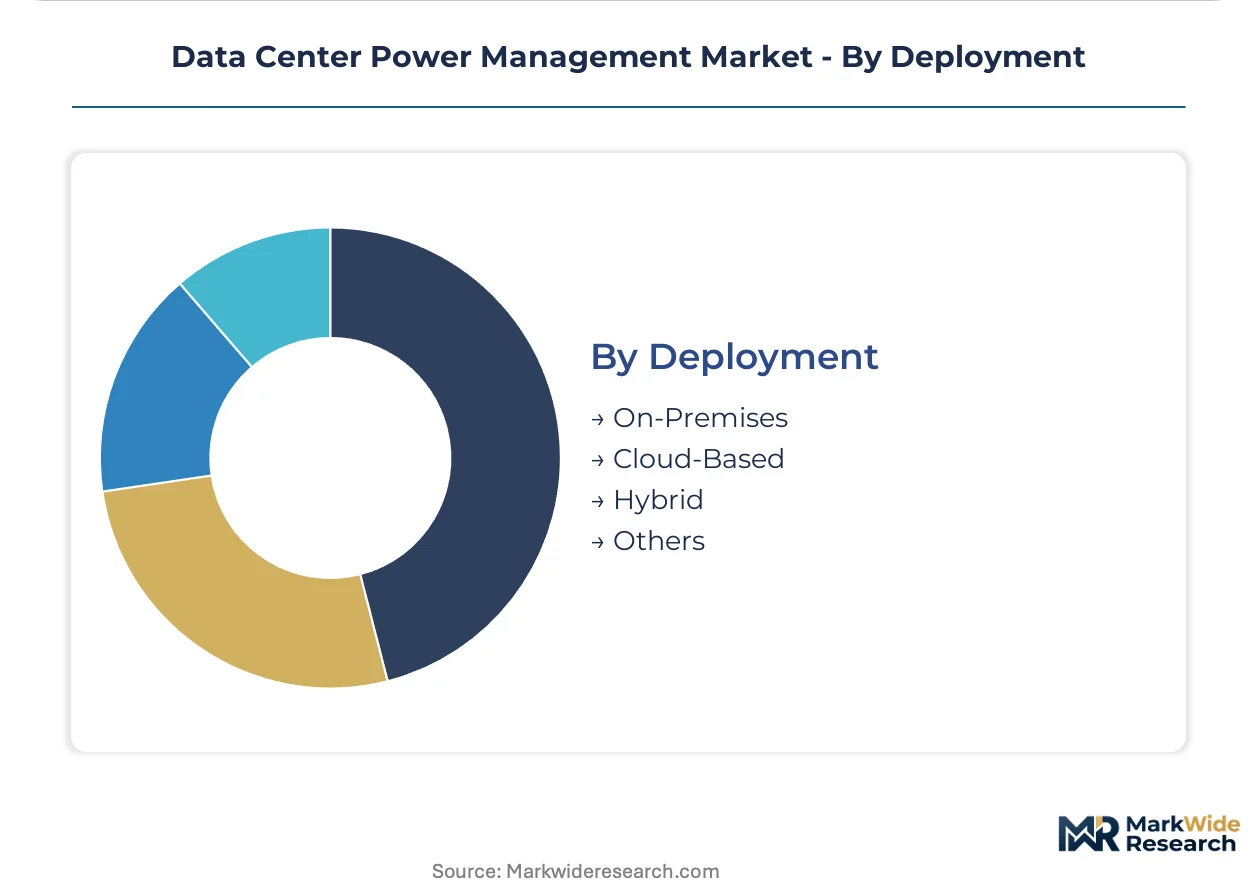
| Segmentation | Technology: UPS Systems, Power Distribution Units, Generators, Power Monitoring Software End User: Colocation Providers, Enterprises, Government Institutions, Hyperscale Data Centers Service Type: Consulting, Installation, Maintenance, Managed Services Deployment: On-Premises, Cloud-Based, Hybrid, Others |
| Companies Covered | Eaton, Cyber Power Systems, Schneider Electric, Cummins, Anord Mardix, Vertiv, Delta Electronics, Rosenberger OSI, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Power Management Market Strategic Shifts
Power architecture modularity is decoupling capital deployment from capacity planning, enabling hyperscale operators to scale electrical infrastructure in 2-4MW increments matched to actual server deployment.
Busway power distribution is decomposing traditional raised-floor PDU cabling in AI training facilities. Hyperscale operators in the United States and Germany are specifying overhead busbar systems for 400-800A drops to liquid-cooled racks. This topology is compressing installation timelines and enabling hot-swappable tap box reconfigurations without electrical shutdowns.
EU Ecodesign standby loss regulations are forcing UPS manufacturers to redesign double-conversion architectures for partial-load efficiency. The 2023 tiered limits are eliminating transformer-based designs from European procurement lists. Colocation providers in Frankfurt and Amsterdam are now specifying 96%+ efficient modular UPS with intelligent eco-mode switching.
Lifecycle service unbundling is fragmenting traditional hardware-plus-maintenance contracts. Enterprise buyers in the United States are separating capital equipment purchase from third-party commissioning and ongoing energy optimization services. This pattern is most visible in financial services verticals where internal sustainability teams demand direct access to granular power quality data.
Data Center Power Management Market Segmentation
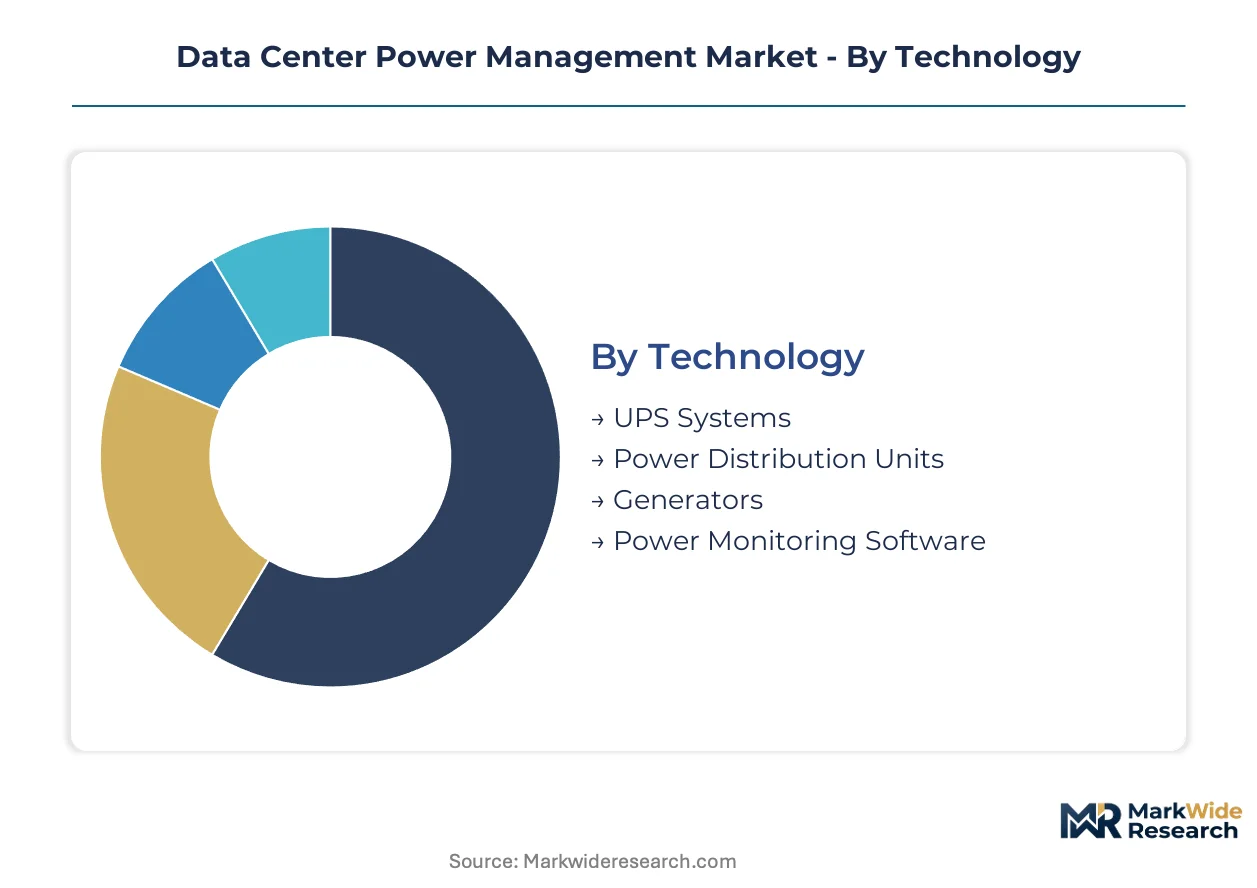
Power management procurement splits sharply between capital-intensive hardware refresh cycles and recurring service contracts. EPA Energy Star and EU Ecodesign certifications are fragmenting vendor qualification pools, forcing buyers to map segments against compliance tiers before sourcing decisions.
Technology:
EPA Energy Star efficiency thresholds and EU Ecodesign standby loss limits are disqualifying legacy transformer-based designs from public procurement pools across the United States and Germany.
- UPS Systems:Double-conversion and modular architectures dominate hyperscale specifications, with 96%+ efficiency ratings now mandatory for Frankfurt and Amsterdam colocation tenders. Demand concentrates in liquid-cooled AI training facilities where power quality tolerance has tightened to ±1% voltage regulation.
- Power Distribution Units:Intelligent rack-level PDUs with outlet-level metering capture retrofit spend in aging enterprise facilities upgrading from 208/120V to 480/277V distribution. North American financial services verticals are prioritizing units with embedded cybersecurity certifications for remote monitoring access.
- Generators:Tier 4 Final diesel and natural gas standby systems anchor 2N+1 redundancy architectures in multi-hundred-megawatt campuses.
- Power Monitoring Software:DCIM-integrated platforms with API-accessible telemetry are displacing siloed vendor-specific tools.
UPS Systems handles the majority of throughput; Power Monitoring Software is the fastest mover on share.
End User:
Customer type determines contract structure, with hyperscale operators favoring capital-light modular deployment while colocation providers lock in decade-long service agreements.
- Hyperscale Data Centers:Cloud operators in India, Germany, and the United States are commissioning 2N+1 redundant architectures for 50kW+ per-rack densities. Liquid-cooled busway distribution is replacing raised-floor PDUs in new builds to compress installation timelines.
- Colocation Providers:Frankfurt and Amsterdam operators are unbundling hardware procurement from lifecycle energy optimization services, creating separate vendor pools for equipment and ongoing efficiency auditing under ISO 50001 protocols.
- Enterprises:Aging 208/120V facilities in the United States face complete electrical infrastructure replacement to support AI GPU deployments.
- Government Institutions:Federal procurement pools are restricting vendor qualification to EPA Energy Star certified equipment with verified audit trails.
Hyperscale Data Centers commands the largest absolute spend; Colocation Providers delivers the stickiest recurring revenue streams.
Service Type:
ISO 50001 certification backlogs are stretching commissioning timelines, elevating the premium on qualified installation and managed services capacity.
- Installation:Certified electricians trained in 480/277V three-phase mission-critical work are concentrated in Germany, the United States, and Japan, creating regional bottlenecks for facility commissioning.
- Managed Services:Third-party energy optimization contracts are expanding fastest as enterprise sustainability teams demand direct access to granular power quality data without vendor lock-in.
- Consulting:Efficiency audit and retrofit planning services are backlogged 12-18 months in markets with mandatory BIS or Ecodesign compliance deadlines.
- Maintenance:Long-term service agreements with guaranteed uptime SLAs anchor colocation provider margins.
Installation absorbs the bulk of current labor allocation; Managed Services is climbing the fastest as procurement unbundling accelerates.
Deployment:
Topology choice tracks data gravity requirements, with latency-sensitive workloads resisting full cloud migration despite operational flexibility advantages.
- On-Premises:Enterprise facilities with sub-10ms latency requirements for high-frequency trading and industrial control systems are retaining captive power infrastructure despite higher capital intensity.
- Hybrid:Split architectures with critical workloads on-premises and burst capacity cloud-hosted are standard for financial services and healthcare verticals with mixed compliance obligations.
- Cloud-Based:Fully outsourced power management through hyperscale colocation is capturing new AI training cluster deployments.
- Others:Containerized and edge micro-data center configurations are emerging for 5G infrastructure and autonomous vehicle processing nodes.
On-Premises retains the largest installed base; Hybrid is gaining share fastest as workload portability demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The 2,500-mile UHVDC transmission spine connecting Xinjiang to eastern load centers underwrites China's dominance in hyperscale power infrastructure. Germany's 50Hertz grid interconnectors and the Netherlands' TenneT corridor similarly anchor European data gravity. India's Green Energy Corridor and the United States' ERCOT-Texas interconnection complete the critical backbone quartet.
United States
Hyperscale operators in Northern Virginia's Data Center Alley and Dallas-Fort Worth are commissioning 2N+1 architectures for 100MW+ campuses. EPA Energy Star certification now gates federal procurement pools under Executive Order 14057. Phoenix and Atlanta submarkets are absorbing liquid-cooled retrofits as AI training clusters exceed 50kW per rack.
Germany
Frankfurt's DE-CIX proximity and renewable energy auctions are drawing multi-hundred-megawatt commitments from cloud operators. EU Ecodesign standby loss regulations are eliminating transformer-based UPS from 2023 procurement lists. Bavaria's Ingolstadt and Nuremberg clusters are specifying 96%+ efficient modular architectures.
India
Mumbai's submarine cable landing stations and Chennai's undersea fiber corridors are anchoring hyperscale buildouts for APAC latency optimization. BIS efficiency labeling mandates are creating first-mover certification advantages for vendors with local testing partnerships. Telangana's Hyderabad and Karnataka's Bengaluru are seeing concentrated 2N+1 deployments.
Netherlands
Amsterdam's AMS-IX exchange and North Sea wind interconnectors are sustaining colocation expansion despite moratorium-driven supply constraints. EU Ecodesign tiered limits are forcing UPS redesigns for partial-load efficiency. Eindhoven's Brainport cluster is piloting thermal-electric co-optimization for liquid-cooled AI facilities.
China
Beijing-Tianjin-Hebei's state-backed data center clusters and the Yangtze River Delta's Shanghai-Nanjing corridor are absorbing government-mandated east-west computing resource rebalancing. GB 50174 design standards are tightening PUE enforcement below 1.3 for new builds. Inner Mongolia's renewable-powered campuses are serving as carbon-neutral templates for state-owned operators.
Data Center Power Management Market Competitive Environment
Listed leaders compete with private specialists across certification depth and service bundling. The vendor pool consolidates around three tiers: integrated platform providers with end-to-end hardware-software stacks, component specialists with deep vertical expertise in thermal or power conditioning, and regional system integrators with local commissioning capacity. M&A activity targets ISO 50001-certified energy auditors and liquid-cooled busway fabricators. Geographic expansion into India and Southeast Asia dominates strategic positioning as BIS and local content rules harden.
Within the integrated platform tier, Schneider Electric and Eaton exemplify divergent scale strategies. Schneider anchors European hyperscale contracts through its EcoStruxure architecture. Eaton occupies a position in enterprise segments with captive medium-voltage and UPS production. Among thermal-electric specialists, Vertiv represents the liquid-cooled co-optimization archetype for AI training clusters. Delta Electronics sits within the Taiwan-based power electronics fabricator category with component supply relationships across Asian hyperscale campuses.
| Leading Market Players |
|---|
| Eaton |
| Cyber Power Systems |
| Schneider Electric |
| Cummins |
| Anord Mardix |
| Vertiv |
| Delta Electronics |
| Rosenberger OSI |
| ABB |
| Others |
Value Chain & Pricing Dynamics
Busbar-to-busway architectural substitution in liquid-cooled AI facilities is simultaneously redrawing supplier geography toward German and United States fabricators and compressing installation-cost premiums that once protected legacy raised-floor PDU vendors.
Pricing Analysis
Volume-discount tiering structures stratify across hyperscale megawatt commitments, enterprise retrofit bundles, and spot procurement for edge micro-data centers. Price differentiation hinges on ISO 50001 certification depth and EPA Energy Star verification tier, with uncertified vendors excluded from federal pools entirely. Pricing pressure stems from copper commodity volatility eroding switchgear margins. Hyperscale operators exhibit lowest price sensitivity due to total-cost-of-ownership framing; edge deployment buyers face acute capital constraints.
Supply Chain Analysis
Just-in-time inventory strategies dominate UPS and PDU procurement for hyperscale campuses with predictable deployment cadences, while strategic copper and rare-earth stockpiling characterizes switchgear manufacturers hedging against commodity spikes. Supply concentrates in Germany, the United States, and Taiwan for precision power electronics. Raw material dependencies center on copper cathodes, silicon carbide semiconductors, and transformer-grade electrical steel. Single-source vulnerability in silicon carbide substrates from Wolfspeed and Infineon anchors supply risk. Distribution runs through authorized system integrators with NFPA 70 certification rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as hyperscale capex cycles rebound from post-pandemic normalization, with AI training cluster buildouts providing the demand floor.
For Market Incumbents: Shield core enterprise accounts from modular UPS disruptors by embedding lifecycle energy optimization services with guaranteed PUE outcomes. Deepen backward integration into medium-voltage switchgear to capture margin pool compression from copper volatility. Prioritize ISO 50001 audit capacity expansion to collapse commissioning bottlenecks that delay competitor qualification.
For New Entrants and Emerging Players: Differentiate on liquid-cooled busway thermal-electric co-optimization for 50kW-plus rack densities where Vertiv and Schneider Electric hold incumbency but capacity-constrained delivery creates white space. Target India's BIS efficiency labeling pre-certification window ahead of mandatory adoption deadlines. Pursue joint commissioning partnerships with local electrical contractors in Telangana and Karnataka to bypass ISO 50001 assessor backlogs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional system integrators in Germany and Japan holding captive ISO 50001 auditor relationships and local commissioning licenses. Five-to-ten year viability favors platforms with software-defined power management telemetry rather than pure hardware fabricators. Watch for hyperscale operator direct procurement of busway systems bypassing traditional switchgear vendors as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 50001 Certification Buildout | Creates defensible vendor qualification moats as EPA and EU mandates harden procurement pools. |
| Liquid-Cooled Busway Capacity Expansion | Captures hyperscale retrofit demand as air-cooled architectures collapse under 50kW rack densities. |
| Copper Commodity Hedging Program | Protects switchgear margins against LME price volatility compressing unhedged competitors. |
| DCIM Platform Integration | Displaces siloed vendor monitoring tools with API-accessible telemetry for enterprise sustainability teams. |
| India Local Testing Partnership | Secures BIS efficiency labeling first-mover advantage ahead of mandatory adoption deadlines. |
Study Parameters
Initial hypotheses were tested against primary input from data center facility engineers, hyperscale procurement directors, electrical contractor project managers, and ISO 50001 certification auditors and refined through secondary validation against EPA Energy Star certification databases, EU Ecodesign compliance registries, hyperscaler capital expenditure disclosures, and copper commodity exchange data. Bottom-up equipment shipment tracking was triangulated against top-down facility commissioning permits across the analysis window.
Variance decomposition across technology segments, end-user categories, service types, and deployment models structured the analytical framework. CAGRs were derived from modeled unit economics and replacement cycle assumptions. Key inputs included AI training cluster power density trajectories, BIS and EU Ecodesign regulatory phase-in schedules, and ISO 50001 assessor capacity constraints.
Forecasts assume regulatory continuity in EPA Energy Star, EU Ecodesign, and India BIS regimes; material policy shifts would require re-modeling vendor qualification pools and procurement eligibility. Copper price volatility, assessor backlog duration, and hyperscale capex cycle timing constitute primary revision triggers. Revision becomes warranted when liquid-cooled deployment penetration crosses thresholds that collapse legacy air-cooled replacement demand assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
Smart Water Cooler Market
Energy Management Systems
Energy Management in Data Centers Market
Energy Management Systems
Outage Management System (OMS) Market
Energy Management Systems
North America Energy Management Systems Market
Energy Management Systems
Smart Air Cleaners Market
Energy Management Systems
Building Energy Management Systems (BEMS) Market
Energy Management Systems
AI-Driven Lighting Controls Market
Energy Management Systems
Home Energy Management System Market
Energy Management Systems
Portable Air Cooler Market
Energy Management Systems
Global Thermal Management Technologies Market
Energy Management Systems
Asia-Pacific Home Energy Management System Market
Energy Management Systems
Southeast Asia Cooling Systems Market
Energy Management Systems
Smart Programmable Thermostat Market
Energy Management Systems
Africa Digital Showers Market
Energy Management Systems
Europe Home Energy Management System Market