
 Southeast Asia Cooling Systems Market | 2026-2036
Southeast Asia Cooling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Cooling Systems Market Analytics
Variable refrigerant flow technology is narrowing the efficiency gap between centralized chillers and distributed cooling architectures across Southeast Asia's tropical climates. Danfoss AS leverages its compressor control portfolio to anchor positions in Thailand's commercial retrofit segment. Thermax Limited competes through absorption chiller specialization that matches Indonesia's abundant waste-heat streams from palm oil processing. Alfa Laval AB dominates marine and offshore heat exchanger niches that spill into coastal industrial zones.
Southeast Asia cooling systems encompass engineered thermal management equipment designed to reject waste heat from industrial processes, commercial spaces, and electronic infrastructure, typically operating with refrigerant temperatures between minus forty and plus fifty degrees Celsius and heat transfer coefficients measured in kilowatts per square meter-kelvin. Chillers command the largest installed base across the region's commercial building stock, though data center operators are shifting procurement toward hybrid installation configurations that pair centralized plants with edge-located evaporative cooling to manage tropical humidity loads. Absorption cooling technology leads growth in industrial facilities where onsite cogeneration or biomass combustion yields low-grade thermal energy that would otherwise vent to atmosphere.
Thailand's Ministry of Energy enforces building energy codes that mandate efficiency thresholds for air conditioning systems above specified cooling capacities, while Singapore's National Environment Agency administers refrigerant phase-down schedules aligned with the Kigali Amendment to the Montreal Protocol. Vietnam's Ministry of Construction issues technical standards for centralized HVAC in high-rise developments that increasingly reference ISO 5149 safety requirements for ammonia and carbon dioxide systems. Stakeholders must monitor how Indonesia's planned carbon pricing mechanism treats industrial cooling loads relative to process emissions, as this classification will determine retrofit economics across Java's manufacturing belt.
Market Dynamics
Tropical humidity loads and refrigerant phase-down mandates are forcing simultaneous infrastructure replacement across Southeast Asia's commercial building stock and industrial processing facilities, compressing equipment procurement cycles from fifteen years toward eight.
Growth Catalysts
- Data center capacity expansion:Singapore and Indonesia operators are commissioning facilities faster than legacy cooling infrastructure can support, pulling in modular chiller configurations and edge-located evaporative systems.
- Thailand's Board of Investment incentives:Tax holidays and import duty exemptions for energy-efficient manufacturing equipment are accelerating absorption chiller adoption in food processing and petrochemical plants.
- Vietnam's northern industrial corridor concentration:Samsung and Foxconn supplier parks in Bac Ninh and Thai Nguyen provinces require precision thermal management for semiconductor fabrication, driving demand for variable refrigerant flow systems.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger manufacturing costs fluctuate with London Metal Exchange pricing, squeezing margins for regional equipment fabricators in Malaysia and Thailand.
- Refrigerant supply concentration:Hydrofluorocarbon blending capacity clusters in China and Japan, exposing Southeast Asian service contractors to import dependency and quota allocation uncertainty.
- Ammonia safety code fragmentation:Divergent national standards for industrial refrigeration systems across Indonesia, Vietnam, and the Philippines complicate cross-border project execution and certification reciprocity.
Strategic Opportunities
- Myanmar and Cambodia manufacturing zones:Garment and electronics assembly parks in Yangon and Phnom Penh remain underpenetrated by precision cooling vendors, offering first-mover positioning before supply chain relocation accelerates.
- Waste-heat-to-cooling integration:Palm oil processing, sugar milling, and combined heat and power plants across Indonesia and Thailand generate low-grade thermal streams suitable for absorption chiller retrofits.
- Singapore's Green Mark certification:Building sustainability ratings that weight energy efficiency are creating specification pull for magnetic bearing centrifugal chillers and intelligent building management system integration.
Industry Challenges
- Ammonia refrigeration technician scarcity:Industrial facilities in Indonesia and Vietnam face hiring gaps for certified system operators, delaying project commissioning and inflating training budgets.
- Legacy chiller integration complexity:Hybrid installations pairing centralized plants with distributed cooling architectures require control system harmonization that stretches engineering resources and extends payback calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Cooling Systems Market |
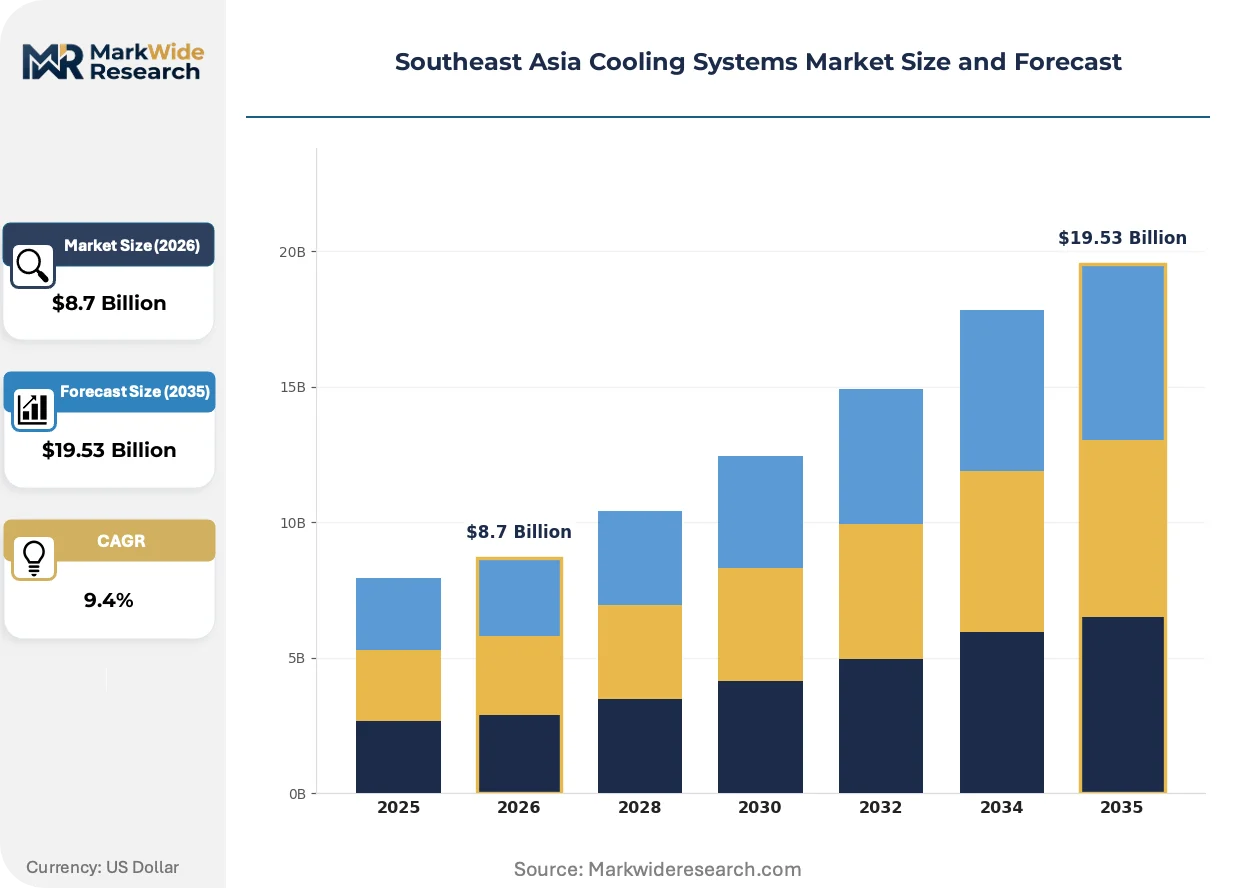
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Condensers, Heat Exchangers, Cooling Towers End User: Commercial Buildings, Industrial Facilities, Residential Properties, Data Centers Technology: Vapor Compression, Absorption Cooling, Evaporative Cooling, Thermoelectric Installation Type: Centralized Systems, Decentralized Systems, Hybrid Systems, Portable Units |
| Companies Covered | Xylem Inc, HRS Heat Exchangers, Danfoss AS, Parker Hannifin Corp, Hydac International GmbH, Thermax Limited, SPX Flow Inc, EJ Bowman, Alfa Laval AB, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Cooling Systems Market Evolving Landscape
Equipment intelligence and refrigerant chemistry are converging to redefine performance benchmarks across Southeast Asia's tropical operating envelope, with implications for maintenance economics and capital planning horizons.
Magnetic bearing compressor technology is collapsing the maintenance cost differential between oil-free centrifugal chillers and conventional lubricated systems. Data center operators in Singapore and Jakarta are specifying these units for twenty-year lifecycle cost advantages despite thirty percent capital premiums. The technology is collapsing traditional service revenue models predicated on scheduled oil changes and bearing replacements.
Singapore's National Environment Agency refrigerant phase-down schedules aligned with the Kigali Amendment are compressing hydrofluorocarbon availability timelines. Industrial facility operators must now budget for retrofit or replacement of R-134a and R-410A systems ahead of original depreciation schedules. Cold storage and food processing plants in Jurong and Tuas industrial estates are responding by piloting ammonia and carbon dioxide cascade systems.
Performance-based cooling service contracts are displacing traditional equipment sale-and-install arrangements in Thailand's commercial building sector. Building owners in Bangkok's central business district now procure guaranteed thermal output per square meter rather than rated chiller capacity, transferring operational risk to equipment vendors and integrators. This model is most visible in hospitality and healthcare verticals where uptime penalties are contractually severe.
Southeast Asia Cooling Systems Market Segmentation
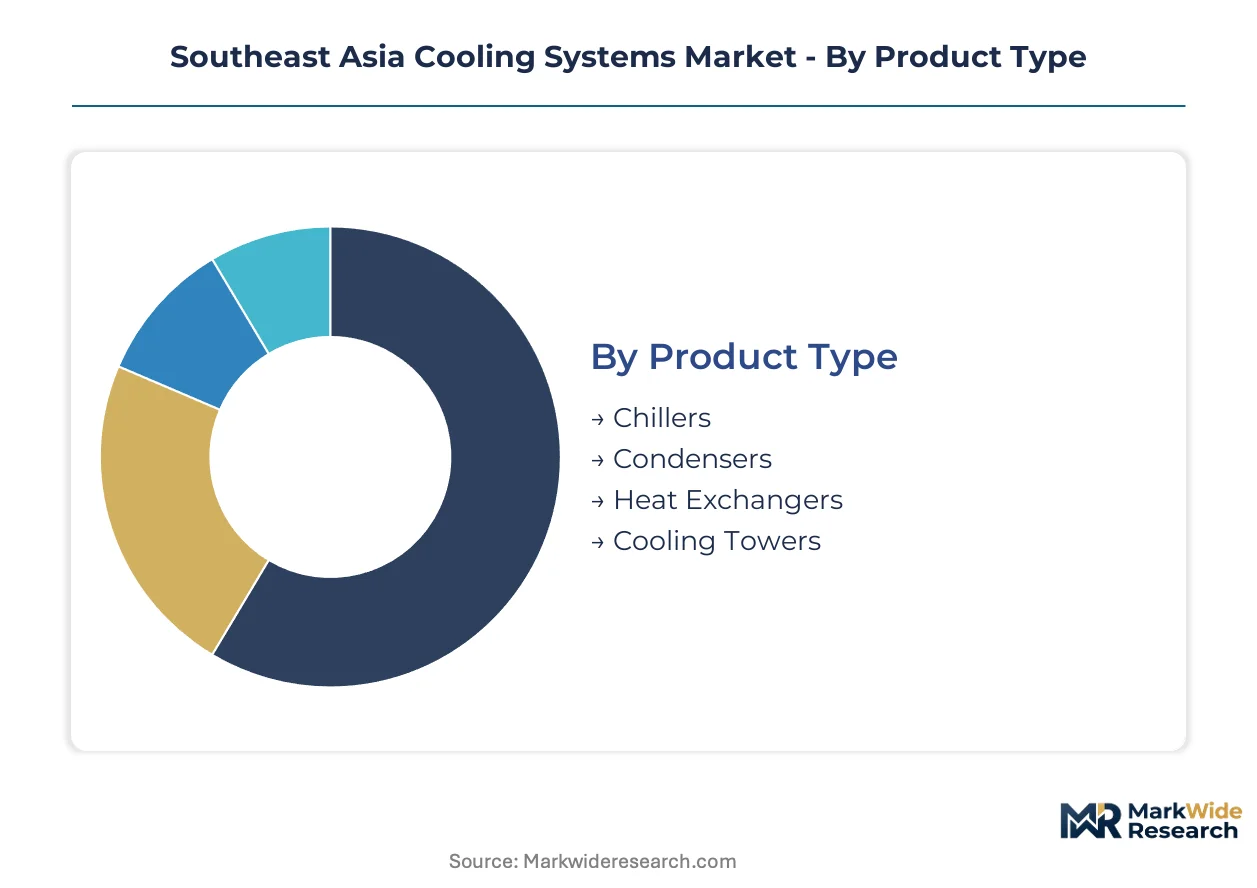
Cooling equipment procurement across Southeast Asia fragments along technical specifications, operational scale, and regulatory exposure. Each segmentation dimension carries distinct margin profiles and vendor specialization patterns that determine competitive positioning.
Product Type:
Equipment category determines capital intensity, maintenance scheduling, and refrigerant handling requirements for tropical climate deployment.
- Chillers:Centralized vapor compression or absorption systems generating chilled water for distribution through building loops. Singapore's data center operators specify magnetic bearing centrifugal units for twenty-year lifecycle economics despite capital premiums. Bac Ninh's electronics fabrication parks in Vietnam drive demand for precision temperature control within plus-or-minus 0.5 degrees Celsius.
- Heat Exchangers:Shell-and-tube or plate configurations transferring thermal energy between process streams without refrigerant phase change. Alfa Laval AB anchors marine and offshore niches that spill into coastal industrial zones across Indonesia and Thailand. Palm oil processing facilities in Sumatra deploy waste-heat recovery exchangers to feed absorption cooling loops.
- Condensers:Air-cooled or water-cooled units rejecting heat from high-pressure refrigerant vapor.
- Cooling Towers:Evaporative heat rejection systems managing condenser water temperatures in large centralized plants.
Chillers command the established base. The steepest expansion runs through heat exchangers.
End User:
Customer verticals impose divergent uptime requirements, efficiency mandates, and refrigerant safety protocols.
- Data Centers:Mission-critical facilities demanding continuous cooling with N-plus-one redundancy configurations. Singapore and Jakarta operators commission capacity faster than legacy infrastructure supports, pulling modular chiller and edge-located evaporative architectures. Tropical humidity loads force hybrid designs pairing centralized plants with distributed cooling.
- Industrial Facilities:Process cooling for petrochemical, food processing, and electronics manufacturing with waste-heat integration opportunities. Thailand's Board of Investment incentives accelerate absorption chiller adoption where cogeneration yields low-grade thermal energy.
- Commercial Buildings:Office, retail, and hospitality HVAC with performance-based service contract displacement of traditional equipment sales.
- Residential Properties:Distributed air conditioning with smaller unitary systems dominating mass-market procurement.
Industrial facilities command the established base. Data centers are climbing the fastest.
Technology:
Refrigerant chemistry and thermodynamic cycle selection determine efficiency curves, maintenance economics, and regulatory compliance timelines.
- Vapor Compression:Mechanical refrigeration cycles dominating commercial and residential applications with hydrofluorocarbon refrigerants. Singapore's National Environment Agency phase-down schedules compress R-134a and R-410A availability, forcing premature retrofit budgeting.
- Absorption Cooling:Thermal-driven cycles using lithium bromide or ammonia-water pairs where waste heat displaces electrical compression. Indonesia's palm oil processing and Thailand's combined heat and power plants generate suitable low-grade thermal streams.
- Evaporative Cooling:Water-based heat rejection managing sensible loads in dry-bulb conditions with lower energy intensity.
- Thermoelectric:Solid-state Peltier cooling for niche precision applications with limited penetration in Southeast Asian climate conditions.
Vapor compression commands the established base. Absorption cooling is gaining share fastest.
Installation Type:
System architecture determines capital deployment patterns, control complexity, and operational flexibility for building operators.
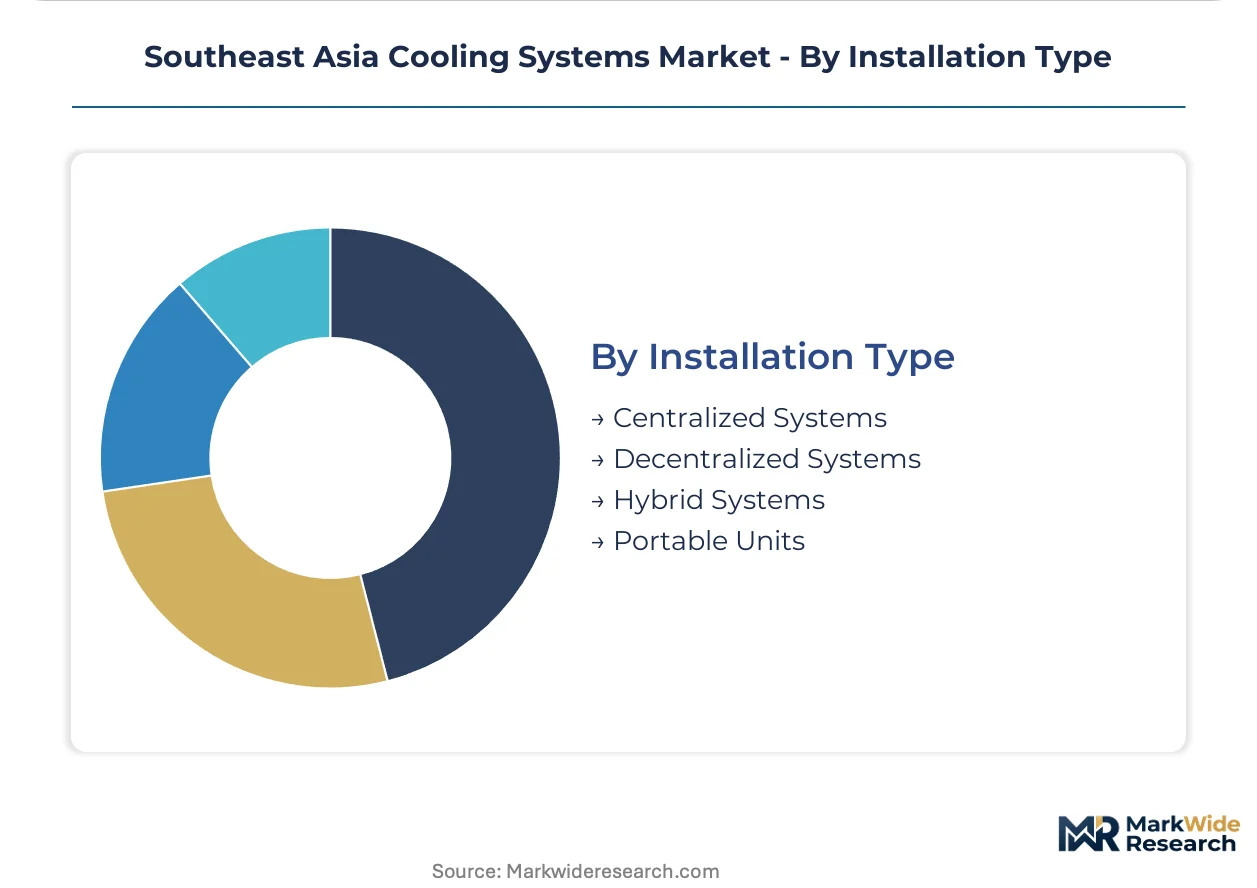
- Hybrid Systems:Configurations pairing centralized chiller plants with edge-located evaporative or direct expansion cooling. Data center operators in Singapore and Indonesia specify these to manage tropical humidity spikes while maintaining efficiency at partial loads. Control system harmonization stretches engineering resources and extends commissioning timelines.
- Centralized Systems:Single-plant designs with chilled water distribution dominating large commercial and industrial campuses. Vietnam's Ministry of Construction technical standards for high-rise developments increasingly reference ISO 5149 safety requirements.
- Decentralized Systems:Multiple smaller units serving zones independently with reduced distribution losses.
- Portable Units:Temporary or supplemental cooling for construction phases, events, or emergency redundancy.
Centralized systems command the established base. Hybrid configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore exports precision cooling equipment to data center operators across Jakarta, Bangkok, and Ho Chi Minh City, establishing a trade corridor that channels technical specifications and procurement standards throughout the lower Mekong and maritime Southeast Asia.
Singapore
Data center capacity expansion and tropical humidity management drive equipment procurement for mission-critical facilities. The National Environment Agency enforces refrigerant phase-down schedules aligned with the Kigali Amendment to the Montreal Protocol. Tuas and Jurong industrial estates host pilot ammonia and carbon dioxide cascade systems for cold storage applications.
Indonesia
Palm oil processing waste streams and combined heat and power generation create thermal energy inputs for absorption cooling retrofits. The planned carbon pricing mechanism will classify industrial cooling loads relative to process emissions, determining retrofit economics. Manufacturing belts across Java face technician scarcity for certified ammonia refrigeration system operators.
Thailand
Food processing and petrochemical plants seek absorption chillers where cogeneration yields low-grade thermal energy. The Board of Investment offers tax holidays and import duty exemptions for energy-efficient manufacturing equipment. Bangkok's central business district building owners now procure performance-based cooling service contracts with guaranteed thermal output per square meter.
Vietnam
Electronics fabrication facilities in Bac Ninh and Thai Nguyen provinces require precision thermal management for semiconductor production. The Ministry of Construction issues technical standards for centralized HVAC in high-rise developments referencing ISO 5149 safety requirements. Samsung and Foxconn supplier parks drive demand for variable refrigerant flow systems with temperature control within plus-or-minus 0.5 degrees Celsius.
Malaysia
Heat exchanger fabricators face margin pressure from copper and aluminum price volatility on the London Metal Exchange. Regional equipment manufacturers concentrate production capacity for export to Indonesian and Thai industrial markets. Coastal industrial zones leverage marine and offshore heat exchanger expertise spilling from adjacent maritime sectors.
Southeast Asia Cooling Systems Market Competitive Landscape
On the supply side, the industry is moderately consolidated around specialized technology portfolios and geographic anchoring positions. European and Indian capital goods conglomerates occupy distinct efficiency and absorption technology niches, while regional fabricators compete on customization and service proximity. Two strategic archetypes dominate: premium-tier technology licensors with magnetic bearing and intelligent control portfolios, and mid-market fabricators with project execution strength in tropical climate adaptation. Dominant competitive moves include technology licensing partnerships for refrigerant transition compliance and backward integration into compressor manufacturing to secure margin control.
Among European-based thermal engineering specialists, Danfoss AS and Alfa Laval AB occupy positions that exemplify divergent specialization paths, while Thermax Limited represents the Indian absorption technology archetype with waste-heat integration capabilities. These three companies anchor distinct competitive vectors: compressor control systems, marine and offshore heat exchange, and industrial thermal energy recovery respectively. Their positioning illustrates how vendor selection in Southeast Asia increasingly hinges on matching specific thermodynamic cycle requirements to onsite energy availability rather than generic efficiency ratings.
| Leading Market Players |
|---|
| Xylem Inc |
| HRS Heat Exchangers |
| Danfoss AS |
| Parker Hannifin Corp |
| Hydac International GmbH |
| Thermax Limited |
| SPX Flow Inc |
| EJ Bowman |
| Alfa Laval AB |
| Others |
Value Network & Pricing Analysis
Singapore-Jakarta freight corridors carry magnetic bearing compressors and absorption chiller components through the Strait of Malacca, where bunker fuel cost spikes and port congestion differentially burden premium-tier equipment shipments against standard-grade alternatives. This logistics architecture concentrates pricing power with vendors controlling compressor manufacturing and refrigerant blending capacity, while downstream buyers in Vietnam's northern industrial provinces absorb delivery premiums for precision thermal management systems.
Pricing Analysis
Conventional lubricated centrifugal chillers, magnetic bearing oil-free units, and emerging ammonia-carbon dioxide cascade systems occupy distinct pricing strata across Southeast Asian procurement. Project-based equipment sales dominate industrial facilities, while performance-based service contracts with guaranteed thermal output per square meter are displacing capital purchases in Thailand's commercial building sector. Price differentiation rests on ISO 5149 certification tier and magnetic bearing technology adoption, with cost compression in standard-grade vapor compression equipment intensifying due to copper and aluminum volatility on the London Metal Exchange. Data center operators demonstrate lowest price sensitivity, prioritizing twenty-year lifecycle economics over capital expenditure, while residential and small commercial buyers remain most responsive to upfront equipment costs.
Supply Chain Analysis
Export control regimes on advanced compressor manufacturing equipment and magnetic bearing technology limit flows from European and Japanese suppliers into Southeast Asian assembly operations. Manufacturing concentration centers on China for hydrofluorocarbon refrigerant blending, Thailand for commercial chiller fabrication, and Singapore for precision data center cooling systems. Raw material dependencies draw from Indonesian nickel processing, Malaysian aluminum smelting, and Chinese rare earth magnet production. Single-source vulnerability runs through hydrofluorocarbon quota allocations controlled by Chinese and Japanese blenders. Distribution runs through authorized dealer networks in Bangkok, Jakarta, and Ho Chi Minh City, with direct OEM engagement for large industrial projects exceeding specified cooling capacities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified ammonia refrigeration technicians remain scarce across Indonesia and Vietnam, constraining commissioning timelines and inflating training budgets for industrial absorption chiller deployments. This capability gap determines competitive outcomes more than equipment efficiency ratings alone.
For Market Incumbents: Insulate service revenue streams against magnetic bearing technology's collapse of scheduled maintenance models by anchoring long-term performance contracts with data center operators in Singapore and Jakarta. Pursue backward integration into compressor manufacturing to secure margin control amid refrigerant phase-down uncertainty. The threat of ammonia safety code fragmentation across Indonesia, Vietnam, and the Philippines demands certification investment in multi-jurisdictional compliance capabilities. For New Entrants and Emerging Players: Establish a beachhead in Myanmar and Cambodia manufacturing zones where garment and electronics assembly parks in Yangon and Phnom Penh remain underpenetrated by precision cooling vendors. Waste-heat-to-cooling integration for palm oil processing facilities in Sumatra offers white-space positioning before supply chain relocation accelerates. A go-to-market angle pairing absorption chiller specialization with onsite cogeneration assessment services addresses Indonesia's abundant low-grade thermal energy streams. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive cooling equipment divisions lacking standalone scale. Long-term viability over a multi-year horizon hinges on refrigerant transition compliance capabilities and magnetic bearing technology access. Acquisition candidates with established technician training pipelines in ammonia refrigeration systems warrant premium positioning. The signal to watch is Indonesia's carbon pricing mechanism classification of industrial cooling loads, which will revalue retrofit economics across Java's manufacturing belt.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Program | Addresses ammonia refrigeration operator scarcity delaying project commissioning in Indonesian industrial zones. |
| Absorption Chiller Specialization | Matches Thailand's Board of Investment incentives for waste-heat integration in food processing plants. |
| Magnetic Bearing Technology Licensing | Secures twenty-year lifecycle cost advantages for Singapore data center operators despite capital premiums. |
| Performance-Based Service Contracts | Transfers operational risk to vendors in Bangkok's central business district commercial buildings. |
| Refrigerant Transition Compliance Investment | Aligns with Singapore National Environment Agency Kigali Amendment phase-down schedules. |
Research Methodology
Desk research of customs trade databases, SEC filings from listed equipment manufacturers, and ASEAN energy agency publications preceded structured interviews with data center facility managers, industrial plant engineers, and commercial building procurement officers across Singapore, Indonesia, Thailand, and Vietnam. Primary fieldwork with absorption chiller service contractors and refrigerant distribution channel partners validated secondary estimates of installed base and replacement cycles. Bottom-up equipment shipment analysis and top-down energy consumption modeling were triangulated against regulatory filing disclosures.
Assumptions held fixed include Singapore's National Environment Agency refrigerant phase-down schedules, Thailand's Board of Investment incentive continuity, and copper-aluminum price bands consistent with recent London Metal Exchange volatility. Segmentation dimensions modeled span product type, end-user vertical, thermodynamic cycle technology, and installation architecture across the analysis window. CAGR derivation incorporated equipment replacement cycle compression from fifteen years toward eight, data center capacity expansion trajectories, and industrial waste-heat availability curves. Forecast inputs included ammonia safety code harmonization progress and magnetic bearing compressor adoption rates in mission-critical facilities.
Stress conditions across refrigerant quota allocation severity, copper price spike magnitude, and carbon pricing mechanism implementation timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and scenario boundaries. Material shifts in Indonesia's cooling load classification under its planned carbon pricing mechanism, or abrupt refrigerant supply disruption from Chinese export controls, would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
IoT Energy Management Market
Energy Management Systems
Airflow Management Market
Energy Management Systems
Smart Programmable Thermostat Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
Outage Management System (OMS) Market
Energy Management Systems
Smart Climate Control Market
Energy Management Systems
Smart HVAC Controls Market
Energy Management Systems
Energy Management Systems (EMS) Market
Energy Management Systems
Smart Cooling Systems Market
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
Saudi Arabia Portable Air Conditioner Market
Energy Management Systems
Mobile Metering System Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
Data Center Power Management Market
Energy Management Systems
Smart Air Cleaners Market
Energy Management Systems
Wi-Fi Smart Thermostat Market