
 AI-Driven Lighting Controls Market | 2026-2036
AI-Driven Lighting Controls Market Size, Share, and Industry Trends Forecast 2026-2036
AI-Driven Lighting Controls Market Insights
Shortage of embedded systems engineers with machine learning deployment experience is collapsing project timelines for intelligent lighting retrofits across North America and Europe. Signify leverages its vertical integration in LED hardware and software stacks to sustain rapid prototyping cycles for neural-network-driven dimming systems. Acuity Brands anchors its competitive stance through deep channel control with electrical distributors serving commercial complexes. Schneider Electric differentiates by extending its EcoStruxure platform into edge-computing lighting nodes that operate independently of cloud connectivity.
AI-driven lighting controls integrate sensor networks, predictive algorithms, and actuation hardware to autonomously modulate illuminance, color temperature, and power draw based on occupancy patterns and daylight availability. These systems typically process data at the edge through embedded processors with sub-100-millisecond response latencies, enabling real-time energy optimization without persistent network dependency. Machine learning platforms currently dominate technology investment as facility managers demand self-optimizing systems that reduce manual commissioning overhead. Commercial complexes represent the most mature application segment with established procurement frameworks, while hospitality venues exhibit the fastest expansion as operators pursue outcome-based energy contracts. Edge computing architectures are capturing margin pools through premium pricing for installations requiring low-latency response and data sovereignty compliance.
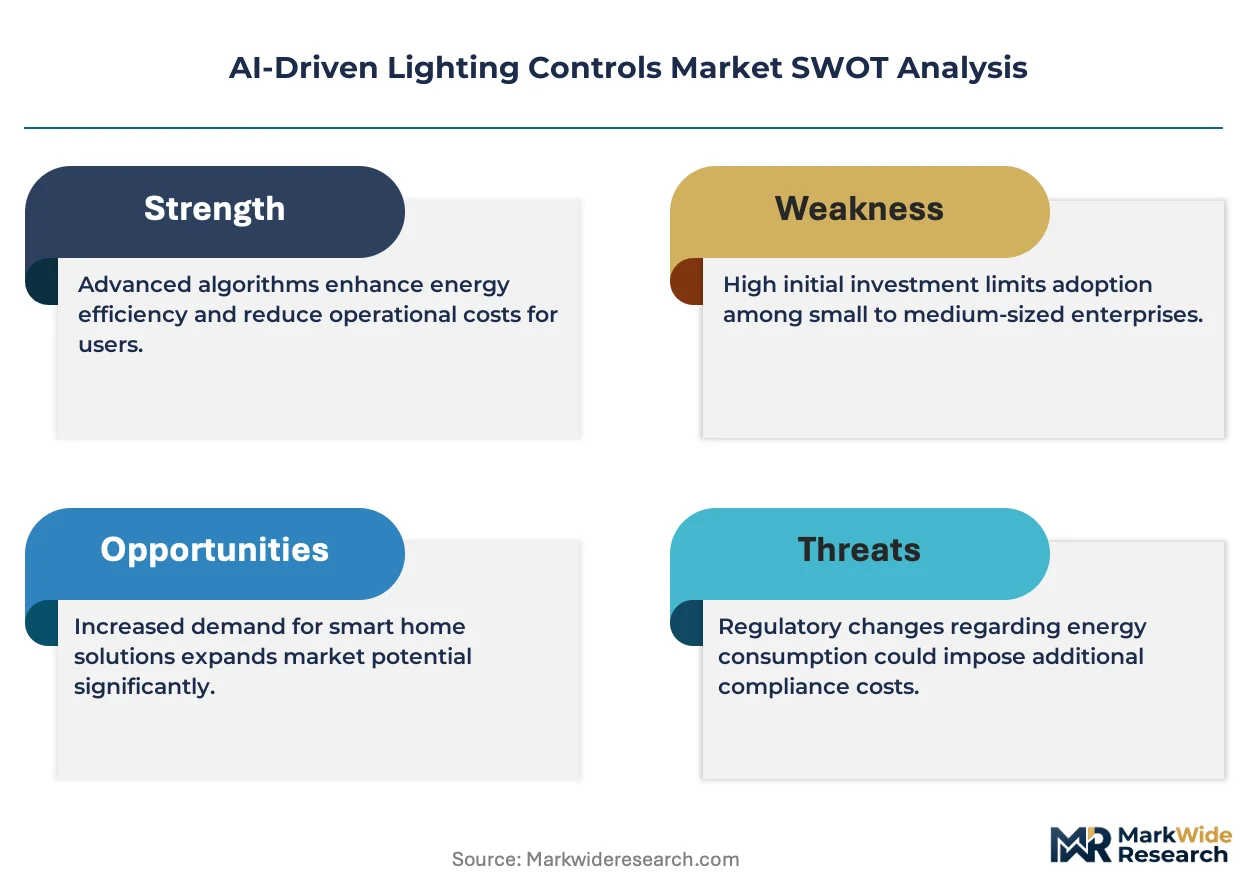
FCC certification requirements govern wireless connectivity modules in US deployments, while the EU Green Deal and Ecodesign regulations mandate minimum efficiency thresholds that only adaptive AI systems reliably achieve. REACH compliance constrains material selections for sensor housings and printed circuit assemblies sold into European commercial projects. Stakeholders must monitor evolving cybersecurity standards for building automation networks as regulatory bodies in multiple jurisdictions draft mandatory encryption protocols for connected infrastructure.
Market Dynamics
Facility managers in commercial complexes now mandate self-optimizing systems that eliminate manual commissioning overhead, compressing deployment timelines and reshaping vendor competitive requirements.
Growth Catalysts
- EU Green Deal building efficiency directives:Mandatory retrofit timelines across member states are accelerating procurement of adaptive AI systems that reliably exceed minimum efficiency thresholds.
- Machine learning platforms:Investment concentrates on edge-computing architectures that process occupancy and daylight data with sub-100-millisecond response latencies.
- German industrial facility upgrades:Concentrated procurement activity from Ecodesign regulation compliance is driving concentrated vendor activity in Central Europe.
Market Restraints
- Embedded systems engineer shortage:Talent scarcity with machine learning deployment experience is collapsing project timelines for intelligent retrofits across North America and Europe.
- Silicon supply concentration:Edge-computing processor fabrication depends on concentrated Asian foundry capacity, exposing lead time volatility for lighting node deployments.
- FCC certification friction:Wireless connectivity module approval requirements in US deployments extend commissioning schedules and increase compliance overhead.
Strategic Opportunities
- Hospitality outcome-based energy contracts:Operators are pursuing performance-guaranteed installations that shift vendor revenue models from hardware sales to energy savings sharing.
- Data sovereignty compliance demand:Edge architectures operating independently of cloud connectivity capture premium pricing from European commercial projects subject to GDPR constraints.
- REACH material constraint innovation:Sensor housing and printed circuit assembly redesigns for European compliance are creating differentiation for compliant component suppliers.
Industry Challenges
- Commissioning complexity with legacy DALI systems:Integration friction between new AI nodes and existing building automation infrastructure extends deployment timelines and requires specialized field engineering.
- Cybersecurity standard evolution:Draft mandatory encryption protocols for connected infrastructure in multiple jurisdictions create certification uncertainty and retrofit risk for installed base systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI-Driven Lighting Controls Market |
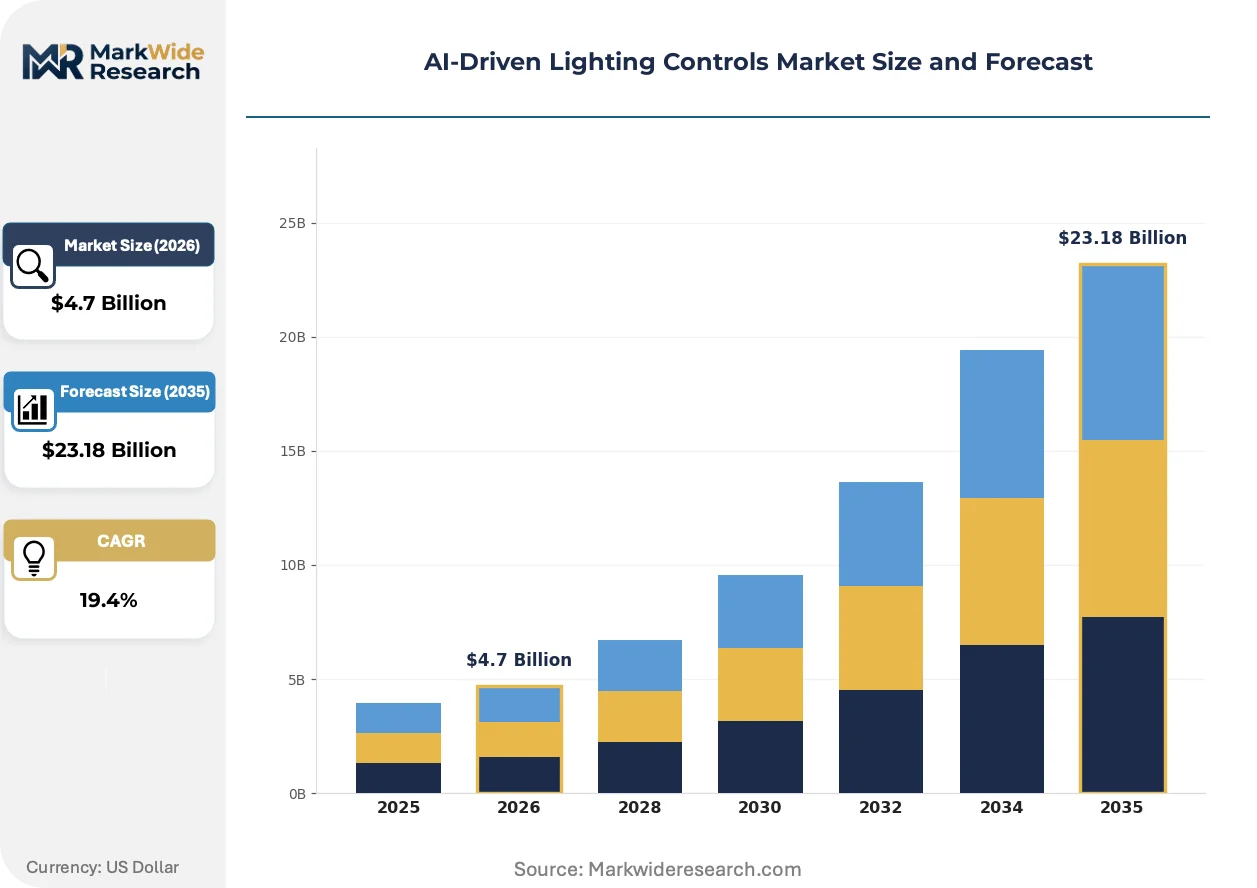
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Switches, Automated Dimmers, Motion Sensors, Ambient Light Sensors, Voice-Controlled Systems Technology: Machine Learning, Neural Networks, Computer Vision, Edge Computing, Cloud Integration Application: Commercial Complexes, Educational Institutions, Warehouses, Public Spaces, Hospitality Venues End User: Facility Managers, Property Developers, Energy Consultants, Building Automation Providers, Lighting Designers |
| Companies Covered | Signify, Acuity Brands, Schneider Electric, Honeywell International, Lutron Electronics, Legrand, Zumtobel Group, ams OSRAM, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-Driven Lighting Controls Market Trends and Innovations
Neural-network-driven dimming systems are fragmenting traditional lighting control architectures. Vendors now compete on edge-computing response latency rather than hardware luminaire margins.
Edge AI inference engines are decomposing centralized building management system hierarchies. Facility managers in Class A office towers are deploying distributed neural processing nodes that autonomously modulate illuminance without persistent network dependency. This decomposition compresses infrastructure requirements and eliminates single-point-of-failure vulnerabilities in mission-critical installations.
Ecodesign regulations under the EU Green Deal are mandating adaptive efficiency thresholds that static control systems cannot achieve. Industrial facility operators in Germany must retrofit with self-optimizing systems or face operational restrictions. Lighting vendors are accelerating firmware development cycles to maintain compliance certification currency across member state implementations.
Electrical distributor channel control is fragmenting as facility managers engage directly with platform vendors for outcome-based energy contracts. Hospitality operators in Spain and Italy now prioritize performance guarantees over hardware procurement, displacing traditional specification-bid-build workflows. This behavioral shift concentrates vendor selection authority with energy service companies rather than traditional electrical contractors.
AI-Driven Lighting Controls Market Segmentation
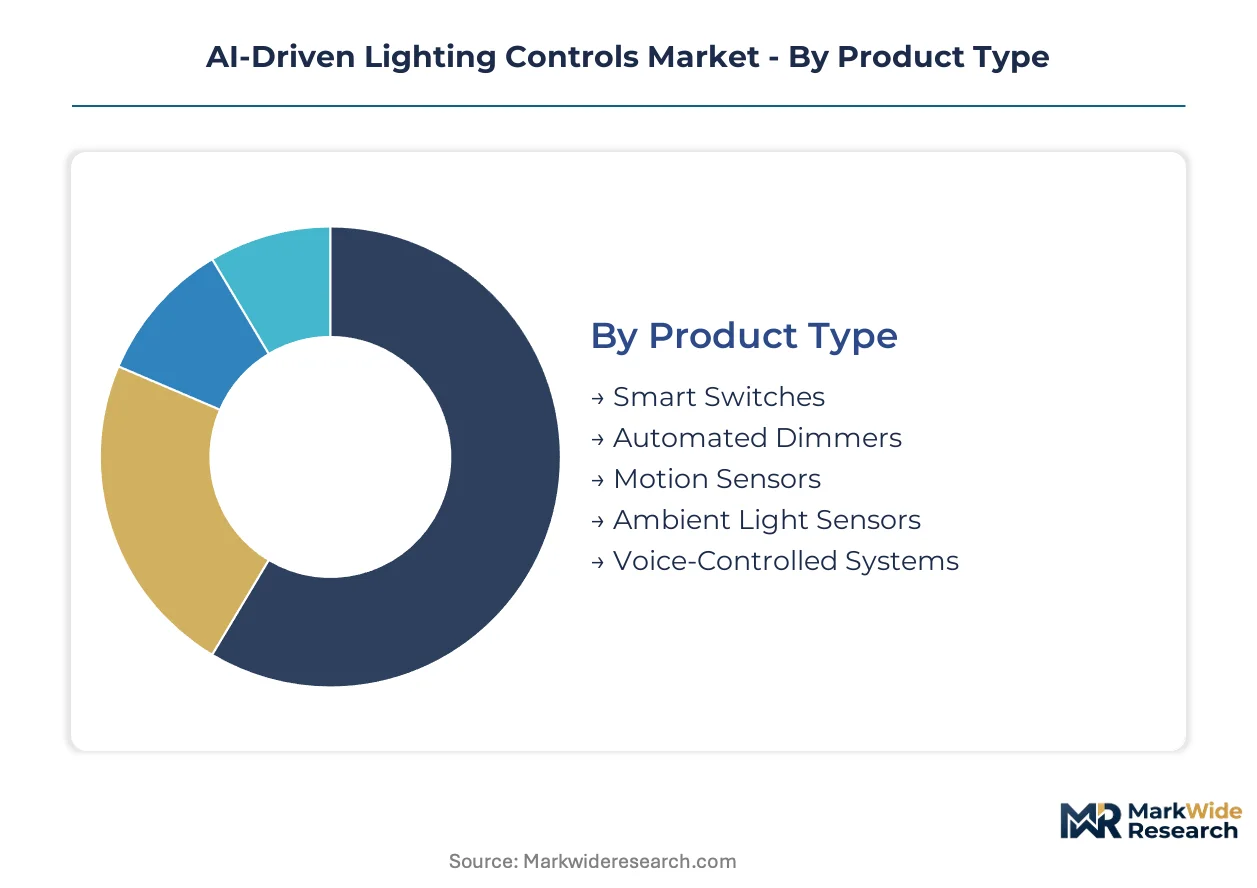
Channel configuration in AI-driven lighting controls varies sharply by segment, with electrical distributors dominating hardware procurement while energy service companies capture outcome-based software contracts. Understanding these pathway divergences enables vendors to align R&D investment with actual purchasing authority.
Product Type:
Smart switches and automated dimmers flow primarily through electrical distributor networks serving retrofit contractors, while sensor-heavy configurations increasingly route through building automation integrators.
- Smart Switches:Wall-mounted control interfaces with embedded microprocessors enabling programmable scene selection and remote override capabilities. Demand clusters in German commercial retrofits where Ecodesign compliance mandates replace legacy toggle installations. FCC certification requirements for wireless variants extend lead times for US distributor stocking programs.
- Automated Dimmers:Silicon-controlled rectifier and trailing-edge modulation circuits adjust voltage waveforms to modulate luminous flux without color shift. Hospitality operators in Spain and Italy specify these for outcome-based energy contracts that guarantee percentage savings against baseline consumption. Neural-network-driven variants command premium positioning through self-optimizing calibration.
- Motion Sensors:Passive infrared and microwave occupancy detectors trigger illuminance adjustments with configurable timeout intervals. Warehouse operators deploy these for aisle-specific lighting zones.
- Ambient Light Sensors:Photodiode arrays measure daylight contribution to maintain target luminance levels through continuous dimming. Educational institutions prioritize these for classroom glare reduction.
- Voice-Controlled Systems:Natural language processing modules integrated with building management platforms enable hands-free scene activation. Property developers specify these for premium residential-adjacent commercial projects.
Smart switches dominate installed base. Voice-controlled systems are where expansion concentrates fastest.
Technology:
Cost tier separation is pronounced, with edge computing architectures commanding hardware premiums while cloud-dependent platforms compete on subscription pricing.
- Machine Learning:Supervised and reinforcement learning algorithms optimize dimming schedules against historical occupancy patterns and energy pricing signals. Facility managers in commercial complexes mandate these platforms to eliminate manual commissioning overhead. GDPR constraints in European deployments favor on-device training rather than cloud-based model refinement.
- Neural Networks:Deep learning architectures with convolutional and recurrent layers process multi-sensor inputs for predictive illuminance modulation. German industrial facilities deploy these to meet adaptive efficiency thresholds under EU Green Deal Ecodesign regulations that static systems cannot achieve. Edge inference engines enable sub-100-millisecond response latencies.
- Computer Vision:Camera-based occupancy detection and activity recognition enable granular zone control without physical sensor proliferation. Privacy regulations constrain deployment in European public spaces.
- Edge Computing:Distributed processing nodes execute AI inference locally without persistent network dependency. Data sovereignty compliance requirements drive specification in European commercial projects.
- Cloud Integration:Centralized platforms aggregate fleet-wide performance data for benchmarking and remote diagnostics. Energy consultants favor these for portfolio-level analytics.
Machine learning platforms anchor current revenue. Edge computing architectures are climbing the fastest as data sovereignty mandates harden.
Application:
Volume concentration varies by maturity, with commercial complexes representing established procurement frameworks while hospitality venues exhibit steepest expansion trajectory.
- Commercial Complexes:Class A office towers and mixed-use developments deploy integrated sensor networks with centralized management dashboards. Procurement flows through established electrical distributor relationships controlled by Acuity Brands and similar incumbents. Self-optimizing systems reduce facilities staffing requirements.
- Hospitality Venues:Hotels and conference centers pursue performance-guaranteed installations shifting vendor revenue from hardware sales to energy savings sharing. Operators in Spain and Italy now prioritize guarantees over specification-bid-build workflows, fragmenting traditional channel control. Direct platform vendor engagement displaces electrical contractor intermediation.
- Educational Institutions:K-12 and university facilities prioritize circadian lighting schedules and glare control for student performance. Budget constraints favor phased retrofit approaches.
- Warehouses:High-bay storage facilities implement aisle-specific occupancy detection with rapid ramp rates for safety compliance. LED high-bay retrofits create bundled control opportunities.
- Public Spaces:Municipal streetlighting and transit hubs require cybersecurity-hardened architectures with encrypted command protocols. Draft mandatory encryption standards create certification uncertainty.
Commercial complexes dominate installed base. Hospitality venues are gaining share fastest through outcome-based contracting.
End User:
Customer type determines specification authority, with facility managers holding direct procurement power for retrofits while property developers delegate to building automation providers for new construction.
- Facility Managers:Operating personnel with direct budget accountability for energy expenditure and maintenance staffing. These stakeholders mandate self-optimizing systems that compress deployment timelines and reduce manual intervention. German industrial facility managers face operational restrictions without Ecodesign-compliant adaptive controls.
- Property Developers:New construction sponsors specifying systems during design phase for tenant lease-up advantages. Green building certification requirements drive AI control specification for energy performance targets.
- Energy Consultants:Third-party advisors conducting feasibility studies and measurement-and-verification protocols for utility incentive programs. These intermediaries influence vendor selection through savings guarantee structuring.
- Building Automation Providers:System integrators combining lighting controls with HVAC and security platforms. Legacy DALI integration friction extends their deployment timelines.
- Lighting Designers:Architectural specification professionals balancing aesthetic scene programming with energy compliance. These stakeholders resist fully autonomous systems that override manual scene selection.
Facility managers dominate retrofit procurement authority. Energy consultants are expanding influence fastest through performance contracting growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial facility operators command 15-20% pricing premiums for Ecodesign-compliant adaptive systems, while US commercial retrofits absorb 8-12% cost penalties from FCC certification friction. This asymmetry reshapes vendor capacity allocation and firmware development priorities.
Germany
Industrial facility upgrades in Baden-Württemberg and North Rhine-Westphalia concentrate procurement for Ecodesign-compliant neural-network dimming systems. The EU Green Deal mandates adaptive efficiency thresholds that static controls cannot achieve, forcing retrofit timelines by 2030. Munich and Stuttgart industrial clusters are driving concentrated vendor activity for edge-computing lighting nodes.
United States
Class A office towers in Manhattan and Chicago mandate self-optimizing systems to eliminate manual commissioning overhead. FCC certification requirements for wireless connectivity modules extend commissioning schedules and increase compliance overhead. The Inflation Reduction Act's building efficiency tax credits are accelerating retrofit demand across commercial complexes in Texas and California.
France
Hospitality operators in Paris and Lyon pursue outcome-based energy contracts that shift vendor revenue from hardware sales to energy savings sharing. The CNIL's GDPR enforcement creates specification preference for edge architectures operating independently of cloud connectivity. Île-de-France commercial developments are specifying data-sovereign lighting controls for premium tenant lease-up.
Italy
Hotel and conference center retrofits in Milan and Rome fragment traditional electrical distributor channel control through direct platform vendor engagement. EU Green Deal building efficiency directives accelerate procurement of adaptive AI systems. Northern Italy's industrial automation corridor is integrating lighting controls with existing building management infrastructure.
United Kingdom
London commercial landlords specify edge-computing lighting nodes to comply with evolving cybersecurity standards for building automation networks. The UK's net-zero building regulations mandate efficiency thresholds achievable only through machine learning platforms. The Southeast England property development cluster is prioritizing circadian lighting schedules for tenant wellness certifications.
AI-Driven Lighting Controls Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with edge-computing specialists commanding hardware premiums while cloud-dependent platforms compete on subscription pricing. The vendor base organizes around three strategic archetypes: vertically integrated LED-hardware incumbents, building-automation platform extenders, and edge-A inference engine specialists. Dominant competitive moves include firmware acceleration cycles to maintain compliance certification currency and strategic partnerships with energy service companies for outcome-based contract structuring.
Among vertically integrated hardware-software stacks, Signify and Acuity Brands exemplify archetypes sustaining rapid prototyping cycles through captive supply of LED components and deep channel control with electrical distributors. Schneider Electric occupies a position as a building-automation platform extender, leveraging its EcoStruxure infrastructure into distributed processing nodes. These three anchors represent contrasting approaches to the fragmentation of traditional specification-bid-build workflows across European and North American commercial complexes.
| Leading Market Players |
|---|
| Signify |
| Acuity Brands |
| Schneider Electric |
| Honeywell International |
| Lutron Electronics |
| Legrand |
| Zumtobel Group |
| ams OSRAM |
| Eaton |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide substrate substitution for legacy silicon edge-computing processors is redrawing foundry geography toward Japanese and US fabrication capacity while compressing hardware margins through premium material costs. This input shift simultaneously fragments legacy Asian supply dominance and forces tiered pricing stratification based on processor architecture rather than luminaire hardware.
Pricing Analysis
German industrial buyers absorb 15-20% premiums for Ecodesign-certified adaptive systems, while US commercial retrofits face 8-12% cost penalties from FCC certification overhead. Three-tier pricing structure across premium edge-computing nodes, standard cloud-dependent platforms, and economy-grade sensor-only configurations dominates procurement frameworks. Pricing pressure stems from outcome-based contract proliferation in hospitality, where energy savings guarantees compress upfront hardware margins. Facility managers in commercial complexes exhibit lowest price sensitivity due to mandate-driven procurement timelines, while educational institutions face acute budget constraints favoring phased retrofit approaches.
Supply Chain Analysis
Inventory buffers for edge-computing processors collapsed during recent foundry allocation cycles, extending lead times for lighting node deployments. Taiwan, South Korea, and Japan anchor semiconductor fabrication for AI inference engines, while China dominates printed circuit assembly and sensor housing production. Raw material dependencies center on rare earth elements for photodiode arrays, copper for power management circuits, and specialized polymers REACH-compliant for European markets. Single-source vulnerability concentrates in 7nm and below processor nodes. Distribution runs through electrical distributor networks for hardware procurement, with building automation integrators capturing sensor-heavy configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Outcome-based energy contracts are expanding service-attach revenue faster than hardware sales, as hospitality operators shift vendor relationships toward performance-guaranteed installations with recurring savings-sharing layers.
For Market Incumbents: Shield installed base relationships from direct platform vendor engagement by accelerating firmware certification cycles for EU Green Deal compliance. Deepen captive supply of edge-computing processors through strategic foundry partnerships in Japan and the US, reducing exposure to Taiwan concentration risk. Reinforce electrical distributor channel control with exclusive outcome-based contract structuring tools that fragment energy service company intermediation. For New Entrants and Emerging Players: Commissioning support gaps for legacy DALI integration represent the most penetrable service layer, as facility managers collapse project timelines without specialized field engineering. Target hospitality venues in Southern Europe through direct engagement for performance-guaranteed installations, bypassing fragmented electrical contractor specification authority. Position through energy consultant partnerships for measurement-and-verification protocol structuring. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed edge-AI inference engine specialists holding government cybersecurity certification but lacking luminaire hardware integration. Five-to-ten year viability hinges on firmware development velocity for evolving Ecodesign mandates across EU member states. Watch for draft mandatory encryption protocol finalization as inflection indicator for compliance-premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Certification Acceleration | Maintains Ecodesign compliance currency across German industrial retrofit mandates. |
| Foundry Partnership Structuring | Secures processor allocation for edge-computing nodes outside Taiwan concentration risk. |
| Energy Service Company Alliance | Captures outcome-based contract revenue sharing in hospitality outcome-guarantee proliferation. |
| Legacy DALI Integration Tooling | Reduces commissioning friction for building automation integrator channel penetration. |
| Cybersecurity Hardening Investment | Positions for draft mandatory encryption standards in public space deployments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with facility managers, electrical distributor procurement leads, building automation integrators, and energy service company contract structuring specialists. Secondary validation drew from FCC equipment authorization databases, EU Ecodesign implementing measure texts, REACH substance restriction updates, and SEC 10-K filings from listed lighting controls vendors. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for construction and building efficiency investment.
Across the analysis window, the analytical framework modeled volume and value trajectories by product type, technology architecture, application vertical, and end-user procurement authority. CAGRs were derived from segment-level growth rate blending with technology substitution curves. Key forecast inputs included EU Green Deal retrofit timeline enforcement, FCC certification queue dynamics, and edge-computing processor foundry allocation patterns.
Forecasts assume regulatory continuity in EU Ecodesign and US FCC regimes; material policy shifts would require re-modeling. Cybersecurity standard evolution and silicon supply concentration represent primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
IoT Energy Management Market
Energy Management Systems
Shared Power Bank Market
Energy Management Systems
Global Personal Cooling Device Market
Energy Management Systems
Global Smart Air Conditioning Market
Energy Management Systems
Home Energy Management System Market
Energy Management Systems
Mobile Metering System Market
Energy Management Systems
Wi-Fi Smart Thermostat Market
Energy Management Systems
Meter Data Management System Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
Global Data Center Energy Management Solution Market
Energy Management Systems
Chemical Control Systems Market
Energy Management Systems
Evaporative Air Cooler Market
Energy Management Systems
Europe Home Energy Management System Market
Energy Management Systems
Grid Optimization Solution Market
Energy Management Systems
District Cooling Market
Energy Management Systems
Smart Air Cleaners Market