
 Chemical Control Systems Market | 2026-2036
Chemical Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Control Systems Market Analytics
A shortage of certified process control engineers is unwinding capacity expansion timelines across North American chemical corridors. Honeywell International Inc. leverages its distributed control system heritage to anchor long-term service contracts with Gulf Coast refiners. Yokogawa Electric Corporation specializes in precision instrumentation for batch chemical processes, sustaining premium positioning in Japanese and Southeast Asian facilities.
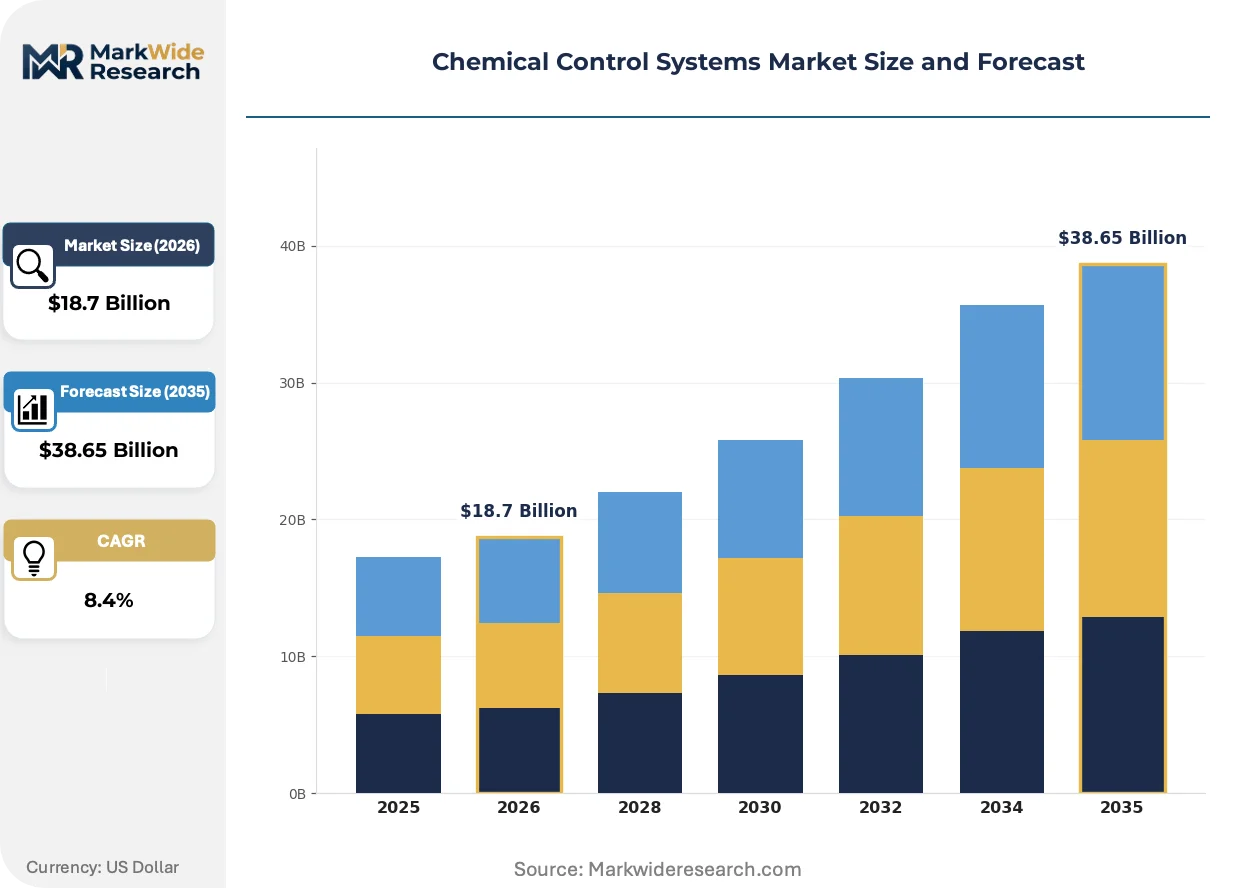
Chemical control systems encompass the integrated hardware and software architectures that regulate temperature, pressure, flow rate, and chemical composition within industrial processing environments, typically operating through sensor arrays, programmable logic controllers, and human-machine interfaces executing closed-loop feedback algorithms. These systems serve the primary commercial purpose of maintaining product uniformity, preventing hazardous deviations, and optimizing raw material conversion efficiency. Process control software captures disproportionate margin pools as recurring licensing revenue, while IoT Solutions represents the fastest-expanding technology dimension driven by edge computing deployments. Safety Monitoring applications dominate capital allocation among petrochemical operators, though Environmental Management is gaining share as discharge regulations tighten.
The EPA enforces process safety management standards that mandate layered protection analyses, directly shaping control system procurement specifications for US chemical facilities. ECHA's REACH compliance obligations and the EU Green Deal carbon accounting frameworks are accelerating European demand for emissions-integrated control architectures. China's MEE enforces real-time pollution monitoring protocols that require domestic chemical producers to retrofit legacy distributed control systems with networked sensor platforms. Stakeholders must weigh the capital requirements of cybersecurity-hardened architectures against the operational risk of maintaining legacy interfaces in an era of escalating industrial threat surfaces.
Market Dynamics
The chemical control systems market is experiencing structural pressure from the convergence of EPA process safety mandates and the operational imperative to retrofit aging distributed control architectures with edge-enabled monitoring platforms across Gulf Coast and Rhine corridor facilities.
Growth Catalysts
- Water treatment infrastructure:Municipal utilities across Germany and the Netherlands are deploying automated chemical dosing systems to meet tightening EU discharge standards. This creates pull-through demand for integrated sensor networks.
- EPA process safety directives:Layered protection analysis requirements are compelling US petrochemical facilities to upgrade legacy safety instrumented systems. Compliance deadlines are accelerating procurement cycles.
- Edge computing architectures:Real-time analytics at the process layer are reducing latency for critical control loops. Batch chemical manufacturers in Japan are piloting these deployments for precision temperature management.
Market Restraints
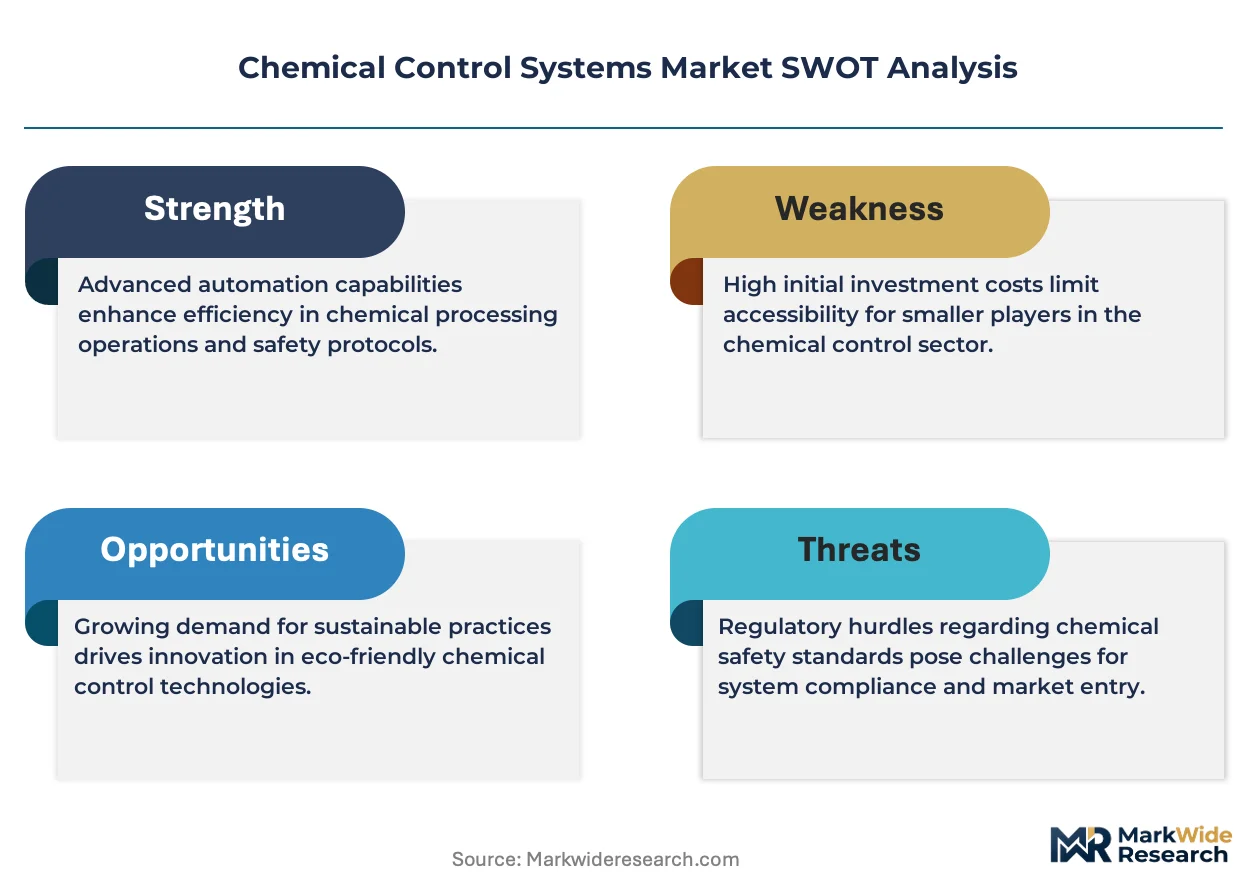
- Specialized engineering talent scarcity:Certified process control engineers command premium compensation. This input cost volatility extends project timelines by 8-14 months across North American corridors.
- Legacy system interdependency:Proprietary communication protocols in 1990s-era distributed control systems create technical lock-in. Replacement requires parallel operational infrastructure.
- Cybersecurity hardening costs:NIST framework compliance for industrial control systems adds 15-25% to total installed cost. Small and mid-scale chemical processors defer upgrades.
Strategic Opportunities
- Carbon-integrated control architectures:EU Green Deal carbon accounting frameworks are creating demand for emissions-monitoring modules. German chemical clusters along the Rhine represent immediate addressable need.
- India's chemical corridor expansion:Gujarat and Maharashtra state industrial zones are greenfield developments. These facilities specify modern control systems without legacy migration burden.
- Digital twin convergence:Physics-based process simulation merged with live operational data enables predictive maintenance. Specialty chemical batch producers are early adopters.
Industry Challenges
- Integration complexity with proprietary legacy interfaces:Fieldbus protocol fragmentation between Honeywell, Yokogawa, and Siemens ecosystems forces custom middleware development.
- Functional safety certification timelines:IEC 61511 compliance documentation for safety instrumented systems requires 18-24 months. This delays revenue recognition for system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Control Systems Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Control Systems, Process Control Software, Instrumentation, Monitoring Devices End Use Industry: Chemicals, Petrochemicals, Pharmaceuticals, Water Treatment Technology: SCADA, DCS, PLC, IoT Solutions Application: Safety Monitoring, Environmental Management, Quality Control, Process Optimization |
| Companies Covered | Siemens AG, ABB Ltd., Honeywell International Inc., Rockwell Automation Inc., Schneider Electric SE, Emerson Electric Co., Yokogawa Electric Corporation, Mitsubishi Electric Corporation, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Control Systems Market Evolving Landscape
Control system architectures are splitting between cloud-native platforms for enterprise analytics and hardened edge nodes for millisecond-loop process control. This technological divergence is reshaping vendor competitive boundaries and customer procurement evaluation criteria.
Edge-native control hardware is bifurcating the market between latency-critical process loops and supervisory optimization layers. Specialty chemical manufacturers in Japan are deploying deterministic edge controllers for batch reactor temperature management. This technology compression is eroding the traditional hierarchical distinction between distributed control systems and programmable logic controllers.
REACH compliance obligations and the EU Green Deal carbon accounting frameworks are mandating emissions-integrated process monitoring. European chemical producers must retrofit control systems with continuous emissions verification modules. Petrochemical operators in Germany's industrial corridor are prioritizing capital allocation toward environmental management applications.
Service contract unbundling is fragmenting the traditional bundled hardware-software-maintenance model. Gulf Coast refiners are separating control system procurement from long-term service agreements. This purchasing pattern shift is most visible among independent refiners seeking operational flexibility.
Chemical Control Systems Market Segmentation
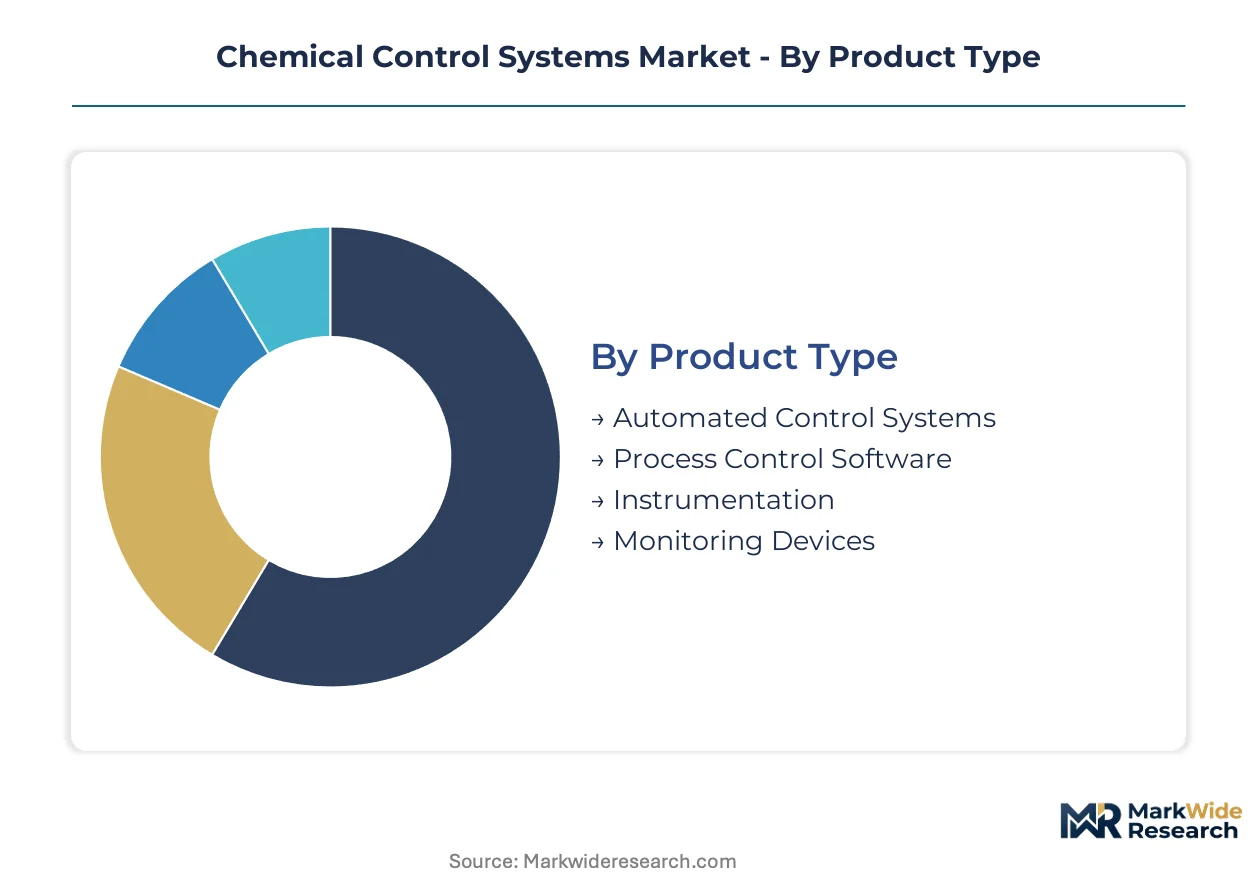
Chemical control systems fragment across hardware, software, and service layers that face divergent procurement cycles and margin structures. Regulatory mandates from EPA, ECHA, and China's MEE create asymmetric pull across these segments, with compliance deadlines concentrating demand in specific technology categories.
Product Type:
EPA process safety management standards and ECHA REACH obligations impose distinct technical requirements on each product category, shaping vendor R&D allocation and certification timelines.
- Automated Control Systems:Integrated hardware architectures combining sensors, controllers, and actuators execute closed-loop regulation of temperature, pressure, and flow. Gulf Coast refiners are retrofitting these systems to meet EPA layered protection analysis mandates, though cybersecurity hardening adds substantial installed cost premiums.
- Process Control Software:Licensing platforms for supervisory control, data historian functions, and operator interface management capture recurring revenue streams. Batch chemical manufacturers in Japan's specialty chemical corridor prioritize these solutions for precision reactor management, with cloud-native deployments gaining traction among newer facilities.
- Instrumentation:Field devices measuring pressure, temperature, level, and analytical parameters.
- Monitoring Devices:Standalone sensors and data acquisition units for emissions and safety verification.
Automated control systems handle the majority of throughput; process control software is climbing the fastest on share.
End Use Industry:
Capital allocation intensity varies dramatically across these verticals, with petrochemical operators commanding the largest individual project scale while water treatment utilities drive volume through distributed municipal deployments.
- Petrochemicals:Olefins, aromatics, and polymer production facilities operate continuous processes requiring millisecond-loop response times. German operators along the Rhine corridor are prioritizing emissions-integrated architectures to satisfy EU Green Deal carbon accounting requirements.
- Chemicals:Specialty and commodity chemical producers span batch and continuous operations. India's Gujarat chemical corridor represents greenfield demand without legacy migration burden, specifying modern distributed control architectures from project inception.
- Pharmaceuticals:FDA-regulated facilities demand validated control systems with full batch record integrity.
- Water Treatment:Municipal utilities across Germany and the Netherlands deploy automated chemical dosing to meet tightening EU discharge standards.
Petrochemicals concentrates the largest individual project value; water treatment is expanding most quickly on unit volume.
Technology:
Edge computing convergence is collapsing traditional hierarchical boundaries between these technology categories, with latency requirements determining deployment architecture rather than historical functional separation.
- DCS:Distributed control systems coordinate multi-variable process regulation across integrated production units. Gulf Coast refiners maintain long-term service relationships with incumbent vendors, though unbundling trends are separating hardware procurement from maintenance contracts.
- IoT Solutions:Networked sensor platforms and cloud analytics enable predictive maintenance and remote monitoring. China's MEE real-time pollution monitoring protocols are compelling domestic chemical producers to retrofit legacy systems with these networked architectures.
- SCADA:Supervisory control and data acquisition for geographically dispersed assets.
- PLC:Programmable logic controllers for discrete manufacturing and auxiliary process functions.
DCS retains the installed base majority; IoT solutions is gaining share fastest among new deployments.
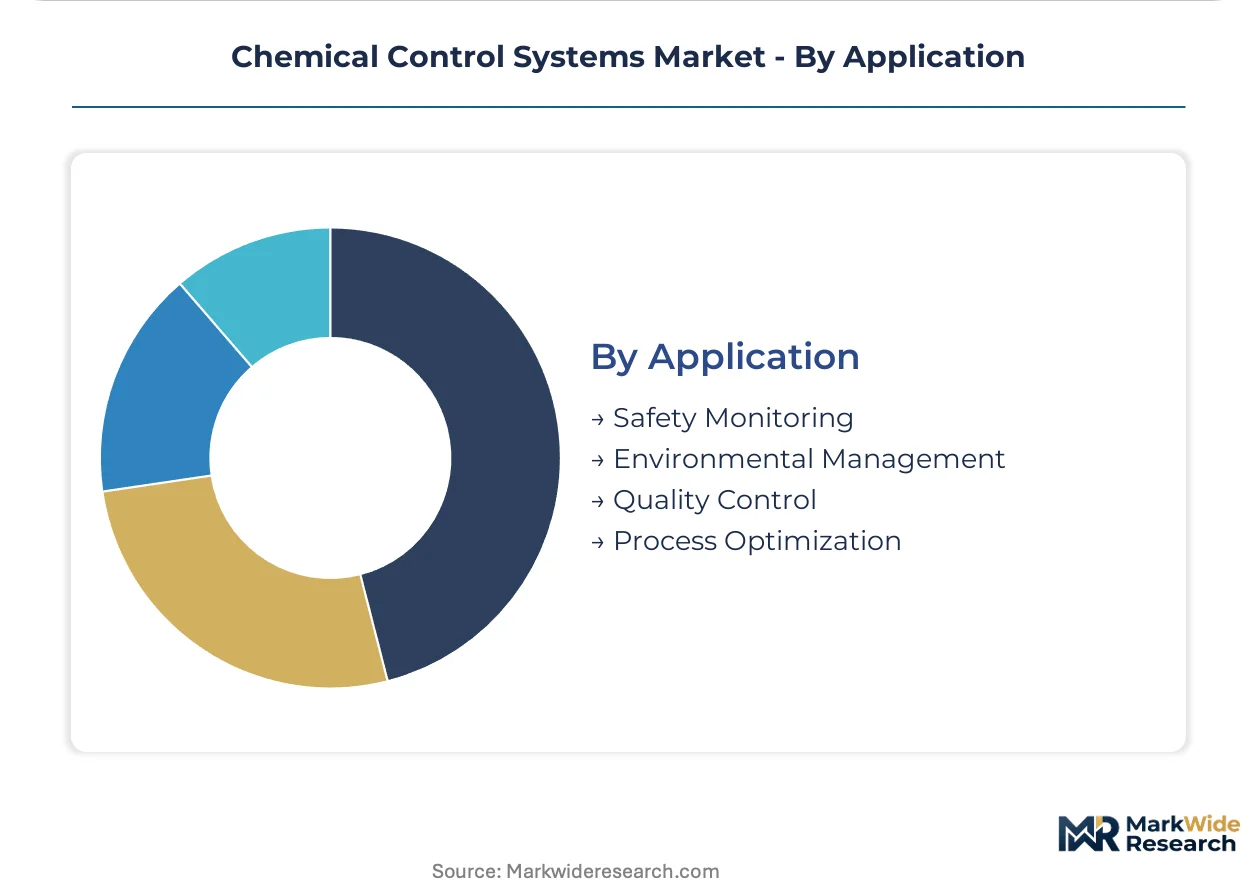
Application:
Functional safety certification under IEC 61511 creates divergent compliance burdens across these application areas, with safety instrumented systems facing the most rigorous documentation and validation requirements.
- Safety Monitoring:Safety instrumented systems and emergency shutdown functions prevent hazardous deviations. Petrochemical operators allocate disproportionate capital here, with EPA process safety management standards mandating layered protection analyses that directly specify procurement requirements.
- Environmental Management:Emissions monitoring, effluent treatment control, and carbon accounting integration. German chemical clusters are prioritizing this application category as ECHA REACH compliance and EU Green Deal frameworks tighten discharge verification obligations.
- Quality Control:In-process analytical verification and batch consistency management.
- Process Optimization:Advanced process control and real-time optimization for yield improvement.
Safety monitoring commands the largest capital allocation; environmental management is the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA process safety management standards anchor demand in the United States, while ECHA REACH obligations and China's MEE pollution monitoring protocols create parallel regulatory pull across three distinct industrial corridors.
United States
Gulf Coast petrochemical complexes drive retrofit demand for safety instrumented systems. EPA layered protection analysis mandates compel facility upgrades before compliance deadlines. Houston and Corpus Christi refiners unbundle hardware procurement from long-term service contracts.
Germany
Rhine corridor chemical clusters prioritize emissions-integrated control architectures. EU Green Deal carbon accounting frameworks require continuous verification modules. BASF and Bayer facilities in Ludwigshafen and Leverkusen allocate capital toward environmental management applications.
China
Domestic chemical producers retrofit legacy distributed control systems with networked sensor platforms. MEE real-time pollution monitoring protocols mandate edge-enabled monitoring infrastructure. Yangtze River Delta petrochemical complexes pilot IoT-enabled predictive maintenance systems.
India
Gujarat and Maharashtra state industrial zones specify modern control systems for greenfield developments. PLI scheme incentives support domestic manufacturing capacity without legacy migration burden. Dahej and Mundra chemical corridors attract integrated DCS-IoT deployments from project inception.
Japan
Specialty chemical manufacturers deploy deterministic edge controllers for batch reactor precision management. METI industrial digitalization frameworks accelerate edge computing pilots. Osaka and Nagoya facilities sustain premium positioning for precision instrumentation.
Chemical Control Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Incumbent European and American conglomerates anchor long-term service relationships with Gulf Coast and Rhine corridor facilities. Mid-scale specialists concentrate on batch process precision for pharmaceutical and specialty chemical verticals. Competitive moves center on unbundling service contracts from hardware procurement and carbon-integrated module development.
Within the diversified industrial conglomerate tier, Siemens AG and ABB Ltd. exemplify archetypes spanning automation hardware through digitalization software, while Yokogawa Electric Corporation occupies a position representing precision instrumentation specialization for batch chemical processes. Honeywell International Inc. anchors the legacy DCS service contract model that Gulf Coast refiners are now unbundling. These three entities collectively represent the competitive tension between bundled long-term relationships and modular procurement patterns reshaping vendor-customer dynamics.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd. |
| Honeywell International Inc. |
| Rockwell Automation Inc. |
| Schneider Electric SE |
| Emerson Electric Co. |
| Yokogawa Electric Corporation |
| Mitsubishi Electric Corporation |
| Omron Corporation |
| Others |
Value Network & Pricing Analysis
IEC 61511 functional safety certification gates both supplier qualification and price tiering simultaneously, forcing buyers to pay substantial premiums for validated safety instrumented systems while limiting the vendor pool to certified integrators. This regulatory barrier concentrates pricing power among incumbent DCS providers serving Gulf Coast and Rhine corridor facilities.
Pricing Analysis
German chemical clusters pay 20-35% premiums over Indian greenfield projects for equivalent DCS hardware due to legacy migration complexity and EU certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates safety-critical petrochemical applications from municipal water treatment deployments. Cost compression in the standard tier is intensifying because Yokogawa and Honeywell are unbundling service contracts to capture independent refiner accounts. Municipal utilities exhibit the highest price sensitivity, while petrochemical operators prioritize compliance assurance over procurement cost.
Supply Chain Analysis
Germany and Japan anchor precision instrumentation manufacturing for batch chemical applications, while China dominates edge computing hardware and networked sensor platform assembly. Controller hardware draws from Taiwanese semiconductor foundries, specialized pressure transmitter components from Swiss and US sources, and enclosure systems from Mexican and Polish fabricators. Single-source vulnerability concentrates in safety instrumented system microprocessors qualified to IEC 61508. Distribution runs through authorized system integrators who bundle installation with long-term maintenance agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chemical control systems market sits in early-cycle expansion as EPA compliance deadlines and EU carbon accounting mandates force simultaneous replacement of aging DCS architectures across multiple industrial corridors. Edge computing adoption in Japanese batch facilities signals penetration acceleration ahead.
For Market Incumbents: Secure long-term service contract renewals with Gulf Coast refiners before unbundling trends fragment maintenance revenue streams. Deepen backward integration into cybersecurity-hardened controller manufacturing to defend margin position against modular procurement patterns. Prioritize IEC 61511 certification pipeline investments to maintain qualification barriers against emerging IoT-native competitors. For New Entrants and Emerging Players: Carbon accounting module integration represents a service-layer gap where Siemens and ABB under-serve mid-scale European chemical producers. Target India's Gujarat corridor greenfield developments specifying modern DCS-IoT architectures without legacy migration burden. Pursue direct OEM partnerships with edge computing hardware vendors to bypass incumbent channel control. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial automation specialists holding EPA-compliant safety system portfolios. The five-to-ten year viability window favors targets with recurring software licensing revenue over hardware-dependent business models. Watch for MEE enforcement intensity in China's Yangtze River Delta as the inflection signal for networked sensor platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Edge Computing Hardware | Reduces controller cost exposure for DCS vendors serving price-sensitive Indian greenfield projects. |
| Carbon-Integrated Module Development | Captures EU Green Deal compliance spending from BASF and Bayer facilities along the Rhine corridor. |
| Service Contract Unbundling | Enables independent Gulf Coast refiners to separate hardware procurement from maintenance agreements. |
| Cybersecurity Certification Investment | Meets NIST framework requirements that currently defer upgrades among small-scale chemical processors. |
| Digital Twin Platform Integration | Supports predictive maintenance pilots at Japanese specialty chemical batch manufacturing facilities. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers, procurement leads at petrochemical operators, DCS system integrators, and EPA compliance officers and refined through secondary validation. Trade data from customs authorities, ACC and Cefic industry reports, SEC 10-K automation disclosures, and MEE pollution monitoring protocol documents provided demand-side triangulation. Bottom-up project pipeline analysis across Gulf Coast, Rhine corridor, and Gujarat facilities converged with top-down industrial automation spend estimates.
Variance decomposition across the projection horizon isolates regulatory compliance deadlines, greenfield development cycles, and technology substitution rates as primary demand drivers. Segmentation modeling spans hardware-software-service layers, end-use verticals from petrochemicals to water treatment, and regional regulatory clusters spanning EPA, ECHA, and MEE jurisdictions. CAGRs derive from unit deployment projections weighted by average system value and service attachment rates, with edge computing penetration curves calibrated against Japanese METI digitalization framework adoption timelines.
Forecasts assume regulatory continuity in EPA process safety management, ECHA REACH obligations, and MEE real-time monitoring mandates; material policy shifts would require re-modeling compliance-driven procurement cycles. Supply chain disruption from semiconductor allocation constraints or fieldbus protocol standardization delays represents specific revision risks. Recalibration cycles align with material shifts in enforcement intensity across environmental regulators and adoption inflections in edge-native control architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Europe Advanced Distribution Management System Market
Energy Management Systems
Global Vibration Control System Market
Energy Management Systems
Peltier Chillers Market
Energy Management Systems
Shared Power Bank Market
Energy Management Systems
Smart HVAC Controls Market
Energy Management Systems
Outage Management System (OMS) Market
Energy Management Systems
Evaporative Air Cooler Market
Energy Management Systems
Cooling Management System Market
Energy Management Systems
North America Energy Management Systems Market
Energy Management Systems
Mobile Metering System Market
Energy Management Systems
Grid Operations Management Software Market
Energy Management Systems
Meter Data Management System Market
Energy Management Systems
Data Center Power Management Market
Energy Management Systems
Grid Optimization Solution Market
Energy Management Systems
USA and Canada Portable Air Conditioner Market
Energy Management Systems
AI Water Heater Market