
 IoT Smart Gas Meter Market | 2026-2036
IoT Smart Gas Meter Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Smart Gas Meter Market Insights
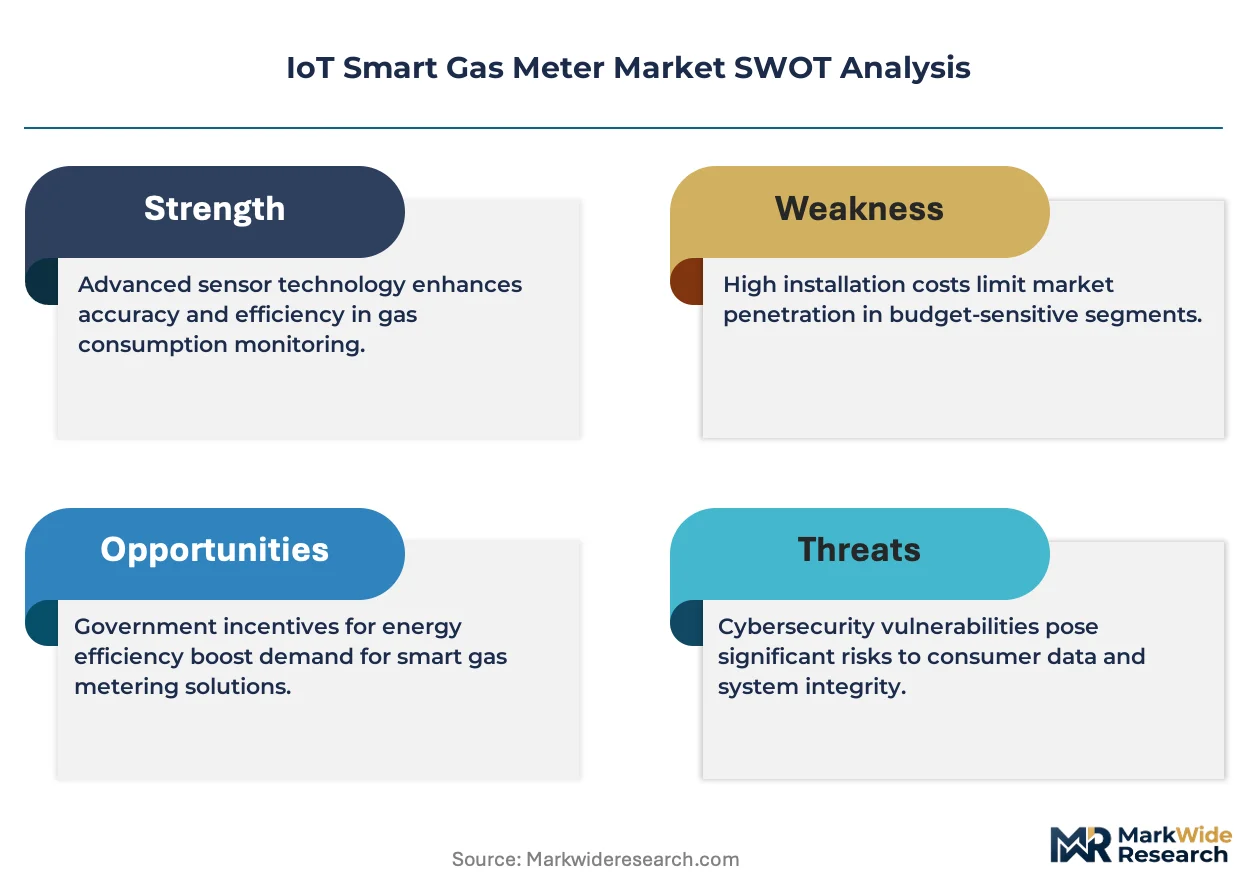
Asset-light leasing and meter-as-a-service financing is tilting competitive dynamics toward vendors with balance-sheet capacity to carry long-dated receivables. Itron Inc. leverages its North American installed base to bundle connectivity with cloud analytics, while Landis+Gyr anchors European tenders through deep utility relationships and local manufacturing scale. Honeywell International Inc. competes on integrated safety sensor architectures that extend beyond basic volumetric measurement into leak detection.
An IoT smart gas meter is a network-connected device that measures natural gas consumption through ultrasonic time-of-flight or diaphragm displacement principles, transmitting data via embedded radio modules for remote billing, demand forecasting, and anomaly detection. Residential Meters dominate unit volume across most installed bases, though Industrial Meters command substantially higher per-unit margins and faster replacement cycles due to custody-transfer accuracy requirements. NB-IoT and LoRaWAN currently split the technology landscape, with cellular gaining ground where utilities already operate under carrier-managed service agreements.
The EU F-Gas Regulation and CE marking under the MDR framework shape product design cycles for any meter containing pressure or temperature sensors, while the EPA in the United States enforces methane leak detection standards that drive demand for integrated sensor arrays. In China, GB standards issued by SAMR mandate communication protocol interoperability, reducing vendor lock-in but compressing differentiation windows. Stakeholders must monitor which regulatory jurisdiction tightens telemetry or cybersecurity requirements first, as compliance investment will concentrate in that geography and cascade through global supply chains.
Market Dynamics
AMI infrastructure mandates across China, Germany, and the United States are compressing replacement cycles for legacy diaphragm meters while ultrasonic time-of-flight sensors displace mechanical measurement cores. Utilities now bundle connectivity with predictive maintenance software, reshaping vendor economics toward recurring revenue streams.
Growth Catalysts
- EU F-Gas Regulation phase-down:Municipal operators in Germany and France must replace mechanical meters with connected units to meet refrigerant containment targets, accelerating tender volumes for ultrasonic diaphragm hybrids.
- China SAMR protocol interoperability:GB standards mandating open communication frameworks reduce vendor lock-in, enabling smaller meter manufacturers to compete on hardware cost while sourcing radio modules from third parties.
- Ultrasonic time-of-flight adoption:Pipeline operators in the United States favor solid-state measurement for custody-transfer accuracy, eliminating mechanical wear points and extending calibration intervals beyond ten years.
Market Restraints
- Semiconductor input volatility:Embedded NB-IoT and LoRaWAN radio modules depend on constrained foundry capacity in Taiwan and South Korea, exposing meter OEMs to 26-week lead time swings.
- CE marking under MDR framework:Pressure and temperature sensor integration triggers medical-device-grade documentation requirements, extending European product certification timelines by eight to fourteen months.
- Legacy mechanical meter residual value:Eastern European utilities delay AMI rollout where existing diaphragm units retain fifteen to twenty years of certified service life, compressing near-term replacement demand.
Strategic Opportunities
- Industrial leak detection convergence:Integration of methane sensors with volumetric measurement creates bundled safety offerings for chemical plants and LNG terminals seeking EPA compliance.
- Meter-as-a-service financing:Asset-light leasing models allow municipal utilities to convert capex to opex, opening procurement to vendors with balance-sheet capacity for long-dated receivables.
- India city gas distribution expansion:PNGRB pipeline licensing for 300+ districts mandates smart metering for compressed natural gas and piped natural gas connections, creating greenfield deployment volume.
Industry Challenges
- Cybersecurity certification fragmentation:Divergent national standards for radio module encryption—FCC Part 15 in the United States, ETSI EN 303 645 in Europe, MIIT requirements in China—force parallel testing programs.
- Legacy billing system integration:Utilities operating 1990s-era customer information systems face API incompatibility with cloud-native AMI headends, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Smart Gas Meter Market |
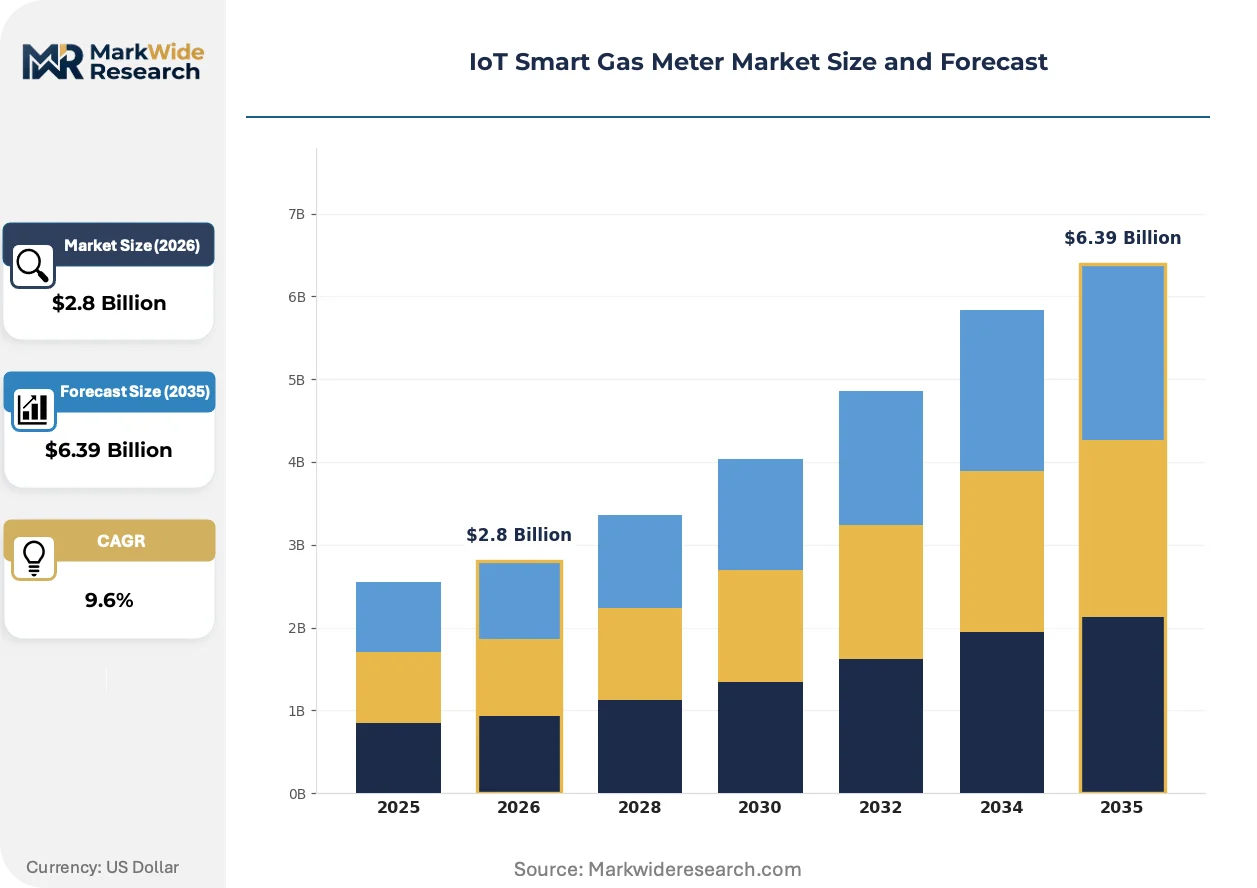
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.39 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Meters, Commercial Meters, Industrial Meters, Portable Meters Technology: LoRaWAN, NB-IoT, Zigbee, Cellular End User: Utilities, Service Providers, Homeowners, Industrial Operators Installation: Retrofit, New Installation, Smart City Projects, Pilot Programs |
| Companies Covered | Itron Inc., Landis+Gyr, Honeywell International Inc., Diehl Stiftung & Co. KG, Apator S.A., Sensus (Xylem Inc.), Siemens, ABB, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Smart Gas Meter Market Trends and Innovations
Edge computing architectures are migrating anomaly detection from centralized servers to meter-mounted processors, reducing latency for leak alerts while compressing data transmission costs. This shift redefines hardware specifications and firmware development priorities across the supply base.
Ultrasonic time-of-flight measurement is digitizing gas consumption tracking by eliminating mechanical diaphragm displacement entirely. Residential utilities in Germany and the Netherlands are specifying solid-state cores for all new tenders, drawn by zero moving parts and temperature-compensated accuracy. This technology is digitizing field service economics by removing periodic mechanical inspection requirements and enabling purely remote calibration verification.
The EPA's methane leak detection standards are forcing sensor array integration into industrial meter form factors. Pipeline operators must now demonstrate continuous emissions monitoring rather than periodic manual surveys, driving demand for multi-parameter devices. Custody-transfer meters in the Permian Basin and Appalachian shale plays are most affected, with operators specifying integrated pressure-temperature-flow-leak quadruple sensing.
Utility procurement teams are unbundling hardware purchase from connectivity management, sourcing radio modules and cloud platforms separately from meter mechanicals. This pattern fragments vendor relationships and opens opportunities for specialized connectivity providers. The behavior is most visible in the United Kingdom and Australia, whereOfgem and AEMO regulatory frameworks encourage competitive separation of network assets from retail operations.
IoT Smart Gas Meter Market Segmentation
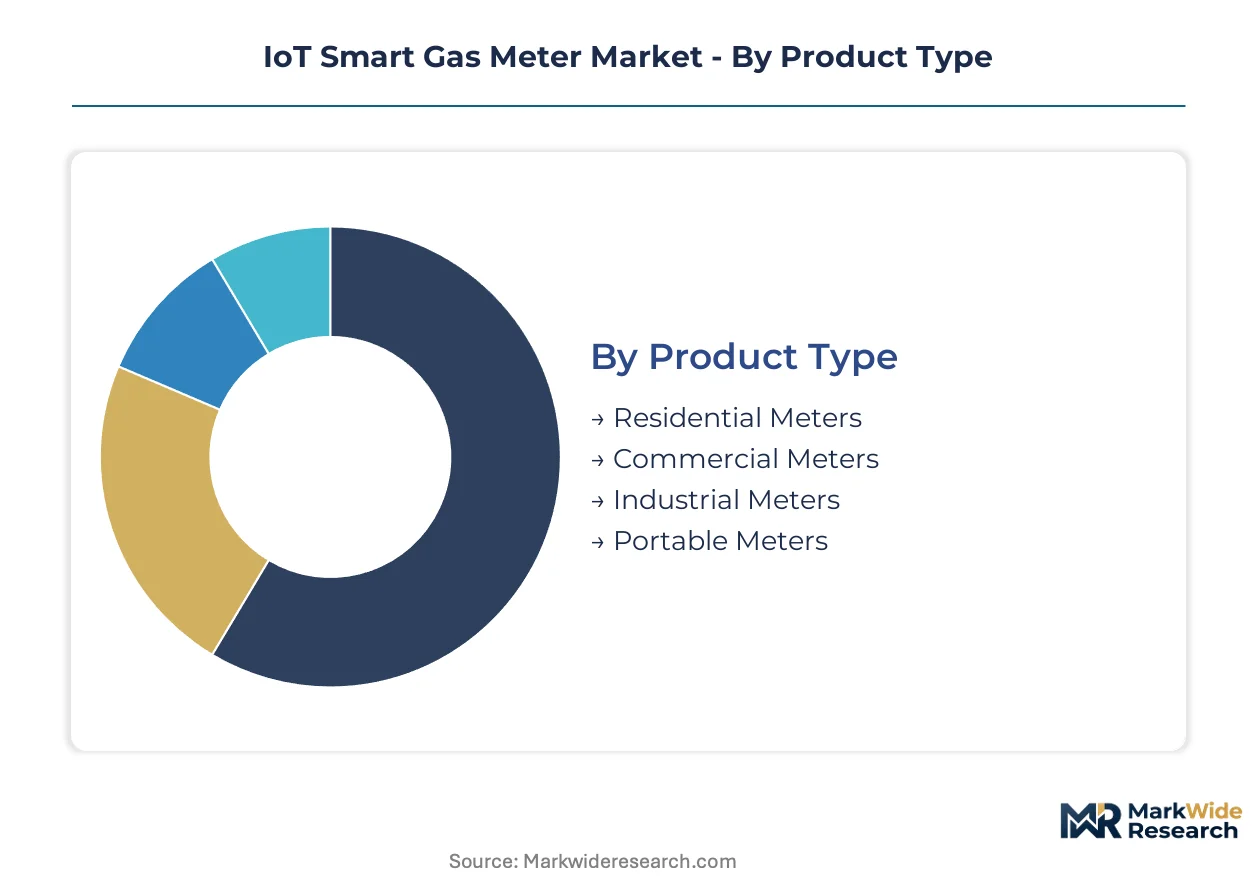
Segmentation in the IoT smart gas meter market reveals distinct procurement patterns across utility scale, communication topology, and deployment maturity. Each dimension carries divergent margin profiles, certification burdens, and replacement cycle timing that reshape vendor go-to-market priorities.
Product Type:
Residential units dominate unit shipments while industrial configurations command premium pricing through custody-transfer precision requirements.
- Residential Meters:Diaphragm-based and ultrasonic time-of-flight designs measure sub-6 m³/hour flow rates for single-family and multi-tenant dwellings. Municipal utilities in Germany and China specify these for mass AMI rollouts where per-unit cost sensitivity constrains specification. The EU F-Gas Regulation accelerates replacement timelines where refrigerant containment sensors integrate with volumetric measurement.
- Industrial Meters:Solid-state ultrasonic cores achieve ±0.5% accuracy for pipeline custody transfer and chemical plant feedstock monitoring. Operators in the United States Permian Basin demand integrated pressure-temperature-leak quadruple sensing to satisfy EPA methane detection mandates. These units cycle faster due to continuous-duty wear and regulatory recertification intervals.
- Commercial Meters:Mid-range flow capacity serves retail chains, hospitals, and educational campuses with monthly telemetry rather than real-time streaming.
- Portable Meters:Battery-powered verification units calibrate installed bases during field audits and dispute resolution.
The dominant share belongs to Residential Meters, while Industrial Meters is closing the gap fastest.
Technology:
Radio module selection determines carrier relationships, firmware certification paths, and data transmission economics across deployment geographies.
- NB-IoT:Narrowband cellular protocols leverage existing mobile infrastructure for deep indoor penetration in urban Chinese and European deployments. SAMR GB standards in China mandate interoperability, reducing module vendor lock-in while extending certification timelines for firmware updates.
- LoRaWAN:Unlicensed spectrum operation suits utilities with private network ambitions or rural coverage gaps where cellular density remains thin. German municipal operators favor this topology for grid-segment isolation and reduced carrier dependency.
- Cellular:Full LTE-M and 5G modules support high-frequency telemetry for industrial leak detection where latency thresholds measure in seconds.
- Zigbee:Mesh networking integrates with home energy management systems for consumer-facing demand response programs.
NB-IoT captures the largest installed base, yet LoRaWAN is expanding most quickly among European utilities seeking operational autonomy.
End User:
Procurement authority concentrates with network asset owners, though financing innovation fragments decision-making across balance sheets.
- Utilities:Municipal gas distributors and national pipeline operators specify meter hardware, AMI headends, and long-term service agreements. German Stadtwerke and Chinese city gas companies currently drive tender volumes through state-mandated replacement programs.
- Industrial Operators:Chemical plants and LNG terminals purchase custody-transfer meters directly, prioritizing integrated safety sensing over connectivity subscriptions.
- Service Providers:Meter-as-a-service financiers carry hardware assets on their balance sheets, converting utility capex to opex.
- Homeowners:Individual procurement remains rare except in deregulated retail markets with consumer choice mandates.
Utilities retain the dominant procurement role, while Service Providers are climbing the fastest as financing models proliferate.
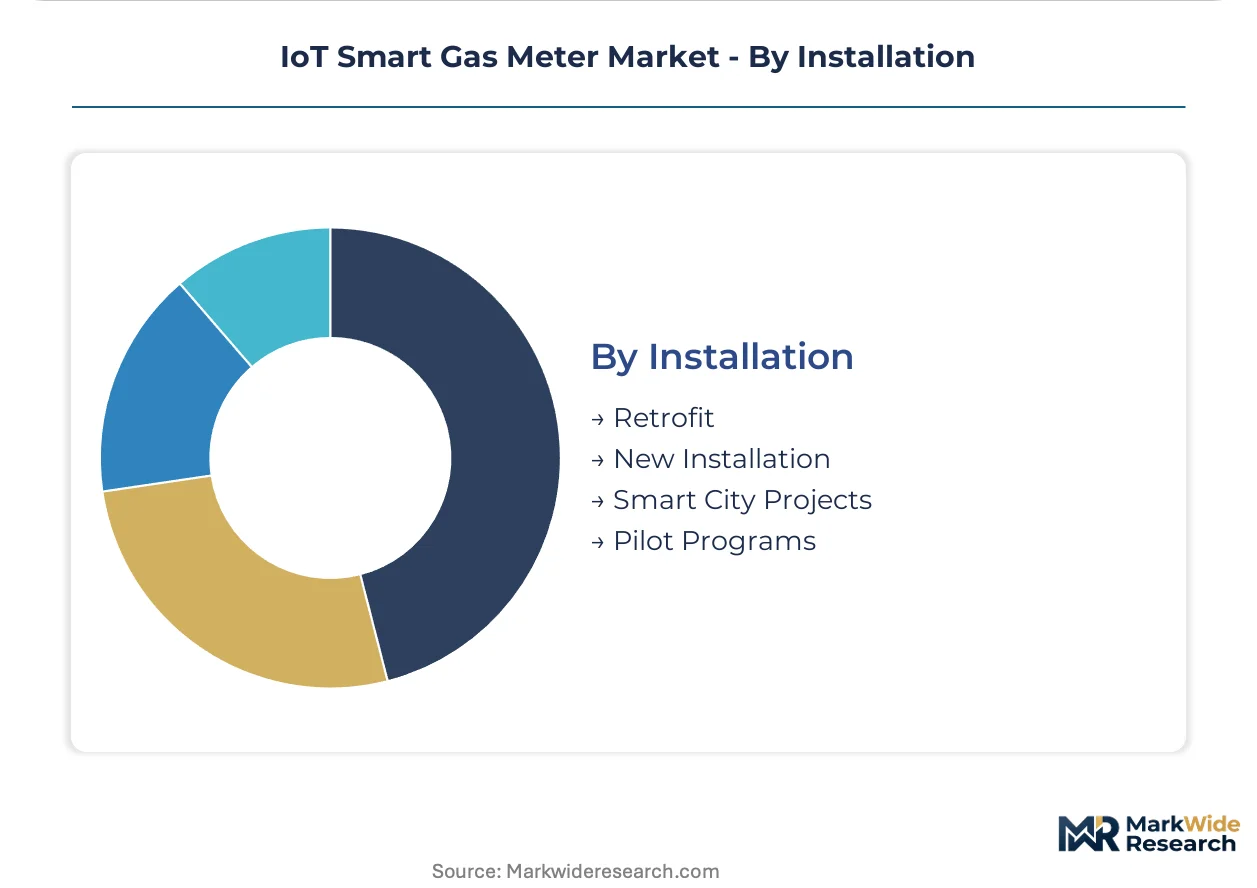
Installation:
Deployment context dictates integration complexity, legacy system compatibility burdens, and revenue recognition timing for meter OEMs.
- Retrofit:Replacement of mechanical diaphragm meters with connected units dominates near-term volume in Germany, France, and Eastern Europe where certified service life expires. CE marking under the MDR framework extends product documentation timelines for pressure-sensor-integrated designs.
- New Installation:Greenfield residential construction and city gas distribution expansion in India and China bypass legacy billing system constraints entirely.
- Smart City Projects:Integrated urban infrastructure tenders bundle gas metering with electricity, water, and waste monitoring under single procurement frameworks.
- Pilot Programs:Limited-scale trials validate ultrasonic accuracy and cybersecurity protocols before utility-wide commitment.
Retrofit commands the dominant share, though New Installation is gaining share fastest through Asia-Pacific city gas expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipal utilities extract 15-20% pricing premiums over Chinese state-owned distributors for functionally equivalent ultrasonic meters. This asymmetry reflects divergent certification burdens, financing structures, and aftermarket service bundling rather than hardware cost differentials.
China
SAMR-mandated GB standards for protocol interoperability accelerate AMI deployment across 300+ city gas distribution networks. State-owned pipeline operators in the Yangtze River Delta and Pearl River Delta specify NB-IoT modules for deep urban penetration. Shanghai and Shenzhen cluster the bulk of domestic meter manufacturing capacity, with local vendors sourcing radio modules from third-party suppliers to reduce cost.
Germany
Stadtwerke municipal utilities drive tender volumes through F-Gas Regulation-mandated replacement programs for mechanical diaphragm meters. CE marking under the MDR framework extends certification timelines for pressure-sensor-integrated designs. The Ruhr industrial corridor and Bavarian manufacturing belt concentrate deployment, with ultrasonic time-of-flight cores specified for all new residential tenders.
United States
EPA methane leak detection standards force integrated sensor array adoption for custody-transfer meters in shale production regions. Pipeline operators in the Permian Basin and Appalachian plays demand quadruple sensing for continuous emissions monitoring. FERC-regulated interstate pipelines accelerate AMI timelines, while municipal utilities in Texas and Pennsylvania lag due to legacy billing system constraints.
India
PNGRB licensing for 300+ city gas distribution districts mandates smart metering for CNG and PNG connections. Greenfield deployment bypasses legacy system integration burdens entirely. Maharashtra and Gujarat anchor initial rollout volumes, with Mumbai and Ahmedabad utilities specifying prepaid-enabled residential units for informal settlement connections.
Netherlands
Ofgem-influenced regulatory frameworks encourage unbundled procurement of meter hardware from connectivity management. Dutch utilities specify solid-state ultrasonic cores exclusively, eliminating mechanical inspection requirements. The Randstad urban corridor leads deployment density, with Amsterdam and Rotterdam utilities trialing edge-computing architectures for localized leak detection.
IoT Smart Gas Meter Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying radio modules and sensor arrays. The vendor base stratifies between full-stack AMI providers and mechanical meter OEMs retrofitting connectivity. Three archetypes dominate: North American software-anchored platforms, European manufacturing-scale incumbents, and Asian cost-optimized hardware specialists. Competitive moves concentrate on meter-as-a-service financing structures and ultrasonic core technology licensing.
Among North American platform providers, Itron Inc. and Sensus (Xylem Inc.) occupy positions emphasizing cloud-native AMI headends and utility software integration. European manufacturing-scale players include Landis+Gyr and Diehl Stiftung & Co. KG, representing archetypes built on deep utility relationships and localized production footprints. Honeywell International Inc. exemplifies the diversified industrial conglomerate model, leveraging integrated safety sensor architectures across multiple meter tiers.
| Leading Market Players |
|---|
| Itron Inc. |
| Landis+Gyr |
| Honeywell International Inc. |
| Diehl Stiftung & Co. KG |
| Apator S.A. |
| Sensus (Xylem Inc.) |
| Siemens |
| ABB |
| Schneider Electric |
| Others |
Pricing and Supply Chain Analysis
Taiwanese and South Korean foundry concentration for NB-IoT and LoRaWAN radio modules concentrates margin capture with semiconductor suppliers, forcing meter OEMs to absorb lead time volatility or forward-contract at compressed hardware margins.
Pricing Analysis
Configured-to-order pricing for industrial meters with integrated pressure-temperature-leak quadruple sensing commands substantial premiums over standard residential diaphragm units. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—CE marking under the MDR framework and EPA methane compliance tiers—plus after-sales telemetry bundling. Pricing pressure stems from SAMR-mandated protocol interoperability in China, which enables smaller hardware vendors to compete on cost while sourcing radio modules from third parties. Municipal utilities in Germany exhibit lowest price sensitivity due to F-Gas Regulation compliance deadlines, while Chinese city gas distributors prioritize per-unit cost minimization above feature depth.
Supply Chain Analysis
Upstream feedstock for ultrasonic time-of-flight sensors centers on piezoelectric ceramics and MEMS wafers sourced from Japan, Germany, and the United States. Semiconductor lithography equipment and rare earth magnet assemblies for valve actuation draw from concentrated supplier bases in Taiwan and China. Single-source vulnerability in radio module foundry capacity exposes meter OEMs to allocation rationing during demand spikes. Distribution runs through utility procurement consortia in Europe, direct state-owned enterprise contracts in China, and meter-as-a-service financiers carrying long-dated receivables in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from cloud-native AMI platforms unbundling hardware from connectivity management, requiring defensive repositioning around integrated safety architectures and balance-sheet-backed financing capacity.
For Market Incumbents: Entrench ultrasonic core technology licensing as a defensive moat against modular competitors sourcing commoditized radio modules. Deepen backward integration into pressure sensor manufacturing to compress CE marking timelines under the MDR framework. Prioritize meter-as-a-service balance sheet capacity to capture municipal utility procurement shifting from capex to opex models.
For New Entrants and Emerging Players: Build out edge-computing firmware capabilities for localized leak detection, targeting Dutch and German utilities trialing distributed processing architectures. India PNGRB-mandated city gas distribution expansion offers the most penetrable geography for greenfield deployment without legacy billing system integration burdens. Position through prepaid-enabled residential specifications for informal settlement connections in Maharashtra and Gujarat.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed connectivity module specialists seeking exit to industrial conglomerates building full-stack AMI platforms. Long-term viability hinges on regulatory compliance depth across F-Gas, EPA, and SAMR frameworks rather than hardware cost position alone. Watch for EPA methane detection standard tightening as the inflection signal accelerating integrated sensor array adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Core Technology Licensing | Captures recurring revenue from meter OEMs adopting solid-state measurement architectures. |
| Integrated Safety Sensor Development | Addresses EPA methane detection mandates in Permian Basin custody-transfer applications. |
| Meter-as-a-Service Financing Buildout | Converts utility capex to opex, opening procurement to balance-sheet-capable vendors. |
| Edge Computing Firmware Migration | Reduces latency for leak alerts while compressing data transmission costs for utilities. |
| Protocol Interoperability Certification | Meets SAMR GB standards in China, reducing vendor lock-in and enabling modular sourcing. |
Research Methodology
Cross-validation between utility procurement officer interviews and AMI platform vendor disclosures anchors the qualitative findings in documented tender behavior and contract structures. Primary fieldwork engaged meter OEM technical directors, municipal utility planning officers, semiconductor procurement leads, and regulatory compliance specialists across China, Germany, and the United States. Secondary validation drew from SAMR GB standard filings, EPA methane detection rulemakings, FERC interstate pipeline dockets, and EU CE marking notifications under the MDR framework. Bottom-up unit shipment estimates triangulate against top-down AMI infrastructure spend projections.
Calibration against historical replacement cycle data and announced tender volumes shapes the projection framework across the analysis window. Segmentation dimensions include product type tier, communication topology, end-user procurement authority, and installation context. CAGRs derive from regression against AMI mandate timelines and regulatory compliance deadlines. Forecast inputs incorporate ultrasonic sensor yield rates, radio module foundry capacity utilization, and utility billing system modernization spend.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native AMI platforms or state-backed Chinese hardware consortia would shift outcomes. Semiconductor supply disruption, MDR certification timeline extensions, or EPA methane standard acceleration represent material revision risks. Cross-checking against announced utility tender awards and disclosed AMI capex budgets is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Smart Utilities Management Market
Energy Management Systems
Data Center Power Management Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
North America Home Energy Management System (HEMS) Market
Energy Management Systems
Evaporative Air Cooler Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
Global Digital Utility Market
Energy Management Systems
India Home Ventilation System Market
Energy Management Systems
Airflow Management Market
Energy Management Systems
Smart Cooling Systems Market
Energy Management Systems
IoT Energy Management Market
Energy Management Systems
Chemical Control Systems Market
Energy Management Systems
Cooling Management System Market
Energy Management Systems
Africa Digital Showers Market
Energy Management Systems
USA and Canada Portable Air Conditioner Market
Energy Management Systems
Grid Operations Management Software Market