
 Airflow Management Market | 2026-2036
Airflow Management Market Size, Share, and Industry Trends Forecast 2026-2036
Airflow Management Market Analysis
Capital-intensity divergence between integrated electrical infrastructure providers and specialized airflow component vendors is bifurcating competitive dynamics in the sector. Schneider Electric leverages its end-to-end data center power and cooling portfolio to bundle airflow management with UPS and power distribution sales. Upsite Technologies anchors its position through proprietary containment analytics and thermal assessment services that sustain recurring consulting revenue.
Airflow management encompasses the engineered control of air distribution, pressure differentials, and thermal gradients within enclosed environments, typically utilizing diffusers, dampers, variable-air-volume boxes, and air curtains fabricated from galvanized steel, aluminum, or polymer composites to achieve target cooling capacity measured in cubic feet per minute per kilowatt. Its primary industrial purpose centers on eliminating hot spots, reducing energy consumption, and maintaining ISO 14644 cleanliness classifications in mission-critical facilities. Diffusers and VAV boxes occupy the largest installed base across commercial buildings and data centers, while computational fluid dynamics software represents the fastest-expanding margin pool as operators digitize thermal planning. Active control systems are displacing passive baffles in hyperscale facilities where real-time sensor feedback optimizes fan speed and damper position against fluctuating IT loads.
ASHRAE thermal guidelines for data centers, the EPA's ENERGY STAR certification for commercial HVAC equipment, and India's BIS energy efficiency standards for air handling units collectively shape product specifications and procurement criteria across major demand centers. Compliance with these frameworks now functions as a baseline market-access requirement rather than a differentiator, compressing margins for non-certified suppliers. Stakeholders must monitor evolving rack-density thresholds and corresponding changes in ASHRAE allowable inlet temperature ranges to anticipate hardware refresh cycles and retrofit timing.
Market Dynamics
Rack density escalation beyond 30 kilowatts per rack is forcing hyperscale operators to abandon passive containment in favor of active, sensor-driven airflow orchestration systems that adjust cooling delivery in real-time against fluctuating compute loads.
Growth Catalysts
- Europe's F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is compelling data center operators across Germany, France, and the Netherlands to retrofit existing facilities with low-global-warming-potential airflow systems.
- Hyperscale data center construction:Operators in the United States, India, and Germany are expanding cooling infrastructure to manage thermal loads from AI training clusters and high-performance computing deployments.
- Computational fluid dynamics software:Digital twin modeling of thermal environments is accelerating hardware refresh cycles and enabling precision airflow commissioning before physical deployment.
Market Restraints
- Aluminum and galvanized steel input volatility:Raw material price swings for sheet metal fabrication compress margins for diffuser and damper manufacturers serving price-sensitive commercial building segments.
- Specialized component supplier concentration:Precision sensor and variable-frequency drive sourcing concentrates among East Asian electronics manufacturers, exposing airflow system integrators to lead time and tariff risks.
- ASHRAE thermal guideline compliance costs:Continuous updates to allowable inlet temperature ranges force engineering redesigns and recertification expenses that deter smaller facility operators from system upgrades.
Strategic Opportunities
- India's Chennai-Mumbai-Bangalore corridor:Tropical ambient temperatures and rapid data center buildout create acute demand for advanced containment and precision cooling solutions in this underpenetrated market.
- AI-driven predictive maintenance:Convergence of machine learning algorithms with IoT sensor networks enables airflow vendors to offer thermal performance guarantees and recurring software subscription revenue.
- US Inflation Reduction Act incentives:Energy efficiency tax credits for commercial building upgrades are lowering payback periods for advanced HVAC and airflow management retrofits.
Industry Challenges
- Thermal engineering talent scarcity:Shortage of computational fluid dynamics specialists and data center cooling engineers constrains deployment velocity for complex active control system installations.
- Legacy building management system integration:BACnet and Modbus protocol fragmentation across installed building automation infrastructure complicates unified airflow orchestration in retrofitted facilities.
- ISO 14644 cleanroom certification timelines:Extended validation periods for pharmaceutical and semiconductor manufacturing environments delay revenue recognition on containment system deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airflow Management Market |
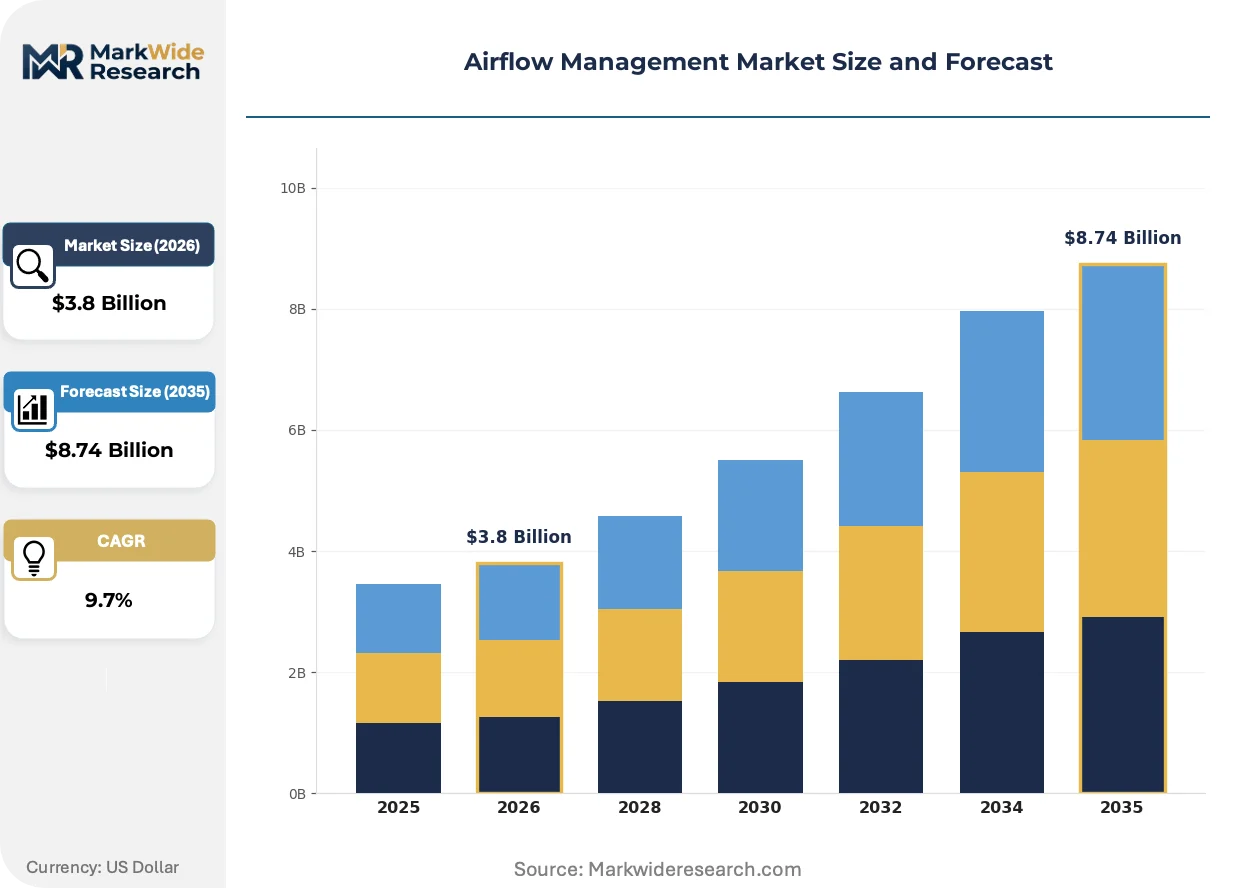
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diffusers, Dampers, VAV Boxes, Air Curtains Application: Data Centers, HVAC Systems, Clean Rooms, Industrial Facilities Technology: Active Control, Passive Control, HVAC Integration, Computational Fluid Dynamics End User: Commercial Buildings, Residential Units, Manufacturing Plants, Healthcare Facilities |
| Companies Covered | Schneider Electric, Upsite Technologies, Kingspan Group, Eaton Corporation, Subzero Engineering, Conteg, Geist, AdaptivCOOL, 42U, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airflow Management Market Emerging Trajectories
Active control architectures are supplanting static containment as the dominant design paradigm, while regulatory pressure on refrigerants and energy intensity accelerates hardware refresh cycles across mission-critical facilities.
Computational fluid dynamics software combined with real-time sensor feedback is supplanting rule-based damper scheduling in hyperscale data centers. Operators in the United States and Germany are deploying these systems to eliminate thermal stratification and hot spots. The shift is compressing demand for passive baffle manufacturers while expanding margin pools for analytics-enabled service contracts.
Europe's F-Gas Regulation is mandating refrigerant phase-downs that cascade into airflow system redesigns. Equipment vendors must now engineer low-pressure-drop diffusers and optimized duct geometries to compensate for reduced refrigerant cooling capacity. Data center operators in Germany and France are responding by bundling airflow upgrades with chiller replacements to maintain thermal resilience.
Facility managers are consolidating vendor relationships around integrated power and cooling portfolios rather than sourcing airflow components separately. Hyperscale buyers in India and the United States are awarding sole-source contracts to electrical infrastructure providers with captive airflow capabilities. This concentration is marginalizing specialized component vendors that lack bundled UPS or power distribution offerings.
Airflow Management Market Segmentation
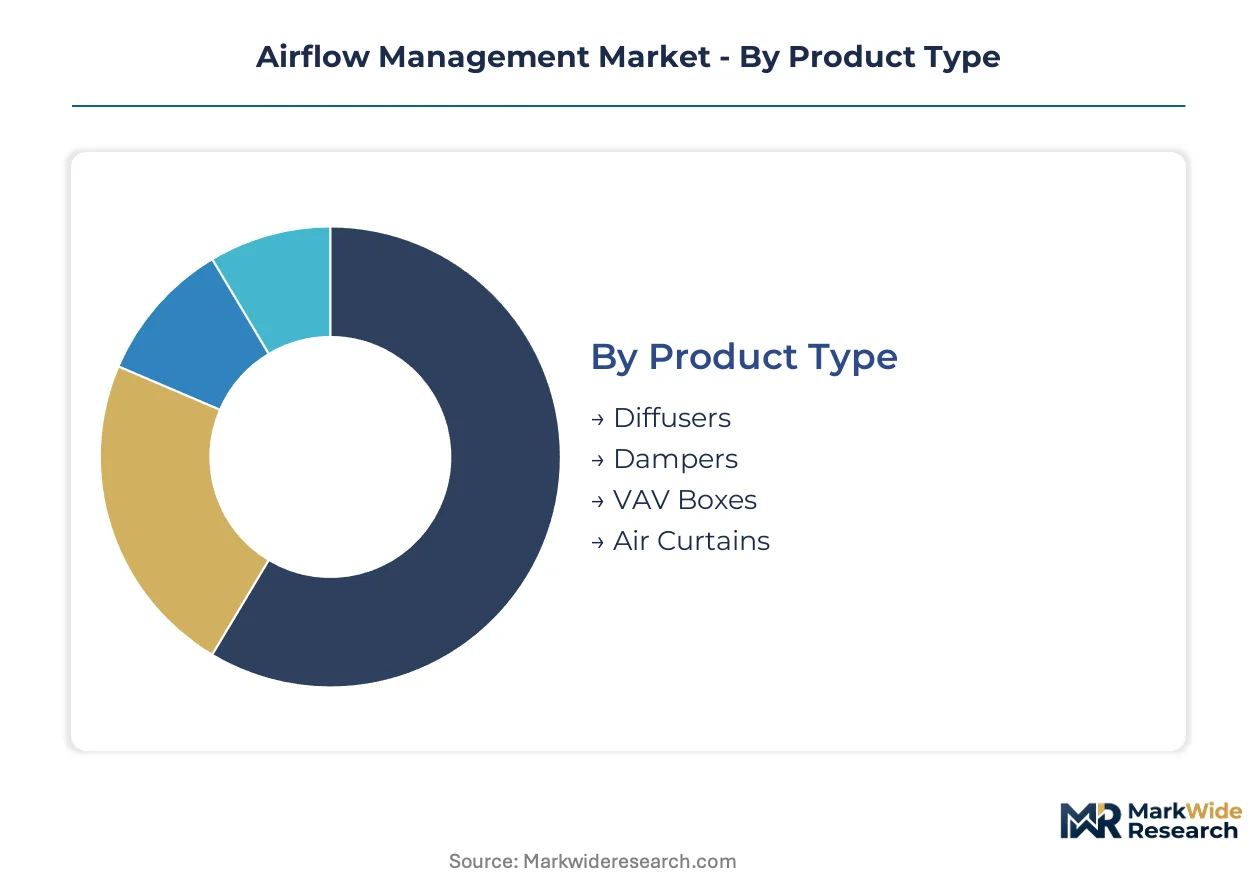
Airflow management procurement splits across hardware, software, and service layers with divergent margin structures. Understanding where value concentrates within each dimension enables vendors to defend pricing power against commoditization pressures.
Product Type:
Margin pools concentrate in precision-engineered active components where sensor integration and real-time adjustability command premium positioning.
- Diffusers:Fabricated from galvanized steel or aluminum with engineered blade geometries to distribute conditioned air across rack rows. Demand concentrates in United States hyperscale facilities where ASHRAE thermal guidelines mandate uniform inlet temperature distribution for densities above 30 kilowatts per rack.
- Dampers:Motorized or manually actuated flow-control devices that modulate air volume through duct networks. India's Chennai-Mumbai-Bangalore data center corridor drives specification intensity as tropical ambient temperatures amplify the penalty for imprecise airflow balancing.
- VAV Boxes:Pressure-independent terminal units with hot water or electric reheat coils for zone-level temperature control.
- Air Curtains:High-velocity air barriers deployed at facility entry points to prevent thermal contamination and maintain ISO 14644 cleanliness classifications.
Diffusers hold installed capacity. VAV Boxes are rotating up the share rankings.
Application:
Volume concentrates in building-wide HVAC retrofits, while value per square meter peaks in mission-critical environments where thermal failure carries catastrophic cost.
- Data Centers:Engineered containment systems, aisle isolation, and precision cooling integration for compute-intensive workloads. Demand from AI training clusters in Germany and the United States is displacing passive containment architectures in favor of sensor-driven active orchestration.
- HVAC Systems:Commercial building-wide air distribution infrastructure including central plant ductwork and terminal equipment. Europe's F-Gas Regulation is forcing refrigerant-dependent system redesigns that cascade into airflow component refresh cycles across France and the Netherlands.
- Clean Rooms:ISO 14644-certified environments for pharmaceutical and semiconductor manufacturing with unidirectional laminar flow requirements.
- Industrial Facilities:Heavy-duty ventilation for process cooling, fume extraction, and ambient temperature management in manufacturing plants.
HVAC Systems dominate unit shipments. Data Centers are climbing the fastest on revenue contribution.
Technology:
Software-enabled intelligence is capturing expanding margin share as hardware commoditizes and service contracts extend customer lifetime value.
- Active Control:Real-time sensor networks with variable-frequency drives and motorized dampers that adjust airflow against fluctuating thermal loads. Hyperscale operators in the United States are deploying these systems to eliminate hot spots from AI workload spikes.
- Passive Control:Static baffles, blanking panels, and containment barriers without powered adjustment mechanisms. Price-sensitive commercial building segments in India retain demand for these lower-first-cost solutions despite efficiency trade-offs.
- HVAC Integration:Unified control architectures that coordinate airflow with chiller, boiler, and ventilation plant operation.
- Computational Fluid Dynamics:Digital twin software for thermal environment modeling and pre-deployment commissioning. German data center engineers are adopting these tools to reduce physical testing cycles and accelerate facility bring-up.
Passive Control retains legacy footprint. Active Control is gaining share fastest.
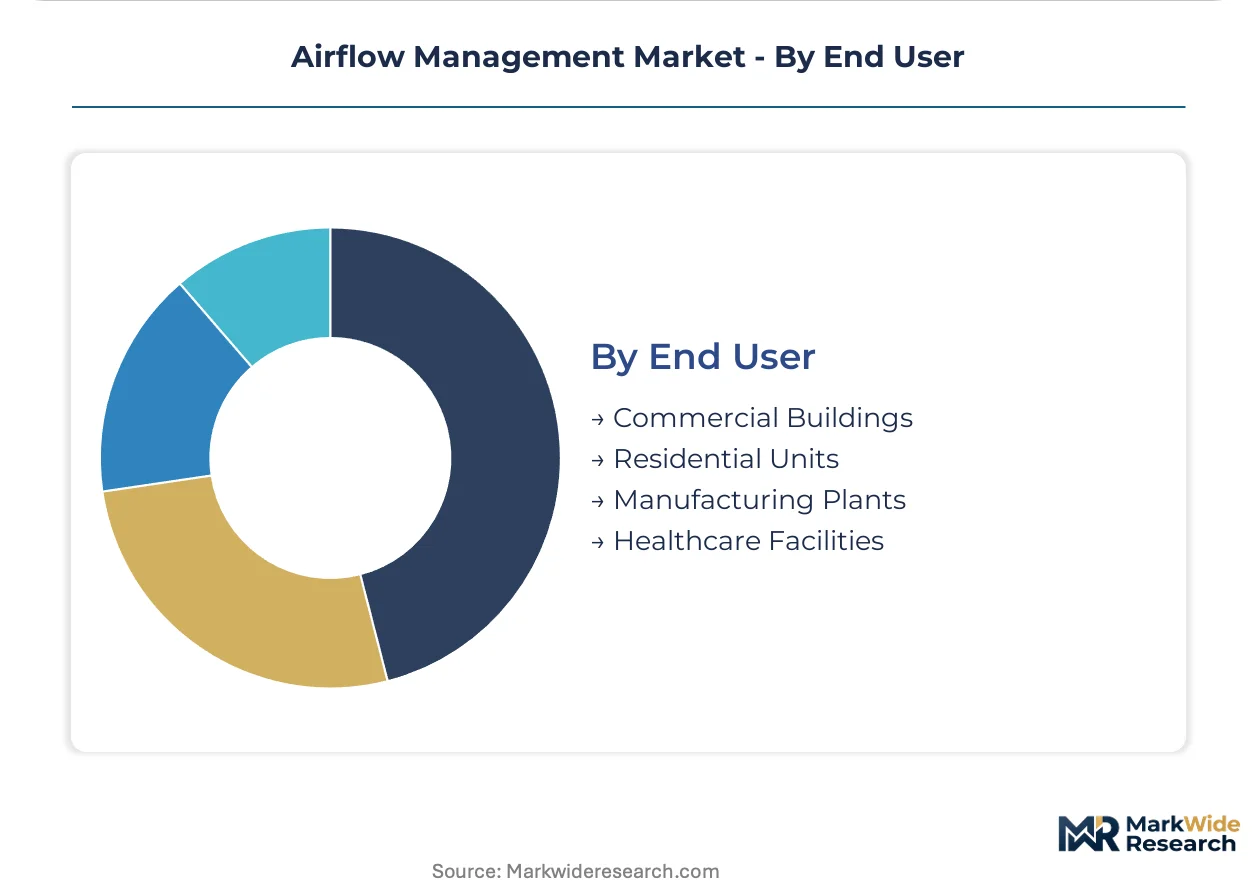
End User:
Procurement sophistication varies sharply across customer types, with manufacturing and healthcare demanding certification rigor that commercial buildings often bypass.
- Commercial Buildings:Office towers, retail complexes, and hospitality properties with comfort cooling and ventilation priorities. The US Inflation Reduction Act's energy efficiency tax credits are compressing payback periods for advanced airflow retrofits in this segment.
- Healthcare Facilities:Hospitals and laboratories requiring infection control, pressure differentials, and strict air change rates. India's BIS energy efficiency standards for air handling units shape procurement criteria in this regulated environment.
- Manufacturing Plants:Process environments with fume extraction, dust control, and thermal conditioning for production equipment.
- Residential Units:Single-family and multi-family dwellings with decentralized HVAC and limited centralized airflow management.
Commercial Buildings anchor volume. Healthcare Facilities are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in airflow management equipment tilt toward import dependence in high-growth Asian markets while established European and North American producers supply precision-engineered components. Export competitiveness hinges on certification alignment with ASHRAE, EPA, and local efficiency mandates.
United States
Hyperscale data center operators in Northern Virginia, Dallas-Fort Worth, and Phoenix are deploying active control systems to manage AI training cluster thermal loads. The EPA's ENERGY STAR certification for commercial HVAC equipment shapes procurement specifications for federal and enterprise facilities. Northern Virginia's Data Center Alley anchors domestic demand concentration with rack densities exceeding 30 kilowatts driving containment retrofits.
Germany
Data center construction in Frankfurt and Berlin is accelerating cooling infrastructure investment to support cloud and HPC deployments. The F-Gas Regulation mandates hydrofluorocarbon phase-downs that cascade into airflow system redesigns for low-global-warming-potential compatibility. Frankfurt's Rhine-Main cluster concentrates retrofit activity as operators bundle containment upgrades with chiller replacements.
India
The Chennai-Mumbai-Bangalore data center corridor faces acute thermal management challenges from tropical ambient temperatures and rapid facility buildout. BIS energy efficiency standards for air handling units establish baseline compliance thresholds for domestic and multinational operators. Mumbai's Navi Mumbai and Thane sub-markets exhibit the fastest specification intensity for precision cooling integration.
United Kingdom
London and Slough data center markets are expanding cooling capacity to accommodate financial services and cloud workload growth. The UK's adoption of EU-derived F-Gas restrictions maintains refrigerant transition pressure on legacy facility operators. Slough's Trading Estate cluster drives demand for aisle containment and hot-cold isolation systems.
France
Paris and Marseille data center operators are retrofitting facilities to meet tightening energy efficiency and refrigerant regulations. ANSM and environmental agency oversight reinforces cleanroom and mission-critical thermal standards for pharmaceutical manufacturing. Paris-Saclay's research and technology cluster generates specialized demand for CFD-modeled airflow commissioning.
Airflow Management Market Vendor Landscape
Concentration sits with integrated electrical infrastructure providers that bundle airflow management with power distribution and UPS portfolios. Specialized component vendors occupy mid-tier positions through proprietary analytics and thermal assessment services. Two strategic archetypes dominate: full-stack infrastructure integrators and niche containment specialists. Competitive moves center on portfolio diversification into adjacent power and cooling categories and geographic expansion through local system integrator partnerships.
Within the integrated infrastructure tier, Schneider Electric represents the bundled power-cooling portfolio archetype, while Upsite Technologies occupies a position among analytics-enabled specialists. Kingspan Group exemplifies the building envelope and containment fabrication segment. Eaton Corporation anchors the electrical infrastructure crossover archetype where power management capabilities extend into thermal optimization.
| Leading Market Players |
|---|
| Schneider Electric |
| Upsite Technologies |
| Kingspan Group |
| Eaton Corporation |
| Subzero Engineering |
| Conteg |
| Geist |
| AdaptivCOOL |
| 42U |
| Others |
Supply Flow & Price Mechanics
Ninety-day lead times for precision variable-frequency drives from East Asian electronics manufacturers compress margin buffers for system integrators while amplifying pricing power among vertically integrated electrical infrastructure providers. This inventory-to-delivery tension concentrates procurement leverage with hyperscale operators that can absorb extended order cycles, forcing specialized component vendors toward configured-to-order pricing models that pass through input volatility.
Pricing Analysis
Configured-to-order pricing for active control systems commands spreads of 35-50% above standard passive containment catalog pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by sensor integration density and CFD commissioning inclusion, with ASHRAE-compliant certification tiers anchoring the premium band. Cost compression in the standard tier is intensifying because aluminum sheet metal input volatility feeds directly through to diffuser and damper manufacturers. Commercial building retrofit buyers exhibit acute price sensitivity, while hyperscale data center operators prioritize thermal performance guarantees over unit economics.
Supply Chain Analysis
Strait of Malacca transit underwrites 60% of global precision sensor and VFD shipments to European and North American system integrators, creating concentrated chokepoint exposure. Manufacturing draws from China, South Korea, and Japan for variable-frequency drives, precision sensors, and motor assemblies, while galvanized steel and aluminum sheet feedstock sources from domestic mills in Germany, the United States, and India. Single-source vulnerability concentrates in East Asian electronics manufacturing for active control system components. Distribution runs through authorized system integrator networks rather than direct OEM-to-end-user channels, with Schneider Electric and Eaton Corporation maintaining captive installer certification programs that gate market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of computational fluid dynamics specialists and data center thermal engineers constrains deployment velocity, creating a capability-scarcity environment where talent access separates viable competitors from marginal participants. This skill gap amplifies returns to vendors that can productize engineering expertise through software-as-a-service delivery models.
For Market Incumbents: Compound defensive positioning by embedding airflow management within bundled power and cooling portfolios that raise switching costs for hyperscale buyers. Acquire CFD software capabilities or specialist thermal consulting firms to capture recurring revenue streams that offset hardware commoditization. Prioritize backward integration into precision sensor sourcing to mitigate East Asian supply concentration risks.
For New Entrants and Emerging Players: Differentiate on AI-driven predictive maintenance subscriptions that deliver thermal performance guarantees rather than competing on hardware unit costs. Target India's Chennai-Mumbai-Bangalore data center corridor, where tropical ambient temperatures and rapid buildout create specification intensity gaps that local system integrator partnerships can exploit. Pursue white-label CFD commissioning services to hyperscale operators as a low-capital entry vector.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across active control system manufacturing as sensor integration and real-time analytics capabilities require specialized assembly infrastructure. Long-term viability favors integrated electrical infrastructure providers with captive airflow portfolios over pure-play component vendors facing margin compression. Monitor ASHRAE thermal guideline revision cycles as inflection indicators that trigger hardware refresh demand and M&A timing windows.
| Strategic Initiative | Industry Significance |
|---|---|
| CFD Software Acquisition | Captures recurring analytics revenue from German hyperscale operators digitizing thermal planning. |
| India System Integrator Partnership | Secures specification influence in the Chennai-Mumbai-Bangalore corridor's rapid data center buildout. |
| Precision Sensor Backward Integration | Reduces East Asian single-source vulnerability for VFD and sensor components. |
| AI Predictive Maintenance Platform Launch | Enables thermal performance guarantees that differentiate against passive containment competitors. |
| ASME/ASHRAE Certification Investment | Establishes baseline market access for federal and enterprise procurement in the United States. |
Methodological Framework
Desk research of regulatory filings, trade association technical standards, and hyperscaler capital expenditure disclosures preceded structured interviews with data center facility engineers, thermal management procurement leads, CFD software developers, and electrical infrastructure sales directors. Primary fieldwork captured specification criteria, vendor selection processes, and retrofit timing decisions across the United States, Germany, and India. Secondary validation drew from ASHRAE technical committees, EPA ENERGY STAR certification databases, and India's BIS energy efficiency notifications. Bottom-up installation data triangulated against top-down infrastructure investment forecasts.
Variance decomposition across product type, application, technology, and end-user dimensions anchored the analytical framework over the projection horizon. Segmentation modeling incorporated rack density thresholds, refrigerant regulatory phase-down schedules, and regional ambient temperature differentials as airflow system demand drivers. CAGRs derived from installed base growth rates, replacement cycle compression, and value-per-unit expansion in software-enabled active control categories.
Decision-makers should treat outputs as directional under assumptions of continued ASHRAE thermal guideline relevance and sustained hyperscale data center construction velocity; material deviation in rack density adoption curves or refrigerant regulatory timelines would warrant model refresh. Practitioners should keep alternative scenarios live as F-Gas Regulation enforcement intensity and AI workload thermal profiles evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Mobile Metering System Market
Energy Management Systems
Advanced Server Energy Monitoring Tools Market
Energy Management Systems
Wi-Fi Smart Thermostat Market
Energy Management Systems
Global Smart Air Conditioning Market
Energy Management Systems
Smart Water Cooler Market
Energy Management Systems
Africa Digital Showers Market
Energy Management Systems
US Energy Management Systems Market
Energy Management Systems
Smart Air Cleaners Market
Energy Management Systems
Meter Data Management System Market
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
AI Water Heater Market
Energy Management Systems
North America Energy Management Systems Market
Energy Management Systems
Global Digital Thermostats Market
Energy Management Systems
Home Energy Management System Market
Energy Management Systems
Global Vibration Control System Market