
 Global Variable Air Volume (VAV) System Market | 2026-2036
Global Variable Air Volume (VAV) System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Variable Air Volume (VAV) System Market Foresight
Aluminum is hardening its position against galvanized steel in VAV terminal unit housings, trimming weight and improving corrosion resistance for coastal installations. Johnson Controls leverages its Metasys building automation ecosystem to bundle digital VAV controllers with service contracts across North American commercial portfolios. Daikin Industries anchors its competitive stance through captive production of inverter-driven fan motors that integrate with its fan-powered terminal units. Trane Technologies differentiates via extensive R&D investment in acoustic attenuation for educational facility applications where noise criteria are stringent.
A Variable Air Volume system modulates supply airflow to conditioned zones based on real-time thermal demand, maintaining space temperature through damper-position adjustments rather than constant-volume reheating. Terminal units typically operate at 0.5 to 2.5 inches water column static pressure with airflow ranges from 100 to 5,000 cubic feet per minute depending on box size and fan configuration. Single duct terminal units dominate existing building retrofits due to simpler ductwork requirements and lower installed cost, while fan-powered variants capture premium specification in perimeter zones with high heating loads. Digital control technology leads new construction specification as BACnet and LON interoperability become baseline owner requirements, though pneumatic retrofits persist in aging government complexes where full control infrastructure replacement faces capital constraints.
ASHRAE Standard 90.1 drives minimum efficiency requirements for VAV systems in US commercial construction, while the EU Green Deal and F-Gas Regulation push adoption of low-global-warming-potential refrigerants in integrated heat pump terminals across European member states. China's GB standards and dual carbon goals enforce building energy intensity reductions that favor pressure-independent digital VAV over constant-volume alternatives in new urban development zones. Stakeholders must monitor evolving interoperability protocols and embedded carbon disclosure rules as procurement criteria shift from first cost toward lifecycle performance verification.
Market Dynamics
The transition from pneumatic to digital control architectures represents the dominant structural force compressing installation timelines and expanding retrofit addressability across commercial building portfolios worldwide.
Growth Catalysts
- ASHRAE Standard 90.1:US commercial construction mandates minimum VAV efficiency thresholds that pressure-independent digital terminals satisfy more readily than constant-volume alternatives.
- Corporate net-zero commitments:Multinational facility operators specify networked VAV solutions with embedded metering to verify carbon reduction claims across their real estate holdings.
- Wireless BACnet integration:Elimination of dedicated control wiring reduces retrofit labor costs and accelerates project approval cycles in aging building stock.
Market Restraints
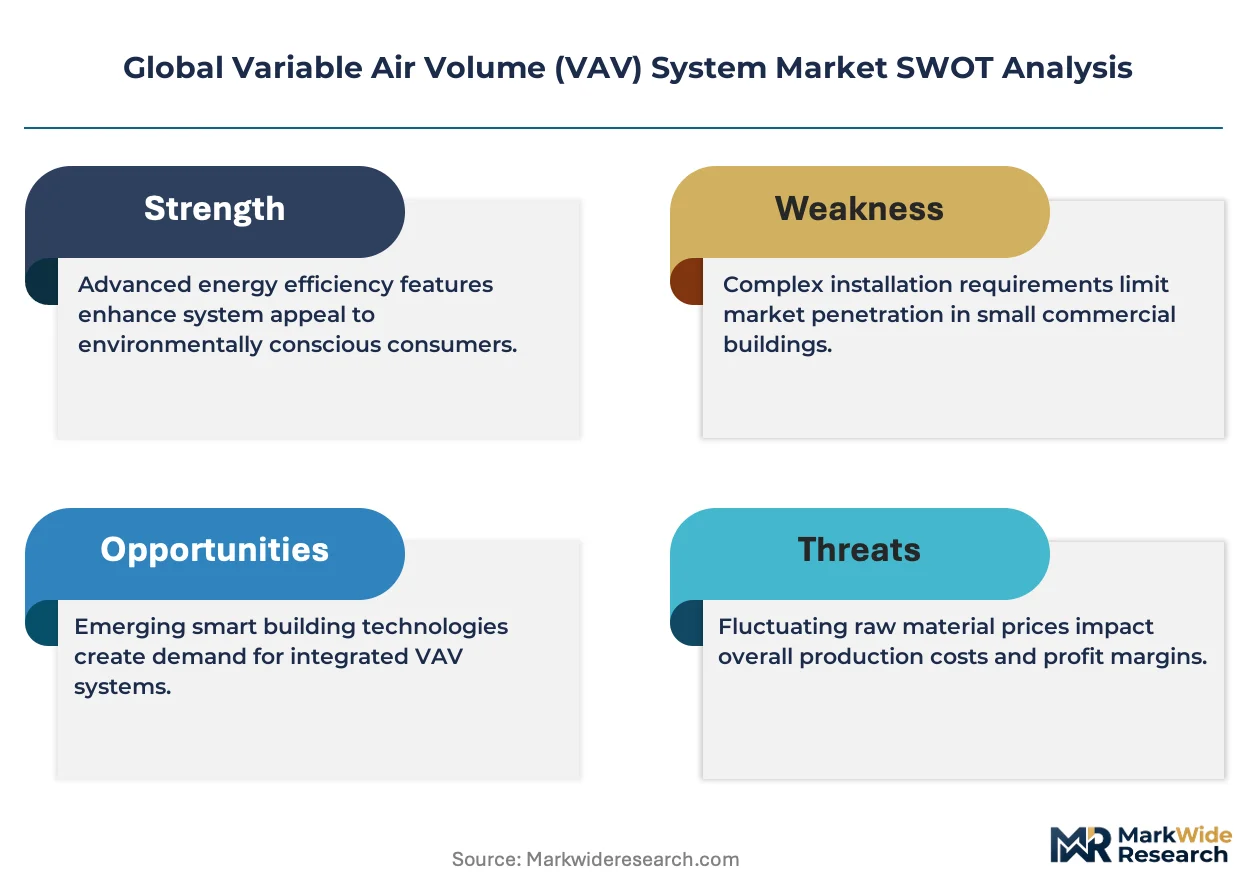
- Copper and semiconductor input volatility:Inverter-driven fan motors and digital controllers face margin pressure from commodity price swings in electrical components.
- Technical limitation in legacy pneumatic infrastructure:Government complexes with aging compressed air systems require complete control backbone replacement before digital VAV adoption.
- Substitution threat from radiant cooling:European data centers and high-performance buildings increasingly specify chilled beam systems that bypass ducted air distribution entirely.
Strategic Opportunities
- India's urban development zones:Smart city mandates and BIS energy efficiency codes create first-mover advantage for pressure-independent digital VAV specification in commercial high-rise construction.
- EU Green Deal renovation wave:Member state building retrofit targets generate demand for heat pump-integrated terminal units with low-GWP refrigerant compatibility.
- IoT-enabled predictive maintenance:Sensor-embedded terminal units enable service revenue streams through fault detection algorithms that reduce unplanned downtime.
Industry Challenges
- Controls integration complexity:Facility engineering teams lack proficiency in commissioning multi-protocol building automation networks spanning BACnet, LON, and proprietary manufacturer ecosystems.
- Acoustic certification timelines:Educational facility projects require extended third-party testing cycles to validate noise criteria compliance for fan-powered terminal units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Variable Air Volume (VAV) System Market |
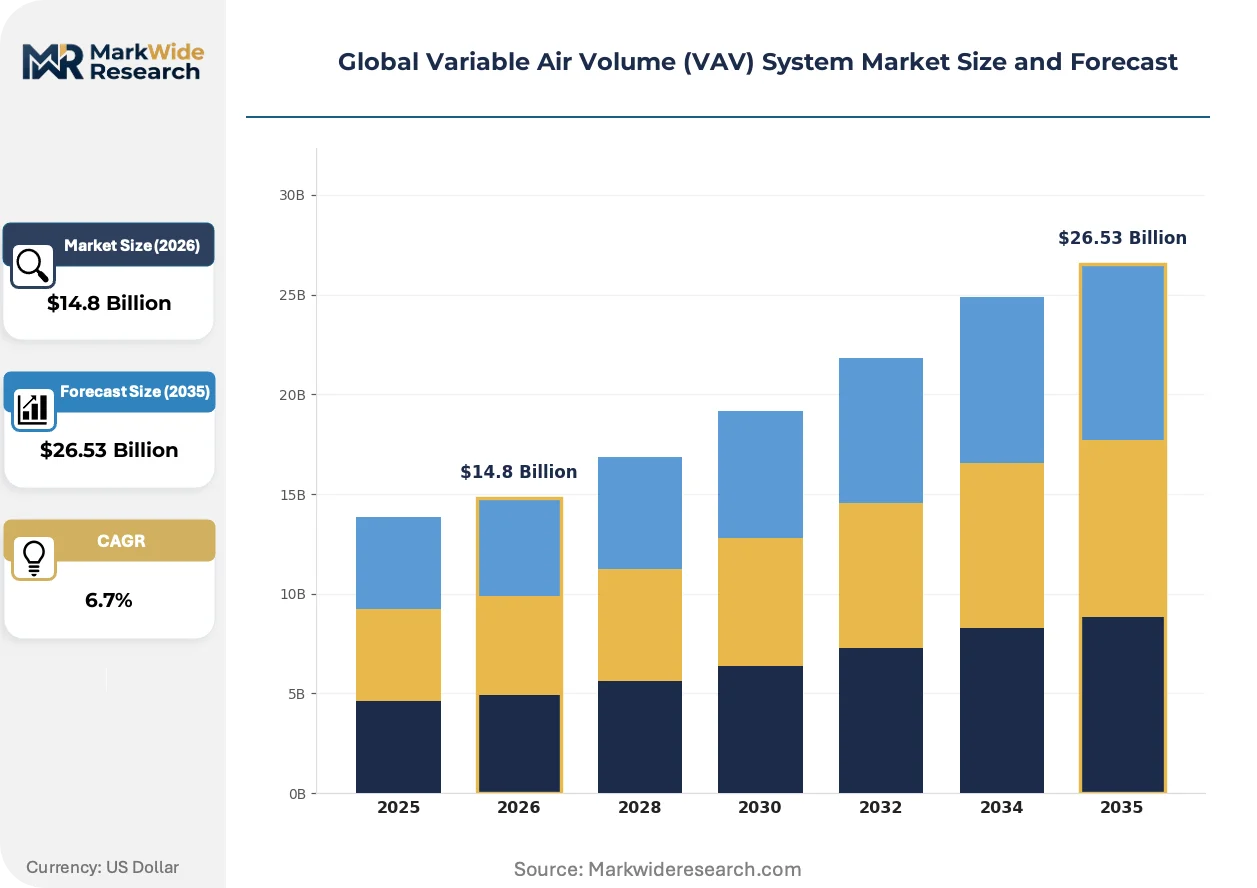
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
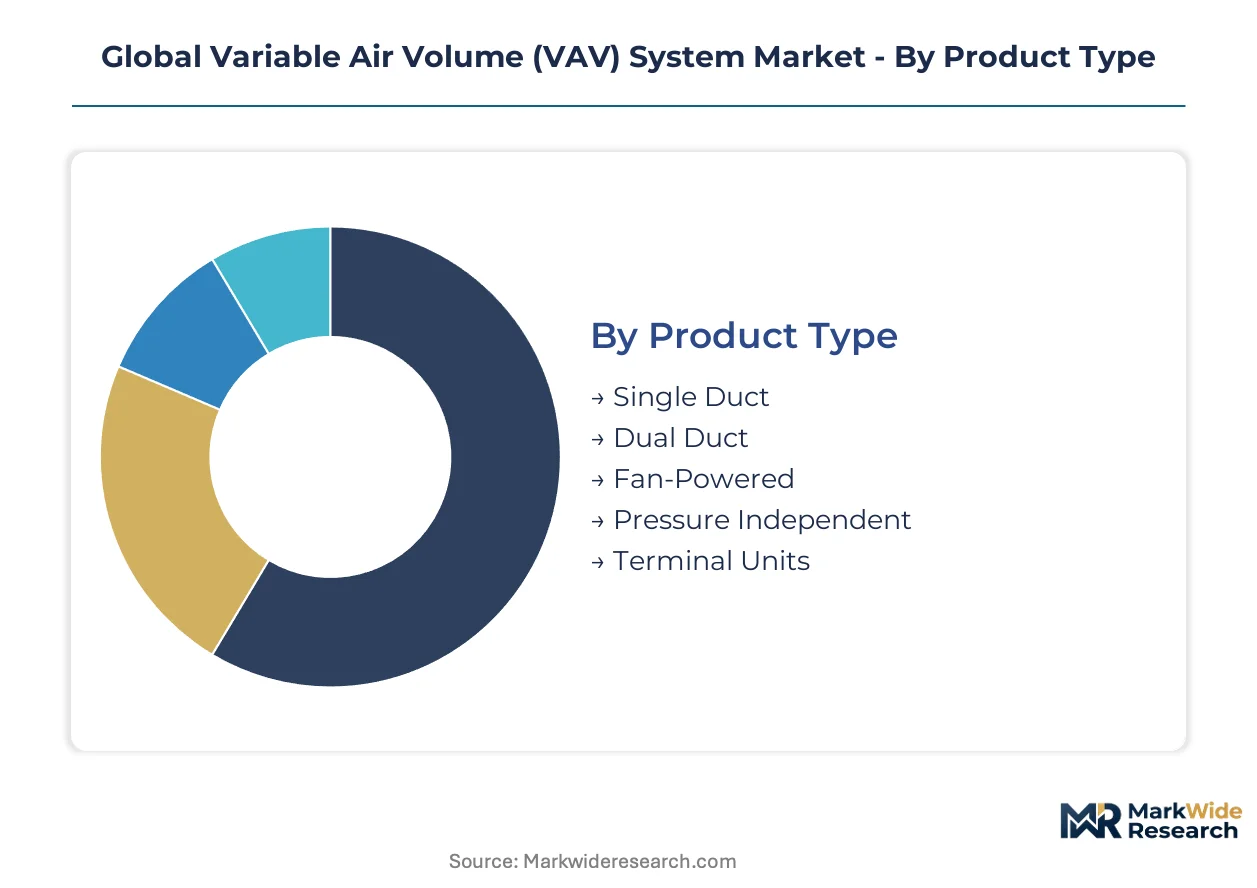
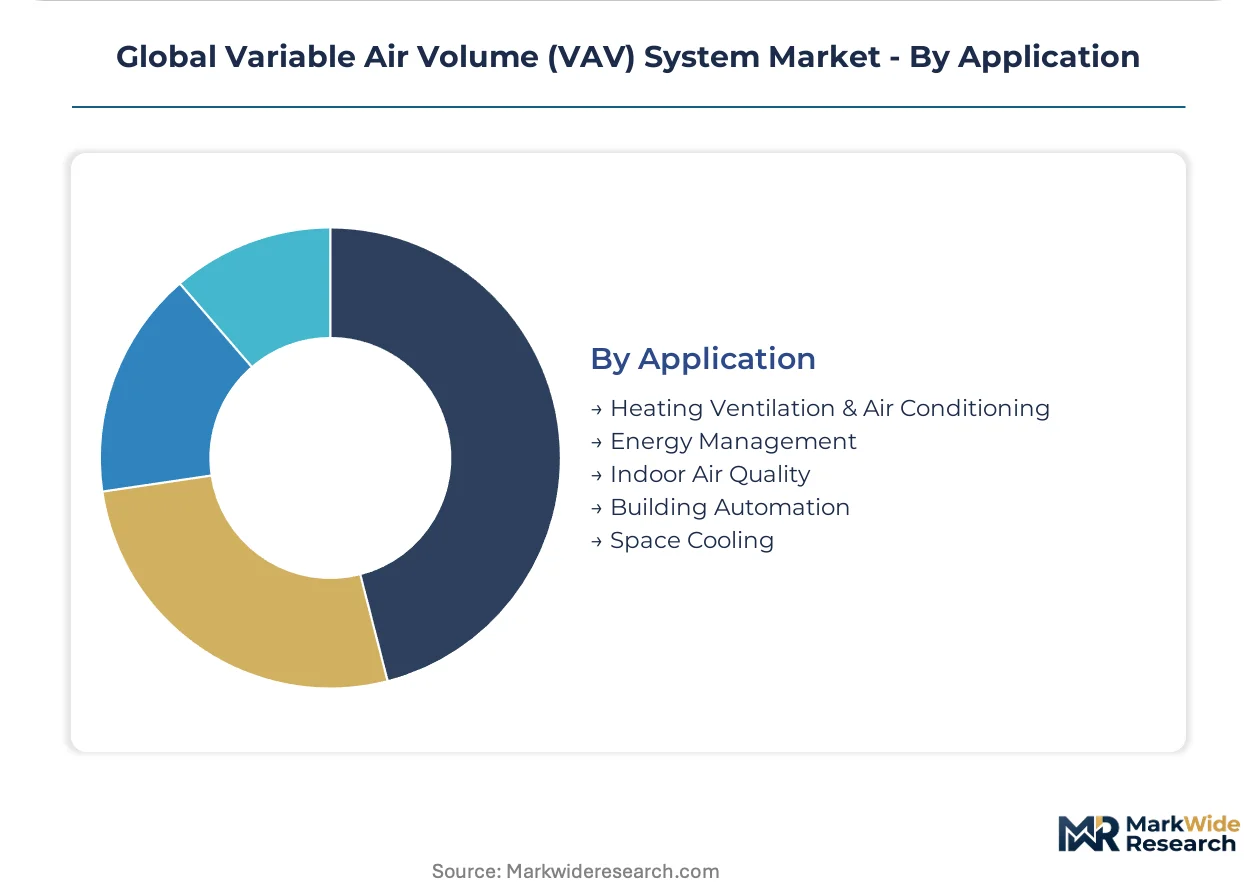
| Segmentation | Product Type: Single Duct, Dual Duct, Fan-Powered, Pressure Independent, Terminal Units Technology: Analog Control, Digital Control, Pneumatic Control, Wireless Control, Networked Systems End User Industry: Commercial Buildings, Educational Facilities, Data Centers, Hospitality, Government Complexes Application: Heating Ventilation & Air Conditioning, Energy Management, Indoor Air Quality, Building Automation, Space Cooling |
| Companies Covered | Johnson Controls, Trane Technologies, Daikin Industries, Honeywell International, Ingersoll Rand, Siemens, Emerson Electric, TROX GmbH, Systemair AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Variable Air Volume (VAV) System Market Shifts & Advancements
Digital control platforms and embedded sensing capabilities are redefining how building operators manage thermal comfort and energy accountability across distributed commercial portfolios.
Pressure-independent airflow measurement technology is overtaking traditional damper-only control in new construction specification. Engineering firms designing Class A office towers in Singapore and Dubai now require airflow-independent thermal response as baseline functionality. This shift is compressing specification windows for legacy pneumatic and analog-electric alternatives.
The EU F-Gas Regulation and accompanying building performance directives are accelerating refrigerant transition timelines for integrated heat pump terminals. Manufacturers serving German and French markets must certify low-GWP alternatives before 2027 equipment bans take effect. This regulatory pressure is concentrating R&D investment in propane and CO2 heat pump architectures for perimeter zone applications.
Building owners now unbundle long-term service contracts from initial equipment procurement, separating capital expenditure approval from operational technology management. Institutional investors acquiring commercial real estate portfolios in the United States and United Kingdom increasingly specify performance-guaranteed VAV maintenance through third-party energy service companies rather than manufacturer-direct agreements.
Global Variable Air Volume (VAV) System Market Segmentation
VAV system specification varies sharply across building types and control architectures, with procurement decisions increasingly driven by lifecycle performance metrics rather than first-cost considerations. Understanding segment boundaries reveals where technology transitions concentrate and where legacy infrastructure persists.
Product Type:
Supply concentration tilts toward terminal unit configurations that minimize field installation labor and integrate seamlessly with digital control backbones.
- Single Duct:These units modulate cooling-only airflow through a single inlet, dominating retrofit specifications where existing ductwork cannot accommodate dual-path configurations. Demand clusters in aging US office stock and Chinese commercial high-rises where simplified infrastructure reduces capital outlay.
- Fan-Powered:Integrated blowers enable independent perimeter zone heating without central fan dependency, capturing premium specification in educational facilities and hospitality properties across Germany and the northeastern United States. ASHRAE Standard 90.1 thermal zone requirements and EU Green Deal envelope performance targets accelerate displacement of reheating-dependent alternatives.
- Dual Duct:Separate hot and cold deck inlets enable rapid temperature response in variable load conditions.
- Pressure Independent:Built-in airflow measurement eliminates damper-position uncertainty.
- Terminal Units:The catch-all category encompasses specialty configurations for atypical ceiling plenum constraints.
Single duct absorbs the bulk of installed capacity; fan-powered is expanding most quickly.
Technology:
Control architecture selection now hinges on interoperability certification and wireless deployment feasibility rather than incremental hardware cost differentials.
- Digital Control:BACnet and LON protocol compatibility enables integration with modern building management platforms, securing dominant specification share in new US commercial construction and Singapore's green building mandate zones. Corporate net-zero reporting requirements favor embedded metering capabilities that pneumatic systems cannot provide.
- Wireless Control:Elimination of dedicated low-voltage wiring slashes retrofit labor costs and accelerates project timelines in aging building stock where conduit replacement is prohibitive. Demand concentrates in UK heritage building renovations and Japanese urban densification projects where structural modifications face regulatory constraints.
- Analog Control:Residual presence in budget-constrained government maintenance cycles.
- Pneumatic Control:Compressed air infrastructure persists in US federal complexes and Indian public sector institutions where full control backbone replacement awaits capital allocation.
- Networked Systems:IoT-enabled fault detection and predictive maintenance capabilities attract institutional investor portfolios seeking operational technology unbundling.
Digital control anchors new construction specification; wireless architectures are climbing the fastest in retrofit applications.
End User Industry:
Facility ownership structure and energy accountability frameworks determine specification sophistication across vertical markets.
- Commercial Buildings:Class A office towers and mixed-use developments in Dubai, London, and Shanghai specify pressure-independent digital terminals with embedded metering to satisfy green lease clauses and corporate sustainability reporting. Institutional ownership models favor performance-guaranteed maintenance contracts.
- Data Centers:Precision cooling requirements and rack-level thermal accountability drive specification for networked VAV with real-time airflow visualization. India's data center expansion under smart city mandates and Netherlands hyperscale construction create concentrated demand clusters.
- Educational Facilities:Acoustic certification requirements and extended procurement cycles characterize K-12 and university projects.
- Hospitality:Guest comfort priorities and franchise brand energy standards shape specification patterns.
- Government Complexes:Capital constraint cycles and compressed air infrastructure legacy delay digital transitions.
Commercial buildings absorb the bulk of installed capacity; data centers are gaining share fastest.
Application:
Functional deployment scope determines whether VAV systems operate as standalone comfort devices or integrated building performance nodes.
- Heating Ventilation & Air Conditioning:Core thermal comfort delivery remains the dominant deployment mode, with single duct and fan-powered terminals serving baseline space conditioning across all geographies. Specification concentrates where ASHRAE Standard 90.1 and China's GB standards mandate efficiency thresholds.
- Building Automation:Integration with centralized control platforms transforms terminal units into data collection endpoints, attracting specification in US and UK institutional portfolios where operational technology management is unbundled from capital procurement.
- Energy Management:Metering-enabled verification of carbon reduction claims.
- Indoor Air Quality:Post-pandemic ventilation rate requirements influence damper sizing and minimum airflow setpoints.
- Space Cooling:Dedicated cooling-only applications in mild climate zones.
HVAC dominates functional deployment; building automation integration is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the United Arab Emirates concentrate specification activity for high-performance building systems serving Middle East commercial development. Tax-advantaged manufacturing clusters in Southeast Asia attract component sourcing for digital control architectures. Special economic zones in China's coastal provinces anchor retrofit demand for legacy pneumatic replacement.
United States
Corporate net-zero commitments from technology and financial sector tenants drive specification for networked VAV solutions with embedded metering. ASHRAE Standard 90.1 mandates pressure-independent digital terminals in new commercial construction above 25,000 square feet. Demand clusters in Dallas-Fort Worth and Atlanta where Class A office development exceeds national permitting rates.
Germany
The EU Green Deal renovation wave targets building energy intensity reductions that favor heat pump-integrated terminal units. F-Gas Regulation deadlines before 2027 force refrigerant transition in perimeter zone equipment. Manufacturing concentration in Baden-Württemberg supplies low-GWP heat pump architectures for French and Benelux export markets.
China
Dual carbon goals and GB building standards enforce energy intensity reductions in new urban development zones. MIIT smart building mandates accelerate displacement of constant-volume systems in commercial high-rises. Specification concentrates in Shenzhen and Shanghai where green building certification rates exceed national averages by 40 percent.
India
Smart city mandates and BIS energy efficiency codes create first-mover opportunity for pressure-independent digital VAV in commercial construction. CEA building energy codes tighten compliance windows for HVAC efficiency in new high-rise development. Demand clusters in Mumbai and Bangalore where institutional real estate investment flows concentrate.
United Kingdom
Heritage building renovation constraints favor wireless control architectures that eliminate structural conduit replacement. CSRD disclosure rules mandate operational carbon reporting that pneumatic systems cannot satisfy. London commercial portfolios lead specification for performance-guaranteed maintenance contracts unbundled from capital procurement.
Global Variable Air Volume (VAV) System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated building automation providers capturing premium specification in new construction while component fabricators supply retrofit replacement markets. The vendor base concentrates around three strategic archetypes: full-system integrators with captive control platforms, terminal unit specialists with material differentiation, and regional fabricators competing on installed cost. Consolidation pressure is accelerating through strategic partnerships between controls developers and mechanical equipment manufacturers, alongside geographic expansion into India's urban development corridors.
Among diversified building technology conglomerates, Johnson Controls and Siemens occupy positions representing full-system integration archetypes with building automation ecosystems. Trane Technologies exemplifies the acoustic-specialization vector within premium-tier specification. Daikin Industries anchors the captive-component archetype through in-house production of inverter-driven fan motors. These three named entities collectively illustrate how competitive positioning stratifies across control integration, mechanical performance, and vertical supply control.
| Leading Market Players |
|---|
| Johnson Controls |
| Trane Technologies |
| Daikin Industries |
| Honeywell International |
| Ingersoll Rand |
| Siemens |
| Emerson Electric |
| TROX GmbH |
| Systemair AB |
| Others |
Supply & Pricing Matrix
Captive production of inverter-driven fan motors anchors Daikin Industries' supply position while insulating its pricing power against copper and semiconductor volatility. This backward integration pattern concentrates margin control among vertically integrated building technology conglomerates serving North American and European commercial portfolios where ASHRAE Standard 90.1 and EU Green Deal mandates compress specification windows.
Pricing Analysis
Volume concentration in single duct terminal units compresses margins while fan-powered variants command premium positioning through acoustic certification and heating performance differentiation. Pricing stratifies across pressure-independent digital tiers, wireless-enabled mid-market offerings, and pneumatic legacy segments where government procurement cycles sustain residual demand. Price erosion runs through standard-grade single duct specifications as Chinese contract manufacturers expand capacity for Southeast Asian export markets. Budget-constrained public sector buyers exhibit highest price sensitivity; institutional investors with net-zero reporting obligations prioritize lifecycle performance over first-cost minimization.
Supply Chain Analysis
Copper winding supply rests on Chilean mining output and Chinese smelter capacity, while semiconductor fabrication for digital controllers concentrates in Taiwan and South Korea. Aluminum extrusion for terminal unit housings draws from domestic Chinese producers serving regional fabrication clusters, with specialty acoustic insulation materials sourced from German and Japanese chemical suppliers. Single-source vulnerability in fan motor controller chipsets exposes lead time volatility following export restriction announcements. Distribution runs through authorized mechanical contractor networks in developed markets and direct OEM relationships with large-scale EPC contractors in emerging urban development zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor controller chip fabrication constraints prop pricing power for vertically integrated terminal unit manufacturers serving specification-sensitive commercial building portfolios.
For Market Incumbents: Deepen captive production of pressure-independent airflow measurement sensors to defend margin position against emerging Asian contract manufacturers. Secure ASHRAE Standard 90.1 pre-certification pathways for wireless BACnet architectures before Indian and Middle Eastern green building mandates accelerate. Expand service contract bundling with institutional real estate portfolios seeking operational technology unbundling from capital procurement. For New Entrants and Emerging Players: Predictive maintenance algorithms embedded at the terminal unit level offer a technology-first wedge into the fragmented aftermarket service segment where incumbent manufacturers maintain weak direct relationships. Target India's smart city commercial high-rise construction where BIS energy efficiency codes create specification windows before established building automation ecosystems achieve lock-in. Pursue white-label manufacturing partnerships with regional HVAC contractors lacking digital control development capabilities. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified building technology conglomerates seeking control platform consolidation. Five-to-ten year viability hinges on interoperability certification breadth across BACnet, LON, and emerging wireless protocols. Monitor F-Gas Regulation compliance certification timelines as inflection indicator for European heat pump-integrated terminal unit manufacturers facing 2027 equipment bans.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fan Motor Production | Captive inverter motor supply insulates Daikin Industries from copper price volatility while securing acoustic performance differentiation. |
| Wireless BACnet Certification Investment | Elimination of dedicated control wiring reduces UK heritage building retrofit labor costs by removing structural conduit replacement requirements. |
| Heat Pump Refrigerant Transition Partnership | Low-GWP propane and CO2 architecture development secures German market access before EU F-Gas Regulation equipment bans take effect. |
| Predictive Maintenance Platform Launch | Sensor-embedded terminal units enable recurring service revenue through fault detection algorithms reducing unplanned educational facility downtime. |
| India Commercial High-Rise Specification Push | Pressure-independent digital VAV positioning captures first-mover advantage under Mumbai and Bangalore smart city mandate implementation. |
Research Methodology
Document review covered ASHRAE Standard 90.1 technical addenda, EU F-Gas Regulation implementation guidance, and China GB building standard enforcement circulars, complemented by interviews with building automation system integrators, commercial facility engineering directors, and HVAC contractor procurement managers. Secondary validation drew from SEC 10-K filings of publicly traded building technology conglomerates, customs trade data for aluminum and copper component flows, and green building certification databases. Bottom-up terminal unit shipment estimates triangulated against top-down commercial construction spending projections across the analysis window.
Segmented outputs reflect modeling across product type, control technology, end-user industry, and application dimensions with geographic disaggregation to country level. CAGRs derived from regression analysis of historical specification rates against regulatory mandate implementation timelines, with inputs including corporate net-zero commitment disclosure tracking and green lease clause penetration in Class A office markets. Inverter-driven fan motor cost curves and wireless control hardware pricing trajectories informed technology transition assumptions throughout the projection horizon.
Several conditions sit outside the modeled scope, including sudden commodity price shocks in copper and semiconductor markets, unanticipated regulatory delays in Indian BIS code enforcement, and disruptive substitution from radiant cooling in European data center applications. Forecasts reflect documented assumptions regarding interoperability protocol adoption rates and embedded carbon disclosure rule implementation timing. A small set of named triggers warrants ongoing watch: F-Gas Regulation compliance certification bottlenecks, CEA building energy code enforcement intensity in Indian states, and hyperscale data center cooling architecture shifts away from ducted air distribution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Global Digital Thermostats Market
Energy Management Systems
Peltier Chillers Market
Energy Management Systems
Evaporative Air Cooler Market
Energy Management Systems
Smart Climate Control Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
Global Data Center Energy Management Solution Market
Energy Management Systems
Africa Digital Showers Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
Outage Management System (OMS) Market
Energy Management Systems
India Home Ventilation System Market
Energy Management Systems
US Energy Management Systems Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
Southeast Asia Cooling Systems Market
Energy Management Systems
IoT Energy Management Market
Energy Management Systems
AI-Driven Lighting Controls Market
Energy Management Systems
Smart Thermostat Market