
 Peltier Chillers Market | 2026-2036
Peltier Chillers Market Size, Share, and Industry Trends Forecast 2026-2036
Peltier Chillers Market Insights
Aftermarket service revenue for recalibration and thermoelectric module replacement is tilting margin pools away from initial equipment sales toward lifecycle contracts. TECA Corp. leverages its specialized service network across North American laboratory installations to capture recurring revenue streams. Samsung Electronics anchors its position through captive semiconductor fabrication demand, while Wakefield Thermal competes on thermal interface optimization for aerospace and defense applications.
Peltier chillers employ solid-state thermoelectric modules that exploit the Peltier effect to transfer heat across semiconductor junctions, achieving temperature stability within ±0.1°C without compressors or circulating refrigerants. Industrial chillers and laboratory chillers command premium positioning due to stringent stability requirements in laser systems and analytical instrumentation, while portable chillers occupy a broader volume tier serving field diagnostics and point-of-care medical devices. Electronics cooling applications sustain the largest installed base as data center edge nodes and telecommunications infrastructure proliferate.
FDA device classification rules for therapeutic hypothermia systems and EU MDR conformity requirements for medical chillers elevate compliance costs for market entry. EPA SNAP program restrictions on high-GWP refrigerants and EU F-Gas Regulation phase-down schedules redirect specification decisions toward thermoelectric alternatives in precision cooling below 500W capacity. Stakeholders must monitor NIST traceable calibration mandates and evolving efficiency standards from IEC 62368-1 as these frameworks increasingly incorporate solid-state cooling performance benchmarks.
Market Dynamics
EU F-Gas Regulation phase-down schedules are compressing conventional compressor chiller availability, forcing precision cooling procurement toward solid-state thermoelectric alternatives in sub-500W applications across semiconductor fabrication and medical device manufacturing.
Growth Catalysts
- Semiconductor cluster expansion:Taiwan and South Korea fabrication facilities are scaling thermoelectric cooling procurement as fluorinated refrigerant supply chains face EU REACH restrictions.
- Medical device regulatory elevation:FDA device classification rules for therapeutic hypothermia systems and EU MDR conformity requirements are excluding compressor-based alternatives from precision temperature control specifications.
- NIST traceable calibration mandates:Laboratory end users in Germany and the United States now require solid-state cooling performance benchmarks that thermoelectric modules satisfy.
Market Restraints
- Bismuth telluride supply concentration:Raw thermoelectric material refining clusters in China create input cost volatility and geopolitical exposure for module manufacturers.
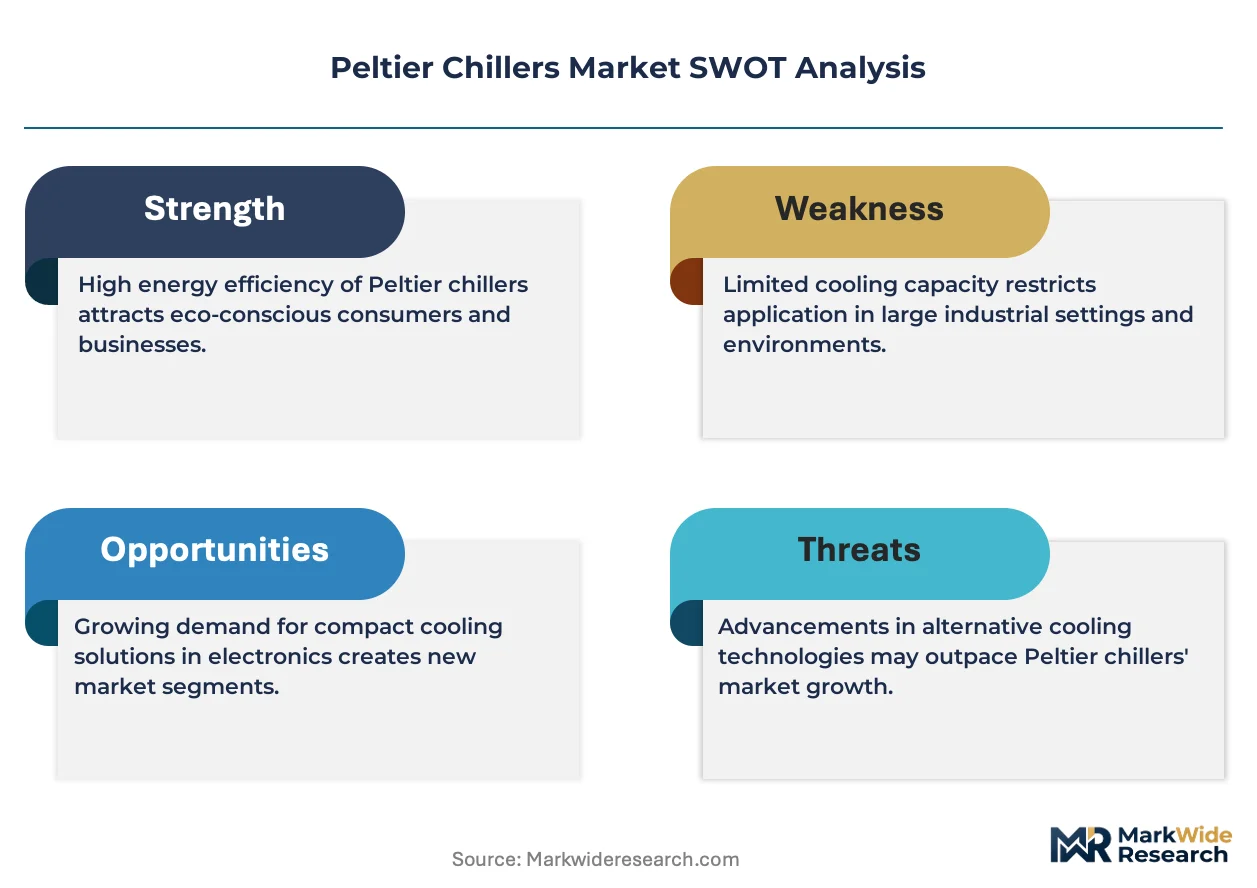
- Coefficient of performance ceiling:Thermoelectric systems face fundamental physics limitations below 0.6 COP that restrict adoption in above-1kW cooling loads.
- EU MDR compliance timeline:Medical chiller certification cycles extending 18-24 months elevate working capital requirements and defer revenue recognition for new market entrants.
Strategic Opportunities
- Edge computing infrastructure:Data center node proliferation in secondary US metropolitan markets creates distributed demand for compact, refrigerant-free cooling below 300W.
- IEC 62368-1 efficiency standard incorporation:Emerging solid-state cooling performance benchmarks in audio/video and IT equipment safety standards are creating specification tailwinds.
- Field diagnostics channel expansion:Point-of-care medical device manufacturers are bypassing traditional distribution through direct OEM integration partnerships.
Industry Challenges
- Thermoelectric module integration engineering:Thermal interface optimization for aerospace and defense applications requires scarce specialist expertise in multi-physics simulation.
- Aftermarket service network buildout:Recalibration and module replacement lifecycle contracts demand field technician training investments that compress near-term margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peltier Chillers Market |
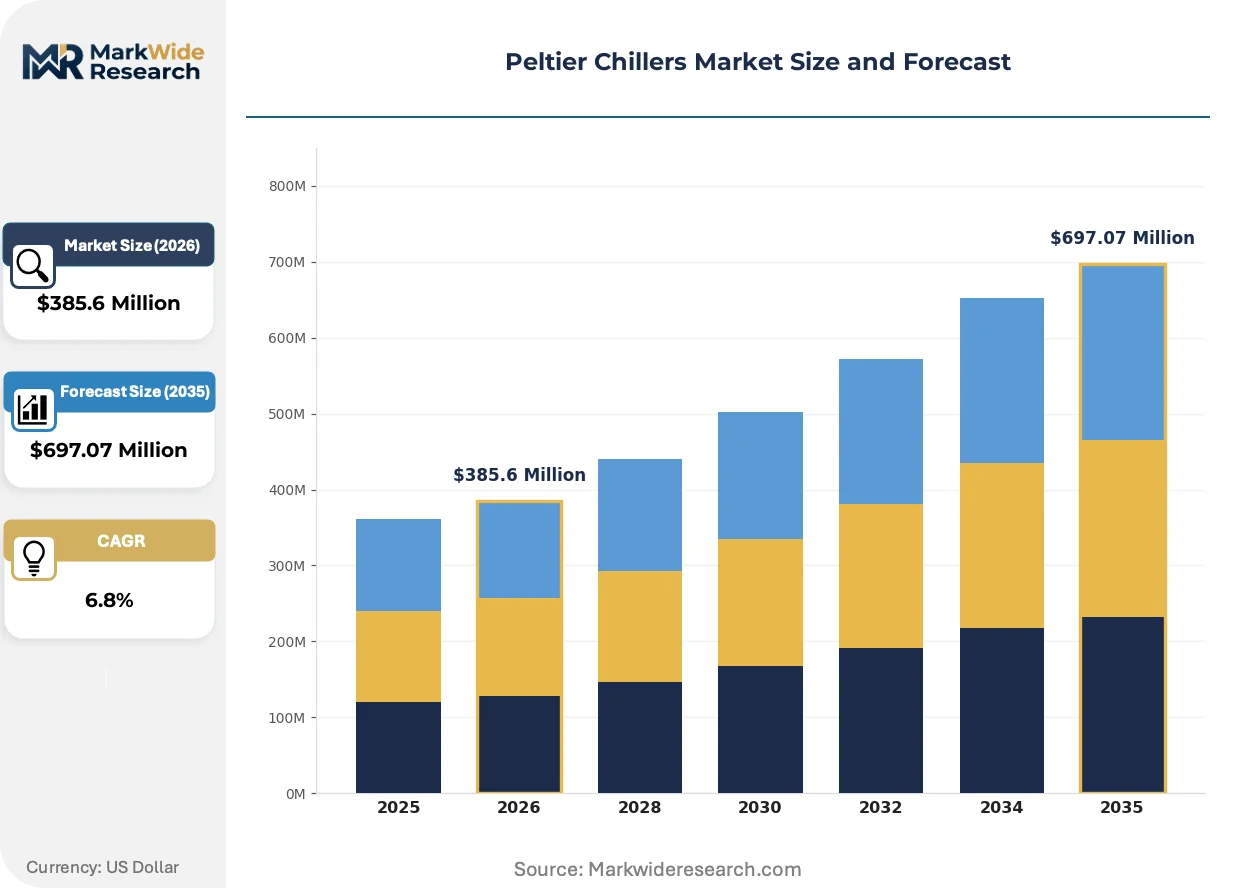
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Chillers, Industrial Chillers, Laboratory Chillers, Medical Chillers Application: Electronics Cooling, Chemical Processing, Medical Devices, Wine Cooling End User: Manufacturers, Laboratories, Hospitals, Restaurants Installation Type: Standalone Units, Integrated Systems, Custom Solutions, OEM Systems |
| Companies Covered | Wakefield Thermal, Samsung Electronics, Advanced Thermal Solutions (ATS), Carrier, Daikin, CUI Devices, TECA Corp., Midea, Delta Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peltier Chillers Market Trends and Innovations
Solid-state cooling architectures are actively hybridizing with adjacent thermal management technologies, while regulatory frameworks and procurement behaviors simultaneously reshape competitive positioning in precision temperature control.
Multi-stage cascaded thermoelectric modules are achieving sub-ambient temperature differentials beyond 100°C for laser system stabilization. Analytical instrumentation manufacturers in Germany and the United States are adopting these configurations at accelerating specification rates. The technology is hybridizing with vapor chamber heat spreaders to compress thermal resistance in semiconductor test equipment.
EPA SNAP program restrictions on high-GWP refrigerants are redirecting specification decisions in sub-500W precision cooling. Industrial chiller procurement teams now face compliance-driven exclusion of conventional compressor alternatives in laboratory and medical device segments. Electronics cooling applications in telecommunications infrastructure are responding fastest through thermoelectric retrofit specifications.
Lifecycle service contracts are displacing equipment-only transactions in North American laboratory installations. TECA Corp. and specialized service networks are capturing recurring revenue through recalibration and thermoelectric module replacement programs. Germany and the United States represent the concentrated geography where this unbundling is most visible, with procurement committees now evaluating total cost of ownership over 7-10 year horizons.
Peltier Chillers Market Segmentation
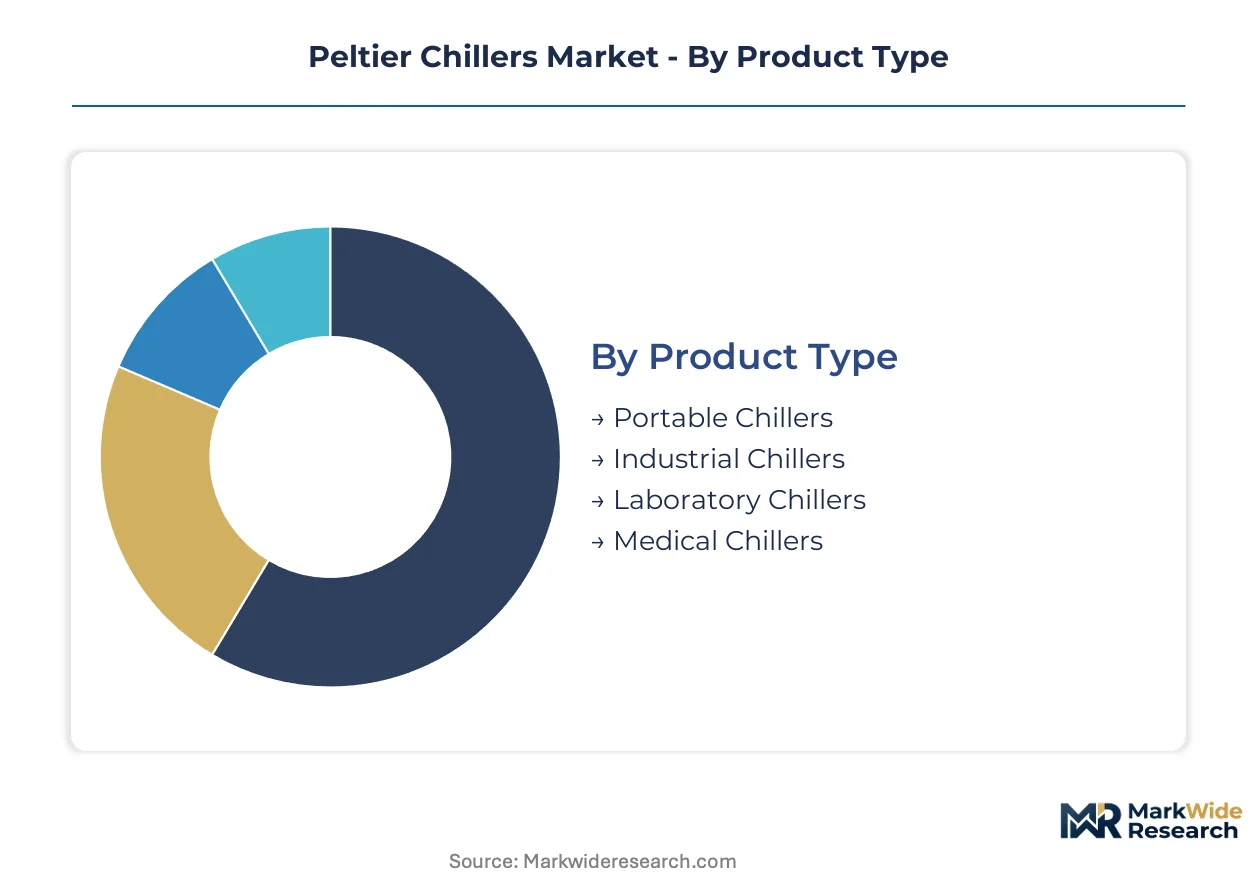
Thermoelectric cooling architectures fragment across precision requirements, thermal loads, and regulatory exposure. Each segment carries distinct service intensity profiles that reshape margin capture from initial sale through lifecycle maintenance.
Product Type:
After-sales service intensity varies dramatically across product tiers, with laboratory and medical installations demanding NIST-traceable recalibration programs that extend revenue recognition over 7-10 year horizons.
- Laboratory Chillers:Multi-stage cascaded thermoelectric modules achieve sub-ambient differentials beyond 100°C for laser system stabilization. Analytical instrumentation manufacturers in Germany and the United States specify these configurations for ±0.1°C stability requirements that exclude compressor alternatives.
- Industrial Chillers:Heavy-duty thermoelectric arrays serve semiconductor fabrication facilities in Taiwan and South Korea where EU REACH restrictions on fluorinated refrigerants have tightened conventional chiller supply chains. These units command premium positioning through 24/7 operational specifications.
- Portable Chillers:Compact solid-state units serve field diagnostics and point-of-care medical devices with refrigerant-free operation below 300W.
- Medical Chillers:FDA device classification rules for therapeutic hypothermia systems elevate compliance costs through 18-24 month certification cycles.
By volume, Portable Chillers leads. By growth pace, Laboratory Chillers is ahead.
Application:
Cost tier stratification separates high-specification precision cooling from commoditized thermal management, with electronics and medical applications occupying opposite ends of the pricing spectrum.
- Electronics Cooling:Data center edge nodes and telecommunications infrastructure sustain the largest installed base. EPA SNAP program restrictions on high-GWP refrigerants accelerate thermoelectric retrofit specifications in sub-500W capacity segments.
- Medical Devices:EU MDR conformity requirements and FDA device classification rules exclude compressor-based alternatives from precision temperature control specifications. Therapeutic hypothermia systems and diagnostic instrumentation drive concentrated demand in Germany and the United States.
- Chemical Processing:Process analytical technology deployments require stable thermal environments for reaction monitoring.
- Wine Cooling:Residential and hospitality applications prioritize silent operation and vibration-free performance over extreme precision.
Electronics Cooling dominates unit shipments. Medical Devices shows the steepest expansion trajectory.
End User:
Customer type determines procurement committee composition, with hospitals and laboratories evaluating total cost of ownership while manufacturers prioritize unit economics and supply security.
- Laboratories:Germany and the United States represent concentrated demand pockets where NIST traceable calibration mandates require solid-state cooling performance benchmarks. Recalibration and thermoelectric module replacement programs now displace equipment-only transactions.
- Hospitals:Point-of-care device integration and therapeutic hypothermia applications drive procurement through direct OEM partnerships rather than traditional distribution channels.
- Manufacturers:Semiconductor fabrication facilities scale thermoelectric cooling procurement as captive demand anchors volume commitments.
- Restaurants:Wine service and food preservation applications occupy a price-sensitive tier with limited service contract attachment rates.
Manufacturers move the highest unit volumes. Laboratories are climbing the fastest.
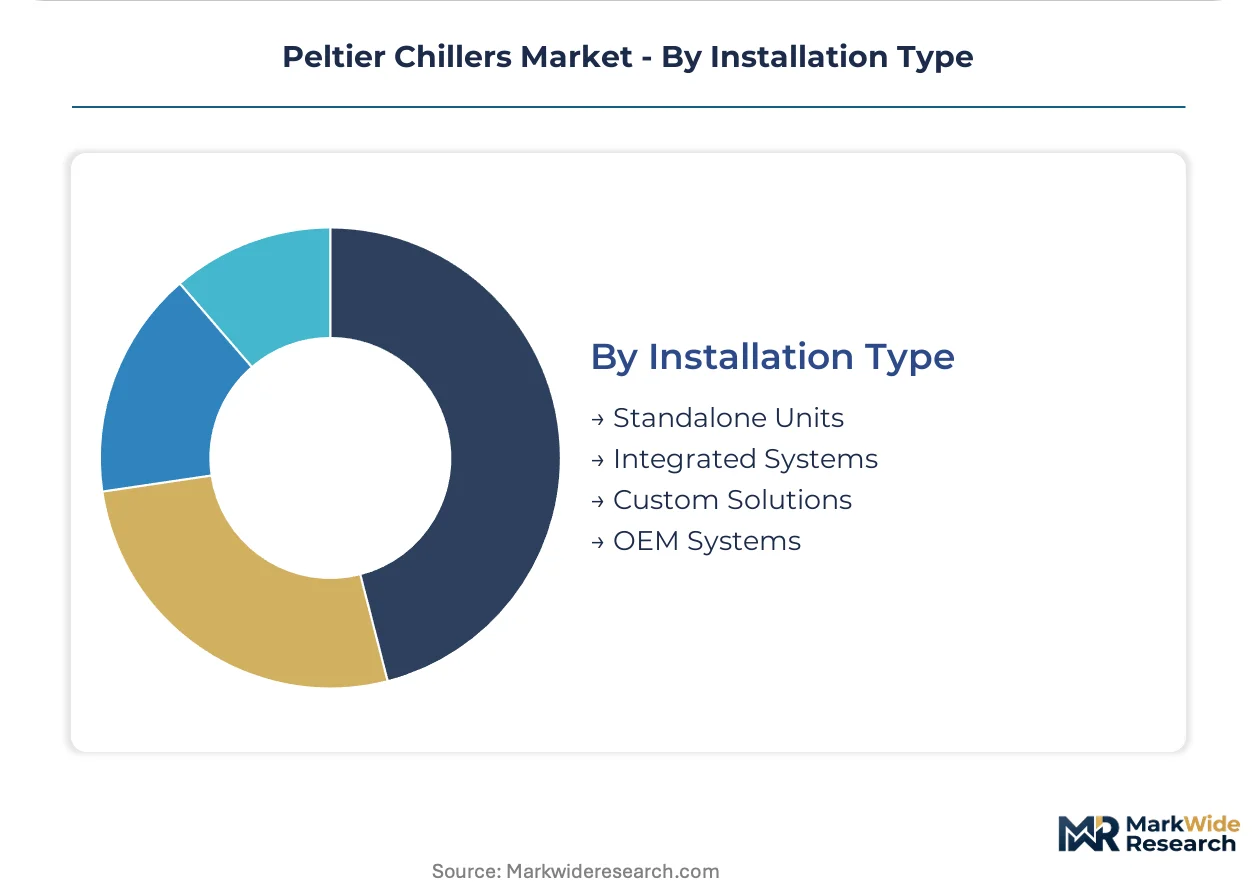
Installation Type:
Supply concentration in thermal interface engineering expertise favors integrated and custom configurations, while standalone units compete on speed-to-install and capital efficiency.
- Custom Solutions:Aerospace and defense applications demand scarce specialist capability in multi-physics simulation for thermal interface optimization. Wakefield Thermal and comparable specialists capture margin through captive engineering relationships.
- OEM Systems:Direct integration partnerships with point-of-care medical device manufacturers bypass traditional distribution, compressing channel costs while locking in specification influence.
- Standalone Units:Field diagnostics and secondary market data centers favor rapid deployment without system integration complexity.
- Integrated Systems:Semiconductor test equipment and analytical instrumentation manufacturers specify hybrid vapor chamber-thermoelectric architectures.
Standalone Units leads by deployment count. Custom Solutions gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Taiwan and South Korea demonstrate the lowest price elasticity, absorbing premium positioning for semiconductor fabrication reliability, while restaurant and residential segments in Western markets exhibit acute sensitivity to unit economics.
United States
Laboratory installations and point-of-care medical device manufacturers drive concentrated demand for NIST-traceable calibration capabilities. EPA SNAP program restrictions on high-GWP refrigerants redirect procurement committees toward solid-state alternatives below 500W. Greater Boston and San Diego host analytical instrumentation clusters where lifecycle service contracts now displace equipment-only transactions.
Germany
Process analytical technology deployments and laser system stabilization requirements sustain premium-tier procurement. EU MDR conformity requirements and REACH restrictions on fluorinated refrigerants exclude compressor-based alternatives from precision specifications. Bavaria and Baden-Württemberg anchor analytical instrumentation manufacturing where multi-stage cascaded thermoelectric modules achieve sub-ambient differentials beyond 100°C.
Taiwan
Semiconductor fabrication facilities scale thermoelectric cooling procurement as captive demand anchors volume commitments. EU REACH restrictions on fluorinated refrigerants tighten conventional chiller supply chains, forcing specification shifts. Hsinchu Science Park and Tainan Technology Industrial Park concentrate fabrication capacity where 24/7 operational specifications command premium positioning.
South Korea
Memory and logic chip manufacturing sustains industrial-scale thermoelectric array deployment. The national semiconductor strategy prioritizes supply security for precision cooling components amid geopolitical exposure. Pyeongtaek and Yongin host advanced fabrication complexes where EU F-Gas Regulation phase-down schedules accelerate solid-state adoption timelines.
China
Domestic module manufacturing and raw bismuth telluride refining clusters create input cost volatility for global supply chains. The dual carbon goals framework elevates energy efficiency scrutiny for thermal management systems. Yangtze River Delta and Pearl River Delta concentrate electronics manufacturing where edge computing infrastructure proliferation drives distributed demand below 300W.
Peltier Chillers Market Competitive Landscape
Capability concentration sits with specialized engineering houses; scale advantage sits with diversified electronics conglomerates. The vendor base stratifies across three tiers: captive semiconductor demand anchors, laboratory service network specialists, and thermal interface optimization boutiques. Consolidation pressure operates through M&A activity targeting scarce multi-physics simulation expertise, while strategic partnerships lock in OEM integration channels for point-of-care medical device manufacturers.
Within the laboratory service specialist tier, TECA Corp. occupies a position exemplifying recurring revenue capture through recalibration and module replacement programs. Samsung Electronics anchors the captive demand vector, representing semiconductor fabrication scale advantages. Wakefield Thermal sits within the thermal interface optimization archetype, specializing in aerospace and defense applications requiring scarce engineering capability.
| Leading Market Players |
|---|
| Wakefield Thermal |
| Samsung Electronics |
| Advanced Thermal Solutions (ATS) |
| Carrier |
| Daikin |
| CUI Devices |
| TECA Corp. |
| Midea |
| Delta Electronics |
| Others |
Pricing and Supply Chain Analysis
Shanghai-to-Rotterdam container freight corridors transmit cost volatility from bismuth telluride refining clusters in China directly into module pricing tiers, compressing margins for non-integrated assemblers while amplifying differentiation power for laboratory service networks that bundle lifecycle contracts.
Pricing Analysis
Long-term offtake agreements between semiconductor fabrication facilities and thermoelectric module suppliers anchor volume pricing, while spot procurement for laboratory and medical applications commands premiums tied to NIST-traceable calibration certification and FDA device classification compliance. Three-tier pricing structure across premium, standard, and economy levels separates 24/7 industrial specifications from portable field diagnostics and residential wine cooling tiers. Cost compression in standard-grade electronics cooling intensifies because EPA SNAP program restrictions on high-GWP refrigerants flood sub-500W segments with competing solid-state alternatives. Restaurant and residential segments exhibit acute price sensitivity, whereas Taiwan and South Korea fabrication buyers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Export-control regimes limiting advanced thermoelectric material processing equipment constrain capacity expansion outside China, concentrating high-purity bismuth telluride refining in Yangtze River Delta clusters while South Korea and Japan maintain specialized module assembly capabilities. Raw material dependencies center on tellurium extraction from copper anode slimes, bismuth from lead smelting byproducts, and ceramic substrates for thermal interface engineering. Single-source vulnerability in rare earth dopant supply creates exposure to geopolitical disruption. Distribution runs through direct OEM integration partnerships for medical device manufacturers and specialized service networks for laboratory installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peltier chillers sit in early-cycle expansion as EU F-Gas Regulation phase-downs force specification shifts away from compressor alternatives in precision cooling below 500W, creating penetration tailwinds across semiconductor fabrication and medical device manufacturing.
For Market Incumbents: Build captive service network moats through NIST-traceable recalibration program investments that lock laboratory end users into 7-10 year lifecycle contracts. Deepen backward integration into bismuth telluride refining to offset input cost volatility from Chinese supply concentration. Defend against emerging thermal interface optimization boutiques by acquiring multi-physics simulation expertise in aerospace and defense applications. For New Entrants and Emerging Players: Pursue point-of-care medical device OEM integration partnerships that bypass traditional distribution channels and compress customer acquisition costs. Target edge computing infrastructure in secondary US metropolitan markets where distributed demand for refrigerant-free cooling below 300W remains undersupplied. Lead with IEC 62368-1 efficiency certification to capture specification influence in audio/video and IT equipment safety standards. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with dormant thermoelectric divisions that lack dedicated service network infrastructure. Long-term viability hinges on lifecycle contract attachment rates rather than equipment-only transaction volumes. Watch for inflection when EU MDR compliance timelines compress working capital requirements for new market entrants, signaling consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Lifecycle Service Contract Expansion | TECA Corp. demonstrates recurring revenue capture through NIST-traceable recalibration programs in North American laboratory installations. |
| Backward Integration into Raw Materials | Control over bismuth telluride refining clusters mitigates geopolitical exposure from Chinese supply concentration. |
| Multi-Physics Simulation Capability Acquisition | Wakefield Thermal specializes in thermal interface optimization for aerospace and defense applications requiring scarce engineering expertise. |
| OEM Integration Partnership Development | Direct relationships with point-of-care medical device manufacturers bypass traditional distribution and lock specification influence. |
| Regulatory Certification Pre-Positioning | FDA device classification and EU MDR conformity investments create 18-24 month barriers against unqualified competitors. |
Research Methodology
Cross-validation between primary interviews with thermoelectric module design engineers, semiconductor fabrication facility procurement directors, laboratory instrumentation specialists, and medical device regulatory affairs managers anchors the qualitative findings against secondary sources including EPA SNAP program filings, EU REACH restriction updates, FDA 510(k) device classifications, and IEC standard revision drafts. Bottom-up unit shipment estimates from fabrication capacity expansions in Taiwan and South Korea triangulate against top-down market size calculations derived from bismuth telluride consumption patterns and module replacement cycle analysis.
Calibration against historical adoption curves for solid-state cooling in telecommunications infrastructure and analytical instrumentation validates growth assumptions across the projection horizon. Segmentation modeling incorporates product type tiering, application thermal load requirements, end user procurement committee composition, and installation type engineering complexity. CAGRs derive from fitted diffusion curves weighted by regulatory phase-down schedules and captive demand anchors from semiconductor fabrication capacity buildouts.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or container freight rate volatility would shift the trajectory. Forecasts reflect documented assumptions about EU F-Gas Regulation enforcement intensity and EPA SNAP program expansion scope. Material shifts in bismuth telluride export licensing regimes or therapeutic hypothermia device reimbursement policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Global Personal Cooling Device Market
Energy Management Systems
Intelligent Digital Meter Market
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
Bed Cooling System Market
Energy Management Systems
Data Center Power Management Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
Smart Water Cooler Market
Energy Management Systems
Smart Programmable Thermostat Market
Energy Management Systems
Evaporative Air Cooler Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
Asia-Pacific Energy Management System Market
Energy Management Systems
Home Energy Management System Market
Energy Management Systems
US Energy Management Systems Market
Energy Management Systems
Global Thermal Management Technologies Market
Energy Management Systems
Smart Cooling Systems Market
Energy Management Systems
Smart Utilities Management Market