
 Bed Cooling System Market | 2026-2036
Bed Cooling System Market Size, Share, and Industry Trends Forecast 2026-2036
Bed Cooling System Market Insights
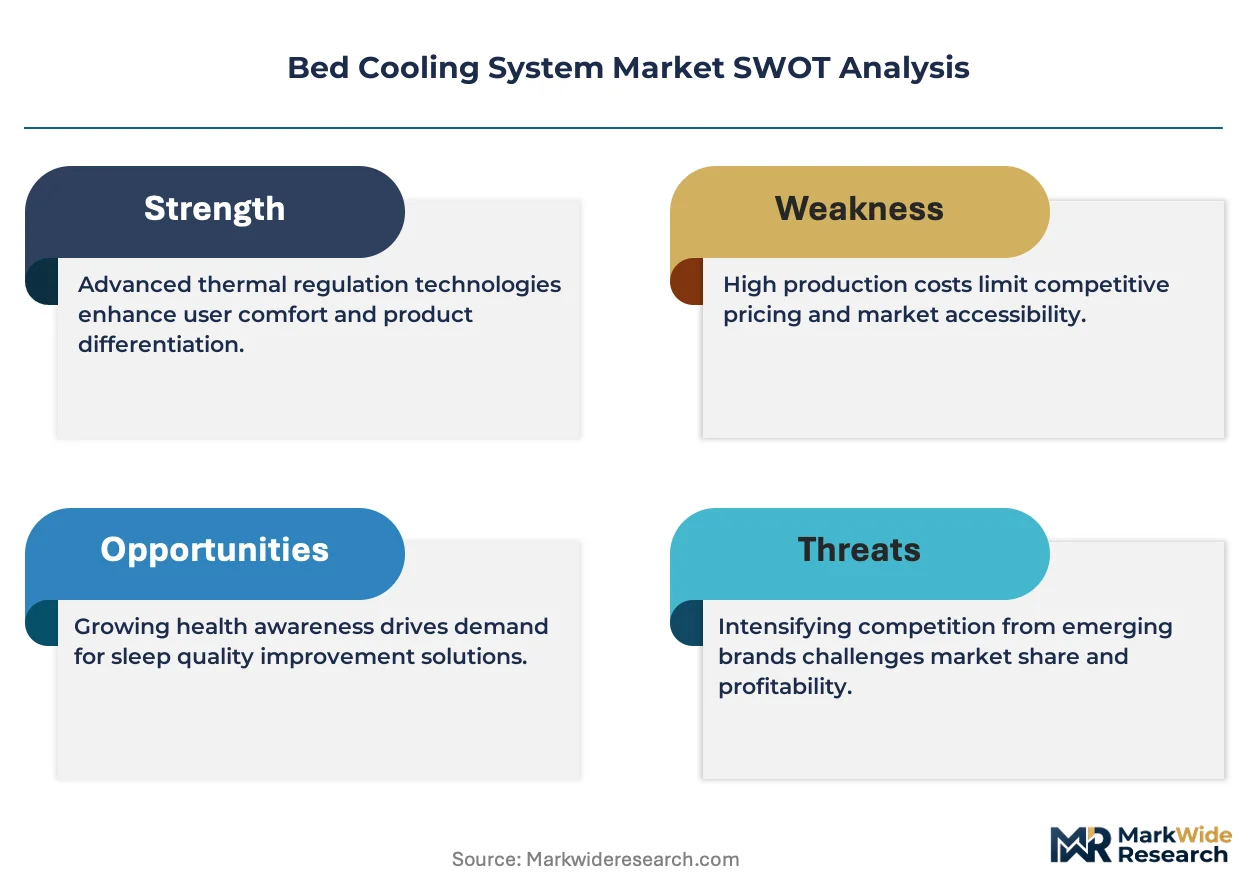
Integration of thermoelectric cooling modules with IoT-enabled sleep tracking is reshaping how bed cooling systems are engineered and sold. Eight Sleep leverages embedded biometric sensors to sustain recurring subscription revenue alongside hardware sales. BedJet anchors its position through forced-air designs that compete on price against water-based rivals. Chilipad specializes in hydro-powered mattress toppers that dominate the premium recovery-sleep segment.
A bed cooling system is a temperature-regulating sleep apparatus that employs thermoelectric elements, forced air circulation, or fluid-based heat exchange to maintain a target surface temperature between 55°F and 115°F, primarily serving consumers with sleep disorders, athletic recovery needs, or menopausal symptom management. Water-based mattresses and active airflow systems represent the most mature product categories, while gel infusion layers command narrower margins due to commoditized materials. Thermoelectric cooling technology leads in patent filings and premium pricing, whereas phase change materials attract hospitality procurement for their silent operation and minimal maintenance.
The U.S. Consumer Product Safety Commission and California's Title 20 appliance efficiency standards constrain standby power draw for plugged sleep devices, while the EU Ecodesign Directive mandates recyclable material quotas that elevate compliance costs for foam-heavy gel pads. Japan's Ministry of Economy, Trade and Industry enforces stringent electromagnetic compatibility rules that delay product launches for WiFi-connected units. Stakeholders must monitor how fragmented national efficiency codes fragment R&D budgets and whether unified IEC sleep-appliance standards emerge to simplify cross-border certification.
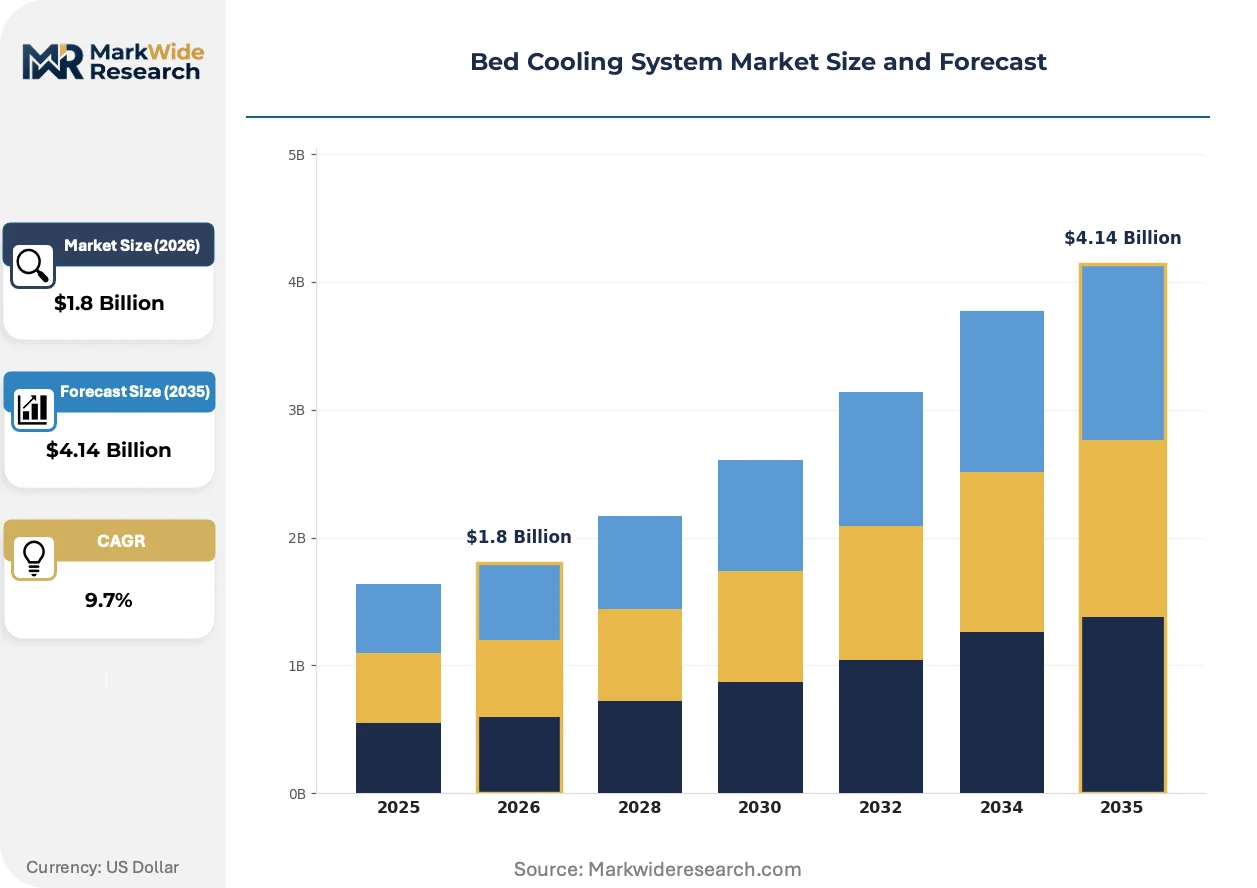
Market Dynamics
Thermoelectric cooling modules are displacing legacy compressor-based architectures across residential sleep systems, compressing unit costs while elevating energy efficiency benchmarks set by the U.S. EPA and EU Ecodesign Directive.
Growth Catalysts
- Sleep Tech Consumerization:Home users with athletic recovery protocols and menopausal symptom management are driving hardware refresh cycles. Biometric sensor integration accelerates replacement demand.
- EU Ecodesign Directive:Mandates for recyclable material quotas and standby power limits favor thermoelectric designs over foam-heavy gel pads, tilting procurement toward active cooling systems.
- German Premium Hardware Demand:Consumer willingness to pay for temperature-regulated rest exceeds European peers, concentrating early adoption of hydro-powered mattress toppers in this market.
Market Restraints
- Copper and Semiconductor Input Volatility:Thermoelectric elements depend on copper interconnects and bismuth telluride semiconductors, exposing manufacturers to mining supply shocks and rare earth processing bottlenecks.
- Japanese Electromagnetic Compatibility Delays:METI enforcement of stringent WiFi-connected unit standards extends product launch timelines by 8-14 months for IoT-enabled sleep systems.
- Passive Gel Pad Substitution:Silent, maintenance-free gel infusion layers capture hospitality procurement despite narrower margins, constraining active cooling penetration in hotel and short-term rental channels.
Strategic Opportunities
- India Residential Underpenetration:Cooling-degree-day expansion and rising disposable income create white space for forced-air systems priced below water-based alternatives in urban centers.
- Healthcare Reimbursement Pathways:FDA recognition of temperature-regulated sleep as adjunct therapy for insomnia disorders opens prescription-adjacent distribution through durable medical equipment channels.
- AI-Driven Personalization Convergence:Machine learning sleep stage prediction fused with real-time thermal adjustment enables outcome-based pricing models distinct from hardware-only revenue.
Industry Challenges
- Thermoelectric Engineering Talent Scarcity:Specialized expertise in Peltier junction optimization and heat sink design concentrates in automotive and aerospace sectors, constraining sleep-system R&D pipelines.
- Fragmented National Efficiency Codes:Divergent standby power limits across California Title 20, EU Ecodesign, and Japanese Top Runner programs fragment certification budgets and delay cross-border launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bed Cooling System Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Cooling Pads, Active Airflow Systems, Water-Based Mattresses, Gel Infusion Layers Technology: Thermoelectric Cooling, Evaporative Cooling, Phase Change Materials, Radiant Cooling End User: Home Users, Hotels, Hospitals, Hospitality Industry Sales Channel: Online Retailers, Direct Sales, Specialty Stores, Mass Merchandisers |
| Companies Covered | Orion Sleep, Helix Sleep, Eight Sleep, Saatva, Leesa, BedJet, Slumber Cloud, WinkBeds, Chilipad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bed Cooling System Market Trends and Innovations
Active cooling architectures are migrating from mechanical compression toward solid-state thermoelectric designs, while regulatory pressure on embodied carbon and standby power reshapes material selection and connectivity roadmaps.
Thermoelectric cooling technology leverages Peltier junctions to transfer heat without refrigerant circulation, enabling precise surface temperature control between 55°F and 115°F. Athletic recovery facilities and high-net-worth residential buyers are adopting these systems at accelerating pace. This migration from compressor-based cooling is compressing maintenance requirements and enabling modular form factors incompatible with legacy HVAC integration.
The EU Ecodesign Directive mandates recyclable material quotas and maximum standby power draw for plugged sleep appliances, elevating compliance costs for foam-heavy gel pad manufacturers. Industrial consequence includes accelerated R&D reallocation toward thermoelectric and forced-air architectures with minimal polymer content. Premium hydro-powered mattress toppers face margin pressure as German and French procurement teams prioritize circularity documentation over performance specifications.
Subscription-enabled hardware models are displacing one-time purchase economics across connected sleep systems. Direct-to-consumer channels and sleep clinic partnerships are replacing traditional mattress retail as primary customer acquisition paths. This behavioral shift concentrates in the United States and Germany, where recurring revenue tolerance among recovery-focused athletes and biohacking consumers exceeds other developed markets.
Bed Cooling System Market Segmentation
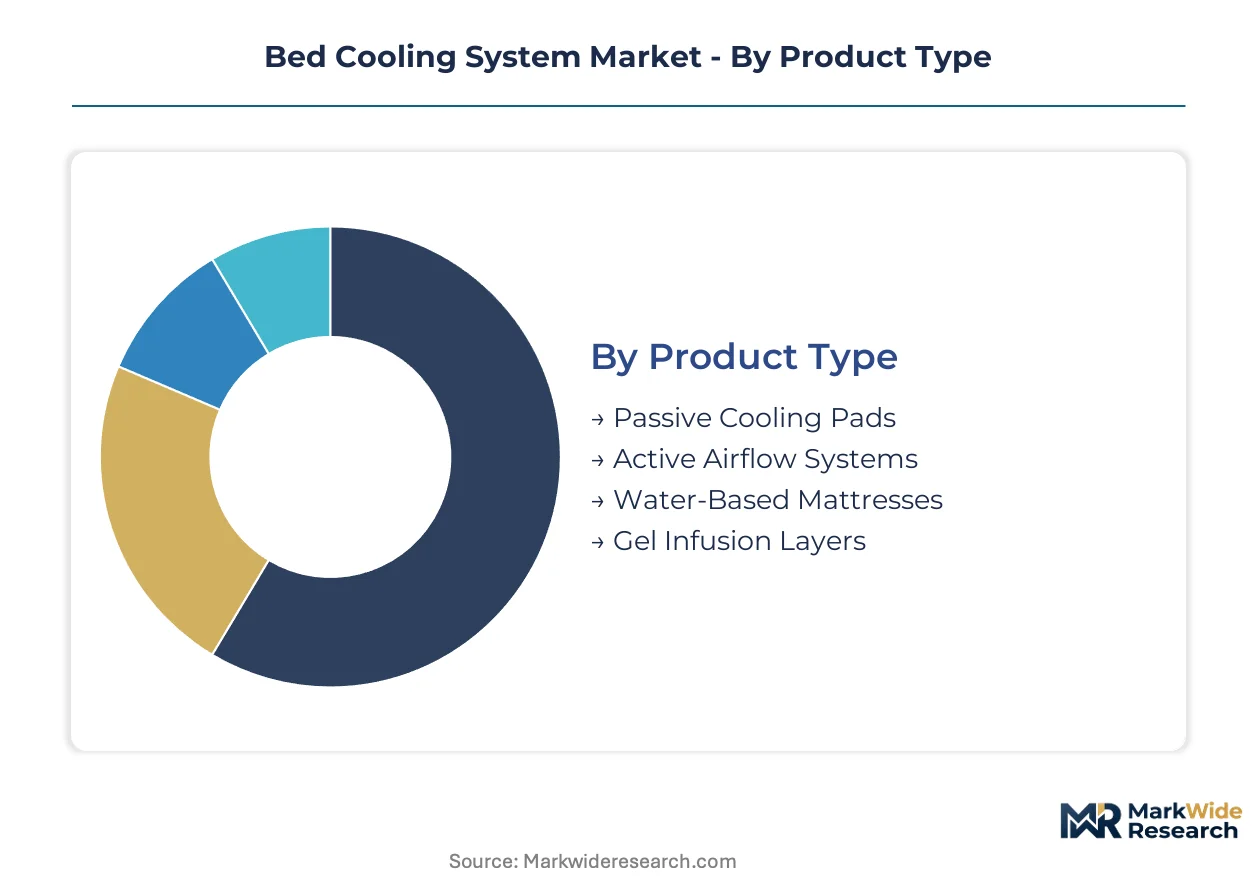
Bed cooling system segmentation reveals how technology maturity, price sensitivity, and channel economics fragment demand across four distinct dimensions. Product architecture and cooling modality determine margin profiles, while end-user context and purchase pathway shape customer acquisition costs and lifetime value calculations.
Product Type:
Cost tier stratification separates maintenance-free entry products from precision-engineered active systems with recurring service requirements.
- Passive Cooling Pads:Gel-infused foam or breathable fabric constructions deliver ambient temperature moderation without power draw. Budget-conscious households in warm climates favor these for seasonal use, though limited efficacy constrains replacement frequency and brand loyalty.
- Active Airflow Systems:Forced-air units circulate conditioned air through mattress ducts or under-bed plenums, achieving rapid temperature transitions. Athletic recovery facilities and biohacking consumers in Germany and the United States concentrate demand here, driven by programmable scheduling and lower upfront cost versus hydro-powered alternatives.
- Water-Based Mattresses:Hydro-powered mattress toppers dominate the premium recovery-sleep segment with precise 55°F-115°F control.
- Gel Infusion Layers:Silent, maintenance-free operation attracts hospitality procurement despite commoditized margins and polymer-heavy circularity challenges under EU Ecodesign.
Water-Based Mattresses commands the established base. The steepest expansion runs through Active Airflow Systems.
Technology:
Application context determines technology selection—residential precision demands differ from hospitality silence requirements and healthcare reliability standards.
- Thermoelectric Cooling:Solid-state Peltier junctions transfer heat without refrigerant circulation, enabling modular form factors and precise surface control. Patent concentration and premium pricing power concentrate here, though copper and bismuth telluride supply volatility elevates input risk.
- Phase Change Materials:Paraffin or salt hydrate microencapsulation absorbs and releases thermal energy at fixed transition temperatures. Hotel procurement teams in France and Spain prioritize these for silent operation and zero maintenance, accepting narrower performance windows.
- Evaporative Cooling:Water evaporation through wicking surfaces delivers energy-efficient cooling in dry climates.
- Radiant Cooling:Chilled surface panels exchange heat through infrared radiation rather than convection.
Thermoelectric Cooling anchors manufacturer R&D investment. Phase Change Materials is climbing the fastest as circularity documentation pressures reshape hospitality procurement.
End User:
Customer type segmentation tracks how sleep disorder prevalence, recovery protocol adoption, and operational reliability requirements diverge across settings.
- Home Users:Individual consumers with insomnia, menopausal symptoms, or athletic recovery protocols drive hardware refresh cycles and subscription attachment. Biometric sensor tolerance and recurring revenue acceptance concentrate in the United States and Germany.
- Hospitals:Patient temperature management for fever control, perioperative recovery, and burn treatment demands clinical-grade reliability. FDA recognition of temperature-regulated sleep as adjunct therapy is opening durable medical equipment distribution pathways.
- Hotels:Guest satisfaction differentiation and review economics motivate amenity investment, though capital-light gel pad substitution constrains active cooling penetration.
- Hospitality Industry:Short-term rental operators and wellness retreat venues seek scalable deployment with minimal housekeeping burden.
Home Users generates the highest absolute revenue. Hospitals is gaining share fastest as reimbursement pathways mature.
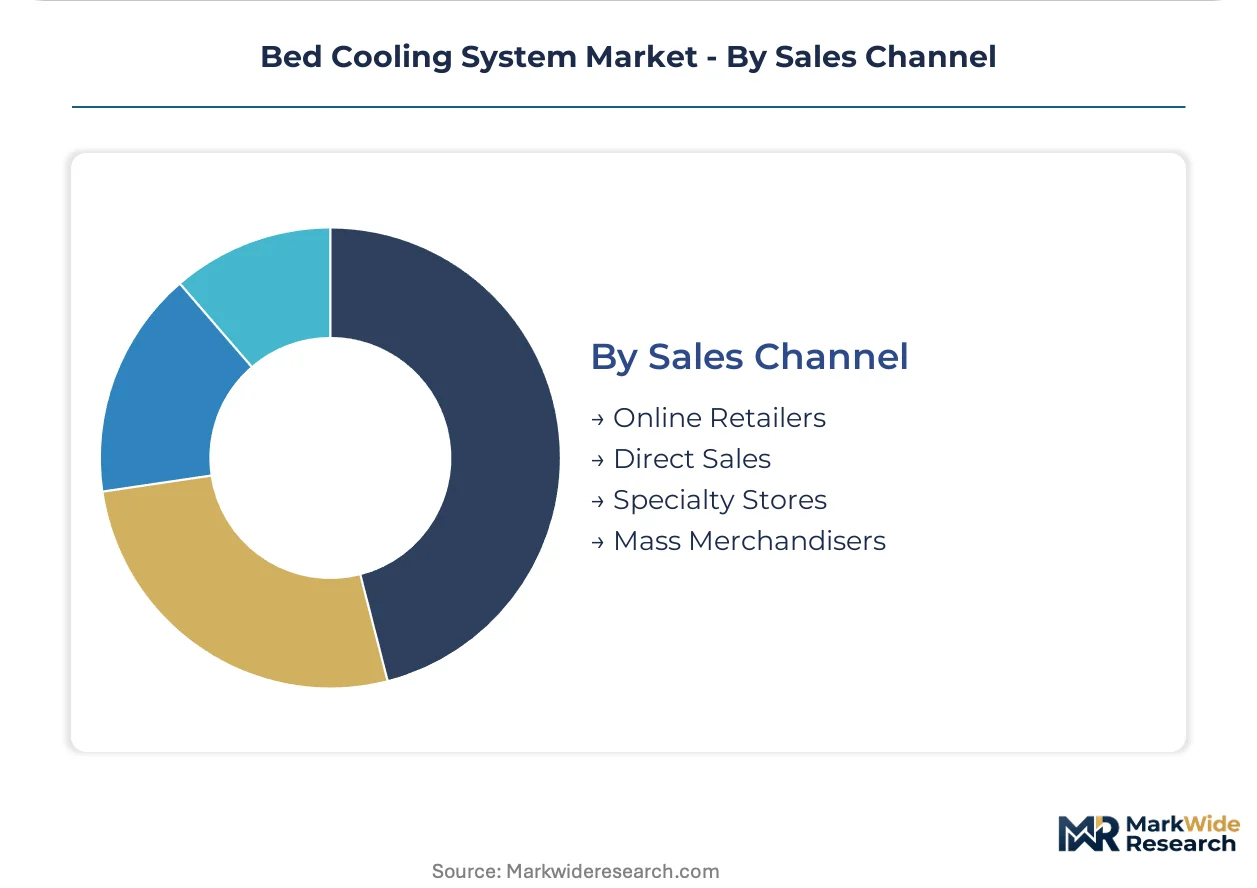
Sales Channel:
Volume concentration and margin capture diverge sharply between direct relationships and third-party retail intermediation.
- Direct Sales:Manufacturer-owned websites and sleep clinic partnerships enable outcome-based pricing, subscription attachment, and full margin retention. Customer acquisition here tolerates higher CAC due to superior lifetime value metrics.
- Online Retailers:Amazon, dedicated sleep e-commerce platforms, and health-focused marketplaces deliver scale with compressed margins. Review density and return logistics complexity challenge profitability.
- Specialty Stores:Mattress retailers and wellness boutiques provide tactile evaluation and consultative selling for premium thermoelectric systems.
- Mass Merchandisers:Big-box retail placement drives passive cooling pad volume with minimal sales support.
Online Retailers moves the highest unit volume. Direct Sales is expanding most quickly as subscription-enabled hardware economics reshape go-to-market strategy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recovery-focused athletes and biohacking consumers in the United States and Germany drive premium hardware adoption, while regulatory fragmentation across California, the EU, and Japan shapes cross-border launch strategies.
United States
Home users with athletic recovery protocols and menopausal symptom management dominate demand for biometric-integrated thermoelectric systems. The EPA energy efficiency standards and California Title 20 appliance standards constrain standby power draw for plugged sleep devices. Sleep tech startups cluster in San Francisco and Austin, where direct-to-consumer subscription models are displacing traditional mattress retail.
Germany
Consumer willingness to pay for temperature-regulated rest exceeds European peers, concentrating early adoption of hydro-powered mattress toppers. The EU Ecodesign Directive mandates recyclable material quotas that elevate compliance costs for foam-heavy gel pad manufacturers. Munich and Berlin host the densest concentration of sleep clinic partnerships driving prescription-adjacent distribution.
Japan
Aging demographics and insomnia prevalence create demand for clinical-grade reliability in temperature-regulated sleep systems. METI enforces stringent electromagnetic compatibility rules that delay product launches for WiFi-connected units by 8-14 months. Osaka-based electronics fabricators specialize in Peltier junction optimization for modular residential form factors.
India
Cooling-degree-day expansion and rising disposable income in urban centers create white space for forced-air systems priced below water-based alternatives. The Bureau of Indian Standards and Central Electricity Authority efficiency codes are beginning to address appliance standby power. Mumbai and Bangalore emerge as test markets for entry-tier active cooling targeting apartment-dwelling professionals.
United Kingdom
Biohacking consumers and wellness-focused hospitality operators drive demand for silent, maintenance-free phase change materials. Post-Brexit regulatory divergence from EU Ecodesign creates certification complexity for cross-channel suppliers. London and Manchester concentrate direct-to-consumer marketing investment for subscription-enabled hardware models.
Bed Cooling System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that fragments between subscription-enabled hardware platforms and component-agnostic mattress retailers. The vendor base organizes around three strategic archetypes: biometric-integrated sleep tech platforms, forced-air price competitors, and hydro-powered premium recovery specialists. M&A activity concentrates on sensor technology acquisitions and sleep clinic network buyouts. Geographic expansion into German and Japanese markets dominates partnership announcements.
Within the subscription-platform tier, Eight Sleep exemplifies recurring revenue architecture through embedded biometric hardware. Among forced-air specialists, BedJet occupies a position competing on upfront price against water-based alternatives. Chilipad anchors the premium hydro-powered recovery segment with precise temperature control targeting athletic facilities. These three players represent divergent bets on customer acquisition economics: hardware-margin versus subscription-lifetime-value versus premium performance pricing.
| Leading Market Players |
|---|
| Orion Sleep |
| Helix Sleep |
| Eight Sleep |
| Saatva |
| Leesa |
| BedJet |
| Slumber Cloud |
| WinkBeds |
| Chilipad |
| Others |
Pricing and Supply Chain Analysis
Copper and bismuth telluride processing capacity concentrates in Chinese and German specialty chemical facilities, tethering thermoelectric module costs to rare earth supply quotas and downstream margin capture in biometric-integrated sleep platforms. This upstream concentration forces active cooling manufacturers to absorb input volatility or pass through to subscription-tolerant home users in the United States and Germany.
Pricing Analysis
Cost-plus contracts with copper and semiconductor indexation dominate component procurement for thermoelectric bed cooling systems. Three-tier pricing structure across premium hydro-powered, standard forced-air, and economy passive gel tiers separates precision temperature control from maintenance-free alternatives. Pricing pressure stems from EU Ecodesign circularity documentation costs elevating compliance spend for foam-heavy gel pad manufacturers. Home users with athletic recovery protocols show least price sensitivity, while hospitality procurement teams exhibit acute elasticity favoring silent phase change materials despite narrower performance windows.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Japanese electronics fabricators in Osaka stabilize Peltier junction procurement for modular residential form factors. Manufacturing concentrates in China for thermoelectric element assembly, Germany for precision hydro-powered mattress topper fabrication, and the United States for IoT-enabled biometric integration. Raw material dependencies center on copper interconnects, bismuth telluride semiconductors, and medical-grade silicone tubing for water-based architectures. Single-source vulnerability in rare earth processing creates exposure to export quota shocks. Distribution runs through direct-to-consumer channels and sleep clinic partnerships for premium tiers, with Amazon and dedicated wellness e-commerce platforms handling volume for forced-air entry products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bed cooling system market sits in early-cycle expansion as FDA recognition of temperature-regulated sleep for insomnia disorders unlocks prescription-adjacent distribution channels previously inaccessible to consumer hardware.
For Market Incumbents: Insulate premium positioning by deepening backward integration into Peltier junction optimization and securing exclusive sleep clinic partnerships in Munich and Berlin. Counter forced-air price competition from emerging entrants through biometric sensor differentiation and outcome-based subscription pricing that hardware-only rivals cannot replicate. Prioritize FDA durable medical equipment pathway investment ahead of reimbursement standardization. For New Entrants and Emerging Players: Establish a beachhead in India's urban apartment-dwelling professional segment with forced-air systems priced below hydro-powered alternatives, exploiting cooling-degree-day expansion and nascent Bureau of Indian Standards efficiency code windows. Target hospitality procurement in France and Spain with phase change material offerings that satisfy EU Ecodesign circularity documentation without active cooling maintenance burdens. Deploy white-label partnerships with short-term rental operators to minimize customer acquisition costs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed sleep tech platforms that have scaled subscription revenue but face thermoelectric engineering talent scarcity constraining R&D velocity. Long-term viability favors manufacturers with captive sensor technology and clinic network density over pure hardware-margin competitors. Watch for FDA reimbursement pathway standardization as the inflection signal separating adjunct therapy recognition from durable medical equipment coverage expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Sensor Integration | Eight Sleep's embedded hardware architecture sustains recurring subscription revenue alongside unit sales. |
| Sleep Clinic Partnership Network | Prescription-adjacent distribution in Germany concentrates early adoption among recovery-focused athletes. |
| Backward Integration into Peltier Manufacturing | Osaka-based fabricators specializing in junction optimization reduce rare earth processing exposure. |
| EU Ecodesign Compliance Certification | Recyclable material quotas elevate barriers against foam-heavy gel pad competitors in French procurement. |
| Direct-to-Consumer Subscription Launch | Austin and San Francisco startup clusters displace traditional mattress retail with outcome-based pricing models. |
Research Methodology
A spread of perspectives from sleep tech product managers, thermoelectric engineering specialists, hotel procurement directors, and durable medical equipment distributors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, EU Ecodesign Directive implementation guidance, EPA appliance efficiency standards, and METI electromagnetic compatibility rulings. Bottom-up unit economics from subscription-enabled hardware models triangulated against top-down market sizing from sleep disorder prevalence data and athletic facility capital expenditure surveys.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling adoption curves against thermoelectric module production capacity and rare earth supply quotas. Segmentation dimensions included cooling modality, technology architecture, end-user context, and purchase pathway. CAGRs derived from hardware refresh cycle analysis and biometric sensor replacement rates. Forecast inputs incorporated EU circularity documentation cost trajectories and FDA reimbursement pathway maturation timelines.
Sensitivities concentrate around copper and bismuth telluride price volatility, Japanese electromagnetic compatibility approval delays, and fragmentation of national efficiency codes across California Title 20, EU Ecodesign, and METI programs. Forecasts reflect documented assumptions about sleep tech consumerization velocity and clinic partnership scalability. Macroeconomic contraction, regulatory harmonization failure, or breakthrough passive cooling materials would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Shared Power Bank Market
Energy Management Systems
Energy Management in Data Centers Market
Energy Management Systems
AI-Driven Lighting Controls Market
Energy Management Systems
Airflow Management Market
Energy Management Systems
Global Personal Cooling Device Market
Energy Management Systems
Smart Water Cooler Market
Energy Management Systems
North America Residential Lighting Control System Market
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
Smart HVAC Controls Market
Energy Management Systems
Africa Digital Showers Market
Energy Management Systems
Intelligent PDU Market
Energy Management Systems
North America Energy Management Systems Market
Energy Management Systems
IoT Smart Gas Meter Market
Energy Management Systems
Global Thermal Management Technologies Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
Mobile Metering System Market