
 Smart Water Cooler Market | 2026-2036
Smart Water Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Water Cooler Market Outlook
Market Context
A shift from single-source procurement to multi-vendor supply strategies is broadening vendor access for mid-sized commercial buyers. Igloo leverages its established cold-chain logistics network to sustain distribution advantages across North American retail channels. Avalon competes through dedicated commercial leasing programs that anchor recurring revenue streams in workplace hydration. Brio differentiates via modular filtration architectures that extend product lifecycles across hospitality installations.
Technical Definition and Segment Structure
A smart water cooler integrates temperature control systems with IoT connectivity, UV or carbon filtration stages, and usage telemetry typically operating between 38°F and 185°F output ranges for commercial and residential hydration. Freestanding units dominate installed base volumes while IoT-enabled technology commands premium positioning through predictive maintenance and consumption analytics capabilities. The commercial end-user segment leads absolute value contribution as facility managers prioritize connected hydration infrastructure, though residential countertop formats are gaining traction among urban apartment dwellers seeking space-efficient purification.
Regulatory Environment
The U.S. EPA and FDA jointly govern drinking water safety and contact-material compliance for hydration equipment sold in American jurisdictions. China's SAMR enforces GB standards for electronic water processing appliances while the EU's RoHS and REACH frameworks restrict hazardous substances in thermoelectric cooling assemblies. Stakeholders must monitor evolving state-level lead remediation mandates and building code integrations that will determine product certification requirements for connected hydration systems.
Market Dynamics
Corporate wellness mandates and IoT building integration requirements are converging to reshape procurement criteria for connected hydration infrastructure, elevating predictive maintenance and consumption analytics from optional features to baseline specifications.
Growth Catalysts
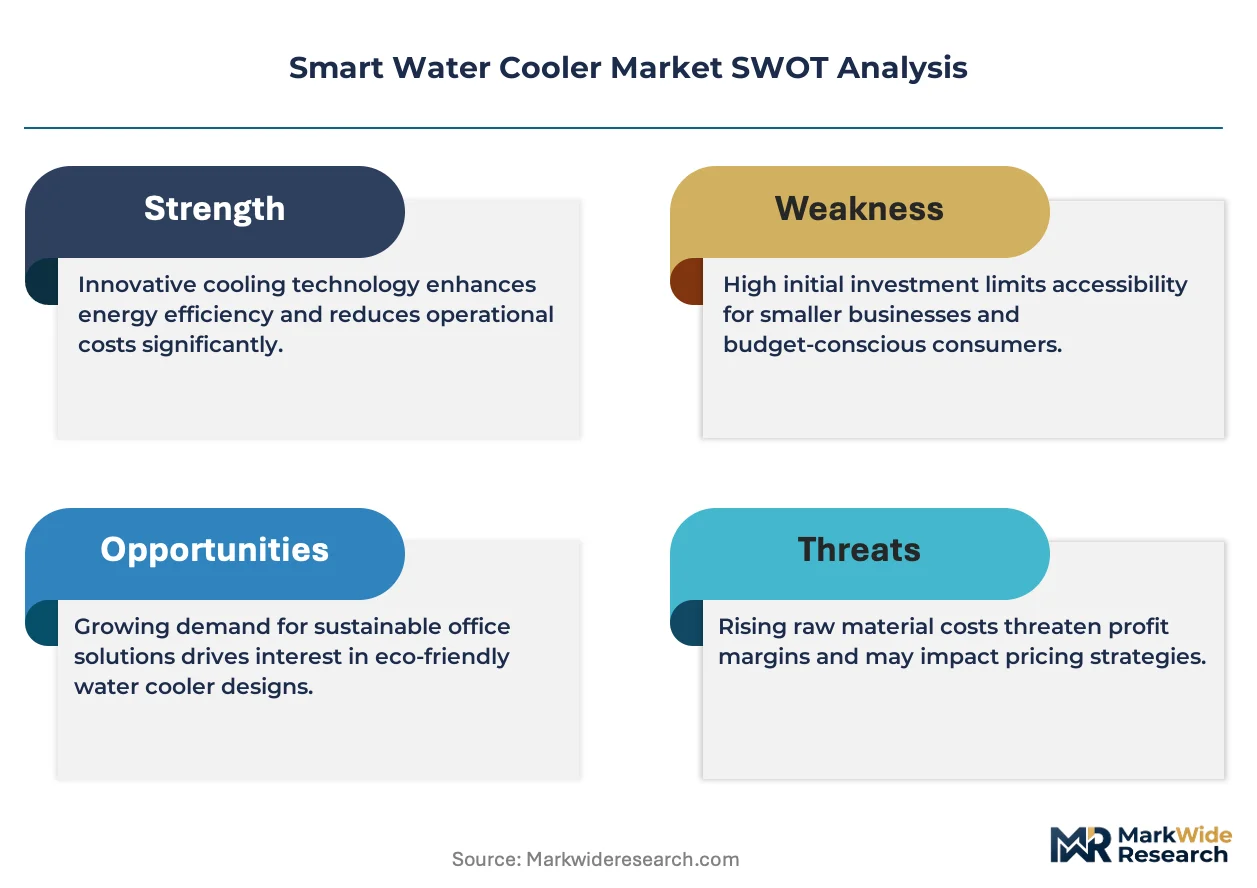
- EPA Lead and Copper Rule revisions:Public-facing facilities across the United States face compelled filtration upgrades, accelerating replacement cycles for legacy equipment in schools, municipal buildings, and healthcare settings.
- China's tier-one smart building mandates:Beijing, Shanghai, and Shenzhen now require IoT-enabled utility infrastructure in new commercial construction, embedding smart water coolers as standard building systems rather than discretionary amenities.
- UV-C LED sterilization modules:Solid-state ultraviolet technology eliminates mercury-based lamp disposal costs while extending maintenance intervals, reducing total cost of ownership for high-traffic installations.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate microcontroller and sensor chip fabrication, exposing cooler manufacturers to allocation volatility and extended lead times for IoT-enabled units.
- Refrigerant input cost volatility:R290 propane and R600a isobutane prices fluctuate with petrochemical feedstock markets, compressing margins on thermoelectric cooling assemblies during energy price spikes.
- RoHS substance restrictions:EU REACH and RoHS frameworks limit lead solder and certain flame retardants in electronic assemblies, forcing redesign cycles that delay product launches in European markets.
Strategic Opportunities
- India's commercial real estate expansion:Bangalore, Hyderabad, and Mumbai are adding Class A office stock faster than hydration infrastructure deployment, creating first-mover advantages for connected cooler providers.
- Subscription-based sensor-as-a-service models:Facility management platforms bundle water quality monitoring with cooler hardware, converting capital expenditures into recurring operational budgets for mid-market buyers.
- EU F-Gas Regulation phase-down:The progressive ban on high-GWP refrigerants creates replacement demand for hydrocarbon-based cooling systems in existing installed bases across Germany, France, and Italy.
Industry Challenges
- Embedded systems firmware talent scarcity:Secure over-the-air update architectures require specialized IoT security expertise that competes with automotive and medical device sectors for limited engineering pools.
- Multi-jurisdiction certification complexity:NSF/ANSI 42, 53, and 401 standards in the United States, GB standards under China's SAMR, and CE marking under EU MDR create parallel testing timelines that extend product launch windows.
- Legacy building management system integration:BACnet and Modbus protocol fragmentation across existing HVAC infrastructure forces custom middleware development for unified facility dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Water Cooler Market |
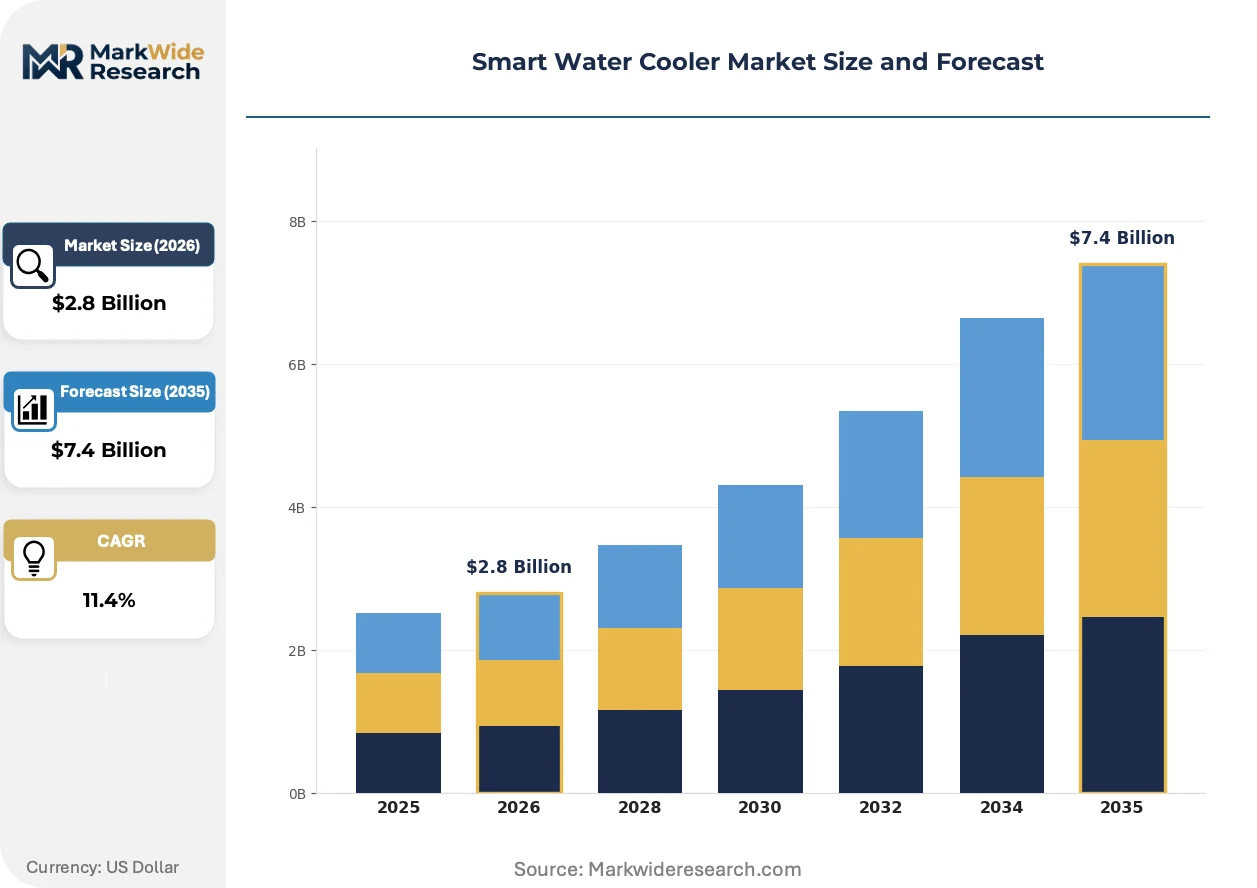
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Wall-Mounted, Countertop, Bottled Technology: IoT-Enabled, Sensor-Based, Thermoelectric, Compressor End User: Residential, Commercial, Industrial, Hospitality Installation Type: Self-Contained, Connected, Standalone, Built-In |
| Companies Covered | Igloo, Costway, Brio, Myvision, Euhomy, Avalon, Frigidaire, CozyBlue, Primo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Water Cooler Market Strategic Shifts
Filtration technology convergence with building automation protocols is redefining product architecture, while regulatory pressure on refrigerants and materials compliance accelerates hardware refresh cycles across installed bases.
Multi-stage carbon block and reverse osmosis hybrid systems now dominate premium commercial specifications, replacing single-technology approaches. Facility managers in healthcare and education verticals specify these configurations to meet stringent contaminant reduction targets. This technology is expanding into mid-market workplace installations as leasing programs absorb upfront capital barriers.
REACH substance restrictions and RoHS hazardous substance limits are tightening permissible material compositions in thermoelectric assemblies. European manufacturers must reformulate solder joints and thermal interface materials to maintain market access. The commercial segment bears primary compliance costs, passing material substitution expenses through three-tier pricing structures that separate premium-certified from standard-tier offerings.
Service unbundling from hardware procurement is compressing traditional equipment ownership models. Corporate buyers now prioritize operators offering predictive filter replacement and remote diagnostics over capital purchase arrangements. This behavioral shift concentrates fastest in United States coastal metro markets where facility outsourcing contracts dominate commercial real estate management.
Smart Water Cooler Market Segmentation
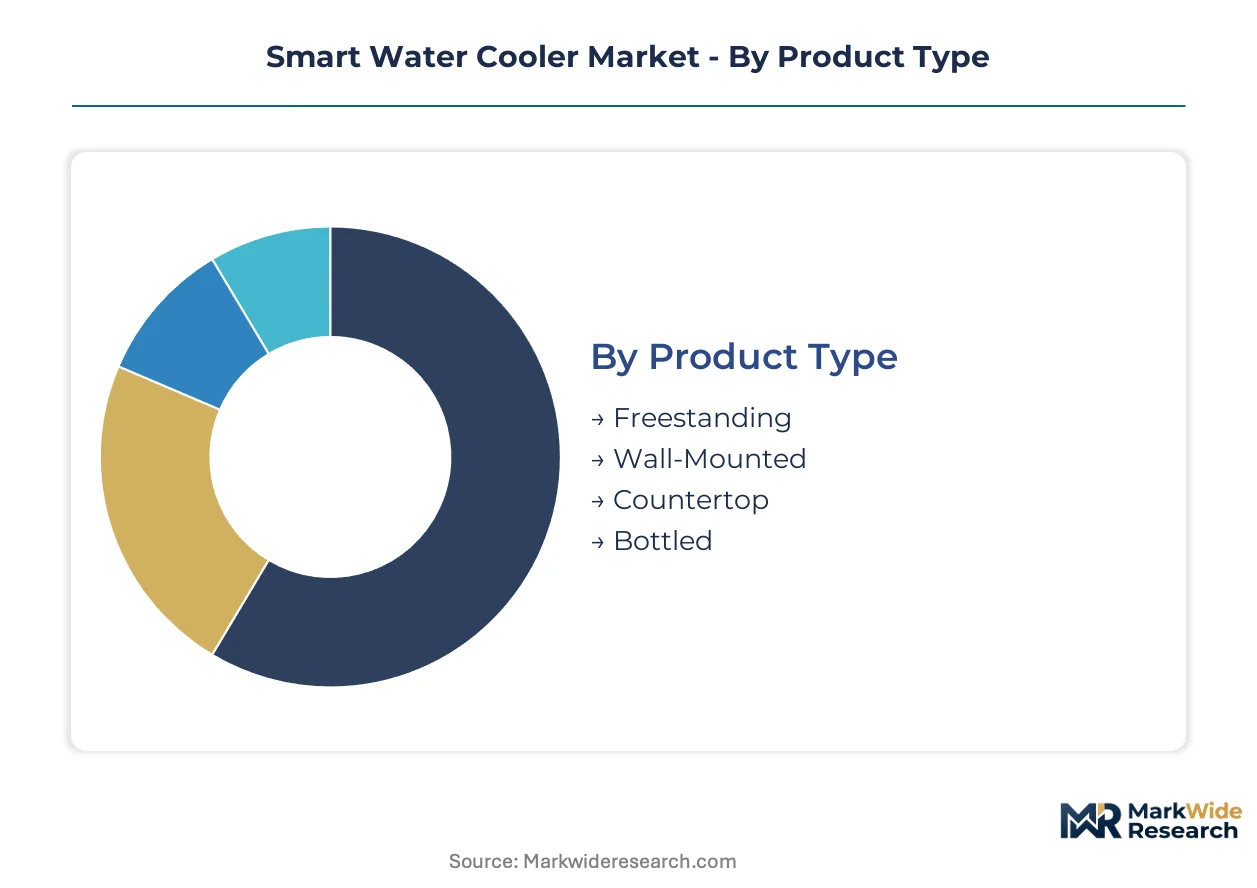
Segmentation in the smart water cooler market reveals distinct procurement patterns across hardware formats, connectivity architectures, and facility integration requirements. Buyers prioritize different specifications based on deployment scale, building infrastructure, and regulatory compliance obligations.
Product Type:
Temperature control mechanisms and spatial constraints define the specification axis across physical form factors.
- Freestanding:These floor-standing units integrate multi-stage filtration with 38°F to 185°F output ranges and typically accommodate 5-gallon bottle or direct-plumb configurations. Demand concentrates in U.S. school districts and municipal buildings where EPA Lead and Copper Rule compliance mandates replacement of legacy fountains. Facility managers specify these for high-traffic corridors requiring minimal installation complexity.
- Countertop:Compact units under 18 inches in height deploy reverse osmosis or carbon block filtration for space-constrained environments. China's tier-one cities—Beijing, Shanghai, Shenzhen—drive adoption through smart building integration mandates that embed these as standard apartment fixtures rather than optional appliances.
- Wall-Mounted:Bracket-fixed systems eliminate floor footprint while delivering bottle-free hydration through plumbed connections. These suit healthcare corridors and educational facilities requiring ADA-compliant accessibility.
- Bottled:Traditional dispenser formats using 3- to 5-gallon refillable containers persist in regions with unreliable municipal infrastructure and temporary installations.
Mature deployment sits with freestanding units in North American commercial retrofits. Newer deployment is concentrated in countertop formats across China's urban residential stock.
Technology:
Cost tier differentiation separates premium connected systems from baseline thermal management offerings.
- IoT-Enabled:Microcontroller-driven platforms with Wi-Fi or Bluetooth connectivity transmit usage telemetry, filter life data, and maintenance alerts to facility management dashboards. Predictive maintenance capabilities command 40-60% price premiums over non-connected alternatives. Corporate wellness mandates in U.S. coastal metros accelerate specification of these units as employee amenity infrastructure.
- Thermoelectric:Peltier-effect cooling assemblies operate without compressors, enabling silent operation and refrigerant-free compliance with EU F-Gas Regulation phase-down requirements. These dominate European hospitality installations where noise restrictions and environmental regulations constrain mechanical alternatives.
- Sensor-Based:Ultraviolet-C LED or turbidity sensors monitor water quality in real-time, triggering filter bypass or maintenance alerts without full IoT connectivity. These occupy mid-market positioning for buyers seeking quality assurance without subscription fees.
- Compressor:Conventional vapor-compression refrigeration delivers rapid cooling capacity for high-volume environments. Energy efficiency regulations in multiple jurisdictions are compressing margins on these legacy architectures.
Volume leadership belongs to compressor-based units in price-sensitive segments. Margin expansion concentrates fastest in IoT-enabled platforms through recurring sensor-as-a-service revenue streams.
End User:
Application context determines specification priority across hydration infrastructure deployment.
- Commercial:Workplace installations specify connected units with consumption analytics supporting corporate sustainability reporting and wellness program documentation. Leasing programs from specialized operators convert capital expenditure to operational budgets, accelerating replacement cycles in Class A office buildings.
- Residential:Urban apartment dwellers prioritize countertop formats with space-efficient footprints and direct-plumb or pour-through filtration. China's smart home integration mandates embed these as standard fixtures in new construction.
- Hospitality:Hotels and restaurants require NSF/ANSI-certified multi-stage systems meeting stringent contaminant reduction targets for guest-facing deployment. Aesthetic customization and quiet operation dominate procurement criteria.
- Industrial:Manufacturing facilities deploy heavy-duty units with high-capacity filtration for workforce hydration in environments where municipal supply quality varies.
Revenue concentration sits with commercial end users through enterprise-scale procurement contracts. Steepest expansion trajectory appears in residential countertop adoption among Asia-Pacific urban consumers.
Installation Type:
Integration depth with building infrastructure separates self-sufficient deployments from connected facility systems.
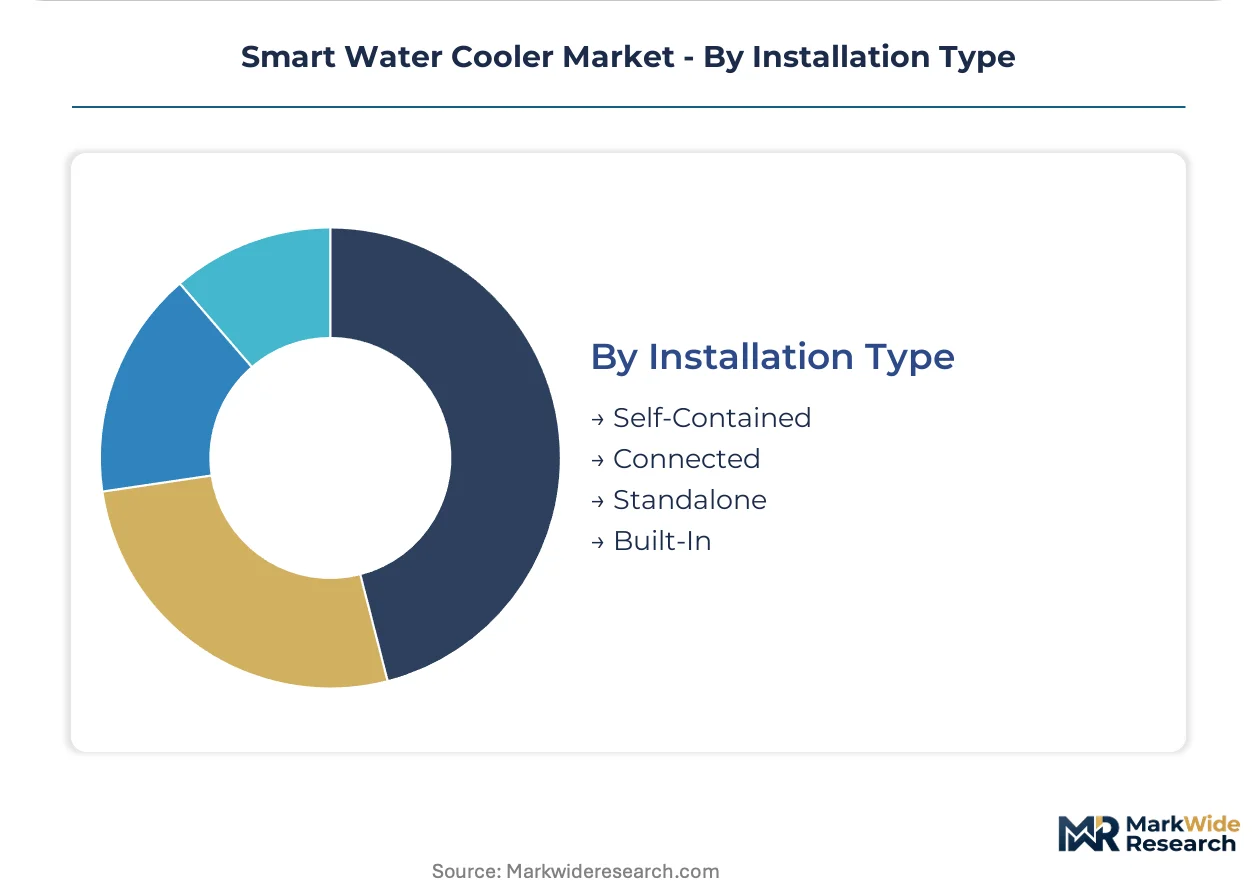
- Connected:BACnet or Modbus protocol integration enables unified facility dashboards combining HVAC, lighting, and hydration telemetry. These require custom middleware development due to protocol fragmentation across legacy building management systems.
- Self-Contained:Independent units with onboard filtration, cooling, and dispensing require no external plumbing or electrical beyond standard outlet connections. These dominate retrofit installations and temporary deployments.
- Standalone:Bottled or bottle-free units operating without network connectivity occupy budget-tier positioning in regions with limited smart building penetration.
- Built-In:Cabinet-integrated or architectural millwork-embedded systems specified during new construction or major renovation, requiring coordinated MEP design.
Specification maturity sits with self-contained formats across replacement cycles. Integration investment concentrates in connected installations within China's smart building mandates and U.S. corporate campus developments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refrigerant-grade propane feedstock from the U.S. Gulf Coast petrochemical corridor anchors thermoelectric cooling supply chains serving North American and European assembly operations. This concentration shapes regional production economics and cross-border component flows.
United States
Corporate wellness mandates from Fortune 500 employers accelerate connected hydration infrastructure deployment across Class A office buildings. The EPA's Lead and Copper Rule revisions compel filtration upgrades in public schools and municipal facilities. Dallas-Fort Worth and Atlanta metropolitan clusters concentrate retrofit demand from legacy fountain replacement programs.
China
Smart building integration mandates in tier-one cities embed IoT-enabled coolers as standard apartment fixtures rather than discretionary appliances. SAMR enforces GB standards for electronic water processing appliances with tightening compliance timelines. Beijing, Shanghai, and Shenzhen construction codes now require connected utility infrastructure in new commercial developments.
Germany
EU F-Gas Regulation phase-down drives hydrocarbon refrigerant adoption in thermoelectric assemblies across hospitality installations. ECHA REACH restrictions on hazardous substances force solder joint reformulation in cooling module production. Bavaria and Baden-Württemberg industrial clusters concentrate precision thermoelectric component manufacturing for European distribution.
India
Commercial real estate expansion in Bangalore, Hyderabad, and Mumbai outpaces hydration infrastructure deployment, creating specification gaps in new Class A stock. BIS certification requirements for electronic appliances establish entry barriers for unqualified imports. Maharashtra and Karnataka state building codes are beginning to reference smart utility integration in premium commercial developments.
Japan
Space-constrained urban residential patterns favor compact countertop formats with direct-plumb filtration in Tokyo and Osaka metropolitan areas. METI energy efficiency standards constrain compressor-based cooling system specifications. Kanto and Kansai industrial corridors maintain precision sensor and microcontroller component supply for regional assembly operations.
Smart Water Cooler Market Competitive Environment
Capacity expansion dominates the current landscape as established cold-chain distributors and appliance specialists scale IoT-enabled assembly lines to capture corporate procurement contracts. The vendor base organizes across three tiers: legacy cold-chain distributors with established logistics networks, appliance OEMs diversifying into connected hydration, and emerging specialists in sensor-as-a-service business models. M&A activity concentrates among logistics-enabled players acquiring filtration technology capabilities, while strategic partnerships between cooler manufacturers and facility management platforms accelerate subscription revenue conversion.
Among North American cold-chain distributors, Igloo leverages established retail channel relationships to sustain volume positioning across replacement cycles. Avalon and Brio occupy distinct archetype positions within the connected hydration segment—Avalon through commercial leasing program structures that convert capital expenditure to operational budgets, and Brio via modular filtration architectures that extend product lifecycles across hospitality verticals. These three entities exemplify the strategic divergence between logistics-scale, financing-innovation, and technology-modularity competitive vectors currently reshaping procurement relationships with facility managers and corporate buyers.
| Leading Market Players |
|---|
| Igloo |
| Costway |
| Brio |
| Myvision |
| Euhomy |
| Avalon |
| Frigidaire |
| CozyBlue |
| Primo |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up cold-chain distributors anchor supply behavior through captive logistics networks that compress delivery costs while enforcing pricing discipline across replacement cycles. Their consolidation of warehousing and last-mile infrastructure feeds directly into three-tier pricing structures that separate premium IoT-enabled units from standard compressor-based and economy bottled alternatives.
Pricing Analysis
Warranty and predictive maintenance bundling now commands 40-60% price premiums over unbundled hardware transactions, with subscription-based sensor-as-a-service models converting capital expenditure to recurring operational budgets. Price differentiation rests on certification grade—NSF/ANSI 42, 53, and 401 tiers—and volume scale procurement from facility management platforms. Cost compression in standard-tier compressor units is intensifying because refrigerant input cost volatility from petrochemical feedstock markets squeezes assembly margins. Mid-sized commercial buyers exhibit highest price sensitivity, while Class A office developers prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Freight cost escalation from Asia-Pacific component origins to North American assembly points is reshoring thermoelectric module production toward Mexico and Texas corridor facilities. Taiwan and South Korea dominate microcontroller and sensor chip fabrication, while China concentrates carbon block filtration media and UV-C LED sterilization module supply. Single-source vulnerability in semiconductor allocation exposes cooler manufacturers to extended lead times for IoT-enabled units. Distribution runs through cold-chain logistics networks anchored by established retail channel relationships, with direct procurement from facility management platforms gaining share in coastal metro markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into filtration media production and captive sensor module assembly represents the decisive upstream lever as refrigerant cost volatility and semiconductor allocation constraints reshape competitive economics.
For Market Incumbents: To counter emerging sensor-as-a-service specialists eroding hardware margins, secure backward integration into UV-C LED and carbon block filtration component production. Anchor channel control through exclusive leasing program structures with Class A office developers, converting replacement cycle visibility into recurring revenue lock-in. For New Entrants and Emerging Players: Capture specification gaps in India's Class A commercial real estate expansion across Bangalore, Hyderabad, and Mumbai where hydration infrastructure deployment lags construction completion. Prioritize countertop formats with direct-plumb integration for China's tier-one residential stock, leveraging domestic contract manufacturing partnerships to bypass import certification barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap filtration technology specialists in Germany and Bavaria industrial clusters with reformulated REACH-compliant solder joint capabilities. Long-term viability hinges on sensor firmware talent acquisition and predictive maintenance platform integration. Watch EU F-Gas Regulation enforcement intensity as inflection indicator for hydrocarbon refrigerant replacement demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Filtration Technology Acquisition | Secures captive supply of carbon block media from German precision manufacturers facing REACH compliance redesign costs. |
| Sensor-as-a-Service Platform Launch | Converts capital expenditure to recurring budgets for U.S. coastal metro facility management outsourcing contracts. |
| Hydrocarbon Refrigerant Transition | Aligns product portfolios with EU F-Gas Regulation phase-down requirements across German and Italian hospitality installations. |
| India Distribution Partnership | Establishes first-mover positioning in Bangalore and Mumbai Class A office stock ahead of hydration infrastructure deployment. |
| Smart Building Protocol Integration | Enables BACnet and Modbus middleware development for unified facility dashboards in China's tier-one construction mandates. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across facility managers, cold-chain distribution executives, filtration technology R&D directors, and commercial real estate developers. EPA Lead and Copper Rule documentation, China's SAMR GB standard publications, EU ECHA REACH restriction updates, and NSF/ANSI certification databases provided regulatory validation. Bottom-up unit shipment modeling triangulated against top-down market value estimates from refrigeration equipment trade flows.
Granularity-level modeling operated at product type, technology architecture, end-user vertical, and installation configuration dimensions across the analysis window. CAGRs derived from segment-level volume trajectories weighted by regional construction permit data and corporate wellness mandate adoption curves. Forecast inputs incorporated smart building integration mandate timelines from Beijing, Shanghai, and Shenzhen construction codes alongside U.S. school district fountain replacement program budgets.
The model holds under stable refrigerant feedstock pricing and semiconductor allocation continuity; deviation in Taiwan Strait logistics or EU F-Gas enforcement acceleration would shift replacement cycle timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
District Cooling Market
Energy Management Systems
Europe Advanced Distribution Management System Market
Energy Management Systems
Global Digital Utility Market
Energy Management Systems
Smart Programmable Thermostat Market
Energy Management Systems
Airflow Management Market
Energy Management Systems
Intelligent PDU Market
Energy Management Systems
IoT Smart Gas Meter Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
Grid Optimization Solution Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
Global Smart Air Conditioning Market
Energy Management Systems
IoT Energy Management Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
Smart HVAC Controls Market
Energy Management Systems
US Energy Management Systems Market
Energy Management Systems
Global Data Center Energy Management Solution Market