
 Global Vibration Control System Market | 2026-2036
Global Vibration Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vibration Control System Market Intelligence
The direct-to-OEM sales channel for specialized components is reshaping competitive positioning among system providers. Parker Hannifin Corporation leverages its extensive portfolio to serve diverse end-users from transportation to industrial machinery. Hutchinson specializes in elastomeric solutions for the automotive and aerospace sectors. LORD Corporation differentiates through its focus on advanced magnetorheological fluid technologies.
A vibration control system is an engineered assembly designed to mitigate unwanted mechanical oscillations. It employs sensors and actuators to generate counter-forces, thereby protecting sensitive equipment and enhancing structural stability. Its purpose is to improve performance and safety in applications from precision instruments to large buildings. Passive systems anchor the market in building and infrastructure, while active systems are gaining share in high-specification aerospace equipment and transportation assets.
Regulatory frameworks like the FAA's airworthiness standards in the United States and the CE marking requirements for machinery in Europe mandate specific vibration tolerance levels. In Japan, JIS standards govern the performance of systems used in precision instrument manufacturing. Vendor selection will increasingly depend on the ability to deliver solutions compliant with divergent regional safety and environmental protocols.
Market Dynamics
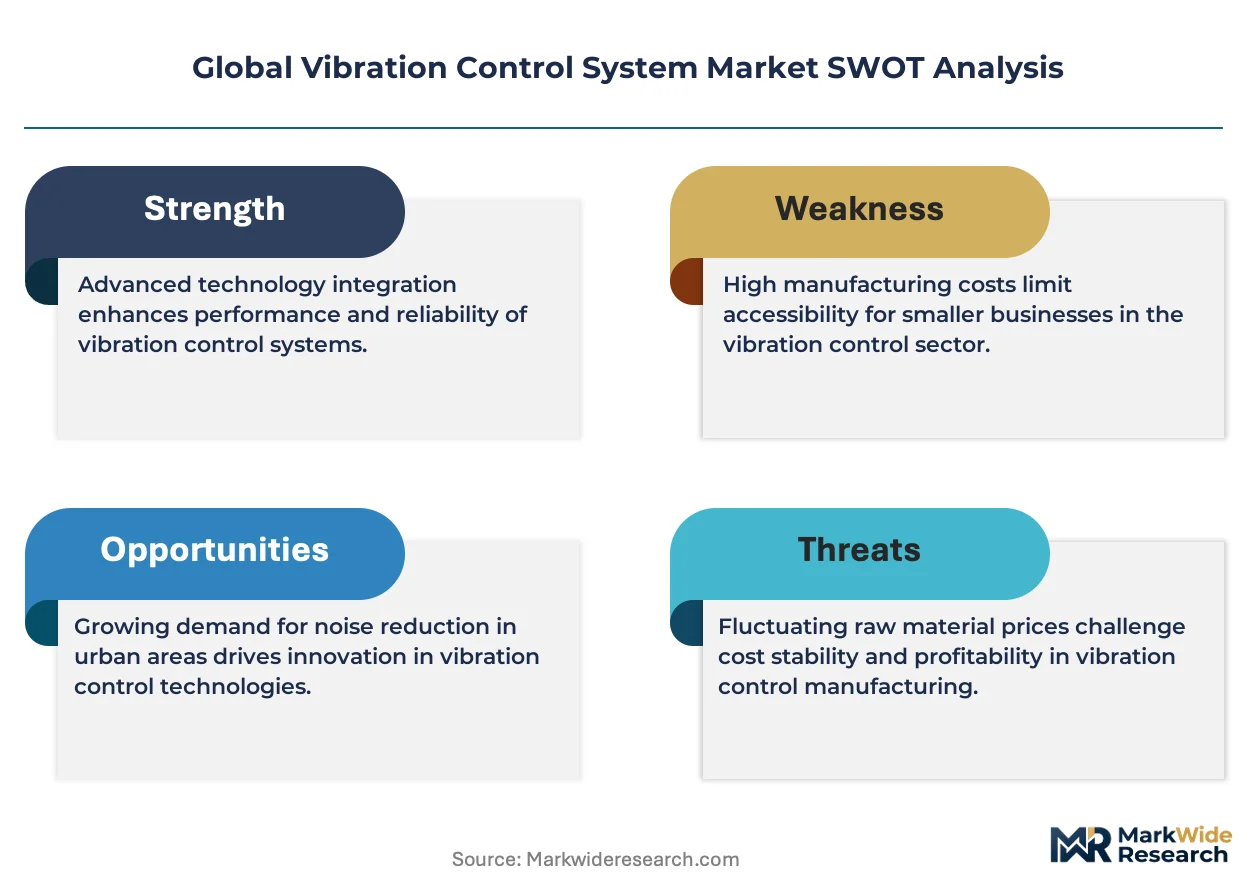
The convergence of stringent safety mandates and advanced material science is the central force shaping the market. This accelerates the displacement of passive systems with high-performance active solutions in critical aerospace, industrial, and infrastructure applications.
Growth Catalysts
- Aerospace Regulatory Pressure:Strict airworthiness standards from the FAA and EASA mandate advanced systems to manage structural fatigue in aircraft, compelling adoption of active vibration control.
- Asian Infrastructure Projects:Major construction in China and India, governed by updated seismic codes, drives demand for high-capacity passive dampers and base isolation systems.
- Precision Manufacturing Demands:The semiconductor industry's need for ultra-low vibration for photolithography equipment fuels the market for specialized isolation platforms.
Market Restraints
- High Initial Capital Outlay:The cost difference between advanced active systems and passive solutions is a primary adoption barrier, especially for cost-sensitive industrial machinery.
- Integration Complexity:Retrofitting existing structures with active control systems presents technical challenges and downtime, limiting deployment in established industrial plants.
- Specialized Material Dependency:The supply chain for materials like magnetorheological fluids is concentrated, creating vulnerability to price volatility and supply disruptions.
Strategic Opportunities
- Renewable Energy Sector:Offshore wind energy presents an opportunity for tuned mass dampers to mitigate tower oscillations, extending turbine lifespan and operational efficiency.
- AI and Predictive Maintenance:Integrating artificial intelligence into active systems enables predictive diagnostics and adaptive control, creating value through enhanced performance and reduced downtime.
- Smart Building Integration:An opportunity exists to embed vibration control within smart building platforms, offering centralized monitoring for comfort and structural health.
Industry Challenges
- Cross-Disciplinary Skills Gap:A shortage of engineers proficient in control theory, software, and materials science hinders the design of sophisticated active control systems.
- Navigating Divergent Regulations:Vendors face complexity and costs ensuring systems comply with fragmented standards like Europe’s CE marking and Japan's JIS requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vibration Control System Market |
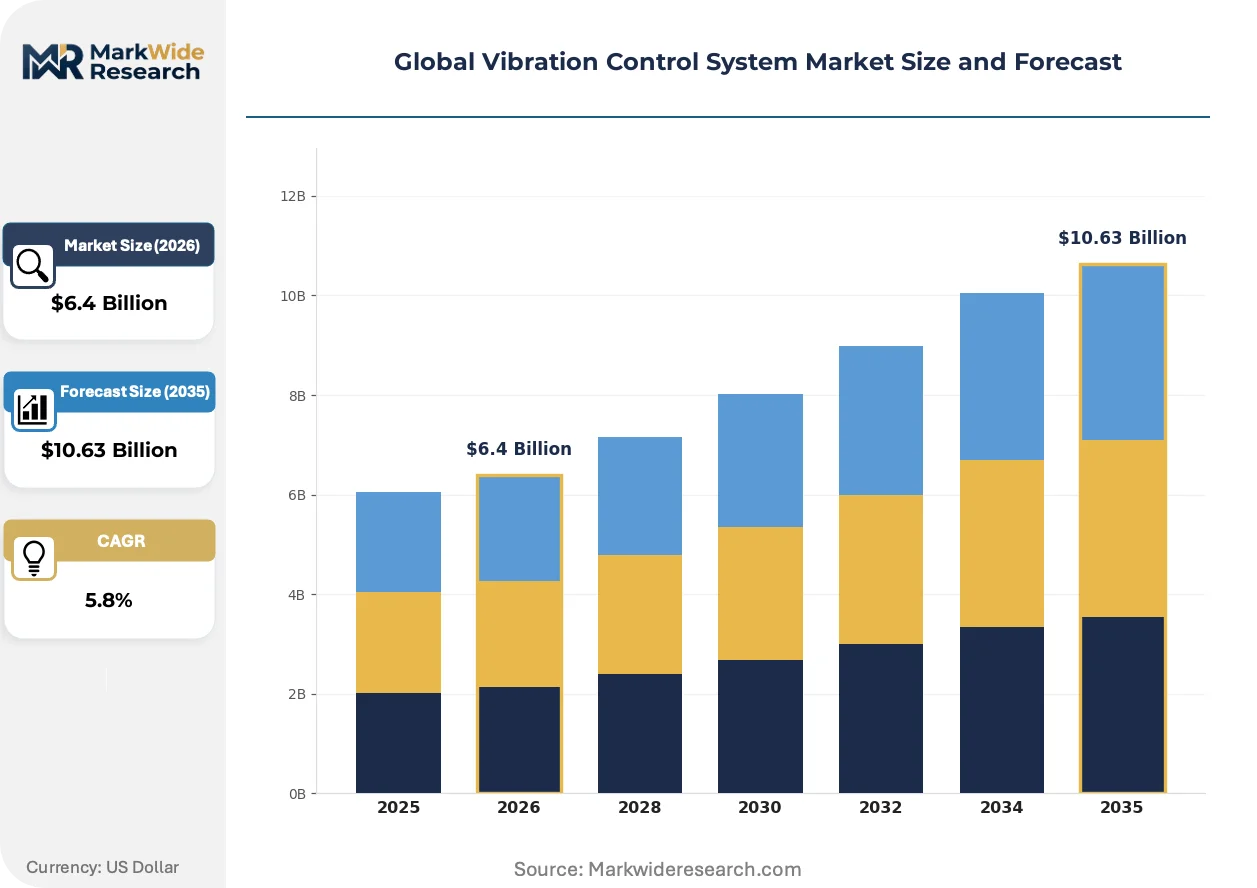
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.63 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Systems, Passive Systems, Semi-Active Systems, Tuned Mass Dampers, Vibration Absorbers Technology: Piezoelectric, Electromagnetic, Hydraulic, Magnetorheological, Pneumatic Application: Building & Infrastructure, Aerospace Equipment, Transportation Assets, Heavy Machinery, Precision Instruments End User: Construction Firms, Aircraft Manufacturers, Railway Operators, Manufacturing Plants, Research Laboratories |
| Companies Covered | LORD Corporation, Cooper Standard Holdings, Parker Hannifin Corporation, Kinetics Noise Control, Technical Manufacturing Corporation, Hutchinson, Trelleborg Aktiebolag, Fabreeka International, GERB Vibration Control Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vibration Control System Market Strategic Shifts & Innovations
The market's evolution is defined by a transition from static components to intelligent, networked systems. This shift emphasizes real-time data processing and autonomous adaptation to changing operational conditions across industrial and transportation assets.
Advanced piezoelectric technology provides a mechanism for generating precise counter-forces in active control systems. The aerospace sector integrates these materials into structural components for localized damping. This fusion of material science and engineering is collapsing the traditional separation between a structure and its vibration control system.
European Union directives, specifically CE marking for machinery, impose strict limits on vibration to ensure operator safety and equipment reliability. This regulation compels OEMs of industrial tools to embed certified vibration control solutions into product designs. The industrial machinery segment is most affected, redesigning equipment for compliance.
End-user procurement is evolving from purchasing discrete components to sourcing complete, integrated solutions. This shift favors suppliers offering a pre-validated package of sensors, actuators, and software, reducing integration risk. The change is most visible in transportation and aerospace, where system-level performance validation is critical.
Global Vibration Control System Market Segmentation
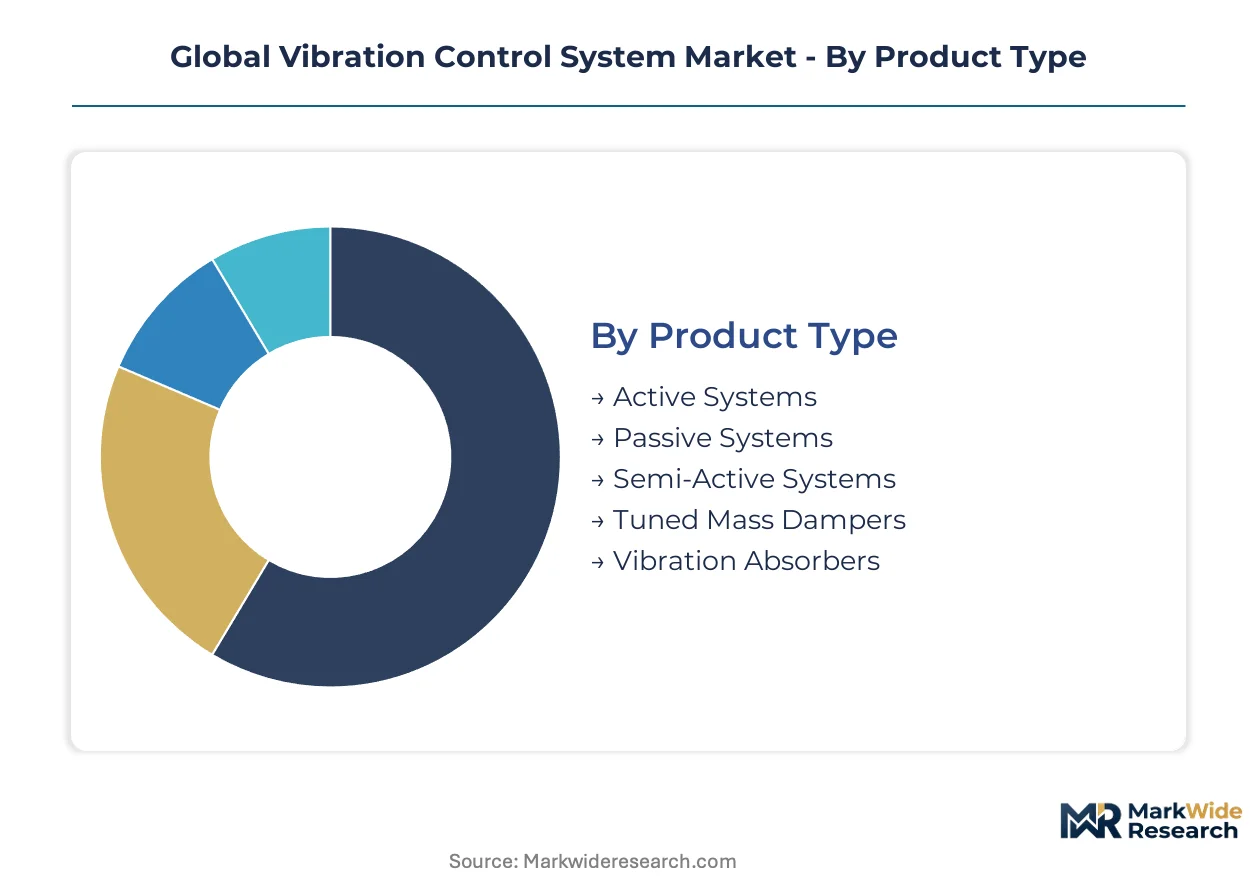
The Global Vibration Control System Market is dissected into distinct segments to clarify the varying demands and technological preferences across industries. This segmentation highlights the diverse solutions required to address mechanical oscillations, from large-scale infrastructure projects to precision manufacturing environments. Understanding these divisions is essential for strategic product development and market penetration.
Product Type:
The market for vibration control systems spans a spectrum of solutions catering to different performance needs and cost considerations.
- Active Systems:These advanced systems employ sensors, controllers, and actuators to dynamically generate counter-forces, effectively canceling unwanted vibrations. Adoption is expanding within the aerospace equipment sector due to stringent airworthiness standards from the FAA and EASA.
- Passive Systems:Comprising materials like rubber, springs, and viscous fluids, passive systems absorb or dissipate vibrational energy without external power. Demand for high-performance passive dampers is concentrating in China's and India's large-scale building and infrastructure projects, driven by updated seismic codes.
- Semi-Active Systems:Combining elements of both active and passive designs, these systems adjust their properties in real-time using controllable components, offering a balance of performance and cost.
- Tuned Mass Dampers:These are secondary masses attached to a structure, oscillating at a specific frequency to reduce the amplitude of vibrations in the main system.
- Vibration Absorbers:Designed to minimize vibration at a specific frequency, these devices are commonly used in industrial machinery to protect components.
Established volume favors Passive Systems; emerging adoption favors Active Systems.
Technology:
The technological underpinnings of vibration control systems determine their precision, responsiveness, and application suitability.
- Piezoelectric:This technology utilizes materials that generate an electric charge when mechanically stressed, or vice versa, enabling precise and rapid force generation in active control systems. The aerospace sector integrates these materials into structural components for localized damping.
- Magnetorheological:These fluids change viscosity in response to a magnetic field, allowing for adjustable damping properties in semi-active systems. LORD Corporation differentiates through its focus on advanced magnetorheological fluid technologies.
- Electromagnetic:Employing magnetic fields to generate forces, electromagnetic actuators provide non-contact vibration control, suitable for sensitive equipment.
- Hydraulic:Using incompressible fluid to transmit force, hydraulic systems offer robust damping capabilities, often found in heavy machinery and large structures.
- Pneumatic:These systems use compressed air to provide isolation and damping, commonly applied in precision manufacturing environments for sensitive instruments.
The market is evolving towards Piezoelectric technology for high-performance applications, while Hydraulic solutions maintain their base in heavy-duty industrial contexts.
Application:
Vibration control systems find diverse applications across sectors where mitigating mechanical oscillations is critical for safety and performance.
- Building & Infrastructure:This segment includes seismic isolation for buildings, bridges, and other large structures, protecting them from earthquake damage and enhancing structural integrity. Major construction projects in China and India drive demand for high-capacity systems.
- Aerospace Equipment:Vibration control is crucial for aircraft components, engines, and interiors to manage structural fatigue and improve passenger comfort. Strict airworthiness standards from the FAA and EASA compel adoption of active vibration control.
- Transportation Assets:This category encompasses vibration mitigation in rail vehicles, automobiles, and marine vessels to enhance ride quality and component longevity.
- Heavy Machinery:Industrial equipment such as presses, pumps, and generators utilize vibration control to reduce noise, improve operational efficiency, and extend machine lifespan.
- Precision Instruments:Applications in semiconductor manufacturing and laboratory equipment require ultra-low vibration environments to ensure accuracy and functionality.
Key growth is observed in Aerospace Equipment driven by regulatory pressure, with Building & Infrastructure providing foundational demand.
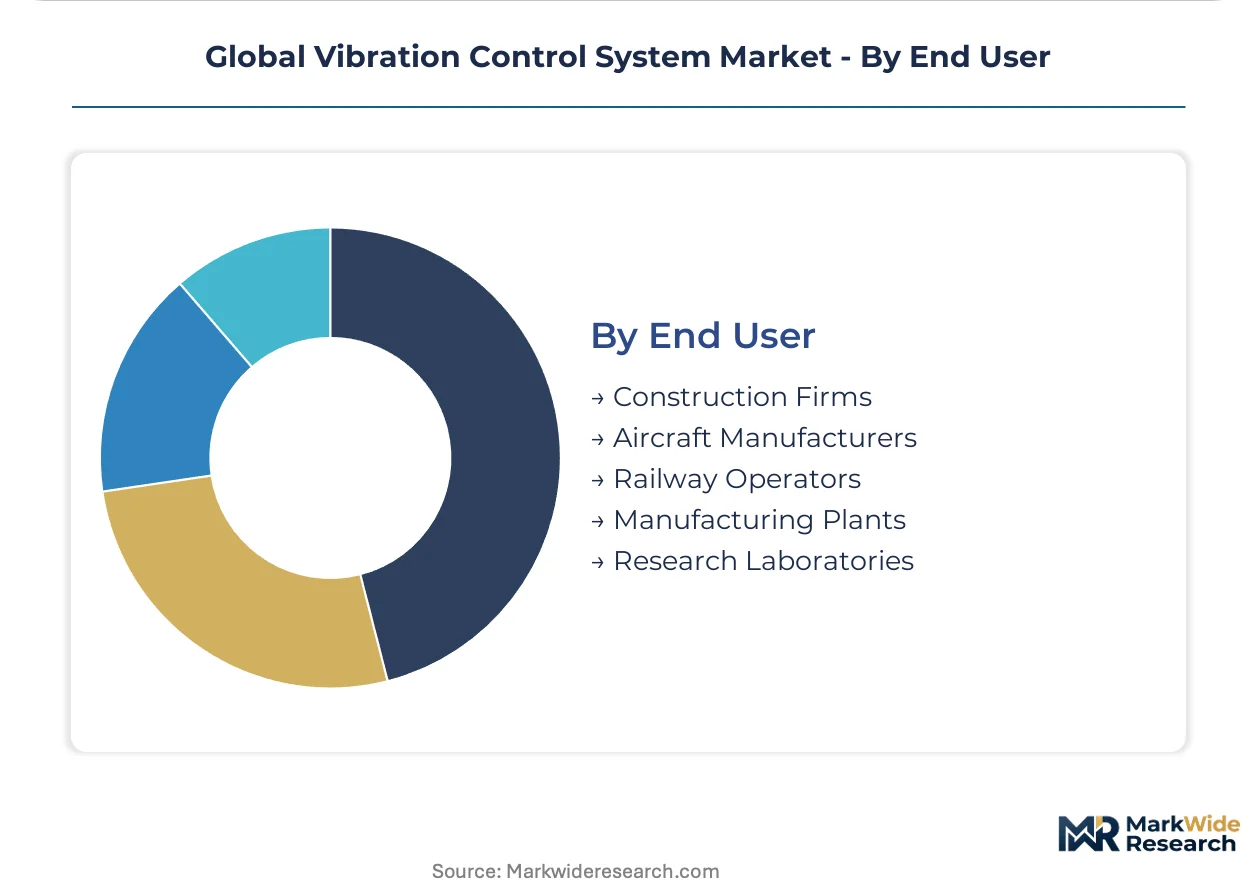
End User:
The end-user landscape reflects the primary beneficiaries and purchasers of vibration control solutions across various industries.
- Construction Firms:These entities integrate vibration control systems into new builds and retrofitting projects for seismic protection and structural stability. Construction firms drive demand for base isolation systems in major urban developments.
- Aircraft Manufacturers:OEMs in the aviation industry incorporate advanced vibration control into airframes, engines, and cabin systems to meet stringent safety and performance requirements. Aircraft manufacturers are compelled by FAA mandates for structural integrity.
- Railway Operators:Operators of passenger and freight rail systems use vibration control to improve track stability, reduce wear on rolling stock, and enhance passenger comfort.
- Manufacturing Plants:Industrial facilities deploy vibration control for machinery, production lines, and cleanroom environments to protect sensitive processes and equipment.
- Research Laboratories:Scientific and academic institutions utilize specialized vibration isolation platforms to ensure the accuracy of experiments and sensitive instrumentation.
Construction Firms drive significant revenue, while Research Laboratories represent a specialized, high-value niche.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power asymmetry defines market dynamics, with cost-sensitive infrastructure projects in China and India driving demand for economical passive systems, contrasting with the United States' and Germany's willingness to invest in high-performance active solutions for aerospace and precision manufacturing. This divergence shapes product development and market penetration strategies. Regulatory environments also vary significantly, influencing technology adoption across different geographies.
United States
Demand for advanced vibration control systems stems from the aerospace equipment sector and the precision instrument manufacturing industry. The FAA's airworthiness standards compel aircraft manufacturers to integrate sophisticated solutions for structural integrity and passenger comfort. Silicon Valley's semiconductor fabrication plants require ultra-low vibration platforms to support photolithography processes.
China
Extensive large-scale building and infrastructure projects, including high-rise structures and bridges, generate substantial demand for high-capacity passive dampers. Updated seismic codes mandate robust vibration mitigation strategies in new construction, particularly in earthquake-prone regions. Coastal megacities like Shanghai and Guangzhou are key hubs for implementing advanced structural damping technologies.
Germany
The industrial machinery and automotive sectors are primary demand drivers for vibration control solutions, focusing on enhancing operational efficiency and operator safety. CE marking requirements for machinery dictate strict vibration tolerance levels, influencing product design for original equipment manufacturers. Bavaria's strong manufacturing base integrates certified vibration control systems into production lines and vehicles.
India
Major infrastructure development, including metro rail networks and smart city initiatives, fuels the need for effective vibration isolation in buildings and transportation assets. National building codes are progressively incorporating stricter seismic resistance standards for new constructions. The Delhi-NCR region's rapid urbanization and industrial growth drive significant demand for base isolation systems.
Japan
The precision instrument manufacturing sector, particularly optics and semiconductors, requires exceptionally stable environments. JIS standards govern the performance and application of vibration control systems used in sensitive industrial processes. The Kanto region, home to numerous high-tech industries, concentrates demand for specialized active isolation platforms.
Global Vibration Control System Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing critical materials and sub-assemblies. The market exhibits a tiered structure, with a few large players offering comprehensive solutions alongside numerous niche providers focusing on specific technologies or applications. Strategic archetypes include diversified engineering conglomerates, specialized elastomeric solution providers, and advanced material technology innovators. Portfolio diversification and strategic partnerships represent dominant competitive moves.
Within the diversified engineering conglomerate archetype, Parker Hannifin Corporation leverages its extensive product portfolio to serve diverse end-users from transportation to industrial machinery. Hutchinson exemplifies specialized elastomeric solution providers, focusing on automotive and aerospace sectors with tailored damping materials. LORD Corporation anchors the advanced material technology innovators, differentiating through its focus on magnetorheological fluid technologies for high-performance applications.
| Leading Market Players |
|---|
| LORD Corporation |
| Cooper Standard Holdings |
| Parker Hannifin Corporation |
| Kinetics Noise Control |
| Technical Manufacturing Corporation |
| Hutchinson |
| Trelleborg Aktiebolag |
| Fabreeka International |
| GERB Vibration Control Systems |
| Others |
Cost & Logistics Intelligence
Specialized material inputs, particularly magnetorheological fluids, concentrate margin pools upstream with technology innovators. This influences pricing power for integrated system providers in high-performance applications.
Pricing Analysis
Configured-to-order pricing for active vibration control systems commands a premium over standardized passive components. Project-based pricing dominates integrated solutions for aerospace and infrastructure, with price differentiation stemming from customization levels and stringent certification requirements like FAA airworthiness standards. Pricing softness is observed in industrial machinery due to high initial capital outlay, making these buyers more price-sensitive than aerospace equipment manufacturers.
Supply Chain Analysis
Upstream feedstock for advanced vibration control systems relies heavily on specialized material producers in China and Germany. Magnetorheological fluids, piezoelectric ceramics, and performance elastomers constitute critical component dependencies. Supply chain risk stems from the concentrated production of magnetorheological fluids, creating vulnerability to price volatility. Downstream distribution primarily runs through direct-to-OEM channels for specialized components, with a growing shift towards integrated solution providers offering complete packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Vibration Control System Market is in an early-cycle expansion phase, driven by the increasing integration of advanced piezoelectric technology. This technological shift enables higher performance solutions across critical applications.
For Market Incumbents: Entrench existing OEM relationships through co-development of integrated solutions. Invest significantly in R&D for advanced materials, specifically magnetorheological fluids and piezoelectric composites, to counter specialized material dependency. Pursue strategic acquisitions of niche technology providers to mitigate integration complexity for customers. Strengthen certification capabilities to meet evolving regulatory frameworks like the FAA's airworthiness standards.
For New Entrants and Emerging Players: Pursue specialized niches within the renewable energy sector, particularly offshore wind where demand for tuned mass dampers is growing. Target smart building integration platforms as a white-space opportunity for centralized vibration monitoring. The most penetrable application lies in retrofitting industrial machinery with AI-enabled predictive maintenance systems. Offer value through enhanced operational efficiency and reduced downtime for mid-sized manufacturing plants.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with niche component specialists and regional system integrators, offering attractive consolidation opportunities. This market exhibits strong long-term viability, underpinned by increasing regulatory mandates for safety and performance across critical infrastructure. Target advanced material technology innovators, especially those focused on piezoelectric or magnetorheological solutions. The signal to watch is the expansion of AI and predictive maintenance capabilities within active control systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Piezoelectric Materials | This enhances active system performance for aerospace equipment, meeting stringent FAA airworthiness standards. |
| Form AI Integration Partnerships | Integrating artificial intelligence enables predictive diagnostics and adaptive control for industrial machinery. |
| Expand in Asian Infrastructure Markets | This addresses the growing demand for high-capacity passive dampers in China's and India's large-scale projects. |
| Strengthen Regulatory Compliance Teams | Ensuring adherence to diverse standards like Europe’s CE marking and Japan's JIS requirements is critical. |
| Develop Full-Stack Integrated Solutions | This reduces integration risk for end-users, particularly in transportation and aerospace applications. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted for the Global Vibration Control System Market analysis. Primary interviews with aircraft manufacturers, construction firms, and manufacturing plant engineers provided qualitative insights. This was validated against secondary sources including FAA airworthiness standards, CE marking requirements, and JIS standards. Bottom-up data collection and top-down market sizing ensured robust triangulation.
Quantitative models were calibrated against qualitative insights to develop the forecast framework across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regulatory compliance. Compound annual growth rates were derived from historical growth patterns and projected adoption rates. Evolving airworthiness standards and infrastructure project pipelines informed future market trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified engineering conglomerates would shift outcomes. Forecasts reflect assumptions regarding supply chain stability and rapid technological shifts. Cross-checking against industry association reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
District Cooling Market
Energy Management Systems
Saudi Arabia Portable Air Conditioner Market
Energy Management Systems
Intelligent PDU Market
Energy Management Systems
Building Energy Management Solution Market
Energy Management Systems
Chemical Control Systems Market
Energy Management Systems
Smart Air Cleaners Market
Energy Management Systems
Smart Programmable Thermostat Market
Energy Management Systems
Data Center Power Management Market
Energy Management Systems
AI-Driven Lighting Controls Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
Europe Home Energy Management System Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
Portable Air Cooler Market
Energy Management Systems
Smart Thermostat Market
Energy Management Systems
Global Thermal Management Technologies Market
Energy Management Systems
Smart Climate Control Market