
 Smart Climate Control Market | 2026-2036
Smart Climate Control Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Climate Control Market Outlook
Embedded systems engineering talent scarcity is redrawing competitive boundaries across the smart climate control value chain. Google Nest leverages its silicon partnerships to sustain firmware autonomy and reduce supplier dependency. Ecobee anchors its position through deep utility-channel relationships that dominate North American rebate-program distribution. Tado competes on open-protocol architecture, allowing its hardware to integrate with multi-vendor heating ecosystems without platform lock-in.
Smart climate control denotes networked environmental management systems that modulate temperature, humidity, and air quality through sensor-fed algorithms executing setpoint adjustments via actuated HVAC interfaces, typically operating over wireless mesh or IP-based protocols with sub-second latency requirements. These systems serve commercial and residential buildings by minimizing energy consumption while preserving occupant comfort thresholds. Thermostat hardware still occupies the largest revenue pool, though sensor deployments are expanding fastest as multi-zone granularity becomes a baseline specification. Professional installation channels dominate new construction, while retrofit demand concentrates in Wi-Fi-enabled controllers that bypass dedicated hub requirements.
FERC demand-response rules in the United States, EU Ecodesign requirements under the EU Green Deal framework, and Japan's METI Top Runner program collectively mandate interoperable energy-management interfaces and minimum efficiency thresholds that shape product roadmaps. Compliance with these regimes determines market access eligibility and rebate qualification status across the three jurisdictions. Stakeholders must monitor evolving cybersecurity certification requirements for connected building infrastructure as regulatory scope expands beyond efficiency into data governance.
Market Dynamics
Building electrification mandates are restructuring installer procurement patterns across the smart climate control value chain, with HVAC contractors displacing traditional electrical contractors as the primary channel for thermostat and heat-pump controller deployment.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant-phaseout deadlines in Europe are accelerating retrofit demand for compatible smart controllers that optimize heat-pump efficiency during cooling-system transitions.
- Utility rebate programs:North American demand-response enrollment incentives are bundling smart thermostat subsidies with time-of-use electricity tariffs, expanding residential penetration.
- Sensor miniaturization:MEMS-based multi-parameter environmental sensors are enabling sub-room-zone climate granularity without dedicated wiring infrastructure.
Market Restraints
- Silicon supply concentration:Firmware-autonomous controller production depends on concentrated semiconductor fabrication capacity in East Asia, exposing lead-time volatility.
- Copper and refrigerant input costs:Heat-pump-integrated smart systems face margin pressure from commodity price swings in coil materials and transition refrigerants.
- Cybersecurity certification friction:Emerging connected-building data-governance requirements are extending product launch timelines without harmonized standards.
Strategic Opportunities
- Japan METI Top Runner program:Efficiency-mandate compliance creates entry pathways for interoperable energy-management interfaces in commercial building retrofits.
- Multi-vendor heating ecosystem integration:Open-protocol architectures are capturing share in European markets where platform lock-in resistance shapes procurement.
- Wi-Fi-enabled retrofit controllers:Bypass-hub connectivity is penetrating aging building stock in Germany where heat-pump-to-thermostat bundling has normalized smart upgrades.
Industry Challenges
- Embedded systems engineering scarcity:Firmware talent shortages are constraining in-house controller development at mid-tier HVAC manufacturers.
- Legacy HVAC integration complexity:Proprietary communication protocols in existing commercial installations require costly gateway deployment for smart controller connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Climate Control Market |
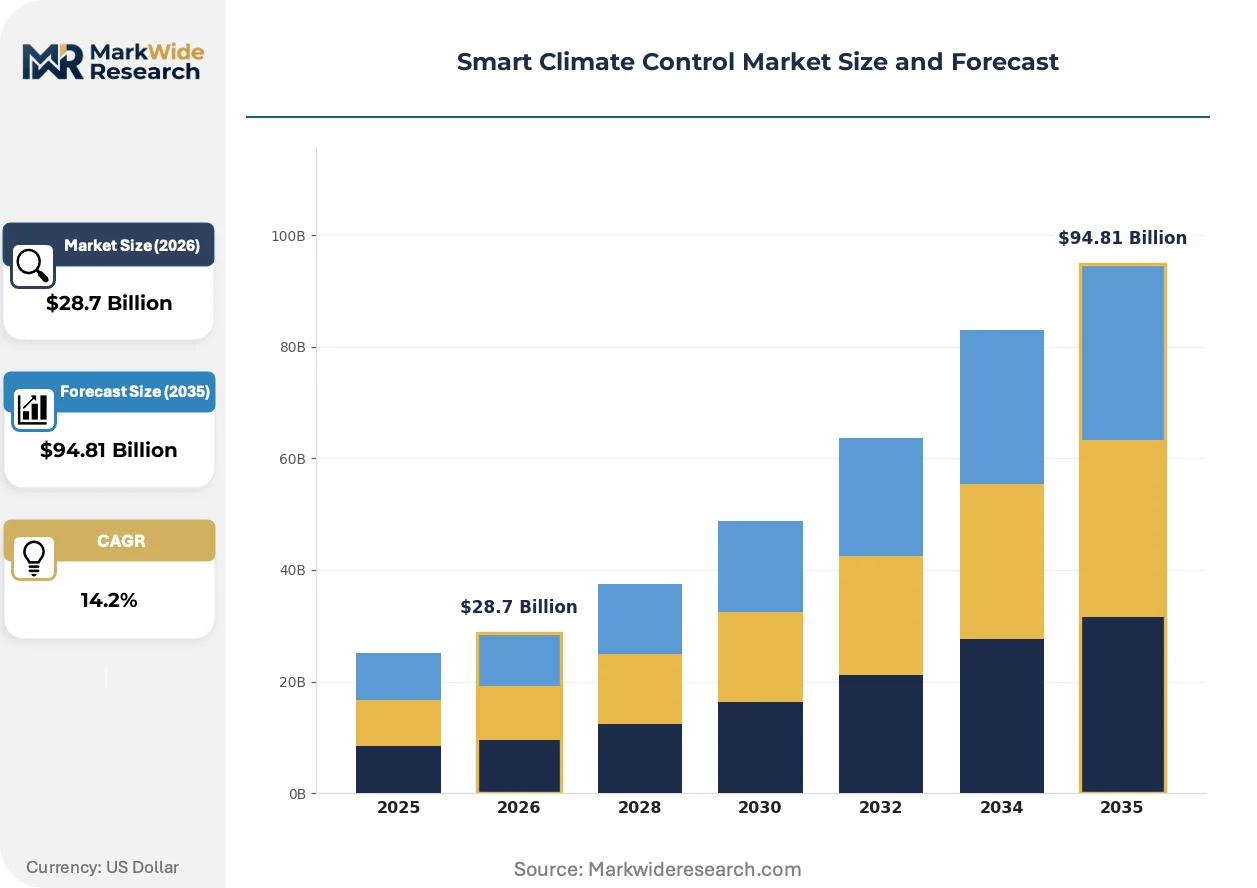
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $94.81 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermostats, Sensors, Controllers, Actuators Technology: Wi-Fi, Zigbee, Bluetooth, Z-Wave Installation: DIY, Professional, Retrofit, New Construction End User: Residential, Commercial, Industrial, Educational |
| Companies Covered | Sensibo, Cielo, Google Nest, Sensi (Emerson Electric), Boldr, ecobee, Mysa, Tado, Honeywell Home, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Climate Control Market Strategic Shifts
Algorithmic environmental management is fragmenting across competing connectivity architectures, with latency requirements and interoperability mandates pulling product development in divergent technical directions.
Edge-computing climate controllers are bifurcating the market between cloud-dependent and local-processing architectures. Commercial building operators in Japan and Germany are prioritizing sub-second actuator response for demand-response events. This technical split is compressing vendor R&D budgets across dual firmware tracks.
EU Ecodesign requirements under the EU Green Deal framework are mandating minimum efficiency thresholds for networked thermostats sold in member states. Manufacturers must redesign power budgets and standby consumption to maintain market access eligibility. The German market is responding fastest, with heat-pump-optimized controllers capturing disproportionate new-install share.
Rebate-program enrollment is consolidating residential purchasing decisions around utility-preferred hardware SKUs. North American retail channels are ceding volume to contractor-direct procurement tied to installation incentives. This channel rotation is most visible in California and New York, where state-level electrification targets concentrate program budgets.
Smart Climate Control Market Segmentation
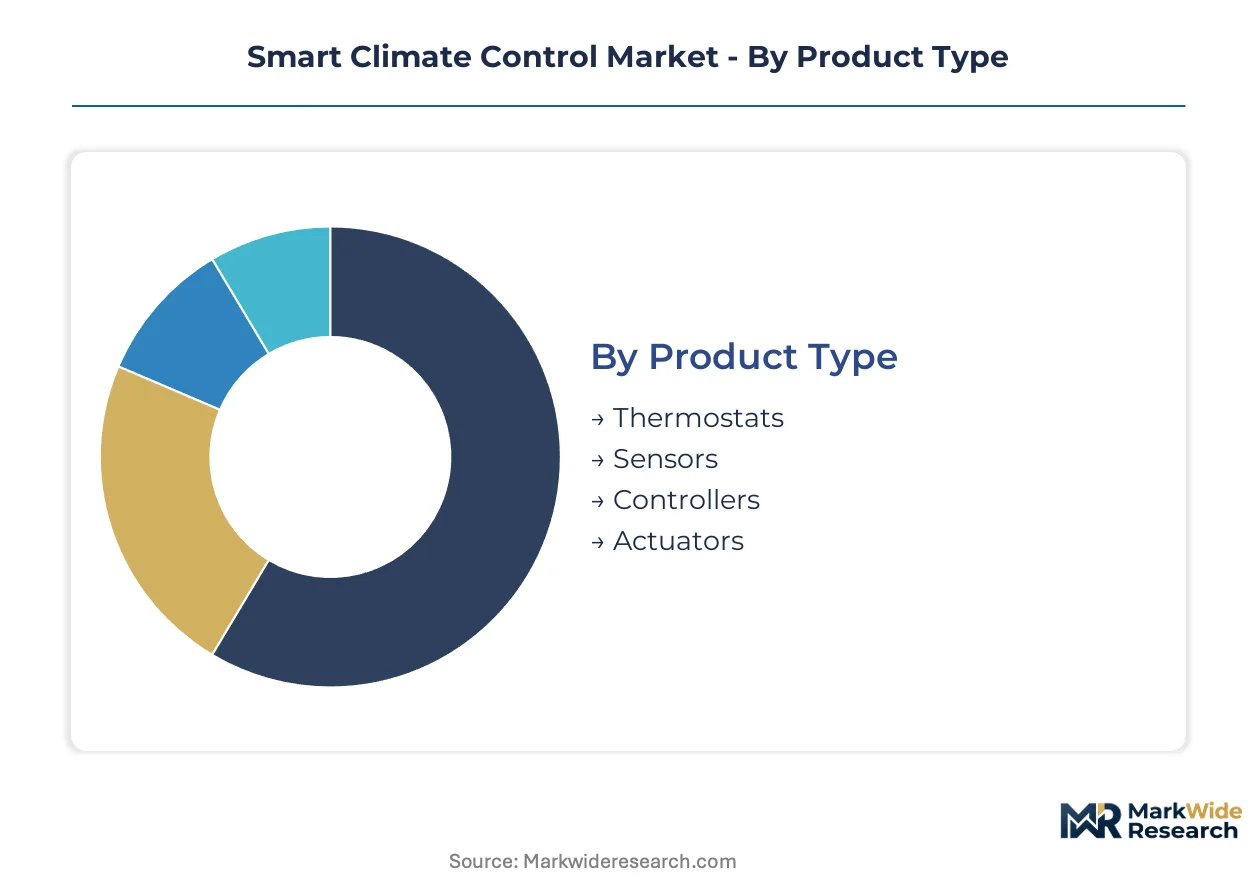
Segmentation in smart climate control reveals how procurement authority, connectivity requirements, and installation constraints fragment addressable demand. Product architecture, protocol selection, and channel configuration each impose distinct margin profiles and competitive dynamics across the value chain.
Product Type:
EU Ecodesign mandates and FERC demand-response rules impose divergent efficiency and interoperability requirements on each hardware category, reshaping R&D allocation and certification sequencing.
- Thermostats:Wall-mounted control units integrating temperature sensing, algorithmic setpoint management, and HVAC interface protocols. Residential retrofits in Germany concentrate demand as heat-pump bundling normalizes smart upgrades under the EU Green Deal framework. F-Gas Regulation compliance timelines accelerate controller replacement cycles.
- Sensors:MEMS-based environmental monitors measuring temperature, humidity, occupancy, and air quality parameters for zone-level granularity. Commercial building operators in Japan prioritize sub-second latency for METI Top Runner demand-response events. Miniaturization trends enable wireless deployment without dedicated wiring infrastructure.
- Controllers:Central processing units executing sensor-fed algorithms and issuing actuator commands across multi-zone installations.
- Actuators:Motorized valves, dampers, and fan-speed regulators translating digital commands into physical HVAC adjustments.
Thermostats handle the majority of throughput; sensors are gaining share fastest as multi-zone granularity becomes baseline specification.
Technology:
Protocol selection determines latency performance, hub dependency, and interoperability scope, with cost tier and application use case driving customer preference.
- Wi-Fi:IP-based connectivity leveraging existing residential broadband infrastructure without dedicated gateway hardware. DIY retrofit channels in aging European building stock favor Wi-Fi-enabled controllers that bypass hub requirements. Standby power consumption must meet EU Ecodesign thresholds to maintain market access.
- Zigbee:Low-power mesh networking protocol optimized for battery-operated sensors and multi-device commercial deployments. German commercial building retrofits adopt Zigbee for its sub-second actuator response in demand-response programs. IEEE 802.15.4 physical layer enables coexistence with Wi-Fi interference.
- Bluetooth:Short-range wireless standard supporting direct smartphone pairing for initial configuration and local control.
- Z-Wave:Sub-GHz mesh protocol prioritizing range penetration through building materials in multi-story residential structures.
Wi-Fi dominates residential volume; Zigbee shows the steepest expansion trajectory in commercial specifications.
Installation:
Channel configuration reflects building age, electrification mandate timing, and contractor certification requirements across jurisdictions.
- Professional:Certified HVAC contractor deployment mandatory for heat-pump-integrated systems and new construction compliance. Building electrification mandates in California and New York concentrate rebate-program budgets through contractor-direct procurement. FERC demand-response enrollment requires utility-approved installer certification.
- Retrofit:Replacement of legacy thermostats and controllers in existing building stock without structural modification. Germany's heat-pump transition under EU F-Gas Regulation generates compatible smart controller demand. Wi-Fi-enabled devices reduce installation complexity for electrical contractors.
- DIY:Consumer self-installation of battery-powered sensors and wireless thermostats requiring no hardwired power.
- New Construction:Pre-wire integration during building development with centralized controller placement and dedicated sensor infrastructure.
Professional channels capture the largest revenue pool; retrofit is climbing the fastest on F-Gas-driven replacement cycles.
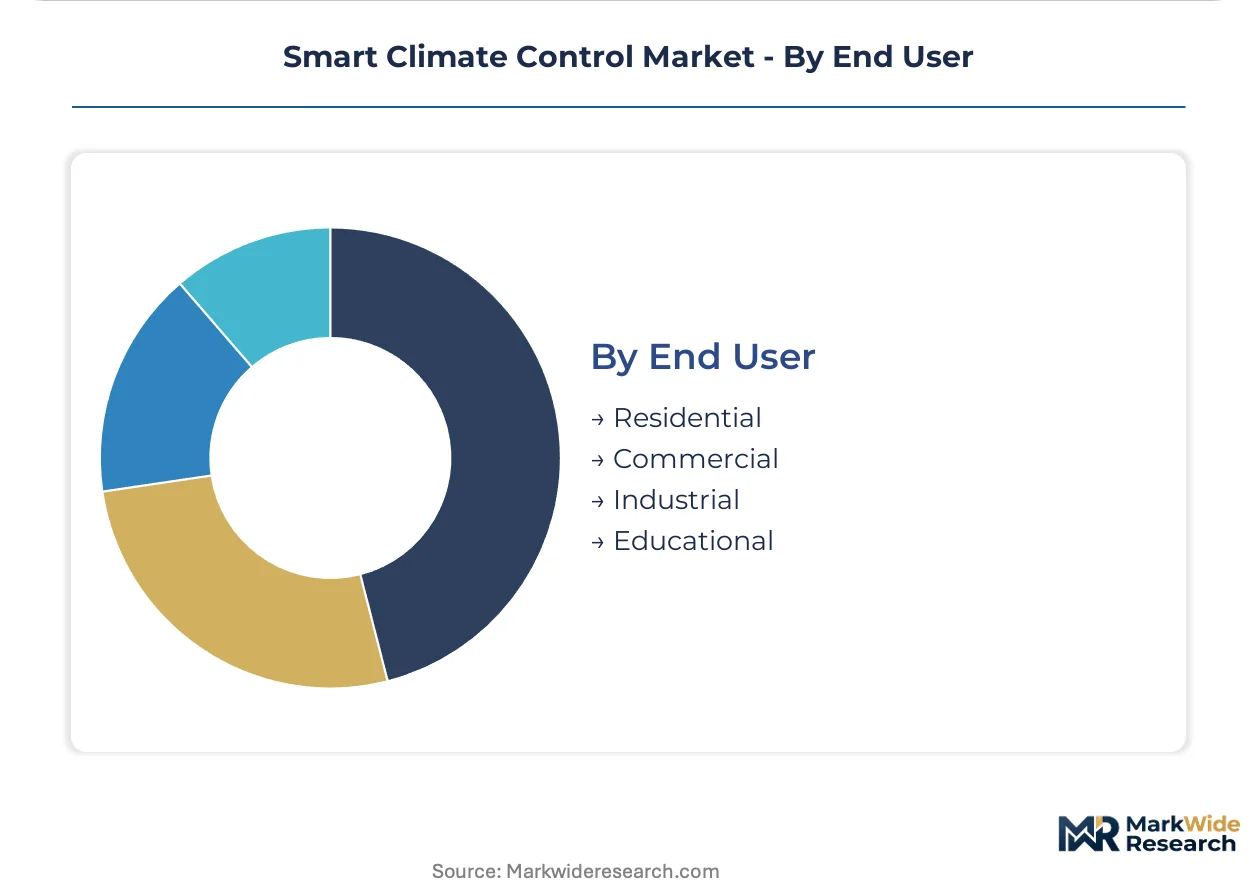
End User:
Occupant density, operating hours, and regulatory exposure differentiate procurement priorities across building types.
- Residential:Single-family and multi-family dwellings optimizing comfort-per-watt through utility rebate programs. North American time-of-use tariff enrollment bundles smart thermostat subsidies with demand-response hardware. Rebate-program consolidation steers purchasing toward utility-preferred SKUs.
- Commercial:Office buildings, retail spaces, and hospitality properties managing energy costs across variable occupancy patterns. Japan's METI Top Runner program mandates interoperable energy-management interfaces for building retrofits. Edge-computing architectures prioritize local processing for cybersecurity compliance.
- Industrial:Manufacturing facilities and warehouses requiring environmental stability for process control and inventory preservation.
- Educational:Schools and universities with intermittent occupancy schedules and public-sector procurement constraints.
Residential generates the highest unit volume; commercial delivers the strongest margin expansion on regulatory compliance premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC demand-response rules anchor the United States as the dominant geography, though EU F-Gas Regulation timelines and Japan's METI Top Runner program create parallel compliance-driven demand centers. Procurement authority concentrates with HVAC contractors in electrification-mandate jurisdictions while utility rebate programs steer residential purchasing decisions.
United States
FERC demand-response enrollment incentives bundle smart thermostat subsidies with time-of-use electricity tariffs across California and New York. State-level electrification targets concentrate rebate-program budgets through contractor-direct procurement channels. Silicon Valley hardware developers and Boston-area building automation clusters drive edge-computing controller innovation for sub-second latency requirements.
Germany
Heat-pump-to-smart-thermostat bundling has normalized smart upgrades under EU Green Deal implementation timelines. EU F-Gas Regulation refrigerant-phaseout deadlines accelerate compatible controller replacement cycles in commercial cooling retrofits. Munich and Stuttgart industrial corridors concentrate MEMS sensor fabrication capacity serving multi-zone climate granularity specifications.
Japan
METI Top Runner program mandates interoperable energy-management interfaces for commercial building retrofits in Tokyo and Osaka metro areas. Edge-computing architectures prioritize local processing for cybersecurity compliance in demand-response event management. Nagoya-area automotive suppliers leverage process-control expertise into industrial environmental stability systems.
China
Dual carbon goals drive building efficiency mandates in Beijing-Tianjin-Hebei and Yangtze River Delta urban clusters. GB standards for networked thermostats impose standby power consumption thresholds shaping product roadmaps for export-oriented manufacturers. Shenzhen hardware ecosystems supply Wi-Fi-enabled retrofit controllers penetrating aging Asian building stock.
United Kingdom
Ofgem energy price cap mechanisms accelerate residential smart meter and thermostat adoption through utility-managed installation programs. London commercial property operators deploy multi-vendor heating ecosystem integration to avoid platform lock-in. Midlands manufacturing bases produce actuator hardware for European heat-pump-integrated system exports.
Smart Climate Control Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with silicon-autonomous firmware development and utility-channel relationships serving as the primary moats. The market structure reflects embedded systems engineering scarcity that constrains mid-tier HVAC manufacturers from in-house controller development. Three archetypes dominate: platform-integrated technology conglomerates, utility-channel specialists, and open-protocol hardware vendors. Competitive moves concentrate on strategic silicon partnerships and rebate-program certification capture rather than price-based confrontation.
Within the open-protocol tier, Tado exemplifies architecture positioning that enables multi-vendor heating ecosystem integration without platform dependency. Google Nest and ecobee occupy positions reflecting divergent channel strategies—silicon partnership leverage versus utility rebate-program dominance. These three anchors illustrate how firmware autonomy, channel depth, and interoperability resistance each command distinct competitive terrain in procurement decisions shaped by electrification mandates and regulatory compliance timelines.
| Leading Market Players |
|---|
| Sensibo |
| Cielo |
| Google Nest |
| Sensi (Emerson Electric) |
| Boldr |
| ecobee |
| Mysa |
| Tado |
| Honeywell Home |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation agreements with Taiwanese foundries lock in microcontroller supply visibility for thermostat manufacturers facing EU Ecodesign compliance deadlines. These contracts stabilize input costs while exposing buyers to silicon allocation rationing during demand spikes.
Pricing Analysis
German heat-pump-integrated controllers command 15-25% premiums over standalone Wi-Fi thermostats in Southern European markets. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in economy-tier Wi-Fi controllers is intensifying because Shenzhen-based manufacturers are absorbing copper coil volatility. Residential retrofit buyers exhibit highest price sensitivity; commercial building operators in Japan show lowest sensitivity due to METI Top Runner compliance mandates.
Supply Chain Analysis
China and Taiwan anchor semiconductor fabrication for wireless mesh chipsets and MEMS environmental sensors. Controller assembly draws from Malaysian and Mexican contract manufacturing for North American utility channel fulfillment. Single-source vulnerability concentrates in 40nm microcontroller wafer supply from TSMC-backed foundries. Distribution runs through HVAC contractor networks in electrification-mandate jurisdictions and retail DIY channels in aging European building stock.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart climate control functions as a defensive-moat market where regulatory entrenchment creates sticky compliance-driven procurement. Switching costs escalate as FERC demand-response enrollment ties hardware to utility-specific firmware certifications.
For Market Incumbents: Shield market position through backward integration into MEMS sensor fabrication and captive silicon design partnerships. Emerging open-protocol entrants threaten platform-integrated leaders by exploiting multi-vendor heating ecosystem demand in Germany. Certification investment in EU Ecodesign and METI Top Runner compliance creates renewal friction that locks out unqualified competitors. For New Entrants and Emerging Players: Anchor in commercial building retrofit white space across Japan's METI Top Runner compliance pipeline where edge-computing architectures face incumbent coverage gaps. Wi-Fi-enabled retrofit controllers for aging German residential stock represent the most penetrable segment. Utility-direct procurement bypass offers the clearest go-to-market angle against retail-channel congestion. For Investors and Strategic Acquirers: Firmware-autonomous mid-tier HVAC manufacturers with silicon partnerships present acquisition targets as embedded systems engineering scarcity constrains in-house development timelines. Long-term viability hinges on regulatory compliance breadth across FERC, EU F-Gas, and METI regimes. Watch heat-pump installation velocity in Germany as inflection indicator for controller demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Partnership Deepening | TSMC and GlobalFoundries alliances secure microcontroller allocation priority during supply crunches. |
| Utility Channel Certification Capture | FERC demand-response enrollment approval locks in contractor-direct procurement volume in California and New York. |
| Open-Protocol Architecture Expansion | Zigbee and Thread interoperability captures German commercial retrofits resisting platform lock-in. |
| Edge-Computing Controller Development | Local processing architectures meet Japan METI cybersecurity requirements for demand-response events. |
| Heat-Pump Integration Bundling | EU F-Gas Regulation retrofit cycles pair controller sales with refrigerant-phaseout system replacements. |
Study Parameters
Operator-level perspectives from HVAC contracting firms, utility demand-response program managers, MEMS sensor fabrication engineers, and building automation system integrators anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, EU Ecodesign regulatory databases, FERC order documentation, and customs trade records for controller hardware flows. Bottom-up installation volume estimates triangulated with top-down market sizing across technology protocol and end-use segmentation.
Sensitivity analysis tested forecast robustness across copper price volatility scenarios, silicon allocation rationing assumptions, and electrification mandate acceleration timelines. Segmentation dimensions modeled include product architecture, connectivity protocol, installation channel, and building type across the projection horizon. CAGRs derived from regression analysis of historical thermostat and sensor shipment trajectories, incorporating heat-pump penetration rates and rebate-program budget trajectories as industry-specific forecast inputs.
Material uncertainties — refrigerant-phaseout policy delays, semiconductor fabrication capacity expansion shortfalls, cybersecurity certification harmonization failures — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory compliance timelines and utility program continuity. Recalibration cycles align with material shifts in FERC rulemaking, EU F-Gas implementation pacing, and METI efficiency standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Asia-Pacific Home Energy Management System Market
Energy Management Systems
North America Energy Management Systems Market
Energy Management Systems
Building Energy Management Systems (BEMS) Market
Energy Management Systems
Saudi Arabia Portable Air Conditioner Market
Energy Management Systems
Building Energy Management Solution Market
Energy Management Systems
Home Energy Management System Market
Energy Management Systems
Evaporative Air Cooler Market
Energy Management Systems
Mobile Metering System Market
Energy Management Systems
Smart Thermostat Market
Energy Management Systems
Shared Power Bank Market
Energy Management Systems
Asia-Pacific Energy Management System Market
Energy Management Systems
Smart Water Cooler Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
Smart HVAC Controls Market
Energy Management Systems
Energy Management in Data Centers Market
Energy Management Systems
Global Thermal Management Technologies Market