
 District Cooling Market | 2026-2036
District Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
District Cooling Market Analysis
Data center operators are reorganizing thermal procurement strategies around centralized district cooling architectures. Keppel District Cooling leverages deep engineering capabilities across Singapore's Marina Bay precinct. Veolia Environnement anchors European service contracts through long-term concession models. Engie SA competes in Middle Eastern tenders with integrated chiller-thermal storage designs.
District cooling distributes chilled water from central plants through insulated piping networks to multiple buildings, typically operating at supply temperatures of 4-6°C with return lines at 12-14°C to serve air conditioning and process cooling loads. Commercial buildings command the largest application area share due to concentrated load densities and predictable demand profiles. Smart cooling systems represent the fastest-expanding system type segment as digital twin platforms and AI-driven load forecasting reduce plant energy intensity. Thermal energy storage within the heat source dimension unlocks peak-shaving revenue streams where time-of-use electricity tariffs apply.
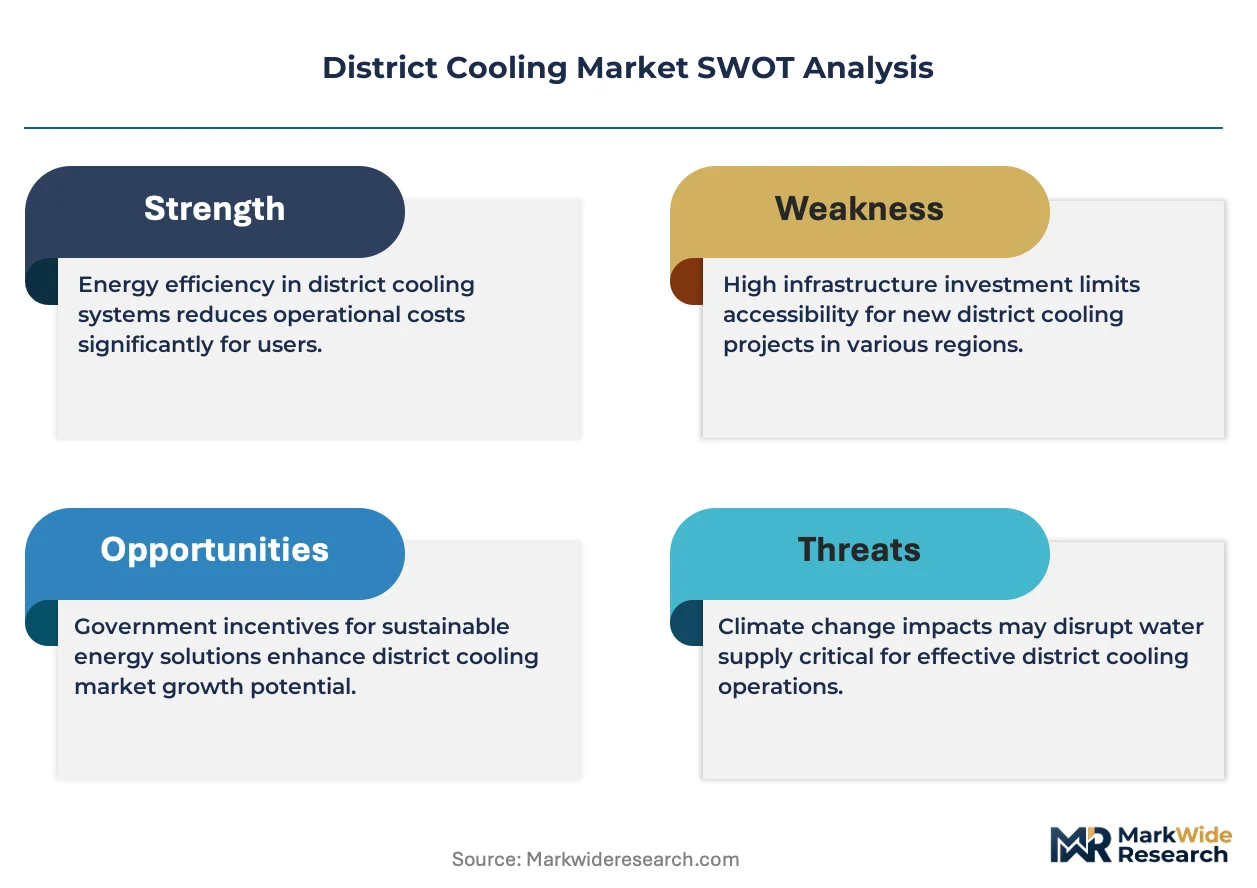
EMA and Singapore's Building and Construction Authority enforce Green Mark standards that mandate district cooling for new developments above specified gross floor areas. UAE's Regulation and Supervision Bureau sets technical and economic frameworks for cooling tariffs and service continuity in Dubai and Abu Dhabi. Stakeholders must monitor how evolving carbon border mechanisms and building performance standards reshape project finance structures for cross-border district cooling investments.
Market Dynamics
Building energy codes across the Gulf Cooperation Council are tightening chiller plant efficiency thresholds, forcing commercial real estate developers toward centralized thermal architectures that distribute chilled water through insulated piping networks at 4-6°C supply temperatures.
Growth Catalysts
- Green Mark Standards:Singapore's Building and Construction Authority mandates district cooling for new developments above specified gross floor areas, creating guaranteed demand pipelines in Marina Bay precincts.
- Data Center Thermal Loads:Hyperscale facilities are consolidating cooling procurement around centralized plants to manage concentrated heat densities and predictable demand profiles.
- Time-of-Use Tariffs:Peak-shaving revenue streams from thermal energy storage unlock project finance viability where electricity pricing varies across demand periods.
Market Restraints
- Copper and Insulation Input Volatility:District cooling piping networks depend on copper pricing and advanced insulation materials, exposing capital-intensive projects to commodity swings.
- Concession Model Concentration:Long-term service contracts anchor European capacity expansion, locking new entrants into decades-long payback horizons with limited exit flexibility.
- Substitute Decentralization:Modular chiller systems and building-scale heat pumps offer developers lower upfront capital requirements and faster deployment timelines.
Strategic Opportunities
- Smart Cooling Convergence:Digital twin platforms and AI-driven load forecasting are compressing plant energy intensity, opening efficiency arbitrage for technology-integrated operators.
- Saudi Arabia Capacity Gaps:The Kingdom's gigaproject pipeline lacks sufficient district cooling infrastructure, creating first-mover positioning for integrated chiller-thermal storage designs.
- Carbon Border Mechanisms:Evolving building performance standards in the European Union are reshaping project finance structures for cross-border thermal investments.
Industry Challenges
- Legacy Building Integration:Retrofitting centralized cooling into existing commercial stock requires coordination with aging HVAC infrastructure and fragmented building management systems.
- Thermal Engineering Talent Scarcity:Specialized expertise in centralized plant design, district network hydraulics, and thermal storage optimization remains concentrated among regional incumbents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | District Cooling Market |
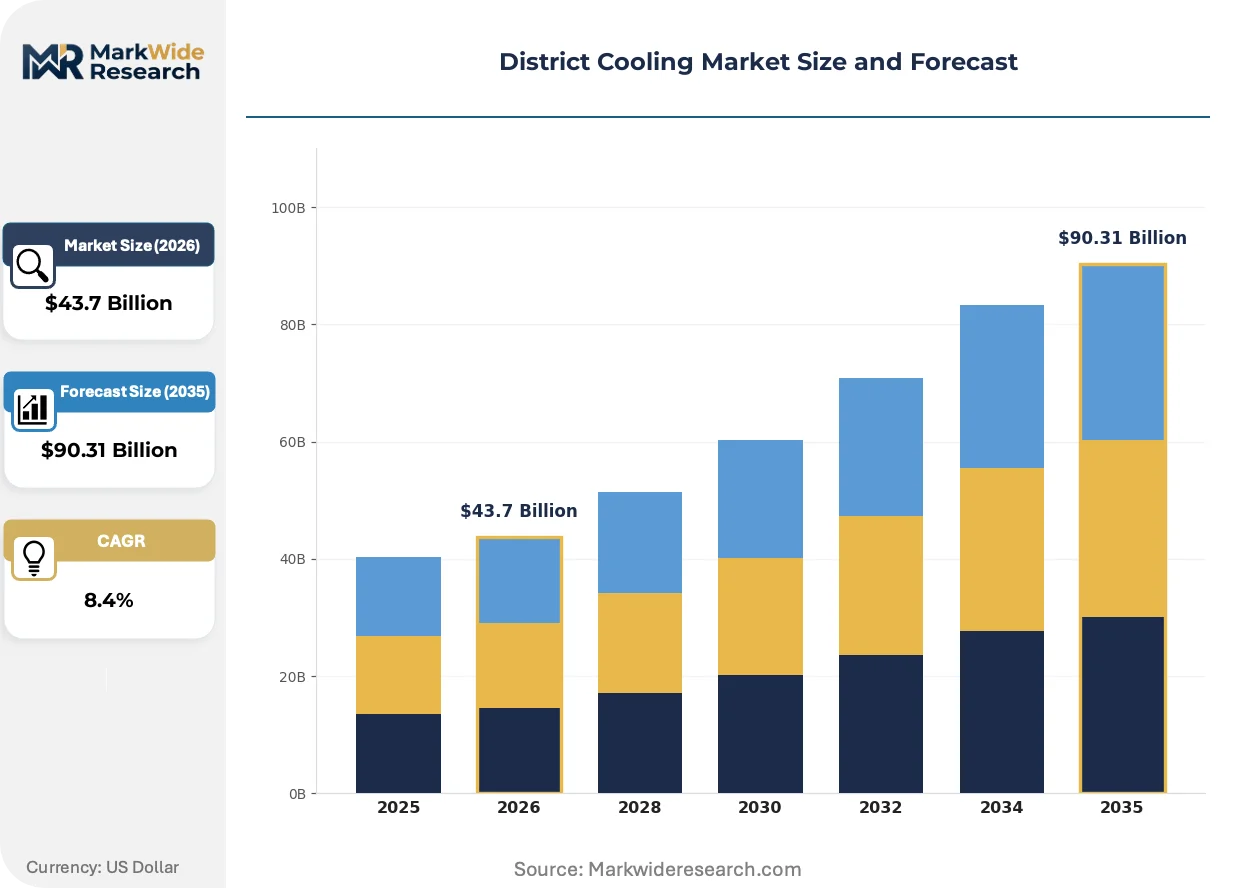
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $90.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Centralized, Decentralized, Hybrid, Smart Cooling Application Area: Commercial Buildings, Residential Complexes, Industrial Zones, Institutional Facilities Cooling Medium: Water, Glycol, Ammonia, Others Heat Source: Chillers, Heat Exchangers, Cooling Towers, Thermal Energy Storage |
| Companies Covered | Keppel District Cooling Pte Ltd., E.ON SE, Veolia Environnement S.A., Fortum Oyj, Vattenfall AB, Engie SA, Qatar District Cooling Company, Enwave Energy Corporation, Emirates Central Cooling Systems Corporation PJSC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
District Cooling Market Emerging Trajectories
Digitalization is compressing operational margins across district cooling networks. Plant operators are deploying predictive analytics and automated demand response to optimize chilled water distribution in real time.
Absorption chillers paired with waste heat recovery are displacing conventional electric compression systems in industrial zone deployments. Petrochemical complexes and combined-cycle power plants are adopting these configurations to monetize low-grade thermal streams. The technology is displacing standalone electric chiller procurement in Middle Eastern industrial parks where fuel diversification policies prioritize thermal integration.
The European Union's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants with high global warming potential. District cooling plant specifications now prioritize ammonia and carbon dioxide-based systems to maintain compliance timelines. Chiller manufacturers serving the Netherlands and Denmark are accelerating natural refrigerant transitions ahead of mandated phase-out dates.
Data center operators are consolidating thermal procurement under long-term cooling-as-a-service agreements. Colocation providers in Singapore and the United Arab Emirates are unbundling capital expenditure from operational responsibility, transferring plant ownership to specialized district cooling utilities. This model is most visible in Marina Bay and Dubai Internet City, where hyperscale tenants demand guaranteed availability without balance-sheet infrastructure exposure.
District Cooling Market Segmentation
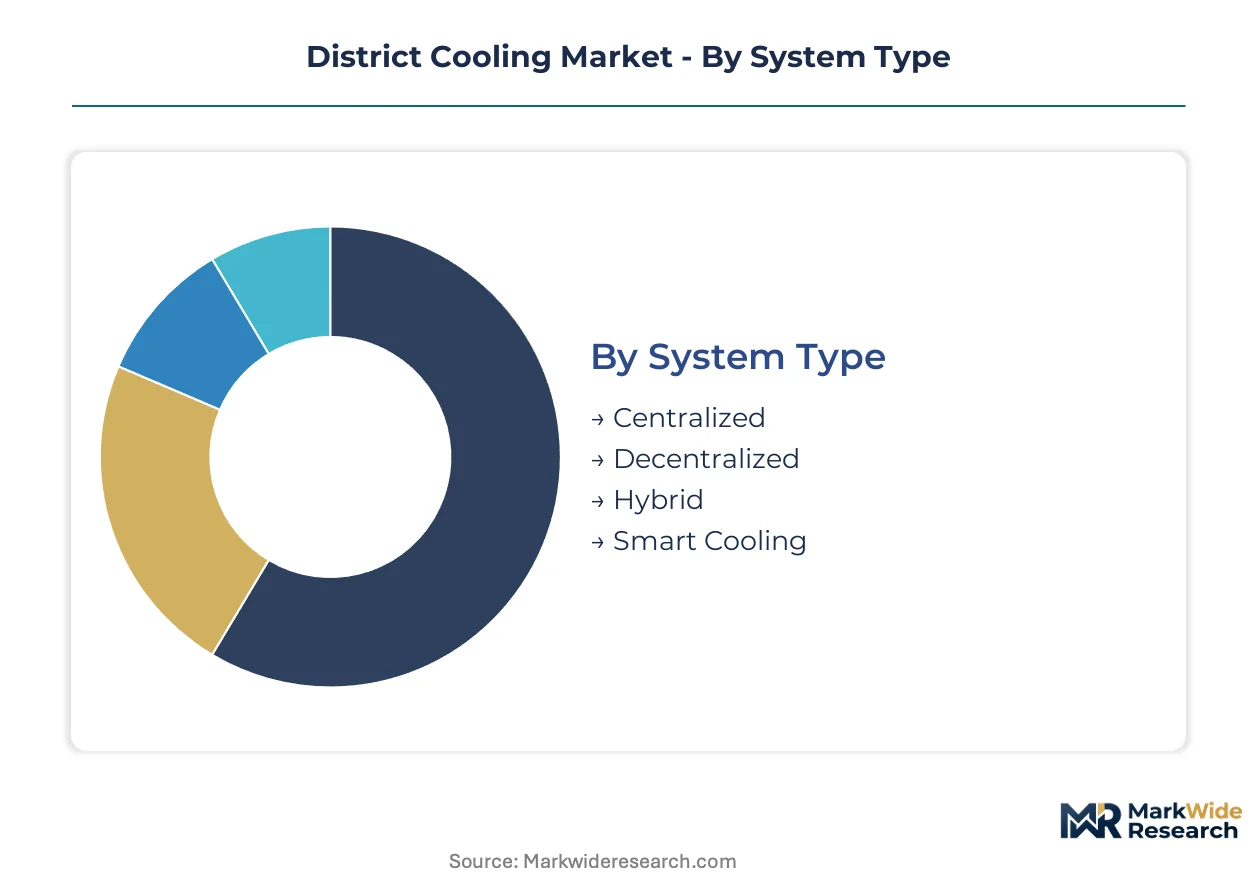
District cooling markets fragment across operational architectures, end-use thermal profiles, and working fluid chemistries. Procurement patterns diverge sharply between legacy centralized plants and digitally integrated smart systems, while cooling medium selection ties directly to local regulatory refrigerant phase-down schedules.
System Type:
Margin pools concentrate in smart cooling deployments where software-enabled optimization commands service premiums over hardware-only contracts.
- Centralized:Single large-scale chiller plants distribute chilled water through insulated piping networks to multiple buildings. Demand clusters in Gulf Cooperation Council commercial districts where Emirates Central Cooling Systems Corporation and Qatar District Cooling Company anchor regional capacity. District-scale thermal procurement reduces per-ton capital intensity for developers facing tightening building energy codes.
- Smart Cooling:Digital twin platforms and AI-driven load forecasting compress plant energy intensity through predictive analytics and automated demand response. Singapore's Marina Bay precinct demonstrates this architecture's revenue potential where EMA and Building and Construction Authority Green Mark standards mandate guaranteed efficiency performance.
- Decentralized:Modular plant configurations serve isolated developments or campus-scale deployments with limited network economies.
- Hybrid:Combined centralized and distributed assets balance base-load efficiency with peak-load flexibility.
The dominant share belongs to Centralized, while Smart Cooling is closing the gap fastest.
Application Area:
Volume concentrates where load densities and predictable demand profiles justify dedicated thermal infrastructure investment.
- Commercial Buildings:Office towers, retail complexes, and mixed-use developments generate concentrated cooling loads with synchronized daytime peaks. Keppel District Cooling leverages Singapore's Marina Bay commercial cluster to demonstrate precinct-scale thermal procurement viability.
- Industrial Zones:Petrochemical complexes and combined-cycle power plants adopt absorption chillers paired with waste heat recovery to monetize low-grade thermal streams. Middle Eastern industrial parks prioritize these configurations under fuel diversification policies.
- Residential Complexes:High-rise apartment clusters in dense urban cores achieve network economies unavailable to single-building solutions.
- Institutional Facilities:Universities, hospitals, and government campuses operate on stable occupancy schedules suited to long-term concession contracting.
Commercial Buildings anchor installed capacity, though Industrial Zones are expanding most quickly through waste heat integration mandates.
Cooling Medium:
Regulatory compliance timelines reshape procurement specifications as refrigerant phase-downs accelerate.
- Water:Dominates United Arab Emirates procurement where Emirates Central Cooling Systems Corporation operates extensive water-based distribution networks. Non-toxic profile and minimal environmental regulation exposure sustain its position in dense urban deployments.
- Ammonia:Natural refrigerant with zero ozone depletion potential and negligible global warming potential. European Union F-Gas Regulation phase-down of hydrofluorocarbons positions ammonia as compliance-critical for Netherlands and Denmark plant specifications.
- Glycol:Antifreeze additives extend operating range in sub-freezing ambient conditions.
- Others:Carbon dioxide and emerging low-GWP synthetic blends serve niche transition applications.
Water retains the dominant share, while Ammonia is gaining share fastest under European refrigerant regulations.
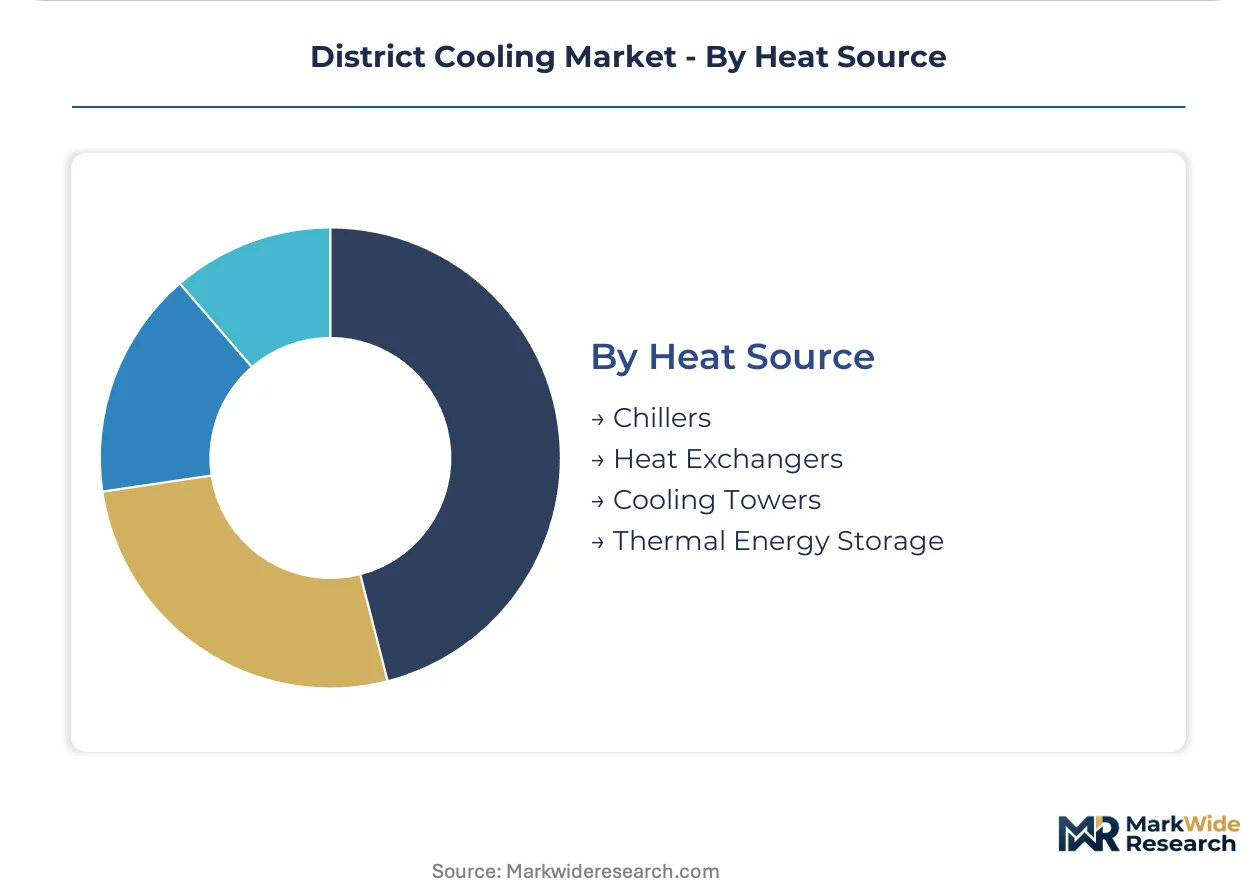
Heat Source:
Technology selection determines project finance structures through capital intensity and operational flexibility trade-offs.
- Thermal Energy Storage:Ice or chilled water tanks decouple electricity consumption from cooling delivery, unlocking peak-shaving revenue where time-of-use tariffs apply. Engie SA competes in Middle Eastern tenders with integrated chiller-thermal storage designs that optimize operational expenditure profiles.
- Chillers:Electric compression and absorption systems remain the primary cooling generation assets. Veolia Environnement anchors European service contracts through long-term concession models covering chiller plant ownership and operation.
- Heat Exchangers:Transfer thermal energy between distribution loops without active refrigeration.
- Cooling Towers:Reject waste heat to atmosphere through evaporative or dry cooling processes.
Chillers command the dominant share, though Thermal Energy Storage is climbing the fastest as electricity market structures reward demand flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial real estate developers and data center operators drive procurement concentration across distinct regulatory environments. Gulf Cooperation Council markets anchor capacity expansion through tightening building energy codes. European jurisdictions prioritize refrigerant compliance under F-Gas Regulation phase-downs. Asian financial centers mandate district cooling through green building certification schemes.
United Arab Emirates
Emirates Central Cooling Systems Corporation and Qatar District Cooling Company anchor regional capacity expansion as commercial developers face tightening chiller plant efficiency thresholds. The country's Regulation and Supervision Bureau sets technical and economic frameworks for cooling tariffs and service continuity in Dubai and Abu Dhabi. Water-based cooling medium systems dominate procurement across dense urban deployments in Dubai Marina and Dubai Internet City.
Singapore
EMA and the Building and Construction Authority enforce Green Mark standards that mandate district cooling for new developments above specified gross floor areas. Keppel District Cooling leverages deep engineering capabilities across the Marina Bay precinct to serve concentrated commercial load densities. Data center operators are reorganizing thermal procurement strategies around centralized architectures in this city-state's digital infrastructure corridor.
Saudi Arabia
The Kingdom's gigaproject pipeline lacks sufficient district cooling infrastructure, creating first-mover positioning for integrated chiller-thermal storage designs. Engie SA competes in Middle Eastern tenders with configurations that optimize operational expenditure profiles. Riyadh and the Eastern Province concentrate demand from commercial and institutional developments under construction.
Netherlands
European Union F-Gas Regulation phase-down of hydrofluorocarbons positions ammonia as compliance-critical for plant specifications. Veolia Environnement anchors European service contracts through long-term concession models covering chiller plant ownership and operation. Amsterdam and Rotterdam districts demonstrate natural refrigerant transitions ahead of mandated phase-out dates.
Qatar
Qatar District Cooling Company anchors regional capacity as commercial real estate developers scale commitments under tightening energy codes. The country's central cooling utility framework supports large-scale thermal procurement for mixed-use developments. Lusail City and West Bay districts concentrate network economies for high-rise commercial and residential clusters.
District Cooling Market Vendor Landscape
Player mix skews toward utility-backed operators and engineering-led specialists with concession contracting expertise. Market structure concentrates around long-term service contracts that lock incumbents into decades-long payback horizons. Strategic archetypes include integrated energy utilities, municipal thermal service providers, and technology-integrated plant operators. Dominant competitive moves encompass geographic expansion into capacity-deficient markets and portfolio diversification through thermal energy storage integration.
Among utility-backed operators, Engie SA and Veolia Environnement exemplify the concession-model archetype with European service contract anchoring. E.ON SE and Vattenfall AB represent Nordic-origin energy utilities extending thermal infrastructure capabilities. Emirates Central Cooling Systems Corporation PJSC occupies a position within the Gulf Cooperation Council specialist tier alongside Qatar District Cooling Company. Keppel District Cooling Pte Ltd. sits within the engineering-integrated operator segment serving Asian financial center precincts.
| Leading Market Players |
|---|
| Keppel District Cooling Pte Ltd. |
| E.ON SE |
| Veolia Environnement S.A. |
| Fortum Oyj |
| Vattenfall AB |
| Engie SA |
| Qatar District Cooling Company |
| Enwave Energy Corporation |
| Emirates Central Cooling Systems Corporation PJSC |
| Others |
Supply Flow & Price Mechanics
Twenty-four-month equipment lead times for large-scale absorption chillers concentrate procurement leverage among Gulf-based developers with advance payment capacity, compressing margins for late-ordering contractors while amplifying pricing power for pre-positioned EPC firms.
Pricing Analysis
Current-generation smart cooling systems command substantial premiums over legacy centralized plants, while next-generation ammonia-based configurations are resetting price floors under European F-Gas Regulation compliance timelines. Three-tier pricing structure across premium smart systems, standard centralized plants, and economy-grade modular units stratifies buyer segments. Cost compression in standard-tier equipment is intensifying because Chinese chiller manufacturers are expanding Middle Eastern distribution partnerships. Data center operators demonstrate lowest price sensitivity due to cooling-as-a-service contract structures that transfer capital risk to utility operators.
Supply Chain Analysis
Strait of Hormuz transit underwrites copper concentrate flows from Chile and Peru to UAE and Saudi fabrication facilities, exposing district cooling pipe networks to geopolitical logistics chokepoints. Manufacturing concentration centers on China, Germany, and South Korea for electric compression chillers and advanced insulation materials. Raw material dependencies include copper piping, polyurethane foam insulation, and specialized refrigerant gases. Single-source vulnerability persists for large-diameter insulated pipe segments where European suppliers dominate technical specifications. Distribution runs through EPC-led project contracting with long-lead equipment procurement preceding civil works.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
District cooling markets are restructuring around service-attach revenue models where predictive maintenance contracts and energy performance guarantees expand faster than hardware sales, creating recurring revenue pools that justify concession-model valuations.
For Market Incumbents: Fortify concession contract portfolios through backward integration into thermal energy storage manufacturing, reducing exposure to modular chiller substitutes that threaten standardized plant deployments. Engie SA and Veolia Environnement demonstrate this defensive positioning through integrated chiller-storage design capabilities. Capacity additions in Saudi Arabia's gigaproject corridor should anchor geographic defense against emerging local competitors.
For New Entrants and Emerging Players: Lead with smart cooling system integration targeting Singapore's Marina Bay precinct and Dubai Internet City, where Green Mark mandates and data center thermal loads create guaranteed demand pipelines. Saudi Arabia's insufficient district cooling infrastructure relative to its development pipeline represents the most penetrable geography. Go-to-market positioning should emphasize AI-driven load forecasting as a differentiated service layer rather than hardware-only procurement.
For Investors and Strategic Acquirers: Carve-out targets emerge from municipal utility divestitures and energy major thermal asset spin-offs across European jurisdictions under decarbonization mandates. Long-term viability frames around concession-model cash flow stability with 10-year contracted revenue visibility. The signal to watch is F-Gas Regulation enforcement intensity in Netherlands and Denmark, where ammonia transition timelines will determine stranded asset risk for synthetic refrigerant-dependent plant portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Energy Storage Integration | Engie SA's chiller-storage designs optimize operational expenditure profiles in Middle Eastern tenders. |
| Natural Refrigerant Transition | Ammonia and carbon dioxide systems maintain F-Gas Regulation compliance timelines in Netherlands and Denmark. |
| Cooling-as-a-Service Expansion | Marina Bay and Dubai Internet City hyperscale tenants demand guaranteed availability without balance-sheet exposure. |
| Digital Twin Platform Deployment | AI-driven load forecasting compresses plant energy intensity through predictive analytics and automated demand response. |
| Gigaproject Corridor Capacity Buildout | Saudi Arabia's Lusail-scale developments lack sufficient district cooling infrastructure for projected commercial loads. |
Methodological Framework
Initial hypotheses were tested against primary input from district cooling plant operators, EPC contractors, commercial real estate developers, and regulatory affairs specialists at Emirates Central Cooling Systems Corporation and Qatar District Cooling Company, and refined through secondary validation across UAE Regulation and Supervision Bureau tariff filings, Singapore Building and Construction Authority Green Mark standards documentation, European Union F-Gas Regulation implementation reports, and IEA district energy system databases. Bottom-up project pipeline tracking and top-down market sizing triangulated volume estimates.
Variance decomposition across system type, application area, cooling medium chemistry, and heat source technology anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers and regulatory enforcement timelines. Forecast inputs incorporated electricity tariff structures, building energy code adoption schedules, and data center power density trajectories.
Forecasts assume regulatory continuity in UAE, Singapore, and European Union regimes; material policy shifts in F-Gas phase-down timelines or Green Mark mandate thresholds would require re-modeling. Practitioners should keep alternative scenarios live as carbon border mechanism implementations and building performance standard evolutions reshape project finance structures for cross-border thermal investments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
Smart Climate Control Market
Energy Management Systems
Peltier Chillers Market
Energy Management Systems
Outage Management System (OMS) Market
Energy Management Systems
United Arab Emirates Portable Air Conditioning Market
Energy Management Systems
USA and Canada Portable Air Conditioner Market
Energy Management Systems
Global Thermal Management Technologies Market
Energy Management Systems
Global Digital Utility Market
Energy Management Systems
Smart Thermostat Market
Energy Management Systems
Europe Home Energy Management System Market
Energy Management Systems
Home Energy Management System Market
Energy Management Systems
Cooling Management System Market
Energy Management Systems
North America Residential Lighting Control System Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
Smart Programmable Thermostat Market