
 Japan Pouch Packaging Market | 2026-2036
Japan Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Pouch Packaging Market Insights
Software-defined packaging traceability is consolidating what converters sell to Japanese food brands. Toppan Packaging Service Co., Ltd. leverages its integrated printing and barrier film capabilities to dominate high-barrier pouch supply for premium seafood exports. Rengo Co. Ltd. anchors the paper-based segment with molded fiber and paper laminate expertise aligned with METI circular economy guidelines. Hosokawa Yoko Co., Ltd. competes through specialized pharmaceutical and medical pouch formats that sustain margins despite raw material volatility.
Japan pouch packaging comprises flexible containers formed from multi-layer films, paper laminates, or aluminum composites, typically sealed by heat or mechanical closure to preserve contents against oxygen, moisture, and light intrusion; retort variants withstand sterilization at temperatures exceeding 121 degrees Celsius to enable ambient shelf stability for prepared foods. Stand-up pouches command the largest volume share among product types due to retail shelf efficiency and consumer handling convenience in convenience stores across Japan. Retort pouches represent the fastest-expanding category as single-person households and aging demographics shift protein and prepared vegetable consumption toward ambient-stable formats. Composites capture premium margin pools where aluminum oxide or silicon oxide barrier coatings replace conventional metalized layers to satisfy both performance and recyclability requirements under emerging packaging waste rules.
METI sets material efficiency targets and recycling infrastructure mandates that directly shape converter investment in mono-material and paper-substrate development. The Japanese Ministry of Environment enforces plastic resource circulation standards that restrict certain multi-layer constructions and push brands toward design-for-recycling certification aligned with JIS packaging protocols. PMDA maintains strict extractables and migration limits for healthcare pouches, creating a compliance barrier that rewards domestic manufacturers with established pharmaceutical quality systems. Stakeholders must monitor whether METI extends extended producer responsibility fees to flexible packaging and decide between retrofitting existing composite lines or accelerating capital deployment into certified recyclable structures before regulatory thresholds tighten.
Market Dynamics
Japan's pouch packaging sector is restructuring around METI's plastic waste reduction mandates, forcing converters to choose between retrofitting multi-layer lines or investing in mono-material and paper-substrate capacity before compliance deadlines tighten.
Growth Catalysts
- Retort Pouch Demand Surge:Single-person households and aging demographics in Japan are shifting protein and prepared vegetable consumption toward ambient-stable formats that eliminate cold-chain dependency.
- METI Circular Economy Guidelines:Japan's Ministry of Economy, Trade and Industry mandates material efficiency targets that accelerate converter investment in recyclable structures and design-for-recycling certification.
- Kanto Industrial Corridor Concentration:Ready-to-eat meal producers cluster around Tokyo and Yokohama, creating dense demand pockets that justify localized high-barrier film production.
Market Restraints
- Aluminum and Resin Price Volatility:Multi-layer composites depend on aluminum oxide and petroleum-derived films, exposing converters to raw material swings that compress margin stability.
- PMDA Extractables Compliance:Japan's pharmaceutical regulator enforces strict migration limits for medical pouches, creating certification timelines that delay new entrant market access.
- Mechanical Recycling Limitations:Existing Japanese recycling infrastructure cannot process conventional multi-layer constructions, forcing brands to absorb higher costs for certified recyclable alternatives.
Strategic Opportunities
- Silicon Oxide Barrier Coatings:Premium seafood exporters are adopting aluminum-free barrier layers that satisfy both shelf-life performance and emerging packaging waste rules.
- Pharmaceutical Pouch Expansion:PMDA's quality system requirements reward domestic manufacturers with established pharmaceutical compliance, insulating margins from commodity competition.
- Paper Laminate Segment Growth:Rengo Co. Ltd.'s molded fiber expertise demonstrates how paper-based formats can capture share aligned with METI circular economy targets.
Industry Challenges
- Mono-Material Line Conversion Costs:Retrofitting existing composite production equipment demands capital deployment before regulatory thresholds tighten, straining mid-tier converters.
- JIS Certification Timeline Compression:Design-for-recycling certification under Japanese Industrial Standards requires extended validation cycles that delay product launches.
- Barrier Performance Trade-offs:Replacing conventional metalized layers with recyclable alternatives forces converters to balance oxygen transmission rates against sustainability claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Pouch Packaging Market |
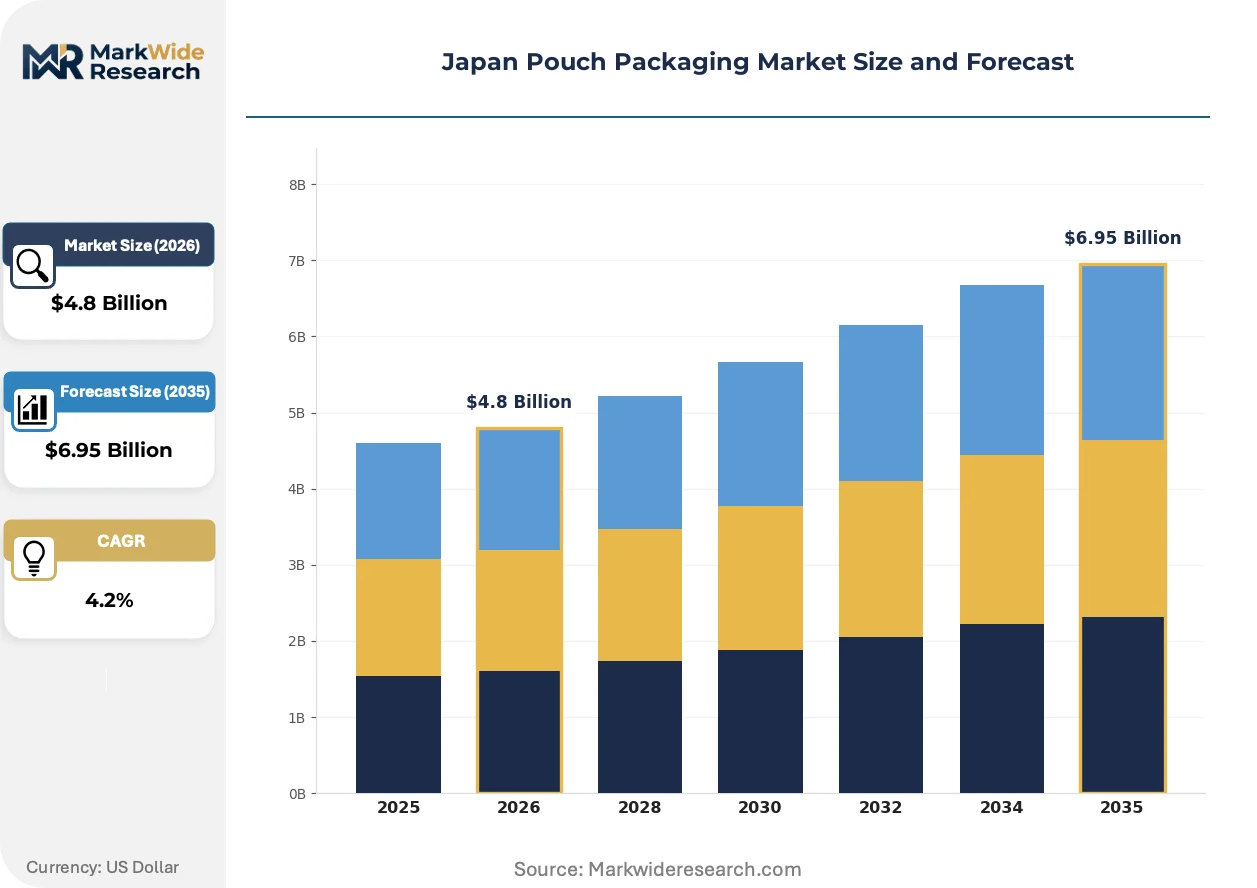
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Gusseted Pouches, Retort Pouches Material: Plastic, Paper, Aluminum, Composites End User: Food & Beverage, Personal Care, Healthcare, Household Products Closure Type: Zip Lock, Spout, Heat Seal, Resealable |
| Companies Covered | Toppan Packaging Service Co., Ltd., Takigawa Corporation, Rengo Co. Ltd., Amcor Group GmbH, Sonoco Products Company, Howa Sangyo Co. Ltd., Hosokawa Yoko Co. Ltd., ZACROS Japan, RM Tohcello Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Pouch Packaging Market Trends and Innovations
Software-defined packaging traceability is consolidating what Japanese converters sell to food brands, merging physical barrier performance with digital authentication layers that verify provenance and recycling compliance.
Mono-material polyethylene pouches are integrating high-barrier coatings to replace multi-layer constructions without sacrificing shelf stability. Premium seafood exporters in Hokkaido and Kyushu are piloting these structures for frozen and ambient distribution. This technology is integrating digital watermarking that enables automated sortation at Japanese recycling facilities, compressing the cost gap between conventional and recyclable formats.
METI's extended producer responsibility framework is tightening material efficiency targets that restrict certain multi-layer constructions. Converters must now document recyclability pathways to maintain brand supply relationships. The ready-to-eat meal segment faces the steepest compliance burden, with producers accelerating JIS certification timelines to avoid placement penalties in major retail channels.
Convenience store chains are consolidating pouch procurement around suppliers offering integrated printing and traceability capabilities. Single-serve retort formats for 7-Eleven and Lawson are displacing traditional canned alternatives in urban Tokyo and Osaka. This concentration is visible most acutely in the Kanto corridor, where shelf-space efficiency and handling convenience override legacy packaging preferences.
Japan Pouch Packaging Market Segmentation
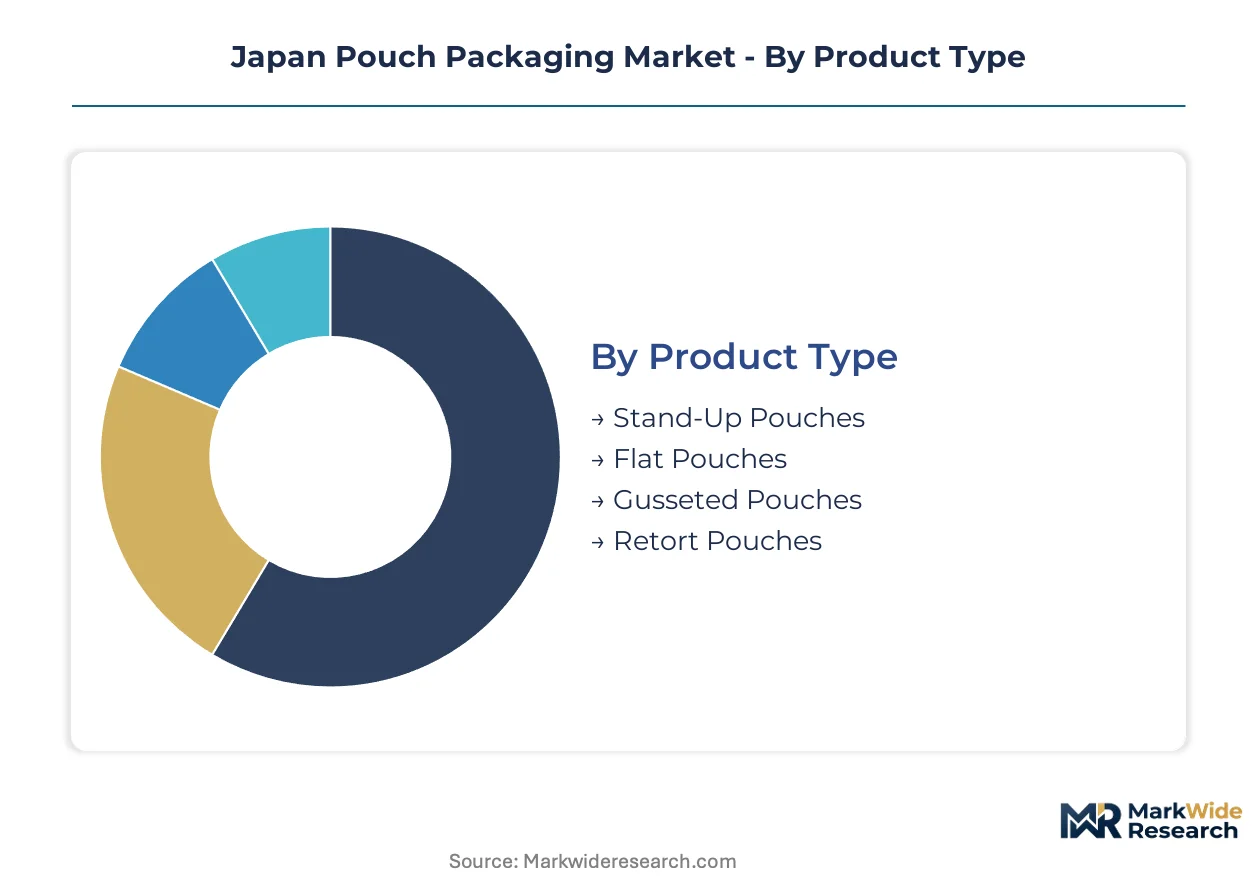
Pouch packaging segmentation in Japan reveals how converters balance shelf performance against METI recyclability mandates. Each dimension—product form, substrate, end-use, and closure—carries distinct compliance burdens and margin profiles that shape capital allocation decisions.
Product Type:
Volume concentration sits with retail-facing formats, while premium expansion clusters around thermal processing applications.
- Stand-Up Pouches:These flexible containers feature bottom gussets that enable vertical display in convenience store chillers across Tokyo and Osaka. Lawson and 7-Eleven procurement teams favor this format for single-serve beverages and wet snacks where shelf-facing efficiency determines placement.
- Retort Pouches:Multi-layer laminates withstand sterilization above 121 degrees Celsius, enabling ambient distribution of prepared proteins and vegetables. Single-person households in the Kanto corridor are displacing canned alternatives with these formats, creating the steepest expansion trajectory among all product types.
- Flat Pouches:Two-dimensional sealed bags dominate dried food and powder applications where pallet density outweighs retail presentation needs.
- Gusseted Pouches:Side-folded constructions expand volume capacity for bulk dry goods and industrial ingredients distributed through Japanese wholesale channels.
Today's leader: Stand-Up Pouches. Tomorrow's challenger: Retort Pouches.
Material:
Substrate selection now hinges on JIS recyclability certification timelines rather than barrier performance alone.
- Composites:Aluminum oxide and silicon oxide barrier coatings replace conventional metalized layers to satisfy both shelf-life requirements and emerging packaging waste rules. Premium seafood exporters in Hokkaido are piloting these structures for frozen distribution to Asian markets.
- Plastic:Mono-material polyethylene constructions are integrating high-barrier coatings to replace multi-layer constructions without sacrificing stability. METI material efficiency targets are accelerating converter investment in these certified recyclable alternatives.
- Paper:Molded fiber and paper laminate expertise aligns with METI circular economy guidelines, capturing share in dry food and personal care applications where moisture sensitivity is moderate.
- Aluminum:Pure foil constructions sustain niche pharmaceutical and medical pouch formats where PMDA extractables compliance demands established quality systems.
Composites dominate premium margin pools. Paper laminates are climbing fastest under regulatory pressure.
End User:
Application mix reflects Japan's demographic compression and convenience retail consolidation.
- Food & Beverage:Ready-to-eat meal producers cluster around the Kanto industrial corridor, generating dense demand for high-barrier retort and stand-up formats that eliminate cold-chain dependency.
- Healthcare:PMDA migration limits and extractables testing create certification barriers that reward domestic manufacturers with established pharmaceutical quality systems.
- Personal Care:Single-serve sachets and resealable pouches for cosmetics and toiletries concentrate in urban Tokyo and Osaka convenience channels.
- Household Products:Refill pouches for detergents and cleaners align with METI plastic waste reduction targets through concentrated formulations that reduce packaging mass.
Food & Beverage commands volume concentration. Healthcare insulates margins through regulatory complexity.
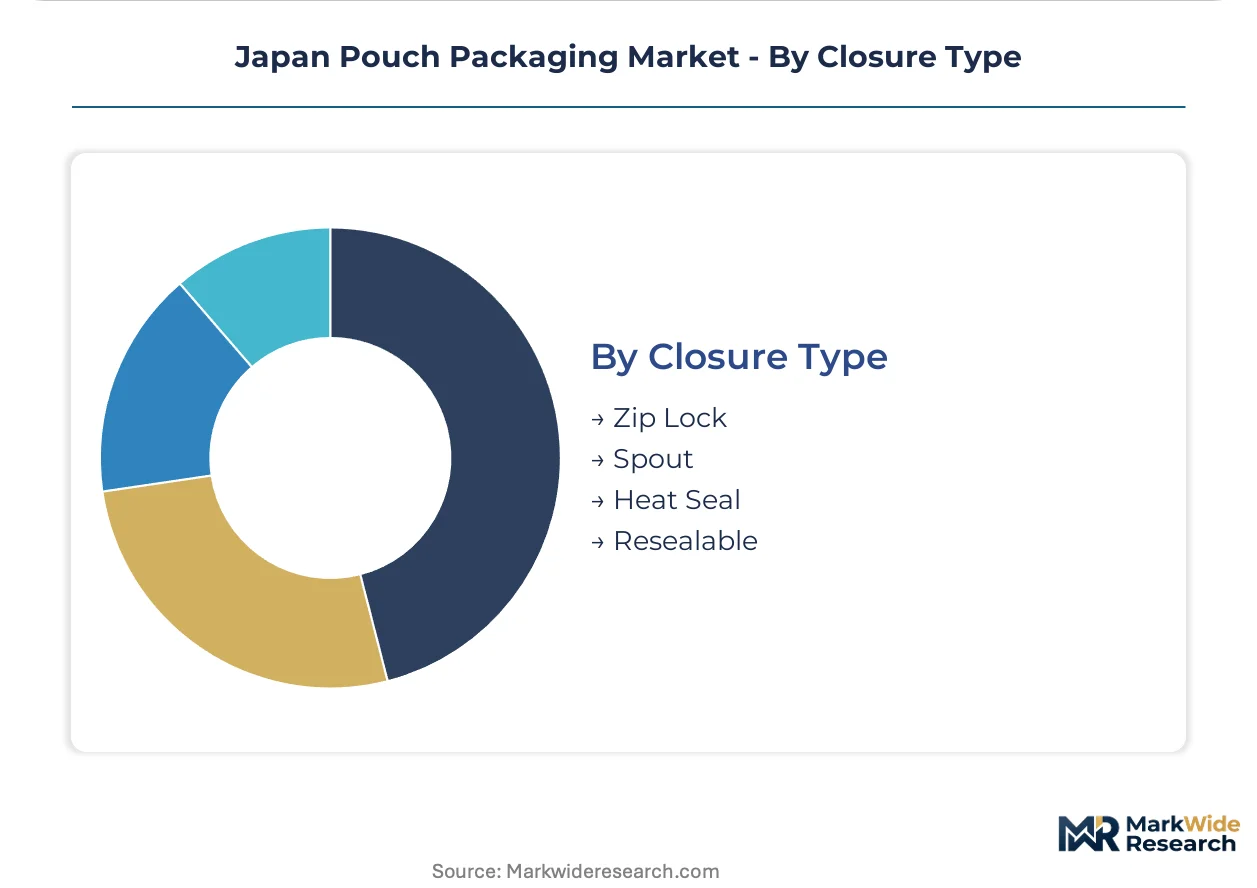
Closure Type:
Consumer handling convenience and recycling compatibility drive format selection in Japanese retail channels.
- Heat Seal:Permanent fusion closures dominate retort and ambient-stable formats where hermetic integrity is mandatory for shelf-life extension.
- Zip Lock:Interlocking plastic tracks enable repeated access for snack and dried food applications in convenience store distribution.
- Spout:Integrated dispensing fitments capture beverage and liquid food share where controlled pouring replaces full package opening.
- Resealable:Adhesive strip and mechanical closure hybrids balance convenience with mono-material recyclability for METI-compliant designs.
Heat Seal anchors industrial volume. Spout closures are expanding fastest in beverage applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pouch packaging sector emphasizes pharmaceutical-grade barrier films, whereas Japan's market concentrates around convenience retail consolidation and METI-mandated recyclability transitions.
Kanto/Tokyo
Single-person households and aging demographics in Tokyo and Yokohama drive retort pouch consumption for ambient-stable proteins. METI's plastic waste reduction targets accelerate converter investment in mono-material lines across the industrial corridor. Convenience store chains including 7-Eleven and Lawson consolidate procurement around suppliers with integrated printing and traceability capabilities.
Kansai/Osaka
Osaka-based food manufacturers prioritize stand-up pouches for wet snacks and beverages in urban retail channels. The Ministry of Environment enforces plastic resource circulation standards that restrict multi-layer constructions. Local converters retrofit existing composite equipment to meet JIS design-for-recycling certification timelines.
Kyushu
Premium seafood exporters in Fukuoka and surrounding prefectures pilot silicon oxide barrier coatings for frozen distribution to Asian markets. METI circular economy guidelines push aluminum-free alternatives that satisfy both shelf-life performance and emerging packaging waste rules. Regional processing clusters align substrate selection with recyclability certification requirements.
Hokkaido
Marine product processors in Hakodate and Otaru adopt high-barrier retort formats for long-distance domestic distribution. PMDA maintains strict extractables limits for healthcare applications, creating compliance barriers that favor established regional manufacturers. Cold-chain infrastructure limitations amplify demand for ambient-stable packaging across the northern island.
Japan Pouch Packaging Market Competitive Landscape
Top-tier vendors anchor integrated printing and barrier film supply, while mid-tier specialists compete through substrate-specific expertise or pharmaceutical compliance systems. The vendor base stratifies across three tiers: multinational converters with full-service platforms, domestic leaders with METI-aligned circular economy capabilities, and niche players serving PMDA-regulated medical segments. Dominant competitive moves include retrofitting multi-layer production lines for mono-material output and securing JIS certification ahead of regulatory threshold tightening.
Within the domestic specialist tier, Toppan Packaging Service Co., Ltd. and Rengo Co. Ltd. exemplify contrasting strategic positions—Toppan represents integrated printing and high-barrier film dominance for premium food exports, while Rengo anchors paper-based formats aligned with METI guidelines. Hosokawa Yoko Co., Ltd. occupies a position within the pharmaceutical-certified segment where PMDA quality system requirements insulate margins from commodity competition.
| Leading Market Players |
|---|
| Toppan Packaging Service Co., Ltd. |
| Takigawa Corporation |
| Rengo Co. Ltd. |
| Amcor Group GmbH |
| Sonoco Products Company |
| Howa Sangyo Co. Ltd. |
| Hosokawa Yoko Co., Ltd. |
| ZACROS Japan |
| RM Tohcello Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Mono-material line conversion across Japanese converters is compressing cost differentials between conventional multi-layer films and certified recyclable alternatives while redistributing pricing power toward integrated suppliers with captive coating capabilities.
Pricing Analysis
Capacity additions in the Kanto industrial corridor are reshaping price floors for high-barrier retort films. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified recyclable constructions from legacy multi-layer formats. Pricing pressure stems from aluminum oxide and resin cost volatility that squeezes mid-tier converters lacking backward integration. Small ready-to-eat meal producers exhibit highest price sensitivity, while pharmaceutical brands under PMDA oversight absorb premium tiers.
Supply Chain Analysis
Freight costs from petrochemical feedstock terminals in Chiba and Kawasaki amplify working capital requirements for converters serving Kyushu seafood exporters. Supply concentrates in Japan, South Korea, and Taiwan for barrier film substrates and coating equipment. Raw material dependencies center on polyethylene resins, silicon oxide deposition targets, and aluminum oxide sputtering materials. Single-source vulnerability runs through specialized vacuum coating equipment. Distribution runs through converter-direct relationships with major convenience store chains and regional seafood processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's pouch packaging sector functions as a stable compounder where METI-mandated recyclability transitions generate persistent replacement demand across installed converter capacity.
For Market Incumbents: Lock in JIS certification timelines ahead of regulatory threshold tightening to foreclose mid-tier competitors from brand supply relationships. Deepen upstream control over silicon oxide coating capacity to defend margin position against resin price volatility. Secure exclusive procurement arrangements with 7-Eleven and Lawson as convenience store consolidation accelerates format standardization. For New Entrants and Emerging Players: Capture white-space in pharmaceutical-certified pouch formats where PMDA quality system requirements insulate margins from commodity competition. Target Hokkaido marine processors seeking high-barrier retort alternatives to canned distribution. Lead with digital traceability integration as a go-to-market wedge against legacy converters lacking software-defined packaging capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier converters facing mono-material retrofit capital demands without secured brand offtake. Long-term viability favors assets with established pharmaceutical compliance or integrated printing-barrier film platforms. Watch METI extended producer responsibility fee announcements as the signal for accelerated consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Line Conversion | Retrofitting multi-layer equipment for polyethylene barrier coatings satisfies METI recyclability mandates ahead of compliance deadlines. |
| JIS Certification Acceleration | Design-for-recycling validation under Japanese Industrial Standards secures placement in Lawson and 7-Eleven procurement channels. |
| Silicon Oxide Coating Investment | Aluminum-free barrier layers capture premium seafood export demand while aligning with emerging packaging waste rules. |
| Pharmaceutical Quality System Expansion | PMDA-compliant manufacturing insulates margins from commodity competition in medical pouch applications. |
| Software-Defined Traceability Integration | Digital authentication layers merge with physical barrier performance to consolidate converter-brand relationships. |
Research Methodology
Coverage spans Japan's Kanto, Kansai, Kyushu, and Hokkaido regions, with primary inputs from each converter cluster and downstream demand pocket. The analysis combines interviews with packaging development executives at major food brands, procurement managers at convenience store chains, technical directors at barrier film coaters, and regulatory affairs leads familiar with METI circular economy guidelines. Secondary validation draws from METI policy documents, PMDA pharmaceutical packaging guidelines, JIS certification registries, and Japanese customs trade data. Bottom-up demand modeling and top-down supply capacity assessments were triangulated to establish market sizing.
Rate-of-change decomposition separates volume growth from value expansion across the analysis window. Segmentation dimensions include product type, substrate material, end-use application, and closure mechanism, with additional modeling of regional regulatory cluster effects. CAGRs were derived from fitted growth curves applied to converter capacity expansion plans and brand procurement forecasts. Industry-specific inputs incorporate METI plastic waste reduction target timelines and PMDA extractables compliance certification cycles.
Underlying measurement precision varies by segment; retort pouch and stand-up pouch categories carry tighter precision than emerging paper laminate formats. Forecasts reflect assumptions about regulatory enforcement consistency and resin price stability. A model refresh is warranted upon material change in METI extended producer responsibility fee structures or JIS certification timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
Pre-Made Pouch Packaging Market
Pouch
Heat Seal Pouch Market
Pouch
Anti-Static Foam Pouch Market
Pouch
Box Pouch Market
Pouch
Open Mouth Sacks Market
Pouch
Horizontal Premade Pouch Packing Machine Market
Pouch
Europe Retort Pouches Market
Pouch
Foil Pouch Packaging Market
Pouch
Clear Pouches Market
Pouch
Kraft Block Bottom Pouch Market
Pouch
Flexible Plastic Pouches Market
Pouch
North America Lithium-Ion Battery Pouch Film Market
Pouch
Flexible Plastic Drinking Pouch Market
Pouch
Doy Pouch Packaging Market
Pouch
Vented Stretch Wrap Market