
 PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market | 2026-2036
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market Insights
Multi-source equipment procurement is expanding across European recycling operations as processors hedge against technology lock-in. EREMA Group leverages its extrusion technology leadership to dominate mechanical recycling deployments. TOMRA sustains its position through sensor-based sorting systems that handle laminated pouch streams. STADLER anchors large-scale plant engineering contracts across centralized recycling infrastructure.
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems encompass integrated machinery and process lines designed to recover polyethylene and polypropylene from flexible multilayer stand-up pouches, operating at throughput rates exceeding one ton per hour with contamination thresholds below five percent. Mechanical recycling systems currently lead installed capacity but face margin compression from rising feedstock competition, while chemical recycling systems command premium pricing due to virgin-equivalent output quality. Deployment through onsite facilities is accelerating among food packaging converters seeking closed-loop compliance, whereas centralized recycling plants retain scale advantages for personal care and household supply streams.
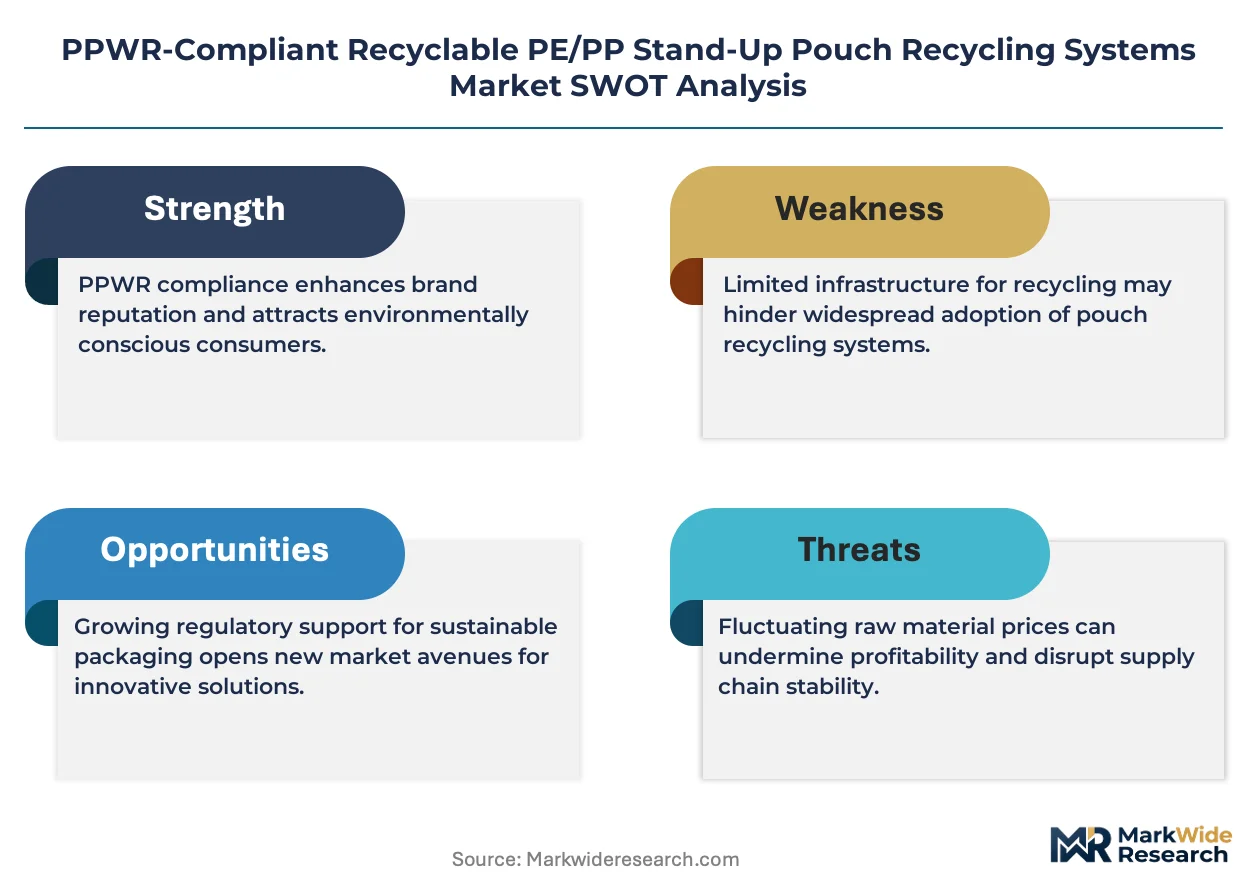
The European Commission's PPWR implementation timeline, enforced through national agencies such as Germany's KBA and France's ANSM alongside ECHA REACH substance restrictions, mandates recyclability design standards that directly determine equipment procurement specifications. EMA and EFSA compliance requirements for food-contact recycled materials further constrain technology selection and validation protocols. Stakeholders must monitor regulatory divergence between EU member states on chemical recycling mass-balance accounting rules to avoid stranded asset risk in facility planning.
Market Dynamics
The EU Packaging and Packaging Waste Regulation mandates are compressing technology adoption timelines, forcing food packaging converters to choose between mechanical and chemical recycling pathways before mass-balance accounting rules fully crystallize.
Growth Catalysts
- REACH substance restrictions:ECHA's evolving chemical safety frameworks are eliminating legacy adhesive systems, compelling pouch manufacturers to redesign for monomaterial compatibility that mechanical recycling lines can process.
- Food packaging converters:Major European brands are embedding recyclability specifications into supplier contracts, creating pull-through demand for integrated sorting and extrusion systems capable of food-contact output.
- Onsite closed-loop facilities:Germany's KBA enforcement timeline is accelerating capital deployment toward distributed recycling infrastructure that eliminates feedstock transport costs and contamination risks.
Market Restraints
- Feedstock cost volatility:Post-consumer flexible film collection rates vary dramatically between Germany's dual systems and France's extended producer responsibility schemes, creating input price instability for plant operators.
- Technology supplier concentration:Austrian and German extrusion equipment manufacturers dominate high-throughput mechanical recycling, exposing buyers to extended lead times and limited negotiation leverage.
- Chemical recycling yield limitations:Pyrolysis and gasification systems for contaminated multilayer pouches achieve sub-optimal conversion efficiency versus virgin resin economics, constraining project finance availability.
Strategic Opportunities
- Spain and Italy underpenetration:Southern European markets lack centralized flexible film recycling infrastructure, creating first-mover advantages for operators securing municipal collection contracts.
- Personal care monomaterial conversion:Shampoo and detergent pouch formats are migrating to single-polymer constructions that bypass chemical recycling entirely, favoring mechanical system deployments.
- EMA food-contact validation:Accelerated regulatory pathways for recycling process notification are shortening time-to-market for converters targeting premium food packaging applications.
Industry Challenges
- Polymer identification skill scarcity:Operating advanced near-infrared sorting systems requires technicians trained in spectroscopic analysis, a competency gap acute in Eastern European labor markets.
- EFSA compliance timeline compression:Novel food-contact recycling processes face 18-24 month safety evaluation cycles that misalign with brand sustainability commitments announced for 2027-2028.
- Legacy extrusion integration:Retrofitting existing film production lines with recycled content feed systems demands substantial downtime that contract manufacturers cannot absorb without penalty clauses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market |
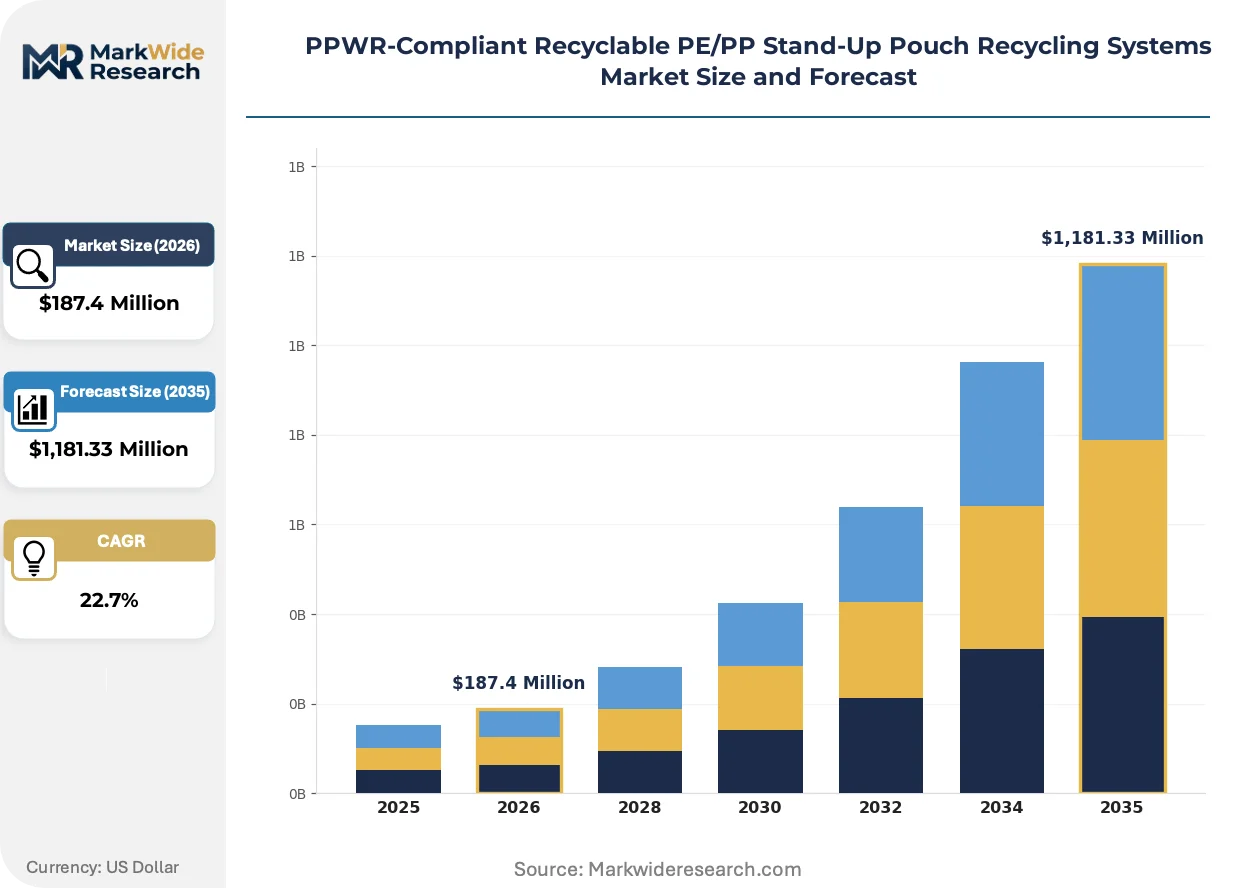
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Mechanical Recycling, Chemical Recycling, Thermal Recycling, Biological Recycling, Solvent-Based Recycling End Use Industry: Food Packaging, Personal Care Products, Pharmaceutical Packaging, Electronic Goods Packaging, Household Supplies Deployment Model: Onsite Facilities, Centralized Recycling Plants, Mobile Recycling Units, Contracted Third-Party Services Technology: Extrusion, Depolymerization, Pyrolysis, Enzymatic Treatment, Flotation Techniques |
| Companies Covered | EREMA Group, TOMRA, STADLER, Pellenc ST, Amut Group, NGR, Starlinger Recycling Technology, Bollegraaf Recycling Solutions, Sesotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market Trends and Innovations
Technology convergence between sensor-based sorting and advanced extrusion is redefining acceptable contamination thresholds, while regulatory mass-balance frameworks determine which process configurations qualify for recycled content claims.
Near-infrared spectroscopy combined with robotic pickers is integrating into pre-sorting lines to identify and eject non-target polymers before they enter extrusion systems. Food packaging converters in the Netherlands and Belgium are deploying these hybrid configurations at pilot scale. The technology is integrating previously incompatible laminated streams into mechanical recycling economics by reducing downstream purification burden.
France's ANSM is coordinating with EFSA to establish accelerated safety assessment protocols for chemically recycled polyolefins intended for food contact. This regulatory alignment is compressing validation timelines from thirty-six to eighteen months for qualified applicants. Personal care and household product segments are responding by locking in offtake agreements with chemical recycling operators ahead of food-grade certification completion.
Buyers are consolidating equipment procurement under performance-based contracting structures that transfer yield risk to technology suppliers. Large-scale converters in Germany are replacing traditional capital purchase models with throughput guarantees and output quality penalties. This shift is most visible among multinational FMCG brands operating integrated packaging facilities in the Rhine-Ruhr industrial cluster.
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market Segmentation
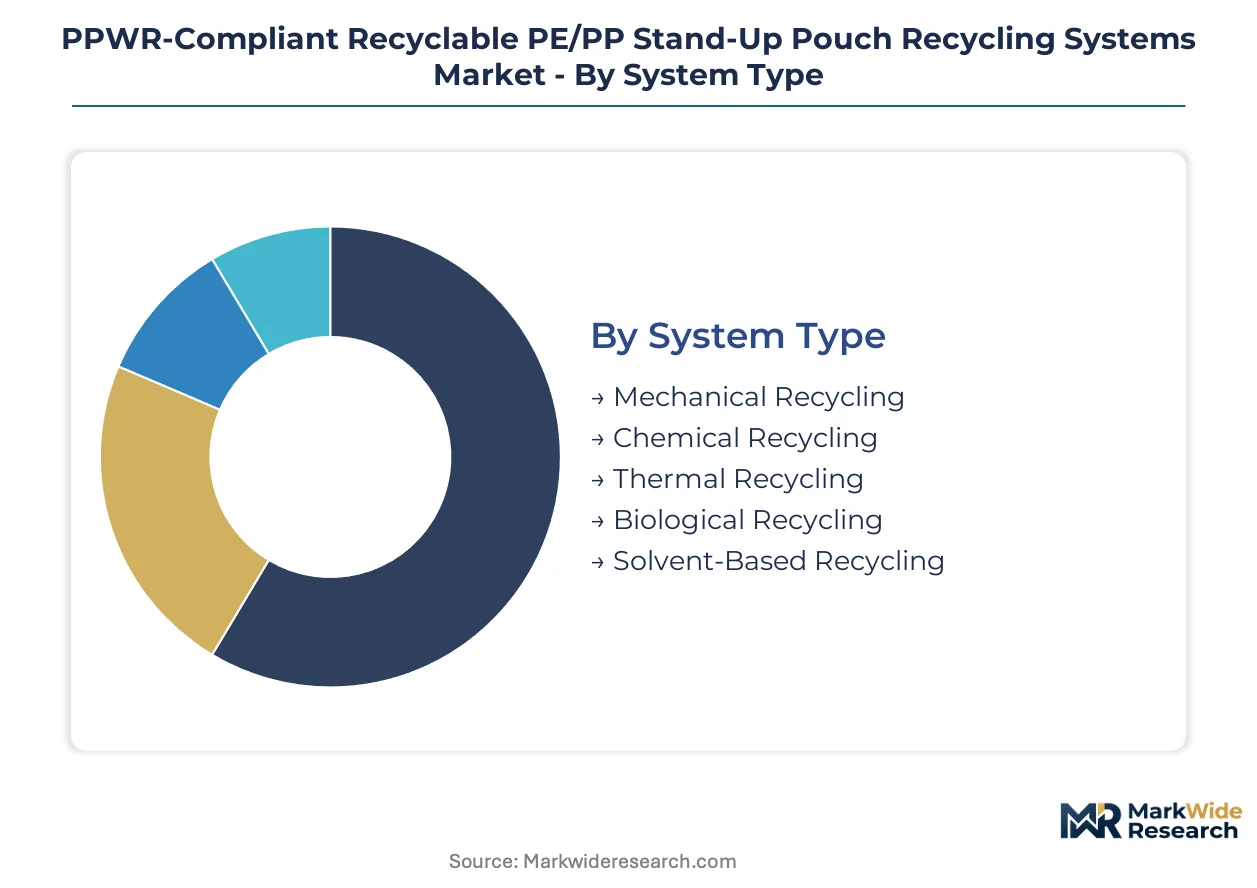
Equipment procurement decisions across the European recycling value chain hinge on segment-specific capital requirements, regulatory compliance pathways, and feedstock availability. Technology selection within each dimension directly determines facility economics and stranded asset exposure.
System Type:
Capital intensity varies dramatically across recycling modalities, with chemical systems demanding five-to-ten-fold higher upfront investment than mechanical alternatives.
- Mechanical Recycling:Extrusion-based reprocessing lines grind, wash, and pelletize monomaterial PE/PP streams at throughputs exceeding one ton per hour. German food packaging converters along the Rhine-Ruhr corridor anchor demand as KBA enforcement timelines compress procurement decisions.
- Chemical Recycling:Pyrolysis and depolymerization units convert contaminated multilayer pouches into virgin-equivalent feedstock. French brands seeking ANSM-aligned food-contact pathways are locking in offtake agreements ahead of EFSA certification completion.
- Thermal Recycling:Energy recovery systems process non-recyclable fractions with limited material recovery.
- Biological Recycling:Enzymatic breakdown of bio-based pouch materials remains pre-commercial at scale.
- Solvent-Based Recycling:Selective dissolution systems separate polymer layers without thermal degradation.
Most installed capacity flows through Mechanical Recycling. Expansion is steepest in Chemical Recycling.
End Use Industry:
Application-driven contamination profiles dictate technology selection, with food-contact requirements imposing the strictest purification burdens.
- Food Packaging:EFSA-compliant output demands sub-five-percent contamination thresholds and full batch traceability. Dutch and Belgian converters pilot near-infrared pre-sorting to integrate laminated streams previously excluded from mechanical economics.
- Personal Care Products:Shampoo and detergent pouch migration toward single-polymer constructions favors lower-capital mechanical deployments over chemical alternatives.
- Pharmaceutical Packaging:EMA validation requirements for recycled content in drug-contact materials remain under development.
- Electronic Goods Packaging:Anti-static and barrier specifications complicate monomaterial conversion.
- Household Supplies:Cleaning product pouches with aggressive chemical residues require specialized washing infrastructure.
Food Packaging commands the dominant share of validation expenditure. Personal Care Products are gaining share fastest as monomaterial redesign accelerates.
Deployment Model:
Facility configuration determines feedstock transport economics and contamination risk exposure across the value chain.
- Onsite Facilities:Closed-loop systems at converter locations eliminate logistics costs and enable direct quality feedback loops. Germany's KBA timeline is accelerating capital deployment toward distributed infrastructure.
- Centralized Recycling Plants:Large-scale operations achieve economies of scope across heterogeneous feedstock streams. STADLER-engineered facilities in France and Benelux handle personal care and household supply volumes at scale.
- Mobile Recycling Units:Containerized systems serve seasonal agricultural film collection.
- Contracted Third-Party Services:Toll processing agreements transfer yield risk to specialized operators.
Centralized Recycling Plants absorb the majority of tonnage. Onsite Facilities are expanding most quickly among multinational FMCG brands.
Technology:
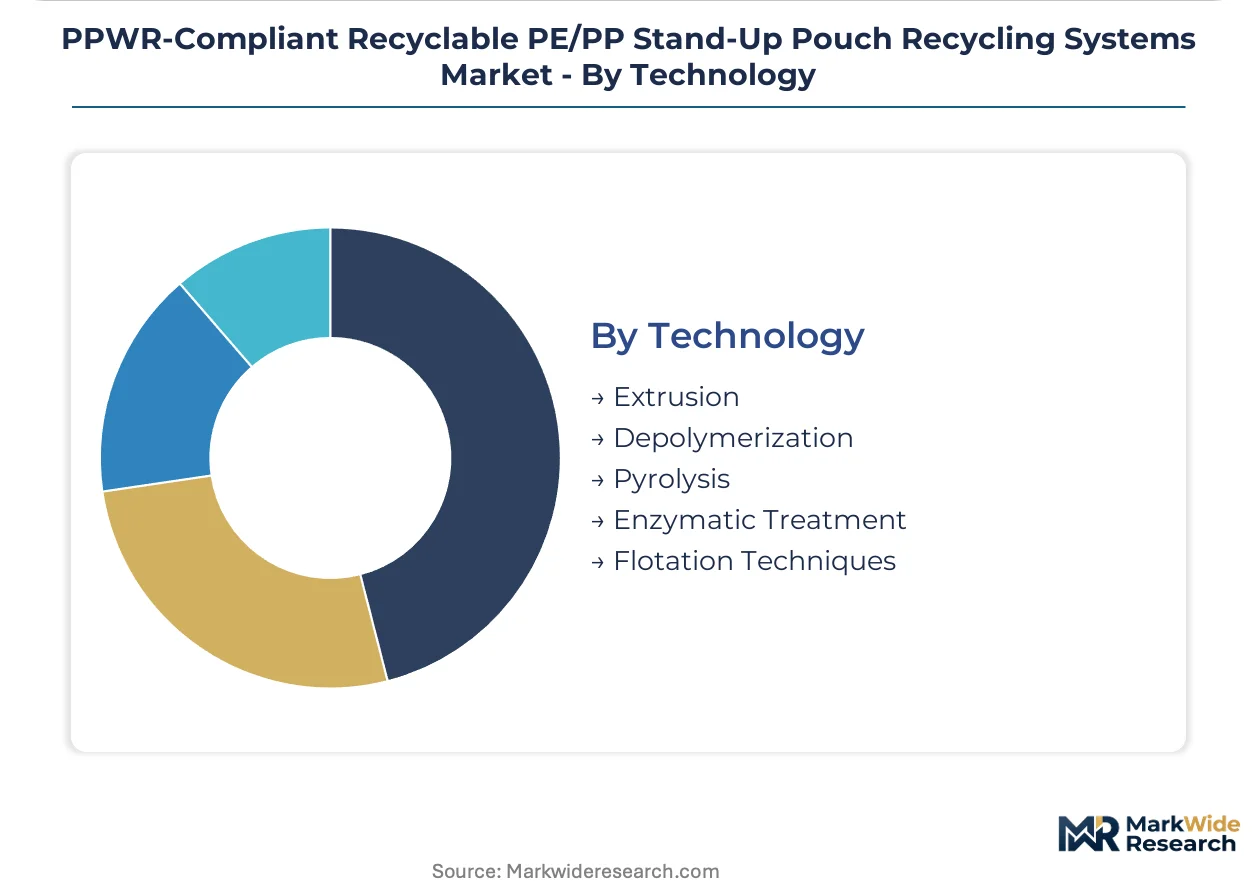
Core process selection locks in output specifications, energy intensity, and regulatory qualification pathways.
- Extrusion:EREMA Group's high-throughput systems dominate mechanical recycling deployments with integrated melt filtration achieving food-contact purity.
- Depolymerization:Catalytic breakdown to monomer feedstock enables circular loop closure for contaminated multilayer structures.
- Pyrolysis:Thermal cracking yields synthetic crude requiring downstream refining for polymer-grade output.
- Enzymatic Treatment:Protein-engineered depolymerization targets bio-PE and bio-PP streams.
- Flotation Techniques:Density-based separation removes contaminants before extrusion.
Extrusion anchors current installed base. Depolymerization is climbing the fastest as mass-balance accounting rules crystallize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European demand for PPWR-compliant recycling infrastructure as Germany's KBA enforcement timeline compresses procurement decisions across mechanical and chemical technology pathways.
Germany
Food packaging converters in North Rhine-Westphalia and Bavaria are deploying onsite closed-loop facilities to eliminate feedstock transport costs. KBA's implementation schedule for extended producer responsibility mandates is accelerating capital commitments toward distributed recycling architectures. EREMA Group's extrusion systems dominate mechanical deployments across the Rhine-Ruhr corridor.
France
ANSM coordination with EFSA on accelerated food-contact safety assessments is compressing validation timelines for chemically recycled polyolefins. Major personal care brands are locking in offtake agreements with pyrolysis operators ahead of certification completion. The Paris-Saclay research cluster is emerging as a hub for mass-balance accounting methodology development.
Netherlands
Dutch converters are piloting near-infrared pre-sorting configurations to integrate laminated pouch streams previously excluded from mechanical recycling economics. Port of Rotterdam infrastructure is enabling chemical recycling feedstock import logistics for multilayer contamination streams. Eindhoven-based equipment integrators are supplying hybrid sorting-extrusion lines to Belgian and German buyers.
Italy
Southern European underpenetration in flexible film recycling infrastructure is creating first-mover opportunities for operators securing municipal collection contracts in Lombardy and Emilia-Romagna. Italian packaging converters are migrating shampoo and detergent pouch formats toward single-polymer constructions. Milan's industrial district is attracting mechanical recycling equipment deployments targeting personal care monomaterial streams.
Spain
Centralized recycling plant engineering contracts remain scarce across the Iberian Peninsula despite rising post-consumer collection volumes under extended producer responsibility schemes. Barcelona and Madrid metropolitan areas are emerging as priority locations for STADLER-engineered large-scale facilities. REACH substance restrictions on legacy adhesive systems are compelling pouch manufacturers to redesign for monomaterial compatibility.
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market Competitive Landscape
Global majors compete with regional champions across extrusion technology and sensor-based sorting domains, producing a tiered structure where Austrian and German equipment manufacturers command premium positioning in high-throughput mechanical recycling. The vendor landscape consolidates around three strategic archetypes: integrated plant engineering specialists, component technology leaders, and toll-processing service operators. Capacity expansion through performance-based contracting structures is displacing traditional capital purchase models. Geographic expansion into underpenetrated Southern European markets is accelerating among scale-driven players.
Within the integrated plant engineering tier, STADLER anchors large-scale facility deployments across France and Benelux. Among component technology specialists, EREMA Group and TOMRA occupy distinct positions—extrusion systems versus sensor-based sorting—without direct product overlap. These three companies exemplify the competitive structure: one representing turnkey infrastructure, one representing process equipment, and one representing material identification technology.
| Leading Market Players |
|---|
| EREMA Group |
| TOMRA |
| STADLER |
| Pellenc ST |
| Amut Group |
| NGR |
| Starlinger Recycling Technology |
| Bollegraaf Recycling Solutions |
| Sesotec |
| Others |
Pricing and Supply Chain Analysis
Food packaging converters in Germany and France are mandating food-contact-grade recycled content specifications in supplier contracts, compelling equipment manufacturers to absorb certification costs and compressing margins across mechanical recycling system tiers.
Pricing Analysis
Input-cost pass-through from specialized alloy components and precision extrusion dies is compressing margins for mid-tier equipment suppliers. Pricing stratifies across EFSA-certified premium systems, CE-marked standard configurations, and economy lines lacking food-contact validation. Cost compression in the standard tier is intensifying because Austrian and German manufacturers dominate high-throughput mechanical recycling, limiting buyer negotiation leverage. Brand-owned converters show lowest price sensitivity due to sustainability commitment timelines, whereas independent toll processors face acute margin pressure from feedstock cost volatility.
Supply Chain Analysis
Freight costs for oversized extrusion systems and pyrolysis reactor modules from Austria, Germany, and Italy are adding fifteen-to-twenty percent to landed equipment costs for Southern European buyers. Equipment manufacturing draws from specialty steel foundries in Austria, precision gearbox producers in Germany, and sensor component suppliers in the Netherlands. Single-source vulnerability concentrates in high-throughput melt filtration systems where EREMA Group holds dominant market position. Distribution runs through direct OEM sales for large converters and regional equipment integrators for mid-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation functions as a demand compounder, with Germany's KBA enforcement timeline forcing procurement decisions before mass-balance accounting rules fully crystallize.
For Market Incumbents: Extend certification coverage across EFSA and EMA validation pathways to preempt competitor lock-in of food-contact recycling contracts. Add capacity in Spain and Italy before municipal collection contract windows close. Chemical recycling yield limitations and extended lead times from Austrian component suppliers threaten margin stability without geographic diversification. For New Entrants and Emerging Players: Begin with solvent-based recycling pilot deployments in Lombardy and Emilia-Romagna, where centralized flexible film infrastructure remains underdeveloped. Personal care monomaterial conversion offers the most penetrable segment given lower purification burdens versus food-contact requirements. Partner with Eindhoven-based equipment integrators to supply hybrid sorting-extrusion configurations without bearing full R&D burden. For Investors and Strategic Acquirers: Asymmetric upside sits with toll-processing service operators holding municipal collection contracts in Southern Europe, as infrastructure scarcity creates pricing power over feedstock access. Five-to-ten year viability hinges on mass-balance accounting rule crystallization favoring chemical recycling output claims. Watch for EFSA certification completion timelines as inflection indicator for food-contact offtake agreement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Certification Investment | Accelerates food-contact recycled content validation for Rhine-Ruhr converter contracts. |
| Southern European Facility Expansion | Captures first-mover municipal collection contracts in Spain and Italy before competitor entry. |
| Performance-Based Contracting Shift | Transfers yield risk from converters to equipment suppliers across German FMCG installations. |
| Near-Infrared Pre-Sorting Integration | Enables Dutch and Belgian converters to process laminated streams previously excluded from mechanical economics. |
| Chemical Recycling Offtake Lock-In | Secures French personal care brand commitments ahead of ANSM-EFSA regulatory alignment completion. |
Research Methodology
Multiple input streams — primary interviews with plant engineering directors, regulatory affairs leads at packaging converters, and EPC contractors — were reconciled against secondary validation from ECHA REACH substance restriction filings, KBA enforcement schedule disclosures, and customs equipment import records. Bottom-up capacity installation tracking across Germany, France, Netherlands, Italy, and Spain was cross-referenced with top-down spending estimates from extended producer responsibility scheme filings.
Historical installation data was cross-referenced against expert panel input from equipment manufacturers and recycling plant operators to establish trajectory parameters across the projection horizon. Segmentation dimensions modeled include system type, end-use industry, deployment model, and technology pathway, with CAGRs derived from regression analysis of capital commitment timing against regulatory milestone schedules. Feedstock availability assumptions incorporated dual-system collection rate differentials between German and French extended producer responsibility schemes.
Several conditions sit outside the modeled scope, including potential regulatory divergence on chemical recycling mass-balance accounting rules and unannounced EFSA safety assessment protocol revisions. Forecasts reflect documented assumptions about KBA enforcement adherence and EMA validation pathway accessibility. Stakeholders should weight assumptions against their own operating context and monitor ANSM-EFSA coordination announcements for timeline compression signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Stand Up Paper Pouches Market
Pouch
Standcap Pouch Market
Pouch
Vented Stretch Wrap Market
Pouch
Japan Pouch Packaging Market
Pouch
Clipless Vertical Pouches Market
Pouch
Sterilization Pouches Market
Pouch
North America Stand-Up Pouch Packaging Market
Pouch
Global Anti Static Bubble Pouch Market
Pouch
Slider Pouches Market
Pouch
Peelable Pouches Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
North America Lithium-Ion Battery Pouch Film Market
Pouch
Argentina Pouch Packaging Market
Pouch
Aluminum Pouches Market
Pouch
Twin Pouch Packaging Market
Pouch
Telemetry Pouch Market