
 Zipper Pouch Market | 2026-2036
Zipper Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Zipper Pouch Market Analytics
Food-grade barrier specifications is rotating toward higher oxygen and moisture resistance as brands compete on shelf-life extension. ProAmpac LLC leverages its film extrusion capabilities to supply multilayer structures for protein packaging. Glenroy, Inc. anchors the premium printed segment with gravure and flexographic expertise for specialty food brands. Amcor plc dominates global pharmaceutical-grade zipper pouch supply with cleanroom-certified production lines across multiple continents.
A zipper pouch is a flexible packaging format incorporating an interlocking closure mechanism, typically constructed from laminated films of polyethylene, polypropylene, or aluminum foil with seal strengths ranging from 15 to 50 N per 15 mm width, designed for repeated opening and closing while maintaining product integrity. Plastic material types lead volume due to cost efficiency in high-speed form-fill-seal operations, though foil laminates command margin pools in pharmaceutical and retort applications where thermal stability exceeds 121 degrees Celsius. Double zipper closure types represent the fastest-growing structural segment as e-commerce fulfillment networks prioritize leak resistance during last-mile transit.
The FDA regulates direct food-contact layers under 21 CFR 177 with migration limits for additives and adhesives, while the EU Packaging and Packaging Waste Regulation mandates recyclability targets that reshape material selection across export-bound production. ISO 9001 and BRCGS certification frameworks govern quality management and food safety protocols, creating market access barriers for uncertified converters. Stakeholders must monitor evolving extended producer responsibility schemes and decide between regional customization or standardized global specifications.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing material selection windows for converters, forcing rapid qualification of recyclable multilayer films while food brands simultaneously demand higher oxygen barrier performance for extended shelf-life claims.
Growth Catalysts
- E-commerce fulfillment networks:Double zipper closures now dominate specifications for protein and prepared meal delivery, driven by leak-resistance requirements during last-mile transit across Germany and the Netherlands.
- REACH-compliant adhesive systems:Solvent-free laminating adhesives enable compliance with migration limits while maintaining seal strengths above 15 N per 15 mm width for pharmaceutical applications.
- Retort pouch conversion:Foil laminate structures withstand thermal processing above 121 degrees Celsius, opening specification upgrades in ready-to-eat segments previously served by rigid cans.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin contracts track naphtha and natural gas liquids, compressing margin pools for high-volume commodity pouch converters.
- Cleanroom capacity concentration:Pharmaceutical-grade zipper pouch supply clusters among converters with ISO 14644-certified production lines, creating bottleneck risk for emerging market entrants.
- Monomaterial performance ceiling:Current polyethylene-only structures fail to match aluminum foil barrier specifications for moisture-sensitive active pharmaceutical ingredients.
Strategic Opportunities
- Extended producer responsibility schemes:Germany's packaging licensing system creates preferential market access for converters with Design for Recycling certification from the Central Agency Packaging Register.
- Smart packaging integration:Printed electronics and time-temperature indicators converge with zipper pouch formats, enabling premium positioning in cold-chain pharmaceutical distribution.
- Specialty coffee micro-roasters:One-way degassing valve integration with resealable closures addresses freshness demands in direct-to-consumer subscription channels.
Industry Challenges
- Multilayer delamination expertise:Converters face acute shortages of process engineers capable of optimizing coextrusion die geometry for recyclable monomaterial structures.
- BRCGS certification timelines:Food safety audits require 6-12 month preparation cycles, delaying market entry for new production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zipper Pouch Market |
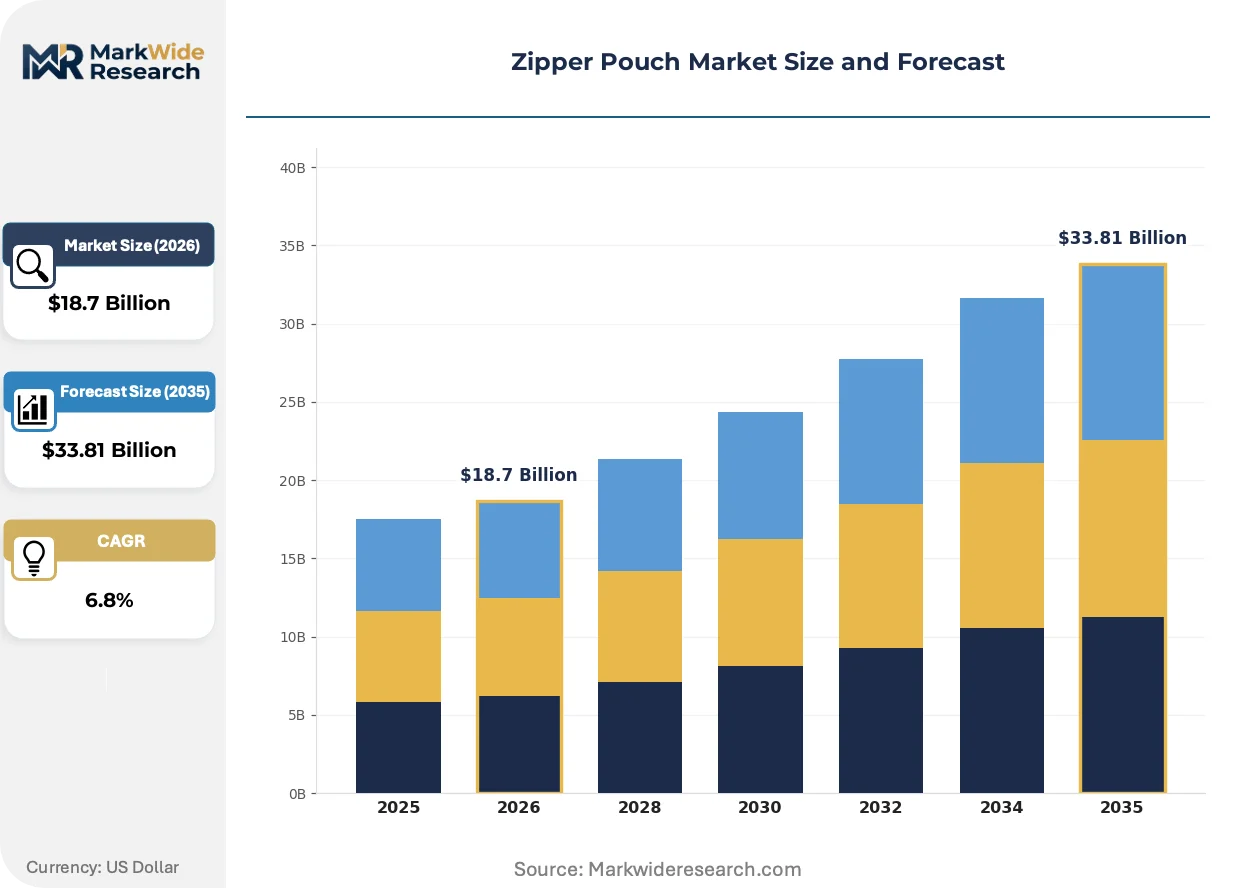
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Cloth, Ziplock, Foil Closure Type: Single Zipper, Double Zipper, Velcro, Heat Seal Size: Mini, Small, Medium, Large End User: Retail, Food Service, E-commerce, Hospitality |
| Companies Covered | Glenroy, Inc., ProAmpac LLC, Amcor plc, Constantia Flexibles Group GmbH, Sonoco Products Company, Berry Global Group, Inc., Sealed Air Corporation, Winpak Ltd., Mondi plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zipper Pouch Market Evolving Landscape
Active barrier technologies and regulatory compliance frameworks are restructuring competitive advantage in zipper pouch supply, separating converters with integrated film extrusion capabilities from those dependent on merchant substrate supply.
High-barrier ethylene vinyl alcohol copolymer grades are displacing conventional metallized polyester in premium snack and pet food applications. Brand owners in Germany and France specify these structures for 12-month shelf-life claims. The shift is compressing demand for legacy metallization capacity while rewarding converters with in-house multilayer extrusion lines.
The EU Packaging and Packaging Waste Regulation mandates recyclability targets that reshape material selection across export-bound production. Industrial consequence includes accelerated R&D spending on compatible adhesive systems and sealant layers. Pharmaceutical and retort segments face the steepest compliance curves due to incumbent foil laminate dependence.
Food service operators now specify recyclable and resealable formats through consolidated procurement frameworks. Direct contracting between private-label grocery chains and certified converters is replacing traditional distributor-mediated purchasing in Germany. This pattern concentrates specification authority among buyers with dedicated sustainability compliance teams.
Zipper Pouch Market Segmentation
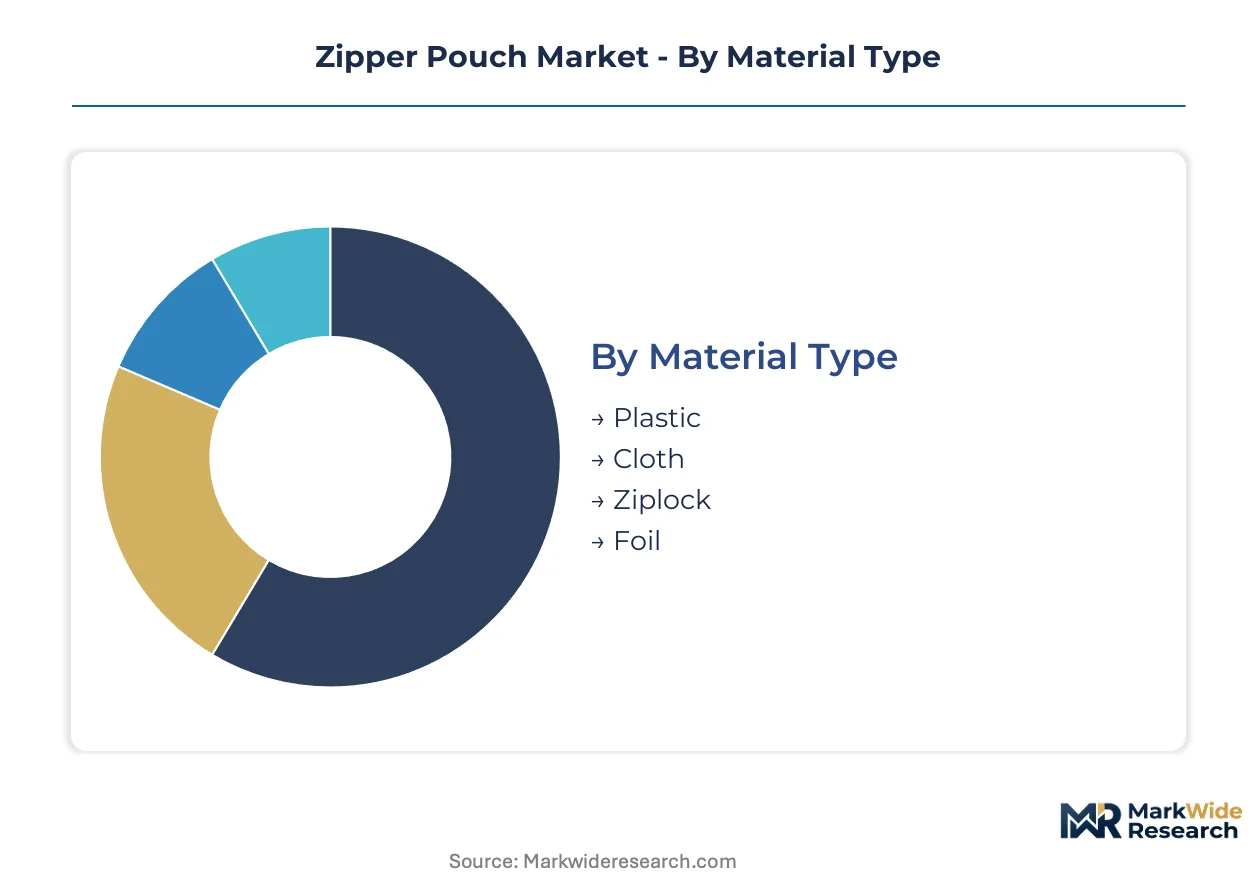
Zipper pouch specifications diverge sharply across material grades and closure mechanisms, with margin pools clustering in high-barrier pharmaceutical formats and double-zipper e-commerce configurations. Understanding segment boundaries enables converters to target qualification investments toward structurally advantaged pockets.
Material Type:
Margin pools concentrate in foil laminates for retort and pharmaceutical applications, while plastic substrates dominate volume throughput in commodity food packaging.
- Plastic:Polyethylene and polypropylene laminates enable high-speed form-fill-seal operations at seal strengths of 15–50 N per 15 mm width. German private-label grocery chains specify these structures for prepared meal delivery where cost efficiency outweighs extended barrier requirements.
- Foil:Aluminum foil laminates withstand thermal processing above 121 degrees Celsius, opening specification upgrades in ready-to-eat segments and active pharmaceutical ingredient packaging where moisture resistance is non-negotiable.
- Cloth:Woven synthetic substrates serve reusable promotional and organizational applications with lower barrier specifications but higher unit margins in specialty retail channels.
- Ziplock:Interlocking polyethylene tracks integrated into flexible sidewalls provide entry-level resealability for household storage and light-duty food applications.
Plastic holds installed capacity across high-volume converters. Foil is rotating up the share rankings as retort pouch conversion accelerates.
Closure Type:
Structural differentiation in closure mechanisms determines leak resistance during transit and directly influences e-commerce fulfillment network specifications.
- Double Zipper:Parallel interlocking tracks provide redundant seal integrity for protein and prepared meal delivery. E-commerce fulfillment networks across Germany and the Netherlands now mandate this format for last-mile leak resistance.
- Single Zipper:Single-track polyethylene closures dominate legacy food retail applications where cost minimization supersedes transit durability requirements.
- Velcro:Hook-and-loop fastening systems enable rapid access in medical kit and emergency supply applications where glove-handled opening is essential.
- Heat Seal:Permanent fusion closures serve single-use pharmaceutical and sterile medical device packaging where resealability is contraindicated.
Single zipper holds installed capacity in traditional retail. Double zipper is climbing the fastest as direct-to-consumer meal delivery scales.
Size:
Format dimensions correlate with end-use value density, with mini and small formats commanding disproportionate margins in pharmaceutical unit-dose applications.
- Mini:Sub-50 mL capacities package single-dose pharmaceuticals and cosmetic samples where precision dosing justifies premium positioning.
- Small:50–250 mL formats serve snack portions and travel-size personal care products with high turnover in convenience retail.
- Medium:250–1000 mL structures dominate standard retail food applications including frozen vegetables and dry pasta.
- Large:Above-1000 mL capacities address bulk food service and industrial ingredient storage with lower per-unit margins but stable volume contracts.
Medium holds installed capacity in mainstream retail. Mini is gaining share fastest as unit-dose pharmaceutical packaging expands.
End User:
Procurement authority is consolidating among food service operators and e-commerce platforms with dedicated sustainability compliance teams, displacing traditional distributor-mediated purchasing.
- Food Service:Commercial kitchens and catering operations specify recyclable and resealable formats through consolidated procurement frameworks with direct converter contracting.
- E-commerce:Fulfillment networks prioritize double-zipper leak resistance and lightweight cube efficiency for last-mile cost optimization.
- Retail:Brick-and-mortar grocery and mass merchandiser specifications lag e-commerce requirements but remain volume anchors for legacy single-zipper formats.
- Hospitality:Hotel and lodging amenity programs drive mini-format demand for single-use personal care and cosmetic sampling applications.
Retail holds installed capacity in legacy supply chains. Food service is rotating up the share rankings as procurement consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters with integrated film extrusion lines cluster in Germany, the United States, and China, each commanding distinct specification authority over export-bound production. Regulatory divergence between FDA migration limits and EU recyclability mandates forces parallel qualification tracks. Regional procurement consolidation accelerates as direct contracting replaces distributor-mediated purchasing.
Germany
Private-label grocery chains in Germany drive specification upgrades for extended shelf-life prepared meals, mandating recyclable multilayer structures. The Central Agency Packaging Register licenses Design for Recycling certification, creating preferential market access for compliant converters. Production concentrates in North Rhine-Westphalia, where film extrusion specialists supply barrier laminates for protein packaging applications.
United States
FDA regulation under 21 CFR 177 governs direct food-contact migration limits for polyethylene and polypropylene laminates used in high-speed form-fill-seal operations. The EPA tracks ethylene feedstock volatility through naphtha and natural gas liquids pricing indices. Flexible packaging converters cluster in the Midwest, particularly Illinois and Wisconsin, serving commodity food brands with seal strengths of 15–50 N per 15 mm width.
China
Domestic demand for retort pouch conversion accelerates as ready-to-eat segments shift from rigid cans to foil laminate structures exceeding 121 degrees Celsius thermal stability. GB standards and MIIT directives shape material compliance for export-bound production. Manufacturing gravity sits in the Yangtze River Delta, where converters supply pharmaceutical-grade pouches with cleanroom-certified production lines.
Netherlands
E-commerce fulfillment networks headquartered in the Netherlands mandate double zipper closures for last-mile leak resistance in protein and prepared meal delivery. ECHA REACH compliance shapes solvent-free laminating adhesive qualification for migration limit adherence. Rotterdam and Amsterdam anchor specification-setting procurement teams for pan-European distribution networks.
India
FSSAI food safety protocols and BIS standards govern flexible packaging material selection for domestic and export markets. The PLI scheme incentivizes domestic manufacturing capacity for specialty barrier films. Production concentrates in Maharashtra and Gujarat, where converters serve pharmaceutical and snack food segments with gravure and flexographic printing capabilities.
Zipper Pouch Market Competitive Landscape
Concentration sits with integrated film extrusion specialists capable of in-house multilayer structure production rather than merchant substrate-dependent converters. The vendor base stratifies across three tiers: global diversified packaging conglomerates with pharmaceutical cleanroom certification, regional flexible packaging specialists with gravure printing depth, and commodity pouch converters competing on high-speed throughput. Dominant competitive moves include capacity expansion in recyclable monomaterial structures and strategic partnerships with food brands for direct specification authority.
Within the integrated extrusion tier, ProAmpac LLC and Glenroy, Inc. exemplify converters with captive film production capabilities. Amcor plc anchors the pharmaceutical-grade segment with cleanroom-certified operations across multiple continents. Constantia Flexibles Group GmbH represents European-based specialists with gravure and flexographic depth for premium printed applications.
| Leading Market Players |
|---|
| Glenroy, Inc. |
| ProAmpac LLC |
| Amcor plc |
| Constantia Flexibles Group GmbH |
| Sonoco Products Company |
| Berry Global Group, Inc. |
| Sealed Air Corporation |
| Winpak Ltd. |
| Mondi plc |
| Others |
Value Network & Pricing Analysis
Recyclable monomaterial films displacing foil laminates in German private-label specifications are simultaneously redrawing supply geography toward North Rhine-Westphalia extrusion clusters and compressing pricing power for legacy metallization-dependent converters. This substitution dynamic concentrates procurement leverage among buyers with Design for Recycling certification while forcing margin reallocation across the value chain.
Pricing Analysis
The EU Packaging and Packaging Waste Regulation dictates the pricing tier structure across pharmaceutical, food service, and commodity segments. Three-tier pricing stratifies across premium certified, standard compliant, and economy non-certified levels, with ISO 14644 cleanroom certification and BRCGS food safety status as the primary differentiation drivers. Cost compression in commodity plastic laminates is intensifying because ethylene feedstock volatility tracks naphtha and natural gas liquids indices. Food service operators with consolidated procurement frameworks exhibit the lowest price sensitivity, while merchant substrate-dependent converters face the highest margin pressure.
Supply Chain Analysis
Inventory cycles for multilayer film substrates extend lead times for converters lacking captive extrusion capabilities. Supply concentrates in Germany, the United States, and China, with North Rhine-Westphalia, Illinois-Wisconsin, and the Yangtze River Delta anchoring production gravity. Raw material dependencies center on polyethylene resin, ethylene vinyl alcohol copolymer barrier grades, and solvent-free laminating adhesives. Single-source vulnerability sits with cleanroom-certified pharmaceutical-grade capacity. Distribution runs through direct contracting between private-label grocery chains and certified converters, displacing traditional distributor-mediated purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among food service operators and e-commerce platforms with dedicated sustainability compliance teams, fragmenting traditional distributor influence and forcing converters toward direct specification relationships.
For Market Incumbents: Shield margin pools by accelerating backward integration into multilayer extrusion capabilities and securing Design for Recycling certification from Germany's Central Agency Packaging Register before qualification windows narrow. The EU Packaging and Packaging Waste Regulation threatens merchant substrate-dependent converters with exclusion from preferential procurement frameworks. Priority investment centers on in-house ethylene vinyl alcohol copolymer film production and REACH-compliant adhesive formulation capacity. For New Entrants and Emerging Players: Differentiate on smart packaging integration capabilities, targeting pharmaceutical cold-chain distribution networks in the Netherlands and specialty coffee micro-roaster subscription channels in Germany. The most penetrable white space sits with printed electronics and time-temperature indicator convergence for unit-dose pharmaceutical applications. Go-to-market execution should leverage partnerships with fulfillment networks mandating double zipper specifications for last-mile leak resistance. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap converters with integrated film extrusion lines and existing BRCGS certification, positioned to capture specification upgrades as private-label grocery chains consolidate procurement. Long-term viability across the analysis window favors integrated specialists over merchant substrate-dependent players. The signal to watch is accelerated direct contracting between food service operators and certified converters, indicating tipping point consolidation in specification authority.| Strategic Initiative | Industry Significance |
|---|---|
| Recyclable Monomaterial Capacity Expansion | EU Packaging and Packaging Waste Regulation compliance secures preferential German market access. |
| Cleanroom Certification Investment | ISO 14644 certification unlocks pharmaceutical-grade zipper pouch supply with premium margin capture. |
| Smart Packaging Integration Partnership | Printed electronics convergence enables premium positioning in cold-chain pharmaceutical distribution. |
| Direct Procurement Relationship Development | Bypassing distributors captures specification authority from consolidating food service operators. |
| Solvent-Free Adhesive Formulation Scale-Up | REACH compliance maintains seal strength above pharmaceutical migration limits. |
Research Methodology
Operator-level perspectives from flexible packaging plant managers, procurement leads at German private-label grocery chains, film extrusion R&D directors, and pharmaceutical packaging quality assurance heads anchored the qualitative base. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, Central Agency Packaging Register certification databases, FDA 21 CFR 177 migration limit documentation, and REACH compliance declarations. Bottom-up capacity assessments across North Rhine-Westphalia, Illinois-Wisconsin, and Yangtze River Delta production clusters triangulated against top-down demand modeling from food service and e-commerce procurement data.
Sensitivity analysis tested forecast outputs against variable ethylene feedstock pricing, regulatory timeline acceleration, and cleanroom capacity expansion scenarios across the projection horizon. Segmentation dimensions modeled included material type, closure mechanism, format size, end-use application, and regional regulatory cluster. CAGRs were derived from multilayer film demand elasticity and retort pouch conversion rates. Industry-specific inputs encompassed Design for Recycling certification adoption curves and double zipper specification penetration in e-commerce fulfillment networks.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated monomaterial performance breakthroughs would require recalibration. Forecasts reflect documented assumptions regarding private-label procurement consolidation and pharmaceutical cleanroom capacity constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Box Pouch Market
Pouch
UAE Pouch Packaging Market
Pouch
Wrap-Around Packers Market
Pouch
South Africa Pouch Packaging Market
Pouch
Europe Retort Pouches Market
Pouch
MAP Flow Wrappers Market
Pouch
Retort Pouch Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Flexible Plastic Pouches Market
Pouch
Pillow Pouch Packaging Market
Pouch
Slider Zipper Pouch Market
Pouch
Aluminum Pouches Market
Pouch
Flexible Plastic Drinking Pouch Market
Pouch
Standcap Pouch Market
Pouch
Monodose Packs Market
Pouch
Rice Paper Stand Up Pouch Market