
 Doy Pouch Packaging Market | 2026-2036
Doy Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Doy Pouch Packaging Market Foresight
Modular portion packs and resealable multi-serve configurations is realigning how CPG buyers evaluate total cost of ownership against shelf impact. Amcor leverages its integrated film extrusion network to capture premium spout-pouch contracts in North American condiment lines. Mondi sustains competitive pressure through kraft-paper barrier hybrids that target European supermarket sustainability scorecards. Sealed Air differentiates via aseptic fitment technology that extends protein-rich ready-meal shelf life without refrigeration infrastructure.
Doy pouch packaging denotes a flexible format with gusseted bottom panels that self-stand when filled, typically constructed from laminated PET, PE, or aluminum oxide-coated films ranging from 80 to 150 microns in total caliper, engineered to replace rigid glass and metal containers across liquid, semi-viscous, and dry-fill applications. Stand-up pouches and spout pouches anchor current volume, with flat-bottom variants capturing bakery and confectionery shelf-space upgrades as retailers reduce secondary packaging. Plastic laminates still dominate material throughput, though paper-based composites are accelerating fastest where European EPR fees and French AGEC law penalties on non-recyclable formats reshape total cost equations.
FDA food-contact notification requirements, EU REACH restrictions on perfluorinated substances, and EFSA migration limits collectively force laminate suppliers to validate alternative barrier chemistries before commercial deployment. The EU Packaging and Packaging Waste Regulation, currently in final negotiation, will mandate minimum recycled content thresholds that directly alter substrate selection for pouches sold in France, Germany, and Italy. Stakeholders must monitor how rapidly mechanical recycling infrastructure for multilayer flexibles scales relative to chemical recycling commitments, as this gap determines which material platforms achieve viable circularity claims.
Market Dynamics
EU REACH restrictions on perfluorinated substances are forcing laminate suppliers to revalidate entire barrier chemistry portfolios before commercial deployment, compressing product development timelines and elevating technical qualification costs for converters serving European retail chains.
Growth Catalysts
- EPR fee differentials:French AGEC law penalties on non-recyclable formats are accelerating format switching from rigid containers to paper-based composites in supermarket private-label lines.
- Protein-rich ready-meal demand:Extended shelf-life requirements without refrigeration infrastructure are pulling aseptic fitment adoption across North American condiment and meal-kit segments.
- Retail shelf-space reconfiguration:Flat-bottom pouch variants are capturing bakery and confectionery upgrades as German retailers reduce secondary packaging layers.
Market Restraints
- Multilayer mechanical recycling gap:Infrastructure for sorting and reprocessing laminated PET/PE/AlOx films remains underdeveloped relative to chemical recycling commitments, trapping circularity claims in pilot-phase uncertainty.
- Aluminum oxide supply concentration:High-barrier coating capacity clusters among Asian specialty chemical suppliers, exposing converters to input cost volatility and extended lead times.
- Migration testing bottlenecks:EFSA notification queues for alternative adhesive systems are extending commercialization timelines by 12-18 months for reformulated laminates.
Strategic Opportunities
- Indian FSSAI compliance pathways:Domestic food-contact material standards are creating first-mover advantage for converters establishing local extrusion and lamination capacity ahead of import substitution mandates.
- Spout-pouch pharmaceutical liquids:Pediatric and geriatric dosing formats are opening high-margin contracts for child-resistant closure integration in OTC and prescription applications.
- EU Packaging and Packaging Waste Regulation thresholds:Pending recycled content mandates will reshape substrate selection for pouches sold in France, Germany, and Italy, favoring suppliers with mechanical recycling partnerships.
Industry Challenges
- Adhesive formulation talent scarcity:Migration-compliant low-VOC chemistries require polymer science expertise concentrated among legacy European and Japanese suppliers, constraining in-house R&D scaling.
- Legacy filling line retrofit costs:Transitioning from rigid container formats to flexible pouch geometries demands capital expenditure on form-fill-seal equipment with modified sealing jaw configurations and film tension control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Doy Pouch Packaging Market |
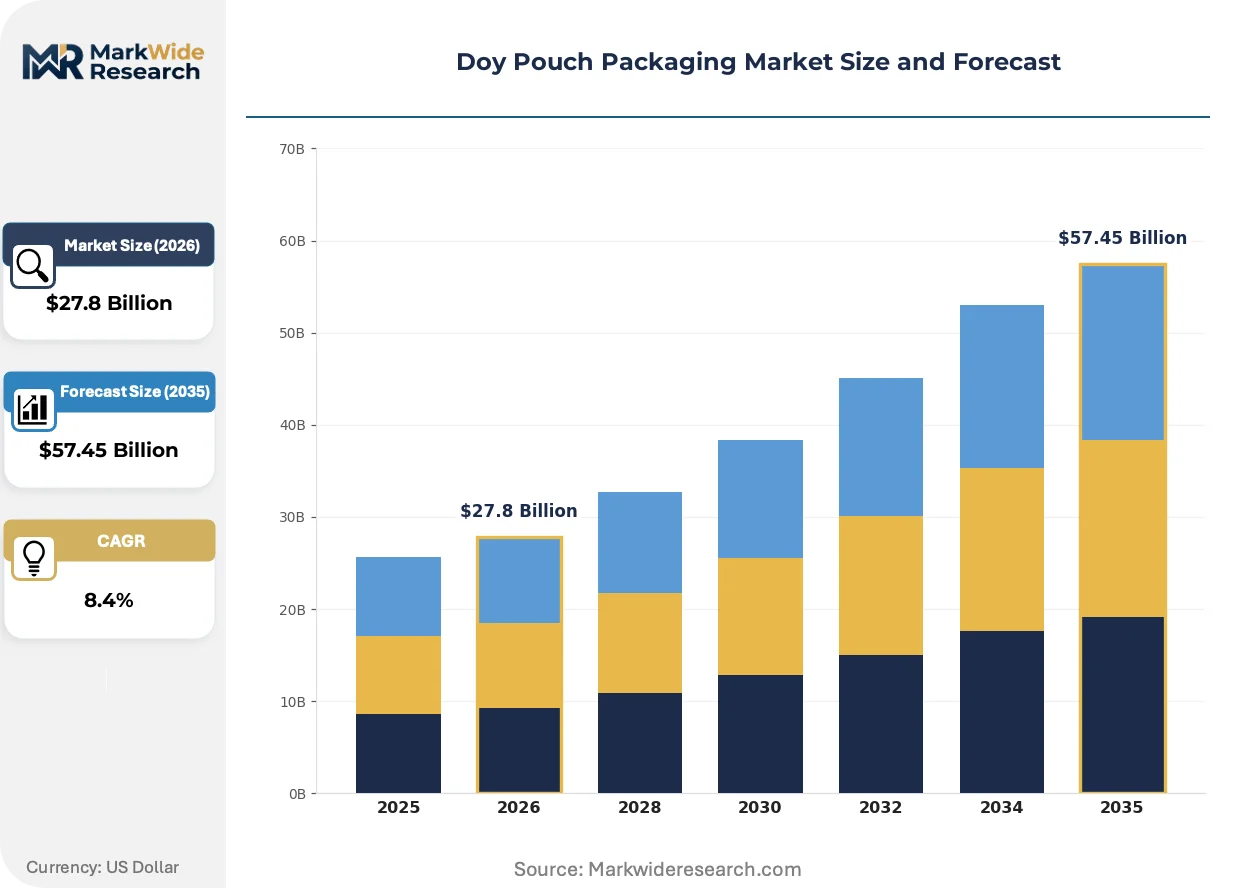
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $57.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up Pouches, Flat Bottom Pouches, Spout Pouches, Slider Pouches Material: Plastic, Paper, Aluminum, Composites Application: Food, Beverages, Pharmaceuticals, Personal Care Closure Type: Re-closable, Heat-sealed, Zip-lock, Tear Notch |
| Companies Covered | Amcor, Mondi, Sealed Air, Astar Packaging, Glenroy, LPS Industries, NNZ, TedPack Company, Rosenflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Doy Pouch Packaging Market Shifts & Advancements
Barrier material innovation and regulatory chemistry substitution are compressing traditional laminate architectures while opening premium positioning for validated sustainable alternatives.
Aluminum oxide-coated PET films are integrating into mid-barrier condiment and sauce applications as converters seek metal-free alternatives to foil laminates. North American private-label brands are qualifying these structures for 12-month shelf-life targets. The technology is integrating oxygen and moisture protection into mono-material-recyclable substrates that satisfy emerging EPR fee structures.
EU REACH Annex XVII restrictions on perfluorinated substances are prohibiting legacy grease-resistant chemistries in food-contact applications. Converters must validate silicone-oxide or bio-based barrier coatings before existing inventory depletion. European ready-to-eat meal and pet food segments are most affected, with German and Italian buyers accelerating supplier audits for PFAS-free certifications.
Resealable multi-serve configurations are displacing single-serve rigid cups in yogurt and dessert categories as household penetration of refrigeration-constrained consumers expands. Club and discount channels are prioritizing pouch formats that reduce cubic volume in reverse logistics. This shift concentrates in US and German markets where retailer sustainability scorecards weight packaging-to-product ratio metrics.
Doy Pouch Packaging Market Segmentation
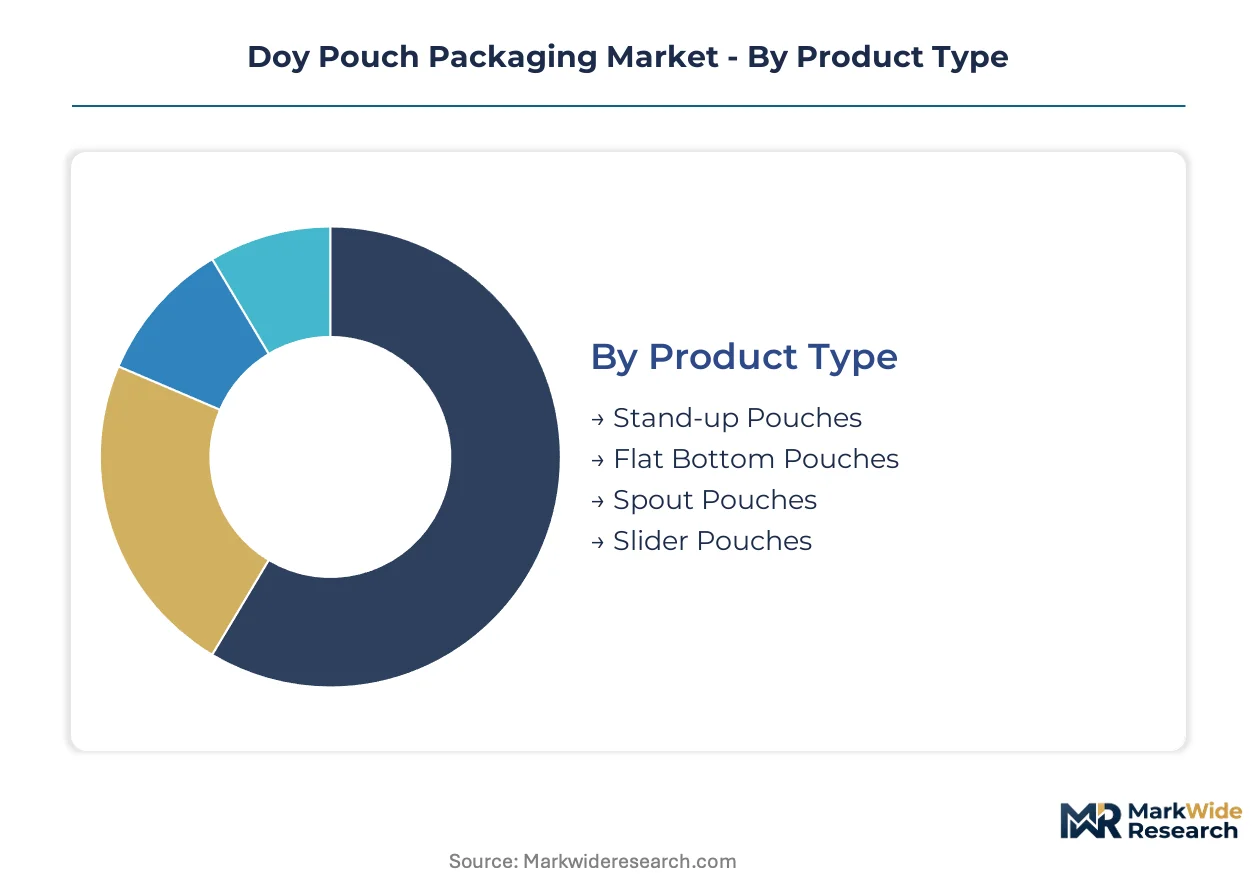
Converters and brand owners evaluate doy pouch specifications through divergent lenses—retail buyers prioritize shelf differentiation and EPR compliance, while operations teams weigh filling-line compatibility and total landed cost. Segment selection directly determines barrier performance, recyclability credentials, and speed-to-market in regulated environments.
Product Type:
Retail shelf-space economics and logistics density drive format selection, with gusset geometry and closure integration determining cubic efficiency and consumer utility.
- Stand-up Pouches:Self-supporting gusseted base constructed from laminated PET/PE or aluminum oxide-coated films ranging 80-150 microns. German supermarket private-label lines are converting condiment and ready-meal volumes from rigid glass as retailers reduce secondary packaging layers and AGEC law penalties bite.
- Spout Pouches:Integrated fitment designs enabling controlled dispensing for liquid and semi-viscous contents. North American condiment brands are capturing premium positioning through aseptic fitment technology that extends shelf life without refrigeration infrastructure.
- Flat Bottom Pouches:Quad-seal base geometry maximizing pallet density and retail facing area. Bakery and confectionery segments in France and Italy are adopting these for shelf-space upgrades.
- Slider Pouches:Track-based reclosure systems targeting multi-serve household formats. Club channel buyers in the US prioritize these for reduced cubic volume in reverse logistics.
Stand-up pouches lead on scale; spout pouches lead on momentum.
Material:
Substrate choice now hinges on circularity infrastructure maturity and EPR fee differentials rather than barrier performance alone.
- Plastic:Dominant throughput through multilayer PET/PE laminates with aluminum oxide or ethylene vinyl alcohol barrier layers. Mechanical recycling infrastructure gaps trap circularity claims in pilot-phase uncertainty across European markets.
- Paper:Kraft-paper barrier hybrids with silicone-oxide or bio-based coatings. French AGEC law penalties on non-recyclable formats are accelerating adoption in supermarket sustainability scorecards.
- Aluminum:Foil laminates for ultra-high barrier pharmaceutical and retort applications. REACH Annex XVII restrictions on perfluorinated substances are forcing chemistry revalidation.
- Composites:Engineered combinations targeting mono-material recyclability thresholds. Pending EU Packaging and Packaging Waste Regulation recycled content mandates favor suppliers with mechanical recycling partnerships.
Plastic laminates retain volume dominance; paper-based structures are climbing the fastest.
Application:
End-use sector dictates barrier specification, migration compliance tier, and closure complexity.
- Food:Largest addressable demand spanning condiments, ready-to-eat meals, and pet food. EFSA migration limits and FDA food-contact notifications force adhesive system validation timelines extending 12-18 months.
- Beverages:Liquid concentrates and adult nutrition formats requiring oxygen and light protection. Aseptic fitment adoption is expanding in meal-kit and protein-rich segments.
- Pharmaceuticals:Pediatric and geriatric dosing formats opening high-margin contracts for child-resistant closure integration in OTC applications.
- Personal Care:Cosmetics and household chemical pouches prioritizing dispensing precision and shelf aesthetics.
Food commands absolute volume; pharmaceuticals offer steepest margin expansion.
Closure Type:
Reseal functionality and opening experience determine repeat purchase rates and retail channel suitability.
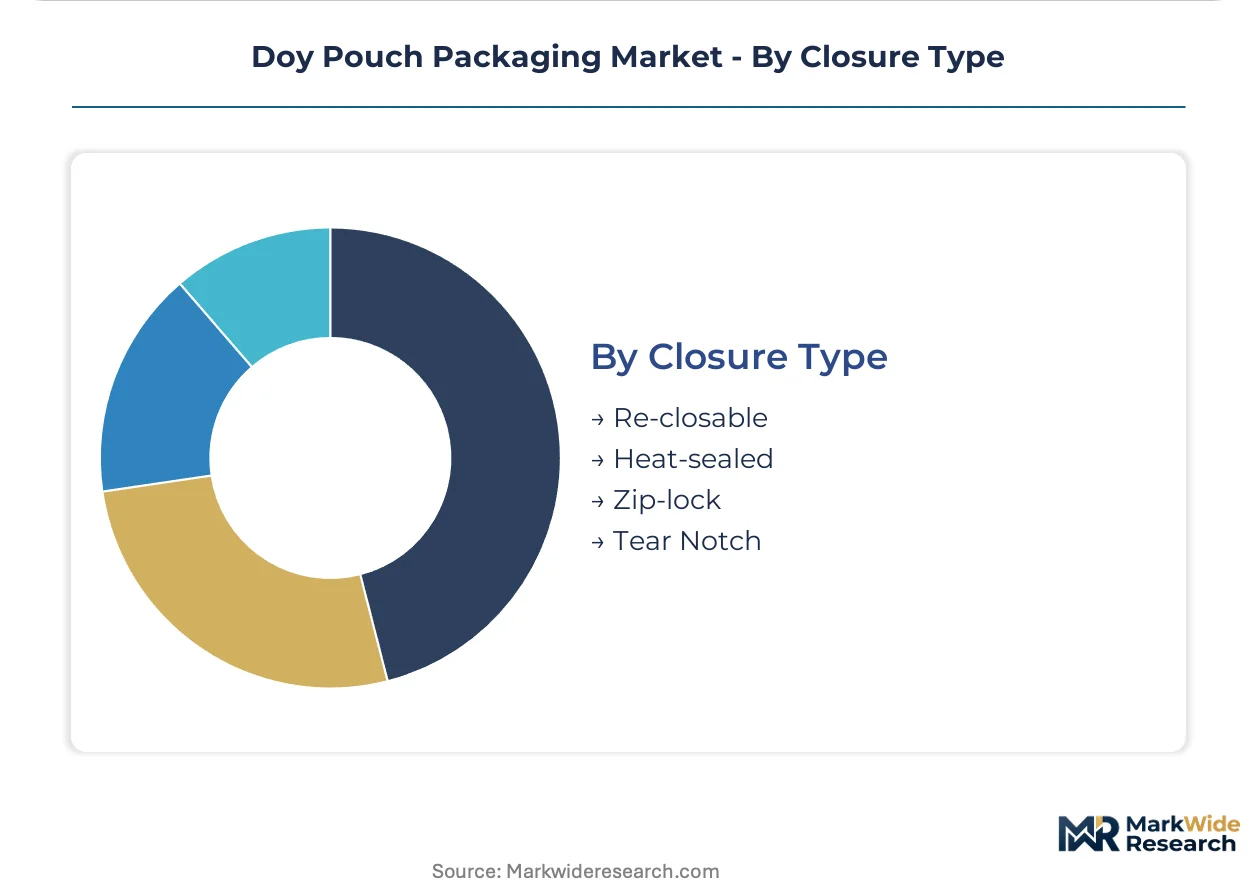
- Re-closable:Screw caps, flip-tops, and press-fit fitments for multi-serve convenience. Yogurt and dessert categories are displacing single-serve rigid cups as refrigeration-constrained household penetration expands.
- Heat-sealed:Permanent hermetic seals for aseptic and extended shelf-life applications. Protein-rich ready-meal demand is pulling adoption across North American condiment lines.
- Zip-lock:Interlocking track systems for dry goods and snack segments. German discount channels weight packaging-to-product ratio metrics heavily.
- Tear Notch:Controlled-opening features for single-serve portions and sampling formats. Lowest unit cost position supports emerging market penetration.
Heat-sealed closures anchor food safety compliance; re-closable systems gain share fastest in premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stand-up pouch technology originated in Japanese food packaging during the 1960s before migrating to European and North American markets through Swiss and German machinery exporters. The format's diffusion followed rigid-to-flexible conversion waves across industrialized economies. Today national regulatory frameworks and retail consolidation patterns determine adoption velocity.
United States
Club channel buyers at Costco and Sam's Club prioritize cubic efficiency in reverse logistics, pulling resealable multi-serve configurations into yogurt and dessert categories. FDA food-contact notification requirements for alternative adhesive systems extend commercialization timelines by 12-18 months. Chicago-area converters serve North American condiment brands qualifying aluminum oxide-coated PET films for 12-month shelf-life targets.
Germany
Supermarket private-label expansion at Aldi and Lidl accelerates format switching from rigid glass containers to stand-up pouches for condiments and ready-meals. EU REACH Annex XVII restrictions on perfluorinated substances force chemistry revalidation across barrier coating portfolios. The Rhine-Ruhr industrial corridor hosts laminate suppliers scaling mechanical recycling partnerships ahead of EU Packaging and Packaging Waste Regulation thresholds.
France
AGEC law penalties on non-recyclable formats reshape total cost equations for supermarket sustainability scorecards, accelerating paper-based composite adoption. EFSA migration limits for silicone-oxide barrier coatings create notification queues extending supplier qualification periods. Lyon-based converters target bakery and confectionery segments with flat-bottom pouch variants capturing shelf-space upgrades.
India
FSSAI compliance pathways for domestic food-contact material standards create first-mover advantage for converters establishing local extrusion capacity. Import substitution mandates in flexible packaging machinery pull joint venture formation with European equipment suppliers. Maharashtra's industrial belt around Mumbai and Pune concentrates new lamination capacity serving ready-to-eat meal brands.
Japan
Pediatric and geriatric dosing formats in pharmaceuticals open high-margin contracts for child-resistant closure integration. METI guidance on mono-material recyclability pushes converters toward simplified laminate architectures. The Kansai region around Osaka retains legacy expertise in adhesive formulation chemistry now concentrated among specialized suppliers.
Doy Pouch Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across barrier technology tiers and regulatory qualification depth. Integrated film extrusion networks command pricing power in spout-pouch contracts, while regional converters compete on speed-to-market for standard stand-up configurations. Three archetypes dominate: multinational material science conglomerates with captive resin supply, mid-tier specialists in aseptic fitment technology, and regional converters exploiting EPR fee arbitrage. Consolidation pressure concentrates in European markets where sustainability mandates raise capital requirements, while Asian markets fragment across machinery-technology licensing arrangements.
Among Switzerland-based and Australia-based packaging conglomerates, Amcor and Sealed Air exemplify scale-driven archetypes with integrated film networks spanning multiple continents. Mondi occupies a position within the European sustainability-focused tier, representing kraft-paper barrier hybrid specialists targeting supermarket scorecard compliance. These three anchors illustrate how geographic origin and corporate structure correlate with strategic positioning across premium and standard margin tiers.
| Leading Market Players |
|---|
| Amcor |
| Mondi |
| Sealed Air |
| Astar Packaging |
| Glenroy |
| LPS Industries |
| NNZ |
| TedPack Company |
| Rosenflex |
| Others |
Supply & Pricing Matrix
Aluminum oxide coating costs cascade from Asian specialty chemical suppliers through laminate converters to European retail chains, with REACH-compliant adhesive premiums widening spreads between qualified and unqualified substrate tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aseptic fitment-integrated pouches from standard stand-up configurations and commodity flat-bottom formats. Price differentiation hinges on EFSA migration certification status and volume scale, with German supermarket private-label buyers extracting maximum leverage on standard-tier contracts. Cost compression in economy laminates is intensifying because paper-based composite suppliers compete for AGEC law-compliant shelf space. Club channel buyers in the United States exhibit lowest price sensitivity due to cubic efficiency premiums in reverse logistics.
Supply Chain Analysis
EFSA and FDA food-contact notification queues gate supplier qualification timelines, stretching commercialization cycles for reformulated barrier chemistries. High-barrier coating capacity clusters in China, Japan, and South Korea, while laminate conversion concentrates in Germany, the United States, and India. Raw material dependencies span PET resin, ethylene vinyl alcohol, and silicone-oxide coatings. Single-source vulnerability in aluminum oxide feedstock exposes converters to input cost volatility. Distribution runs through integrated film extrusion networks serving multinational CPG accounts and regional converters supplying private-label chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The doy pouch packaging market functions as a geographic-arbitrage play where EPR fee differentials between France and India reshape total cost equations for converters establishing extrusion capacity ahead of regulatory divergence.
For Market Incumbents: Extend mechanical recycling partnerships in the Rhine-Ruhr corridor to secure EU Packaging and Packaging Waste Regulation compliance ahead of recycled content thresholds. Extend aseptic fitment R&D investment to defend margin position against emerging Asian equipment licensors. Aluminum oxide supply concentration and adhesive formulation talent scarcity threaten incumbent cost structures. For New Entrants and Emerging Players: Launch via FSSAI-compliant local extrusion capacity in Maharashtra to capture Indian ready-to-eat meal demand ahead of import substitution mandates. Target pharmaceutical spout-pouch contracts for pediatric dosing formats as the most penetrable white-space segment. Pursue joint venture structures with European machinery exporters to bypass legacy qualification bottlenecks. For Investors and Strategic Acquirers: Consolidation pressure builds where sustainability mandates raise capital requirements beyond regional converter capacity. Long-term viability favors converters with backward integration into film extrusion and validated PFAS-free barrier portfolios. Acquisition target archetype: mid-tier specialists with EFSA notification depth and supermarket scorecard relationships. Watch chemical recycling infrastructure scaling relative to mechanical recycling commitments as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive PET/PE supply secures margin control against resin price volatility. |
| PFAS-Free Barrier Certification | REACH Annex XVII compliance unlocks European retail chain qualification pipelines. |
| Aseptic Fitment Technology Licensing | Protein-rich ready-meal shelf-life extension commands premium positioning in North America. |
| Mechanical Recycling Partnership | EU Packaging and Packaging Waste Regulation readiness differentiates substrate selection. |
| Indian Joint Venture Formation | FSSAI compliance pathways capture domestic food-contact material substitution demand. |
Research Methodology
Multiple input streams — primary interviews with laminate converters and CPG procurement directors, secondary validation through EFSA notification databases and EU trade customs records, and supply-side capacity assessments — were reconciled to construct segment-level demand estimates. Conversations with machinery OEMs, adhesive formulators, and supermarket category buyers informed barrier technology adoption curves. Bottom-up volume builds triangulated against top-down macro packaging spend data.
Data-stream reconciliation anchored projections across product type, material substrate, closure integration, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate blending weighted by EPR fee exposure and retail format switching velocity. Forecast inputs incorporated mechanical recycling infrastructure buildout timelines and FSSAI compliance pathway maturation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU Packaging and Packaging Waste Regulation threshold revisions or aluminum oxide supply disruptions. Projections reflect assumptions on barrier coating chemistry substitution rates and private-label format switching momentum. A model refresh is warranted upon material change in chemical recycling commercialization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Slider Zipper Pouch Market
Pouch
Horizontal Premade Pouch Packing Machine Market
Pouch
Feed Pouches Market
Pouch
Pouch Dispensing Fitment Market
Pouch
United States Pouch Packaging Market
Pouch
Thailand Pouch Packaging Market
Pouch
Twin Pouch Packaging Market
Pouch
Russia Pouch Packaging Market
Pouch
Contour Pouches Market
Pouch
Pouch Equipment Market
Pouch
Pouches Market
Pouch
Italy Pouch Packaging Market
Pouch
Global Pouches Packaging Market
Pouch
Four Side Flat Pouch Market
Pouch
Latin America Pouch Packaging Market
Pouch
Germany Pouch Packaging Market