
 Child Resistant Pouches Market | 2026-2036
Child Resistant Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Child Resistant Pouches Market Outlook
Buyer concentration among cannabis product distributors is shifting as state-legal markets mature and multi-state operators consolidate procurement. Amcor leverages its global film supply network to serve pharmaceutical and cannabis clients with certified child-resistant structures. Berry Global sustains manufacturing scale across North American flexible packaging plants. Winpak anchors its position through specialized barrier films that meet dual requirements for product freshness and child safety.
Child resistant pouches are engineered flexible containers incorporating specialized closure mechanisms that require coordinated manual dexterity to open, typically constructed from multi-layer laminates combining polyethylene, polyester, and foil barriers to achieve moisture and oxygen resistance. These structures serve the essential commercial purpose of preventing access by children under five years while maintaining accessibility for adults, particularly for regulated substances including pharmaceuticals, cannabis, and nicotine products. Plastic laminates dominate current production volumes due to cost efficiency and heat-seal reliability, though biodegradable alternatives represent the fastest-growing material category as brand owners respond to extended producer responsibility frameworks. Press-to-close mechanisms lead in unit volume across pharmaceutical applications, while slider closures command premium positioning in cannabis packaging where resealability drives repeat purchase behavior.
The US Consumer Product Safety Commission enforces Poison Prevention Packaging Act compliance, while ASTM International maintains voluntary consensus standards for child-resistant packaging performance. The EU Packaging and Packaging Waste Regulation shapes material specifications for export-bound producers, and Health Canada sets parallel certification requirements for cannabis packaging entering that market. Stakeholders must monitor evolving state-level cannabis packaging mandates alongside federal pharmaceutical requirements to maintain compliant product portfolios.
Market Dynamics
Regulatory certification requirements under the US Poison Prevention Packaging Act and ASTM standards are tightening faster than manufacturing capacity can adapt, forcing converters to restructure production lines around dual-compliant formats.
Growth Catalysts
- State cannabis packaging mandates:California's comprehensive testing and child-resistance requirements for recreational cannabis products are driving volume commitments from multi-state operators seeking compliant supply chains.
- Slider closure technology:Resealable slider mechanisms are capturing preference in premium cannabis segments where repeat opening convenience supports brand loyalty and dosage control.
- Pharmaceutical compliance deadlines:FDA enforcement of unit-dose packaging for certain OTC categories is expanding the addressable market for certified child-resistant pouch formats.
Market Restraints
- Aluminum foil supply concentration:Barrier layer sourcing depends on a limited number of North American metallized film suppliers, creating input cost volatility during energy price spikes.
- Biodegradable performance gaps:Compostable seal layers currently fail ASTM F3159 torque testing at rates that disqualify them from pharmaceutical certification.
- California testing backlog:The state's Bureau of Cannabis Control approval queue extends lead times for new packaging formats entering the regulated supply chain.
Strategic Opportunities
- Health Canada cannabis expansion:Federal licensing of additional retail provinces creates demand for packaging that satisfies both US ASTM and Canadian CSA Z76.1 standards.
- Nicotine pouch transition:Oral tobacco product manufacturers are migrating from rigid cans to flexible child-resistant formats, opening a new end-use vertical with distinct barrier requirements.
- Extended producer responsibility frameworks:EU Packaging and Packaging Waste Regulation compliance is incentivizing mono-material recyclable structures that maintain child-resistance certification.
Industry Challenges
- Dual-certification engineering:Designing structures that simultaneously satisfy senior-friendly accessibility and child-resistant testing protocols extends R&D cycles and capitalizes specialized tooling.
- ASTM D3475 protocol updates:Revisions to senior adult panel testing requirements force reformulation of adhesive layers and closure geometries, invalidating prior certification investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Child Resistant Pouches Market |
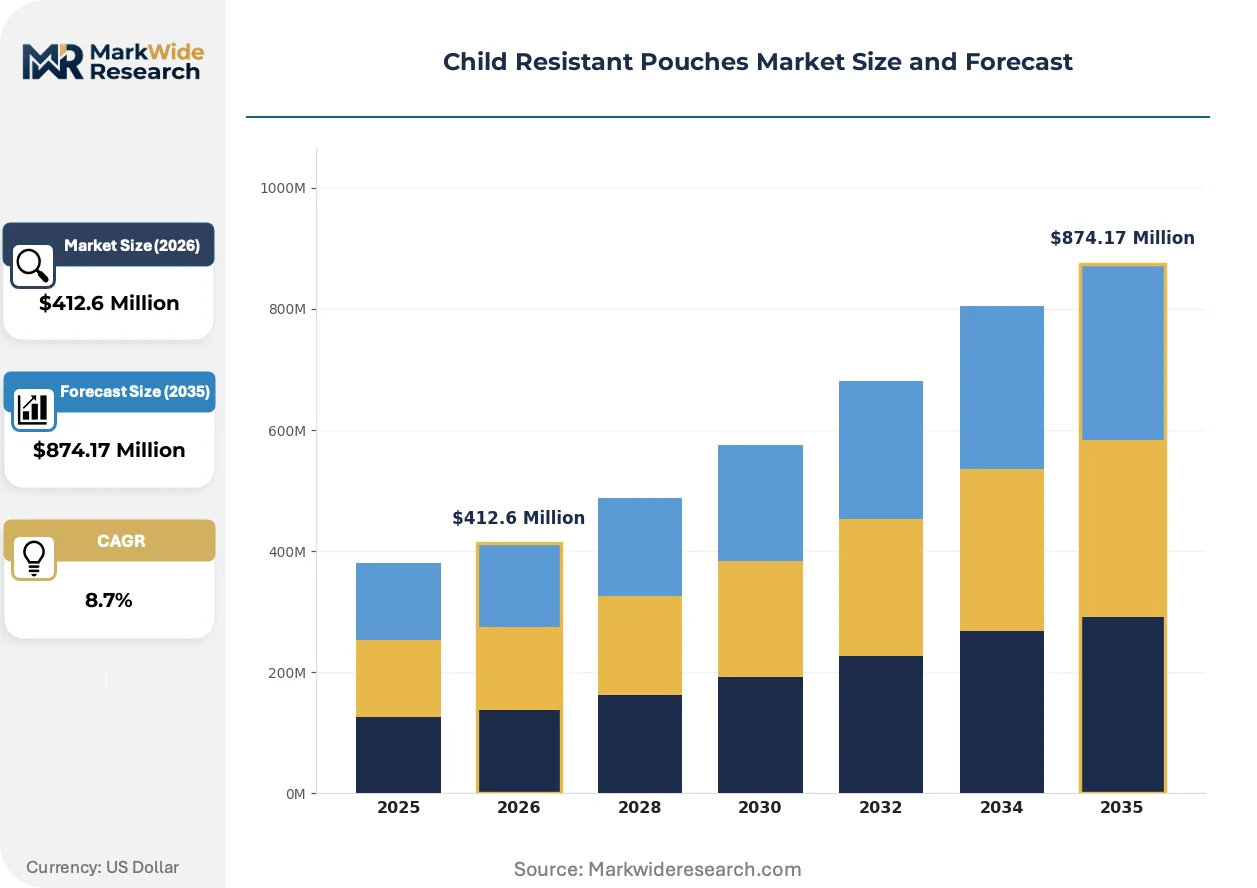
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Aluminum, Biodegradable Closure Mechanism: Press-to-Close, Zip Lock, Slider, Snap Fit End User: Pharmaceuticals, Food Industry, Alcoholic Beverages, Cannabis Products Size: Small, Medium, Large, Extra Large |
| Companies Covered | Amcor, Berry Global, Winpak, ABC Packaging, MST Packaging, IMPAK Corporation, Reynolds Consumer Products, ClearBags, Leader Flexible Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Child Resistant Pouches Market Strategic Shifts
Closure mechanism engineering and material science are converging to address the tension between regulatory compliance and user experience, with particular emphasis on formats that satisfy both child-resistance testing and aging-population accessibility standards.
Digital printing integration with short-run pouch converting is decentralizing production economics for cannabis brands. California craft cultivators and Colorado micro-businesses are adopting on-demand printed child-resistant formats at batch sizes below 10,000 units. This technology is decentralizing volume concentration away from large-format rotogravure contracts toward regional converter networks.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant barrier layers in cannabis edible packaging. The European Chemicals Agency's 2023 PFAS restriction proposal is accelerating migration to silicone-based and clay-modified polyethylene alternatives. German and Dutch converters are advancing pilot lines for PFAS-free structures ahead of anticipated enforcement timelines.
Multi-state operators are consolidating packaging specifications across state lines to capture procurement scale. Curaleaf and Green Thumb Industries have standardized on three pouch formats across twelve state markets, replacing the prior fragmented state-by-state sourcing model. This concentration is most visible in the Northeast corridor where interstate distribution infrastructure supports centralized inventory management.
Child Resistant Pouches Market Segmentation
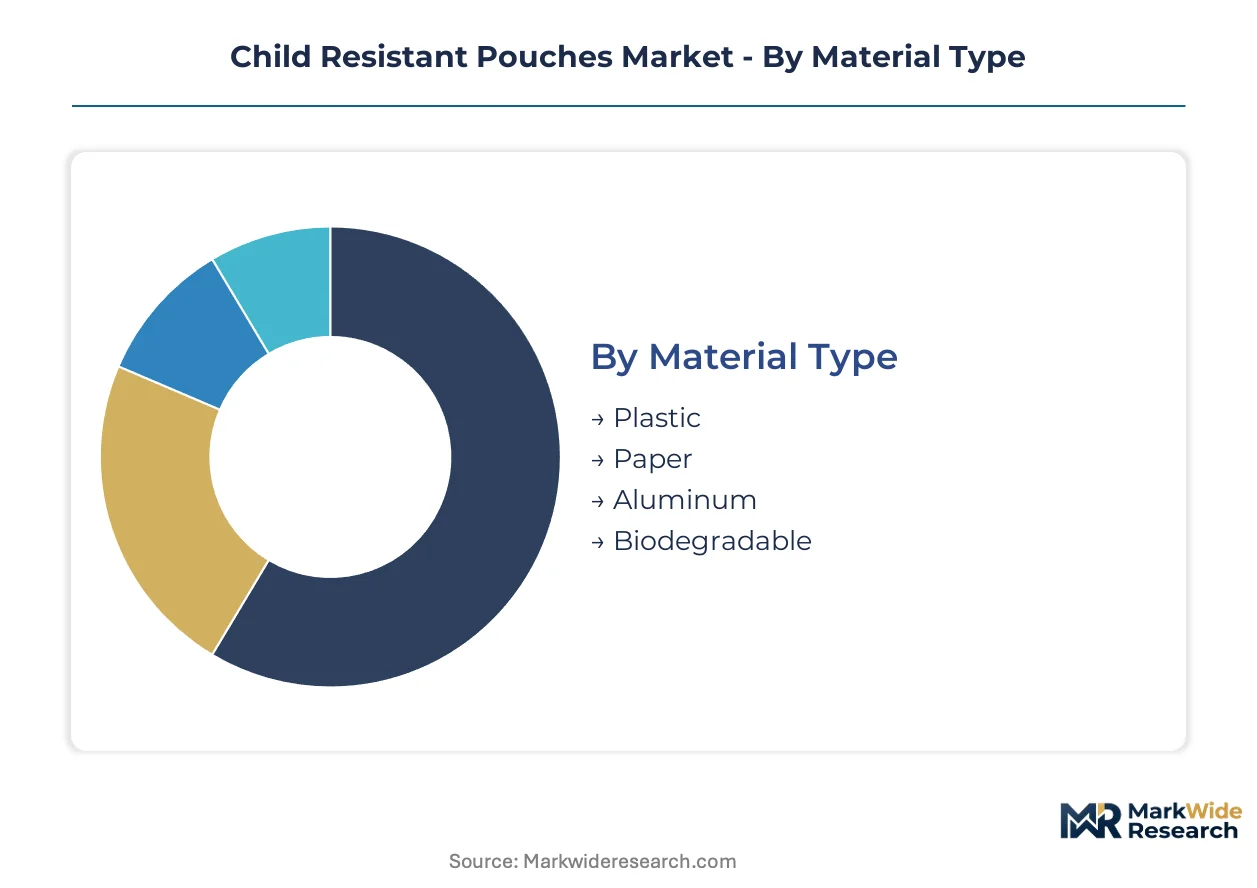
Material selection and closure engineering determine certification compliance and manufacturing economics across child-resistant pouch production. Segmentation reveals how technical specifications align with end-use regulatory requirements and volume procurement patterns.
Material Type:
Plastic laminates dominate unit volumes through cost efficiency, while biodegradable alternatives command development investment responding to extended producer responsibility mandates.
- Plastic:Multi-layer polyethylene and polyester structures provide heat-seal reliability and moisture barrier performance at scale. Pharmaceutical distributors in the United States specify plastic laminates for OTC unit-dose formats under FDA compliance timelines.
- Biodegradable:Compostable seal layers and plant-derived films address EU Packaging and Packaging Waste Regulation requirements. California cannabis brands are piloting biodegradable structures ahead of anticipated state mandates, though ASTM F3159 torque testing failures currently limit pharmaceutical certification.
- Paper:Fiber-based substrates with polymer coatings serve nicotine pouch transitions seeking rigid-to-flexible format migration.
- Aluminum:Metallized foil barriers deliver oxygen and light protection for premium cannabis edibles requiring extended shelf stability.
Mature deployment sits with Plastic. Newer deployment is concentrated in Biodegradable.
Closure Mechanism:
Press-to-close mechanisms anchor pharmaceutical volumes through proven ASTM compliance, while slider closures capture premium positioning where resealability drives repeat purchase behavior.
- Press-to-Close:Dual-squeeze or push-and-turn geometries require coordinated finger pressure that children under five cannot replicate. The US Consumer Product Safety Commission recognizes press-to-close formats across the widest range of pharmaceutical applications.
- Slider:Track-based resealable mechanisms support dosage control and brand loyalty in cannabis segments. Multi-state operators in California and Colorado specify slider closures for premium flower and concentrate packaging.
- Zip Lock:Interlocking channel designs balance accessibility with child-resistance for food industry applications requiring frequent opening cycles.
- Snap Fit:Rigid tab-and-slot configurations serve alcoholic beverage samples and single-serve formats where tamper evidence complements child safety.
Volume concentration favors Press-to-Close. Margin expansion concentrates in Slider.
End User:
Pharmaceutical compliance deadlines and state cannabis mandates are reshaping demand concentration across end-use verticals.
- Pharmaceuticals:Unit-dose packaging requirements for certain OTC categories expand addressable demand. FDA enforcement actions are driving converters to restructure production lines around dual-compliant formats.
- Cannabis Products:California's Bureau of Cannabis Control testing requirements and similar state mandates create procurement scale for certified suppliers. Multi-state operators are consolidating specifications across twelve state markets to capture volume concentration.
- Food Industry:Cannabis edible packaging requirements extend child-resistance mandates to confectionery and baked goods segments.
- Alcoholic Beverages:Single-serve and sample formats adopt child-resistant structures for retail compliance in regulated distribution channels.
Regulatory pressure is most acute in Pharmaceuticals. Procurement consolidation is advancing fastest in Cannabis Products.
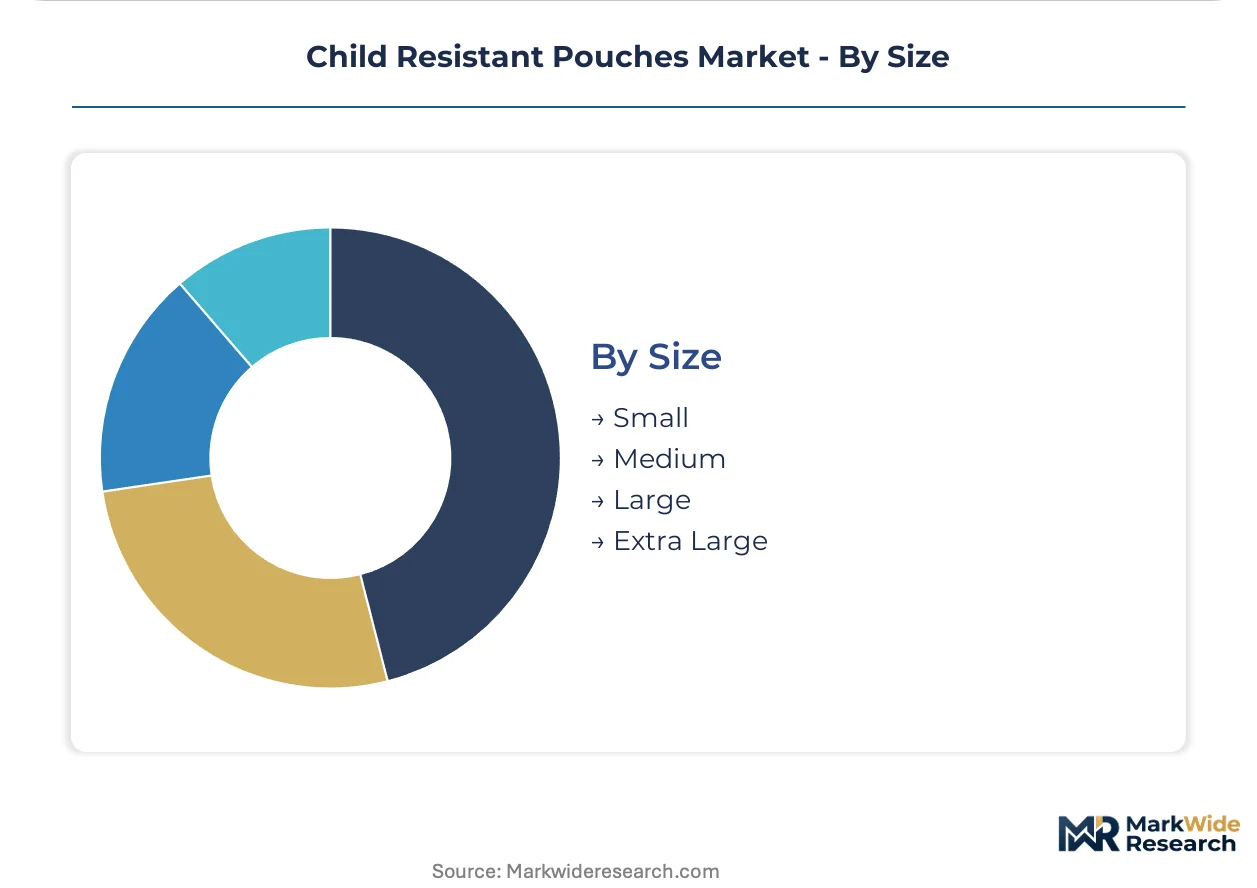
Size:
Format dimensions correlate with end-use dosing patterns and retail display requirements.
- Small:Single-unit and sample formats serve pharmaceutical trial programs and cannabis concentrate micro-dosing.
- Medium:Standard retail quantities dominate current production volumes across pharmaceutical and cannabis segments.
- Large:Bulk formats support medical cannabis patient supply and institutional pharmaceutical dispensing.
- Extra Large:Multi-unit configurations serve licensed cannabis cultivators and pharmaceutical mail-order distribution.
Production scale centers on Medium. Customization demand is expanding in Small.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyethylene resin production clusters along the US Gulf Coast anchor raw material flows for North American flexible packaging converters serving pharmaceutical and cannabis compliance markets.
United States
California's Bureau of Cannabis Control mandates ASTM-certified child-resistant packaging for all recreational products, driving procurement from Los Angeles and Sacramento distribution hubs. The US Consumer Product Safety Commission enforces Poison Prevention Packaging Act compliance for OTC pharmaceuticals, with FDA unit-dose deadlines expanding converter order books. Multi-state operators in Colorado and Oregon are consolidating specifications to capture volume discounts across state lines.
Canada
Federal cannabis licensing in Ontario and British Columbia creates dual-standard demand for packaging meeting both Health Canada requirements and US ASTM protocols. The country's national pharmaceutical regulator maintains CSA Z76.1 certification parallel to US standards, enabling cross-border supplier qualification. Toronto-area converters are expanding capacity to serve provincial retail monopolies in Quebec and Alberta.
Germany
REACH restrictions on PFAS grease-resistant barriers are forcing reformulation of cannabis edible packaging for export-bound producers. The European Chemicals Agency's restriction proposal accelerates migration to silicone-based alternatives at converter pilot lines in North Rhine-Westphalia. Düsseldorf and Hamburg packaging clusters are advancing PFAS-free structures ahead of anticipated enforcement timelines.
Netherlands
Amsterdam and Rotterdam serve as distribution gateways for EU cannabis packaging compliant with the Packaging and Packaging Waste Regulation. Dutch converters specialize in mono-material recyclable structures that maintain child-resistance certification under extended producer responsibility frameworks. Eindhoven's materials science cluster supports barrier film development for pharmaceutical export markets.
Australia
The Therapeutic Goods Administration enforces child-resistant packaging for nicotine replacement therapies and certain pharmaceuticals, creating demand from Sydney and Melbourne contract manufacturers. State-level cannabis decriminalization in Victoria and New South Wales is expanding addressable markets for certified pouch formats. Brisbane converters are positioning for Asia-Pacific export opportunities as regional regulatory harmonization advances.
Child Resistant Pouches Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biodegradable certification and digital printing integration to capture craft cannabis segments. The market structures around three tiers: multinational film suppliers with global certification networks, regional converters with state-level cannabis compliance expertise, and specialized shops focused on short-run digital production. Strategic moves concentrate on dual-certification engineering capabilities and mono-material recyclable structure development.
Among North American flexible packaging specialists, Amcor, Berry Global, and Winpak exemplify distinct competitive archetypes. Amcor leverages its global film supply network across multiple compliance jurisdictions. Berry Global sustains manufacturing scale through distributed North American plant networks. Winpak anchors positioning through specialized barrier film expertise. These three represent the concentration of certified production capacity serving pharmaceutical and cannabis end-use verticals.
| Leading Market Players |
|---|
| Amcor |
| Berry Global |
| Winpak |
| ABC Packaging |
| MST Packaging |
| IMPAK Corporation |
| Reynolds Consumer Products |
| ClearBags |
| Leader Flexible Packaging |
| Others |
Value Chain & Pricing Dynamics
Multi-state cannabis operators consolidating procurement across twelve state markets anchor pricing power in contract-based volume commitments, shifting converters toward long-term offtake structures that penalize spot-market flexibility.
Pricing Analysis
Volume concentration in plastic laminates runs through per-unit transactional pricing, while slider-closure premium tiers command margin expansion through certification-grade differentiation. Price differentiation separates ASTM-certified pharmaceutical formats from state-cannabis compliant alternatives, with California's Bureau of Cannabis Control testing requirements adding compliance cost premiums. Pricing pressure stems from aluminum foil supply concentration among limited North American metallized film suppliers. Craft cannabis cultivators below ten-thousand-unit batch sizes exhibit highest price sensitivity, while pharmaceutical distributors show lowest sensitivity due to FDA enforcement timelines.
Supply Chain Analysis
Certification gating under the US Poison Prevention Packaging Act and ASTM D3475 protocols concentrates qualified supply among converters with dual-jurisdiction testing capabilities. Manufacturing gravity centers on the United States, Canada, and Germany, with polyethylene resin production clusters along the US Gulf Coast feeding North American flexible packaging networks. Raw material dependencies rest on metallized foil barriers, multi-layer adhesive formulations, and specialized closure track mechanisms. Single-source vulnerability in aluminum foil supply creates input cost volatility during energy price spikes. Distribution feeds from regional converter networks toward Los Angeles and Sacramento distribution hubs serving California's regulated cannabis supply chain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where the US Poison Prevention Packaging Act erects a barrier-to-entry moat that rewards certified incumbents with pricing power over uncertified competitors.
For Market Incumbents: To counter biodegradable material failures in ASTM F3159 torque testing, deepen captive supply of certified seal-layer formulations and expand Health Canada dual-standard qualification capacity in Toronto-area plants. Secure long-term metallized film offtake agreements with Gulf Coast resin suppliers to insulate margin structures from aluminum foil volatility. For New Entrants and Emerging Players: Launch via digital-printing-integrated short-run converting to capture California craft cultivators and Colorado micro-businesses below ten-thousand-unit minimums. Target biodegradable certification gaps in EU-bound cannabis edible packaging as the most penetrable white space, with silicone-based barrier pilot lines as the entry mechanism. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional converters with state-level cannabis compliance expertise in Ontario and British Columbia during federal licensing expansion phases. Five-to-ten-year viability hinges on mono-material recyclable structure development ahead of EU Packaging and Packaging Waste Regulation enforcement. Watch California testing backlog resolution as the signal for capacity absorption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Engineering Investment | ASTM and CSA Z76.1 qualification unlocks cross-border supply to Health Canada-licensed provincial retailers. |
| Mono-Material Recyclable Structure Development | EU Packaging and Packaging Waste Regulation compliance positions converters for extended producer responsibility frameworks. |
| Digital Printing Integration | Short-run pouch converting captures craft cannabis segments below rotogravure minimum order thresholds. |
| PFAS-Free Barrier Reformulation | REACH restrictions on per- and polyfluoroalkyl substances force silicone-based alternatives at German pilot lines. |
| Slider Closure Technology Scale-Up | Resealable mechanisms support dosage control and repeat purchase behavior in premium cannabis segments. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews of packaging procurement managers at multi-state cannabis operators, regulatory compliance officers at flexible packaging converters, pharmaceutical supply chain directors, and ASTM certification testing laboratory personnel. FDA enforcement action records, Health Canada licensing databases, California Bureau of Cannabis Control approval queues, and EU REACH restriction proposals supplied validation benchmarks. Bottom-up volume estimates from state-level cannabis packaging mandates reconciled with top-down market sizing across material type, closure mechanism, and end-use verticals.
Data-stream reconciliation across production volume surveys, import-export trade flows, and certification database tracking informed the analytical framework. Segmentation modeling incorporated material type, closure mechanism, end-use vertical, format size, and regional regulatory cluster dimensions across the analysis window. CAGRs derived from trend extrapolation of state cannabis market maturation curves and pharmaceutical compliance deadline phasing, with sensitivity testing around aluminum foil price volatility and biodegradable material performance gaps.
Regulatory timeline acceleration, raw material supply disruption, and certification protocol revision are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding state cannabis packaging mandate adoption rates and ASTM standard update schedules. A model refresh is warranted upon material change in California testing backlog duration or EU PFAS restriction enforcement timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Pouch Equipment Market
Pouch
North America Stand-Up Pouch Packaging Market
Pouch
Child Resistant Single Dose Pouches Market
Pouch
Squeeze Pouch Market
Pouch
UAE Pouch Packaging Market
Pouch
Colombia Pouch Packaging Market
Pouch
Aluminum Pouches Market
Pouch
France Pouch Packaging Market
Pouch
Spain Pouch Packaging Market
Pouch
Liquid Pouch Market
Pouch
Asia-Pacific Retort Pouch Market
Pouch
Rice Paper Stand Up Pouch Market
Pouch
Box Pouch Market
Pouch
High-Barrier Pouches Market
Pouch
Feminine Care Pouch Film Market
Pouch
Self-Seal Pouches Market