
 China Pouch Packaging Market | 2026-2036
China Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
China Pouch Packaging Market Insights
Aftermarket service revenue from pouch printing and customization is reshaping margin pools away from commodity film extrusion toward value-added decoration. Cangzhou Hualiang Packaging Decoration Co., Ltd leverages its integrated gravure printing lines to dominate decorative pouch supply for regional food brands. TedPack Company Limited anchors its position through specialized spout-insertion equipment that sustains technical differentiation against generic converters. Guangdong Danqing Printing Co., Ltd competes on flexible packaging breadth, extending its reach from cosmetics into pharmaceutical-grade barrier pouches.
China pouch packaging denotes flexible containers fabricated from multi-layer films, foils, or paper laminates, typically sealed by heat or mechanical closure to preserve contents against moisture, oxygen, and light intrusion. These structures serve primarily to extend shelf stability while reducing material weight versus rigid alternatives across food, pharmaceutical, and personal care supply chains. Plastic material types occupy the largest volume share given cost efficiency, though aluminum composites command premium margins in retort and aseptic applications. Stand-up design styles lead consumer-facing segments for shelf presence, while flat and side-gusseted formats dominate institutional and bulk pharmaceutical packaging where pallet density governs logistics economics.
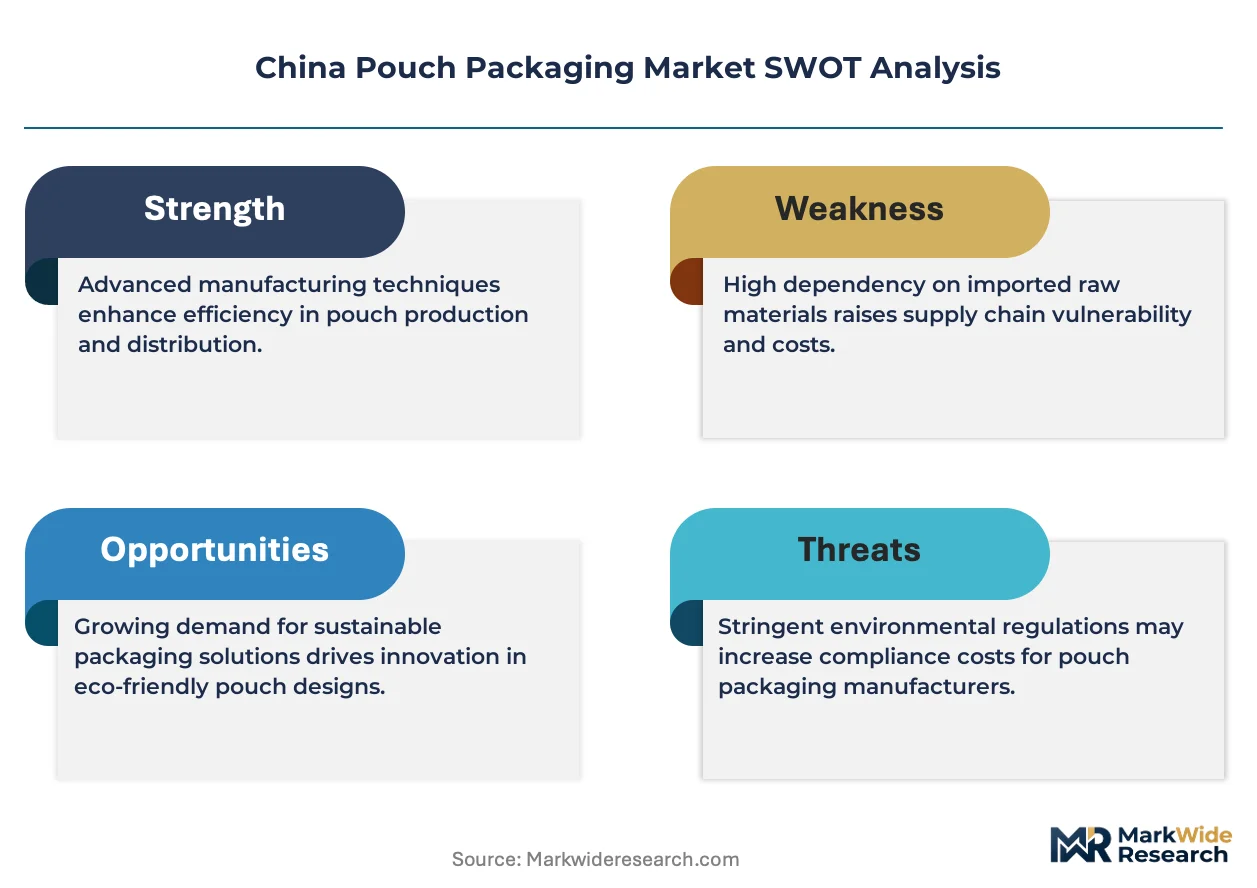
China's SAMR enforces GB standards for food-contact plastics that dictate migration limits and additive approvals, directly constraining material selection for domestic pouch converters. The NMPA imposes pharmaceutical packaging registration rules that create barrier-to-entry dynamics for drug-contact flexible containers, favoring certified manufacturers like Shanghai Dura-Pack Packaging Co., Ltd. The MIIT's dual carbon goals are pressuring energy-intensive lamination and printing processes toward solvent recovery and water-based ink transitions. Stakeholders must monitor evolving provincial emissions enforcement and green packaging mandates to calibrate capital allocation between conventional and sustainable film platforms.
Market Dynamics
China's pouch packaging sector is contending with a structural pivot from commodity film supply toward value-added decoration services, as food and pharmaceutical brands demand shorter print runs and faster turnaround times. The Yangtze River Delta manufacturing cluster concentrates both production capacity and regulatory scrutiny, amplifying competitive pressure on converters lacking integrated gravure or digital printing capabilities.
Growth Catalysts
- GB Standards Compliance:SAMR enforcement of migration limits and additive approvals for food-contact plastics is elevating certified converters above uncertified competitors, creating tiered supply access.
- Ready-to-Eat Meal Expansion:Food and beverage brands in Shanghai, Jiangsu, and Zhejiang are adopting stand-up pouches for single-serve meals, pulling demand from rigid tray formats.
- Spout-Insertion Automation:Specialized equipment for fitment welding is enabling technical differentiation in liquid and semi-liquid packaging applications.
Market Restraints
- Petrochemical Input Volatility:Polypropylene and polyethylene resin prices fluctuate with crude oil benchmarks, compressing margins for non-integrated converters.
- Pharmaceutical Certification Barriers:NMPA registration requirements for drug-contact flexible containers create multi-year approval timelines that freeze out new entrants.
- Aluminum Foil Supply Concentration:Domestic foil rolling capacity clusters in Henan and Shandong provinces, exposing eastern converters to logistics cost spikes.
Strategic Opportunities
- Western Province Penetration:Sichuan and Chongqing food processors remain underserved by high-barrier pouch suppliers, offering first-mover positioning for certified converters.
- Water-Based Ink Transition:MIIT dual carbon goals are accelerating solvent recovery mandates, rewarding early adopters with provincial emissions credit advantages.
- Pharmaceutical-Grade Barrier Extension:Cosmetics pouch specialists are repurposing metallized film expertise to capture NMPA-registered drug packaging contracts.
Industry Challenges
- Gravure Cylinder Lead Times:Custom engraving cycles stretch 4-6 weeks, forcing converters to absorb working capital strain for short-run orders.
- Legacy Lamination Equipment Retrofit Costs:Solvent-based adhesive lines require substantial capex for water-based or solventless conversion to meet MEE emissions enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Pouch Packaging Market |
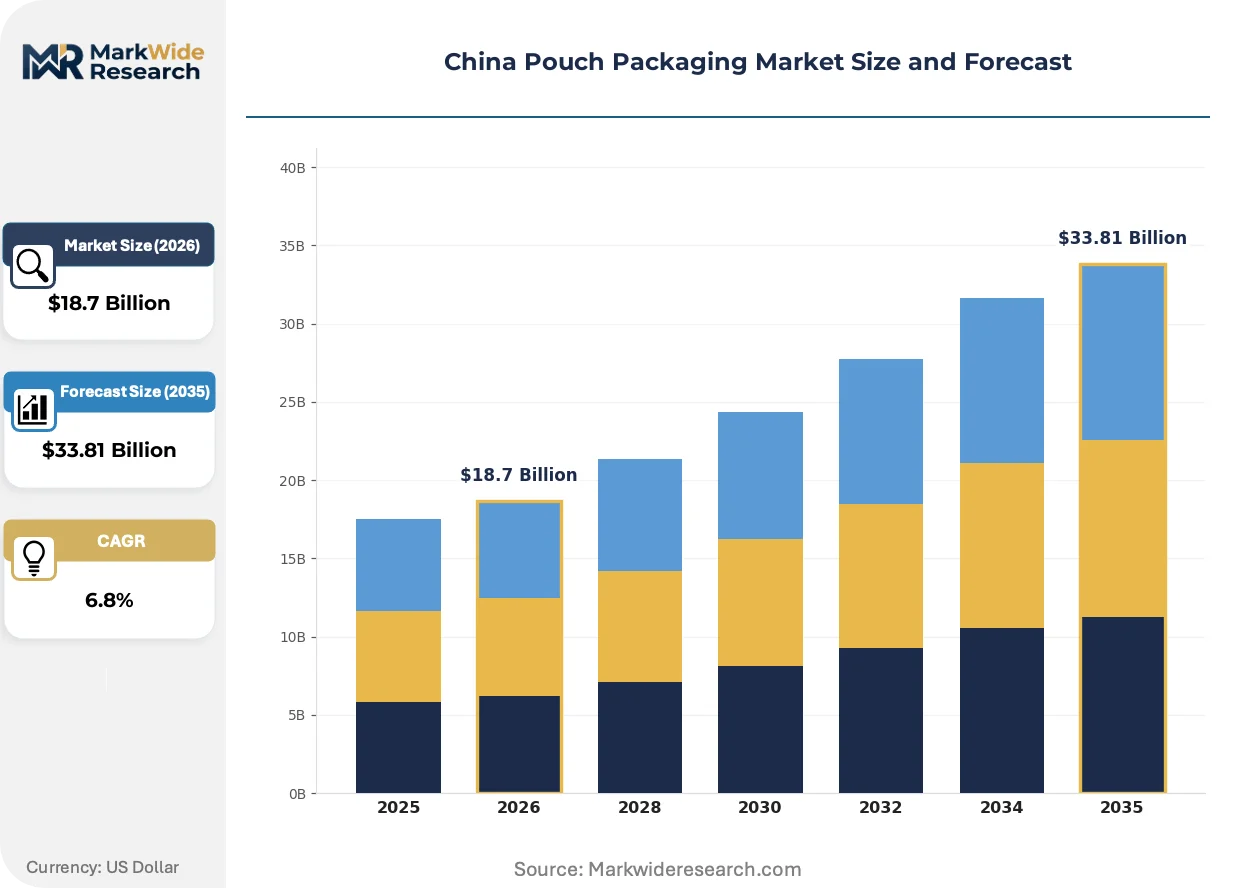
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Aluminum, Paper, Composites Closure Type: Zipper, Spout, Resealable, Heat Seal Application: Food & Beverage, Personal Care, Pharmaceuticals, Pet Food Design Style: Stand-Up, Flat, Side Gusseted, Pillow |
| Companies Covered | Cangzhou Hualiang Packaging Decoration Co., Ltd, TedPack Company Limited, OK Packaging Manufacturing Co. Ltd, Wenzhou Co-pack Co. Ltd, Dongguan Pasike Packaging Co. Ltd, Hangzhou Qinghong Packaging Co. Ltd, Guangdong Danqing Printing Co. Ltd, Shanghai Dura-Pack Packaging Co. Ltd, Rinpac, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Pouch Packaging Market Trends and Innovations
Digital printing and sustainable material transitions are compressing traditional gravure-dominated production models while regulatory enforcement accelerates technology substitution. The sector is witnessing convergence between decoration capabilities and barrier performance requirements.
Single-pass inkjet printing systems are digitizing short-run pouch production for regional food brands and promotional campaigns. Shanghai-based converters are adopting these lines to reduce cylinder costs and enable versioning for e-commerce private labels. The technology is digitizing order economics by collapsing minimum viable run sizes from fifty thousand units toward five thousand.
MEE provincial enforcement of volatile organic compound limits is forcing solvent recovery investments or water-based ink transitions across Jiangsu and Zhejiang printing clusters. Lamination houses face equipment retrofit decisions with eighteen-month payback horizons. Pharmaceutical pouch converters are responding fastest, prioritizing NMPA registration continuity over near-term capital preservation.
Direct-to-manufacturer procurement is consolidating previously fragmented distributor channels for standard barrier films. Large food processors in the Yangtze Delta are establishing approved vendor lists with technical audit requirements, displacing spot-market purchasing. This pattern is most pronounced in retort pouch supply for ready-meal processors seeking batch traceability compliance.
China Pouch Packaging Market Segmentation
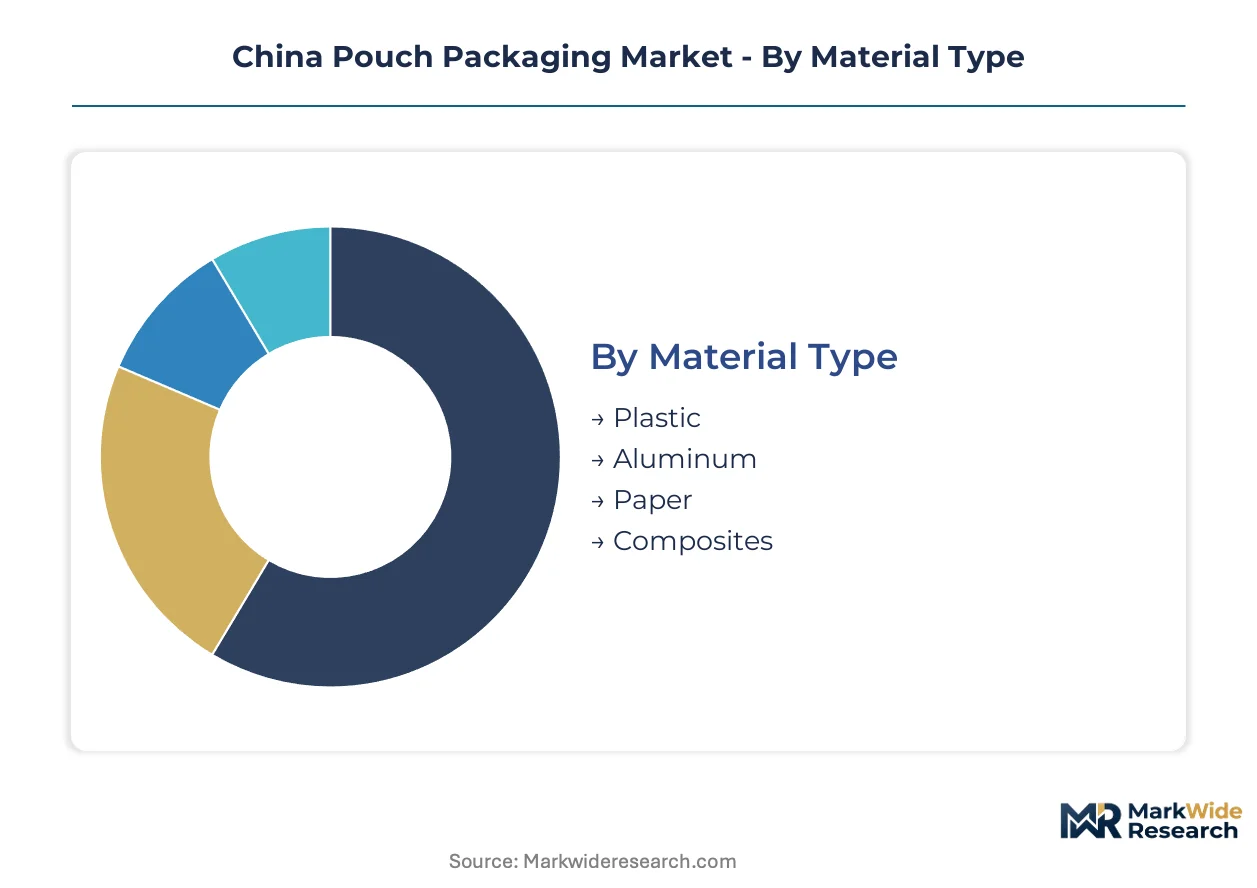
Pouch packaging in China fragments across material chemistry, closure engineering, and end-use specifications that determine barrier performance and regulatory compliance requirements. Each segmentation axis carries distinct margin profiles and capital intensity thresholds that shape converter specialization strategies.
Material Type:
Material selection spans cost-driven commodity films through high-barrier metallized laminates serving distinct shelf-life and sterilization protocols.
- Plastic:Multi-layer polyethylene and polypropylene coextrusions dominate volume through cost efficiency in dry food and retail snack applications. Yangtze River Delta converters leverage integrated film extrusion to supply Shanghai-based ready-meal processors with oxygen-barrier laminates.
- Aluminum:Foil-containing laminates enable retort sterilization and aseptic filling for pharmaceutical and premium food segments. Henan and Shandong foil rolling capacity feeds eastern converters, though logistics exposure creates margin volatility for non-integrated players.
- Paper:Kraft-polyethylene laminates serve dry goods and sustainable positioning for cosmetics brands seeking plastic reduction narratives. MIIT dual carbon goals are accelerating water-based coating investments for paper-based barrier improvement.
- Composites:Metallized PET and EVOH coextrusions bridge performance gaps between plastic economy and aluminum premium tiers. Sichuan food processors are adopting these structures for regional distribution without cold-chain dependency.
Established volume favors Plastic; emerging adoption favors Composites.
Closure Type:
Closure engineering determines dispensing convenience, resealability, and equipment capital requirements across liquid and solid product formats.
- Spout:Injection-molded fitments welded to pouch walls enable controlled pouring for beverages, sauces, and personal care liquids. TedPack's specialized insertion equipment creates technical moats in this segment against generic converters.
- Zipper:Press-to-close profiles provide resealability for multi-serve snacks and frozen foods without specialized filling equipment. Jiangsu converters are integrating zipper application inline with form-fill-seal lines to reduce secondary handling.
- Resealable:Hook-and-loop and adhesive strip systems offer intermediate convenience for institutional and healthcare packaging where full zipper durability exceeds functional requirements.
- Heat Seal:Plain thermal sealing remains dominant for single-serve portions and cost-sensitive commodity applications where opening convenience is secondary to material minimization.
Spout closures command premium positioning; Heat Seal retains volume dominance through material parsimony.
Application:
End-use verticals impose divergent barrier, registration, and traceability requirements that filter converter participation.
- Food & Beverage:Retort and aseptic pouches for ready-to-eat meals are displacing rigid trays in Shanghai, Jiangsu, and Zhejiang retail channels. SAMR GB compliance for migration limits elevates certified converters above uncertified competitors.
- Pharmaceuticals:NMPA-registered flexible containers for oral solids and liquids require multi-year approval timelines that freeze out new entrants. Shanghai Dura-Pack anchors supply through registration continuity investment.
- Personal Care:Metallized and holographic decoration drives pouch adoption for masks, serums, and travel formats where shelf presence competes with rigid alternatives.
- Pet Food:High-barrier structures for wet food and treats are gaining share from metal cans, with stand-up formats improving pallet density for e-commerce fulfillment.
Food & Beverage absorbs capacity; Pharmaceuticals extracts margin through regulatory barriers.
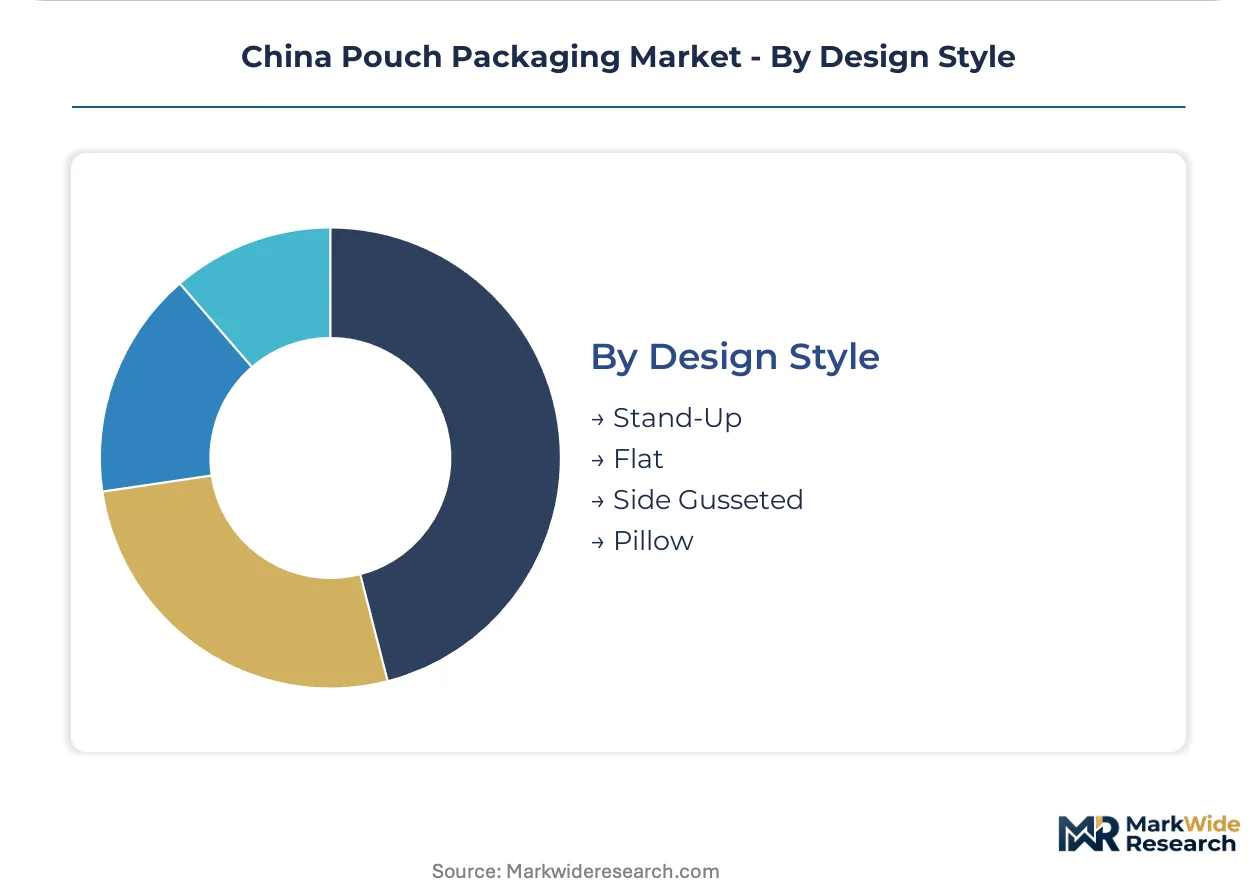
Design Style:
Structural geometry balances shelf presence, pallet efficiency, and filling equipment compatibility across retail and institutional channels.
- Stand-Up:Doyen and K-seal bottom gussets provide vertical display stability for retail-facing food, beverage, and personal care products. Gravure-printed stand-up pouches dominate premium positioning in tier-one city retail.
- Flat:Two-seal and three-seal configurations maximize pallet density for pharmaceutical bulk supply and institutional food service where logistics economics override shelf aesthetics.
- Side Gusseted:Quad-seal structures enable large-format packaging for pet food and industrial ingredients requiring filling volume without stand-up stability.
- Pillow:Simple back-sealed tubes minimize material and equipment cost for commodity snacks and dry goods with short distribution cycles.
Stand-Up captures brand investment; Flat retains pharmaceutical and institutional volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pouch packaging capacity clusters heavily in eastern coastal provinces where film extrusion, gravure printing, and pharmaceutical certification infrastructure overlap. Provincial emissions enforcement and SAMR compliance timelines are widening performance gaps between certified and uncertified converters.
Yangtze River Delta
Shanghai, Jiangsu, and Zhejiang processors dominate high-barrier food and pharmaceutical pouch supply. SAMR GB standards enforcement for food-contact migration limits is elevating certified converters above uncertified competitors in this cluster. Cangzhou Hualiang Packaging Decoration Co., Ltd leverages integrated gravure printing lines to serve regional food brands from manufacturing bases across Jiangsu.
Pearl River Delta
Guangdong converters supply cosmetics and personal care pouches with metallized and holographic decoration capabilities. MIIT dual carbon goals are accelerating water-based ink transitions across Shenzhen and Dongguan printing houses. Guangdong Danqing Printing Co., Ltd extends its flexible packaging breadth from cosmetics into pharmaceutical-grade barrier applications from its provincial base.
Beijing-Tianjin-Hebei
Pharmaceutical pouch demand concentrates around NMPA-registered facilities serving northern drug manufacturers. NMPA registration requirements for drug-contact flexible containers create multi-year approval barriers that freeze out new entrants. Shanghai Dura-Pack Packaging Co., Ltd anchors supply through registration continuity investment despite its Shanghai headquarters.
Sichuan-Chongqing
Western food processors remain underserved by high-barrier pouch suppliers certified for national distribution. Provincial emissions enforcement lags coastal intensity, delaying solvent recovery mandates for local converters. Chongqing-based ready-meal processors are adopting stand-up pouches for regional retail channels without cold-chain dependency.
Shandong Peninsula
Aluminum foil rolling capacity clusters in Shandong, feeding eastern converters with retort-grade laminates. Domestic foil supply concentration exposes Yangtze Delta converters to logistics cost spikes during regional transport disruptions. Qingdao and Yantai rolling mills are expanding output for pharmaceutical and premium food barrier applications.
China Pouch Packaging Market Competitive Landscape
Integrated decoration specialists and equipment-differentiated converters split the market between value-added margin capture and technical moat defense. The vendor base organizes around three strategic archetypes: gravure-integrated printers, spout-insertion equipment specialists, and pharmaceutical-registration incumbents. Competitive moves concentrate on cylinder cost absorption for short-run orders and solvent recovery capex to meet MEE enforcement timelines.
Within the gravure-integrated tier, Cangzhou Hualiang Packaging Decoration Co., Ltd and Guangdong Danqing Printing Co., Ltd exemplify converters capturing margin pools away from commodity film extrusion toward decoration services. TedPack Company Limited occupies a position among equipment-differentiated specialists, representing technical moat defense through specialized spout-insertion capabilities. These three entities collectively illustrate the market's bifurcation between printing-integrated and equipment-specialized competitive vectors.
| Leading Market Players |
|---|
| Cangzhou Hualiang Packaging Decoration Co., Ltd |
| TedPack Company Limited |
| OK Packaging Manufacturing Co. Ltd |
| Wenzhou Co-pack Co. Ltd |
| Dongguan Pasike Packaging Co. Ltd |
| Hangzhou Qinghong Packaging Co. Ltd |
| Guangdong Danqing Printing Co. Ltd |
| Shanghai Dura-Pack Packaging Co. Ltd |
| Rinpac |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Ningbo freight corridor carries aluminum foil laminates from Shandong rolling mills to Yangtze Delta converters, with transport cost spikes during regional disruptions feeding directly into premium tier pricing for retort-grade pouches and compressing margins for non-integrated buyers lacking captive foil supply.
Pricing Analysis
SAMR GB standards dictate the pricing tier structure across food-contact pouch supply. Three-tier pricing structure across premium, standard, and economy levels separates NMPA-registered pharmaceutical converters from certified food-grade suppliers and uncertified commodity producers. Price differentiation hinges on barrier performance certification and gravure cylinder customization depth. Cost compression in standard-tier plastic laminates is intensifying because Yangtze Delta converters absorb petrochemical resin volatility without backward integration. Economy-tier buyers in Sichuan-Chongqing regional markets exhibit highest price sensitivity; pharmaceutical brands purchasing NMPA-registered containers show least.
Supply Chain Analysis
Integrated Yangtze Delta converters including Cangzhou Hualiang and Guangdong Danqing hold dominant gravure printing and lamination capacity. Raw material sourcing draws from Shandong aluminum foil rolling, Sinopec petrochemical resin supply, and Henan metallized film production. Single-source vulnerability concentrates in aluminum foil feedstock where Henan and Shandong capacity clusters expose eastern converters to logistics disruption. Distribution runs through direct-to-manufacturer procurement channels consolidating previously fragmented spot-market purchasing for barrier films.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China pouch packaging is cycling through a petrochemical input cost trough, with resin price normalization enabling margin recovery for converters that deferred equipment retrofits during the volatility peak.
For Market Incumbents: Entrench gravure-integrated positions by absorbing cylinder lead times for short-run orders that generic converters cannot service profitably. Prioritize solvent recovery capex ahead of MEE enforcement timelines in Jiangsu and Zhejiang to capture provincial emissions credits. Defend against digital printing entrants by bundling barrier certification with decoration services for pharmaceutical and ready-meal accounts. For New Entrants and Emerging Players: Western province food processors in Sichuan and Chongqing represent the most penetrable entry point, with regional ready-meal brands adopting stand-up pouches without cold-chain dependency and lacking certified high-barrier supply. Spout-insertion equipment specialization for liquid condiments and sauces offers technical differentiation against commodity converters. Partner with regional distributors possessing established relationships with Chongqing-based processors to bypass direct vendor list barriers. For Investors and Strategic Acquirers: NMPA-registered pharmaceutical pouch specialists with active registration continuity represent the highest-conviction acquisition archetype, given multi-year approval barriers that freeze out new entrants and sustain pricing power. Long-term viability over the next decade rests on regulatory compliance infrastructure rather than commodity film extrusion scale. Monitor MIIT dual carbon enforcement intensity across provincial emissions audits as the inflection signal for accelerated industry consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Ink Transition | MEE provincial enforcement rewards early adopters with emissions credit advantages in Jiangsu printing clusters. |
| Spout-Insertion Equipment Investment | TedPack's technical moat demonstrates how specialized welding capabilities capture liquid packaging margin pools. |
| NMPA Registration Continuity | Shanghai Dura-Pack anchors pharmaceutical supply through multi-year approval timelines that block new entrants. |
| Western Province Distribution Buildout | Sichuan-Chongqing food processors remain underserved by certified high-barrier pouch suppliers. |
| Solvent Recovery Infrastructure | Lamination houses face eighteen-month payback horizons for equipment retrofit to meet MEE VOC limits. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation across regulatory and trade databases. Conversations captured perspectives from pouch converter operations managers, gravure cylinder engraving houses, SAMR compliance consultants, pharmaceutical packaging procurement leads at northern drug manufacturers, and ready-meal brand supply chain directors in Shanghai and Jiangsu. Secondary sources included NMPA registration filings, MIIT emissions enforcement notices, customs trade data for aluminum foil and resin imports, and provincial environmental audit disclosures. Bottom-up capacity estimates from individual converter facilities were triangulated against top-down demand projections from end-use verticals.
Forecast inputs considered material type segmentation across plastic, aluminum, paper, and composite structures; closure engineering spanning heat seal through spout insertion; and end-use verticals from food and beverage through pharmaceutical applications. Growth trajectories were derived from elasticity modeling against petrochemical input cost cycles, regulatory compliance investment waves, and regional manufacturing cluster expansion patterns. CAGRs reflect segment-specific assumptions for barrier performance tier migration and digital printing adoption curves.
Stress conditions across resin price volatility bands, MEE enforcement intensity scenarios, and NMPA registration approval delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of provincial emissions audit schedules and aluminum foil logistics cost indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Digital Printed Pouch Market
Pouch
Brazil Pouch Packaging Market
Pouch
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market
Pouch
North America Pouch Packaging Market
Pouch
Fin Seal Pouches Market
Pouch
Aluminium Bags and Pouches Market
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
Child Resistant Pouches Market
Pouch
Contour Pouches Market
Pouch
India Pouch Packaging Market
Pouch
Heat Seal Pouch Market
Pouch
Inverted Pouch Market
Pouch
Spouted Pouches Market
Pouch
High-Barrier Pouches Market
Pouch
North America Lithium-Ion Battery Pouch Film Market
Pouch
PCR Pouches Market