
 Pipette Controllers Market | 2026-2036
Pipette Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Pipette Controllers Market Analytics
Polypropylene is expanding its share in pipette controller housings and tip cones as manufacturers phase out polystyrene to cut unit costs and improve chemical resistance. Thermo Fisher Scientific leverages its global distribution network to sustain volume leadership across clinical research accounts. Eppendorf AG anchors its position through captive production of precision piston assemblies in Germany. INTEGRA Biosciences AG specializes in software-operated electronic controllers that differentiate on programmable step sequences for cell culture workflows.
Pipette controllers are handheld or motorized instruments designed to aspirate and dispense precise liquid volumes through disposable tips, typically achieving accuracy within ISO 8655-defined tolerances of 0.6% to 2.0% depending on volume range. Their primary purpose is to eliminate human error in repetitive liquid handling across quantitative analytical procedures. Electronic product types command the dominant share of value given their integration with laboratory information management systems, while manual variants retain volume in resource-constrained quality control settings. Drug development applications represent the fastest-expanding end-use pool as biologics pipelines multiply titration and formulation steps requiring traceable dispensing records.
FDA 21 CFR Part 11 compliance requirements shape software-operated controller design by mandating electronic records and audit trails for pharmaceutical quality control workflows. ISO 8655 and EU In Vitro Diagnostic Regulation standards jointly determine calibration intervals and performance verification protocols that laboratories must document for regulatory inspections. Stakeholders should monitor how MDR traceability requirements in Europe reshape service and recertification revenue models for instrument vendors.
Market Dynamics
Electronic pipette controllers are consolidating laboratory workflows as pharmaceutical quality control demands ISO 8655 traceability and FDA 21 CFR Part 11 audit trails, compressing manual instrument share in regulated environments.
Growth Catalysts
- Biologics pipeline expansion:Cell culture titration and formulation steps multiply traceable dispensing requirements across contract development and manufacturing organizations.
- EU MDR traceability mandates:European laboratories must document calibration intervals and performance verification, extending instrument replacement cycles and service contract attach rates.
- Polypropylene material transition:Manufacturers phase out polystyrene housings to improve chemical resistance and cut per-unit production costs.
Market Restraints
- Precision piston supply concentration:Captive production in Germany limits second-source availability for mid-tier controller assemblers.
- ISO 8655 calibration cost burden:Small contract research organizations face recurring third-party verification expenses that erode total cost of ownership advantages.
- Manual controller residual demand:Resource-constrained quality control settings in emerging markets delay electronic upgrade cycles.
Strategic Opportunities
- Software-operated programmable sequences:Integration with laboratory information management systems enables step-automation for high-throughput screening workflows.
- Service revenue recertification models:MDR traceability requirements in Europe reshape vendor economics toward recurring calibration and compliance documentation.
- Cell culture workflow specialization:Programmable electronic controllers capture share in regenerative medicine applications requiring sterile liquid handling protocols.
Industry Challenges
- ISO 8655 technician certification scarcity:Qualified calibration specialists concentrate in Western European and North American metropolitan laboratory clusters.
- Legacy system integration friction:Electronic controllers must interface with existing laboratory information management infrastructure without disrupting established sample tracking protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipette Controllers Market |
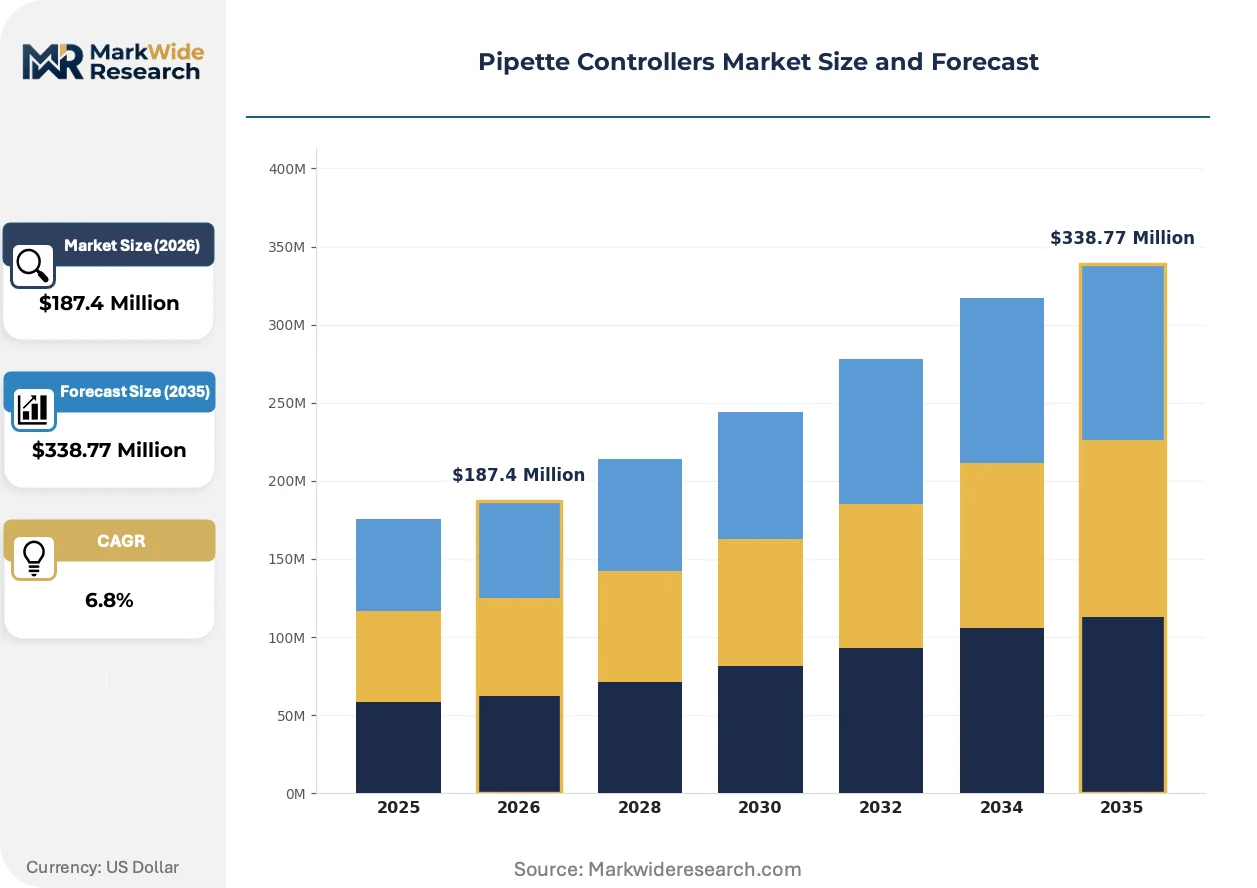
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
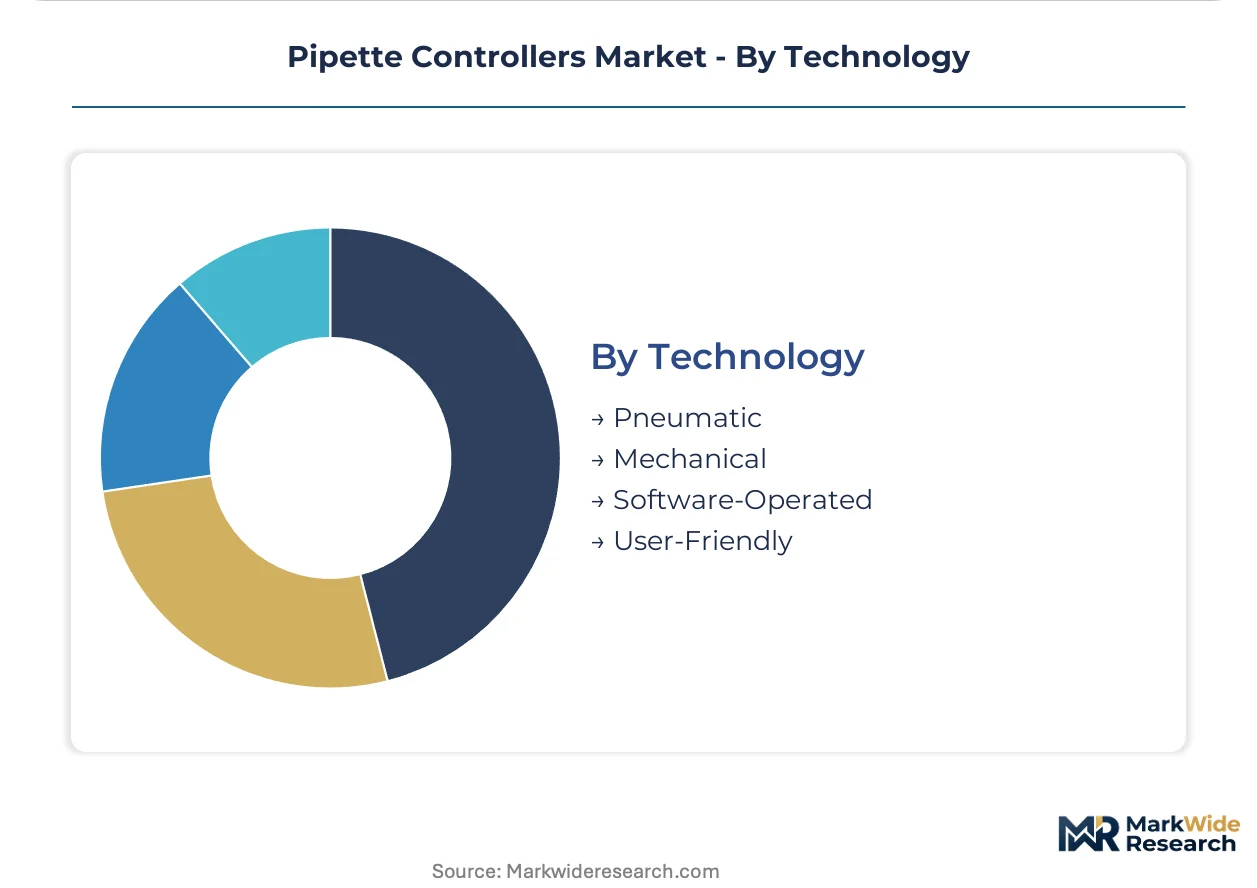
| Segmentation | Product Type: Electronic, Manual, Portable, Fixed Volume End User: Laboratories, Pharmaceutical Companies, Research Institutions, Quality Control Application: Clinical Research, Drug Development, Environmental Testing, Academic Research Technology: Pneumatic, Mechanical, Software-Operated, User-Friendly |
| Companies Covered | Thermo Fisher Scientific, Drummond Scientific Company, Eppendorf AG, Avantor, Inc, Merck, Gilson Incorporated, INTEGRA Biosciences AG, Mettler Toledo, Sartorius AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipette Controllers Market Evolving Landscape
Software-operated technology is compressing hardware differentiation as programmable step sequences and electronic record-keeping become baseline requirements rather than premium features.
Lithium-ion battery systems are consolidating power architecture in electronic pipette controllers, replacing alkaline disposable configurations. Pharmaceutical quality control laboratories adopt these rechargeable platforms to eliminate workflow interruptions during high-throughput screening. The shift is consolidating maintenance schedules and reducing hazardous waste disposal liabilities across FDA-regulated facilities.
EU In Vitro Diagnostic Regulation performance verification protocols now mandate documented calibration intervals for all quantitative liquid handling. Diagnostic laboratories must maintain audit-ready records for notified body inspections. German research institutions and French hospital laboratories are responding by consolidating vendor relationships around suppliers offering integrated compliance documentation.
Consolidated procurement through group purchasing organizations is compressing distributor margins and concentrating volume with manufacturers offering direct service networks. Academic medical centers and multi-site pharmaceutical companies negotiate enterprise agreements spanning instruments, calibration, and software licenses. This pattern is most visible in United States research corridors where integrated delivery networks centralize laboratory capital planning.
Pipette Controllers Market Segmentation
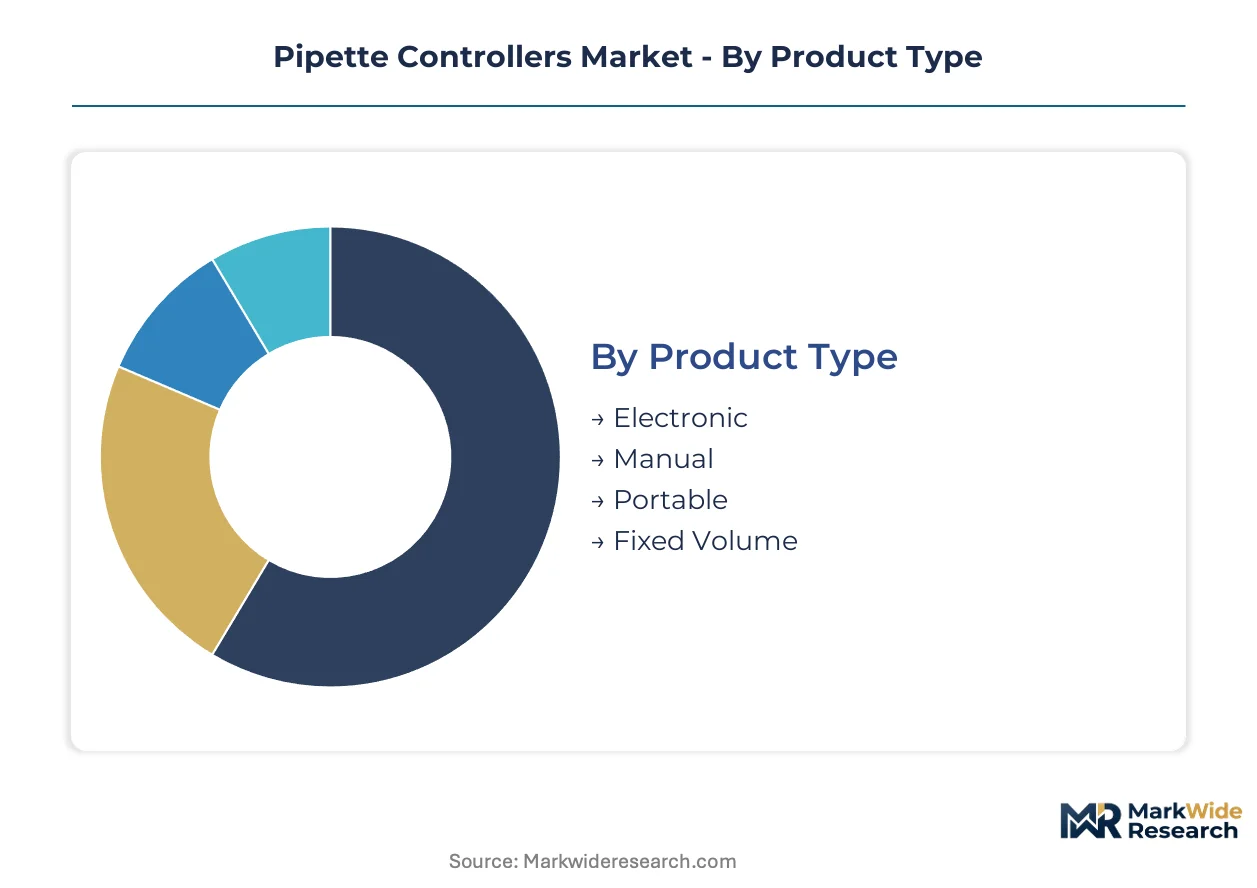
Segmentation in pipette controllers reveals how precision requirements, regulatory compliance burdens, and workflow automation intensity vary across user environments. Each dimension shapes procurement criteria, service attach rates, and vendor positioning strategies differently.
Product Type:
The customization-to-standardization spectrum spans programmable electronic units with LIMS integration at one extreme to fixed-volume mechanical devices for repetitive assays at the other.
- Electronic:Motorized piston drive with digital volume display and programmable step sequences. Pharmaceutical quality control laboratories in Germany and Switzerland specify these for FDA 21 CFR Part 11 audit trails in high-throughput screening workflows.
- Manual:Thumb-wheel or lever-actuated piston mechanisms without electronic components. Resource-constrained quality control settings in India and Brazil retain volume here due to lower capital outlay and minimal calibration infrastructure.
- Portable:Battery-powered lightweight designs for field sampling and mobile laboratory deployments.
- Fixed Volume:Factory-calibrated single-volume settings for repetitive diagnostic assays requiring minimal operator training.
Leading the category by volume: Electronic. Growing fastest: Portable.
End User:
Cost tier stratification separates capital-rich pharmaceutical enterprises from grant-dependent academic centers and fee-for-service testing laboratories.
- Laboratories:Hospital, reference, and independent diagnostic facilities performing quantitative analytical procedures. French hospital laboratories and German research institutions concentrate demand for ISO 8655-compliant units with documented calibration intervals.
- Pharmaceutical Companies:Drug development and manufacturing quality control operations. Biologics pipelines at CDMOs in Switzerland and the United States multiply traceable dispensing requirements, compressing manual instrument share.
- Research Institutions:University and government-funded basic science facilities with cyclical capital budgets.
- Quality Control:Industrial testing and regulatory compliance laboratories in food, environmental, and chemical sectors.
Pharmaceutical companies command the highest per-unit spend. Academic research institutions represent the most price-sensitive tier.
Application:
Application maturity varies from established clinical protocols to emerging regenerative medicine workflows requiring sterile liquid handling documentation.
- Drug Development:Cell culture titration, formulation, and stability testing across biologics pipelines. Contract development organizations in the United States and Germany drive specification intensity for programmable step sequences and electronic record-keeping.
- Clinical Research:Diagnostic assay validation and biomarker quantification in regulated settings. EU In Vitro Diagnostic Regulation performance verification protocols now mandate documented calibration intervals for all quantitative liquid handling in French and German diagnostic laboratories.
- Environmental Testing:Field sampling and laboratory analysis of water, soil, and air matrices.
- Academic Research:Basic science investigations with variable throughput and limited compliance documentation requirements.
Drug development commands premium pricing. Academic research exhibits the steepest expansion trajectory in absolute unit terms.
Technology:
Supply concentration for precision piston assemblies favors pneumatic and mechanical architectures with established German manufacturing clusters.
- Software-Operated:Microprocessor-controlled volume setting with LIMS integration and programmable automation. Eppendorf AG and INTEGRA Biosciences AG anchor European supply for these systems, with programmable step sequences now baseline for cell culture workflows.
- Mechanical:Precision-machined piston assemblies with manual volume adjustment. Captive production in Germany limits second-source availability for mid-tier controller assemblers serving emerging markets.
- Pneumatic:Compressed air or vacuum-driven aspiration for high-volume liquid handling.
- User-Friendly:Simplified interfaces and ergonomic designs reducing operator training burden and repetitive strain injury risk.
Software-operated systems lead value concentration. User-friendly designs are gaining share fastest in resource-constrained settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical quality control laboratories in Germany and Switzerland generate the densest demand concentration for ISO 8655-compliant electronic pipette controllers. Biologics pipelines at contract development organizations in the United States multiply traceable dispensing requirements. Academic medical centers in France consolidate procurement through enterprise agreements spanning instruments and calibration services.
United States
FDA 21 CFR Part 11 compliance mandates electronic records and audit trails for pharmaceutical quality control workflows. Biologics pipelines at contract development and manufacturing organizations in Massachusetts and North Carolina multiply programmable step sequence requirements. Greater Boston anchors demand concentration for software-operated controllers serving high-throughput screening facilities.
Germany
Eppendorf AG and Sartorius AG anchor a precision instrument manufacturing cluster serving European research institutions. EU MDR traceability requirements reshape service contract economics toward recurring calibration documentation. The Hamburg-Heidelberg corridor concentrates captive production of precision piston assemblies for mid-tier controller assemblers.
Switzerland
Swissmedic oversight tightens performance verification protocols for diagnostic liquid handling in Basel and Zurich. Contract development organizations specializing in biologics formulations drive specification intensity for programmable electronic controllers. The Basel pharmaceutical cluster consolidates vendor relationships around integrated compliance documentation.
France
ANSM enforces EU In Vitro Diagnostic Regulation calibration interval documentation for hospital laboratories in Paris and Lyon. French diagnostic laboratories maintain audit-ready records for notified body inspections. The Île-de-France region concentrates procurement consolidation through academic medical center enterprise agreements.
India
CDSCO quality control requirements expand traceable dispensing documentation for pharmaceutical manufacturing in Maharashtra and Gujarat. Resource-constrained quality control settings retain manual controller volume due to lower capital outlay. The Mumbai-Pune corridor exhibits emerging demand for electronic upgrades as calibration infrastructure matures.
Pipette Controllers Market Competitive Landscape
Portfolio diversification dominates the current landscape as precision instrument manufacturers extend software-operated controller lines with LIMS integration capabilities. The vendor base organizes around three strategic archetypes: diversified life science conglomerates with global distribution networks, German captive producers of precision piston assemblies, and Swiss specialists in programmable automation for cell culture workflows. M&A activity and strategic partnerships concentrate competitive moves among mid-tier assemblers seeking second-source piston supply.
Within the diversified conglomerate tier, Thermo Fisher Scientific leverages its global distribution infrastructure to sustain volume leadership across clinical research accounts. Eppendorf AG anchors the captive production archetype through its German-based precision piston assembly operations. INTEGRA Biosciences AG occupies a specialist position exemplifying software-operated electronic controller differentiation for programmable step sequences in cell culture workflows.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Drummond Scientific Company |
| Eppendorf AG |
| Avantor, Inc |
| Merck |
| Gilson Incorporated |
| INTEGRA Biosciences AG |
| Mettler Toledo |
| Sartorius AG |
| Others |
Value Network & Pricing Analysis
Qualified calibration specialists concentrated in Hamburg and Heidelberg compress labor-cost differentials between Western European and emerging-market service tiers, widening the spread between premium ISO 8655-certified units and economy manual controllers. This workforce scarcity in Germany anchors pricing power for captive piston producers while forcing mid-tier assemblers in India and Brazil to absorb margin compression or defer electronic upgrades.
Pricing Analysis
Volume concentrates in manual controllers sold to resource-constrained quality control settings, while margins accrue to software-operated electronic units with LIMS integration and FDA 21 CFR Part 11 audit trail capabilities. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade programmable units from hospital laboratory workhorses and emerging-market manual devices. Price differentiation hinges on ISO 8655 certification grade and after-sales calibration bundling. Cost compression in the economy tier is intensifying because polypropylene material transitions cut production expenses while calibration infrastructure scarcity in India and Brazil delays electronic adoption. Academic research institutions exhibit the sharpest price sensitivity; pharmaceutical quality control laboratories show the least.
Supply Chain Analysis
Regional distribution centers in Hamburg, Boston, and Singapore orchestrate hub-and-spoke patterns that consolidate inventory for precision piston assemblies before last-mile deployment to hospital laboratories and CDMOs. Geographic supply concentration rests on Germany for captive piston production, Switzerland for programmable controller final assembly, and China for polypropylene housing injection molding. Raw material dependencies center on medical-grade polypropylene resin, lithium-ion battery cells, and precision-machined stainless steel piston rods. Single-source vulnerability in German piston supply exposes mid-tier assemblers to allocation risk during demand surges. Distribution runs through direct service networks for pharmaceutical accounts and laboratory distributors for academic institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pipette controller supply remains constrained by captive precision piston capacity in Germany, propping pricing power for incumbents with in-house manufacturing while compressing margins for second-source-dependent assemblers.
For Market Incumbents: Deepen captive production of precision piston assemblies in the Hamburg-Heidelberg corridor to defend against emerging mid-tier assemblers seeking alternative supply sources. Expand calibration service contract attach rates to capture recurring revenue from EU MDR traceability mandates, using ISO 8655 technician certification scarcity as a retention lever against price competition from manual controller distributors. For New Entrants and Emerging Players: The mid-tier price gap between Eppendorf-grade programmable units and unbranded manual controllers opens white-space in portable battery-powered controllers for field sampling applications. Target environmental testing laboratories in India and Brazil with simplified user-friendly designs that bypass ISO 8655 calibration infrastructure requirements. Penetrate through regional distributors serving CDSCO-regulated pharmaceutical manufacturing in Maharashtra and Gujarat. For Investors and Strategic Acquirers: Re-rating potential sits with software-operated controller specialists given biologics pipeline expansion and programmable step sequence demand from cell culture workflows. Long-term viability favors acquisition targets with integrated compliance documentation capabilities and direct hospital laboratory relationships in France and Germany. Watch calibration technician certification scarcity as the inflection signal for service revenue multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Piston Manufacturing | Captive supply of precision piston assemblies secures allocation priority during demand surges from German CDMOs. |
| Calibration Service Contract Expansion | EU MDR traceability mandates in France and Germany convert one-time instrument sales into recurring compliance documentation revenue. |
| Software Companion Development | LIMS integration capabilities differentiate programmable controllers for FDA 21 CFR Part 11 pharmaceutical quality control workflows. |
| Portable Controller Line Launch | Battery-powered designs capture environmental testing demand in India and Brazil where field sampling infrastructure is expanding. |
| Hospital System Partnership | Enterprise agreements with French academic medical centers consolidate procurement volume and lock out distributor competitors. |
Research Methodology
Multi-period observation of pharmaceutical quality control capital expenditure patterns, biologics pipeline announcements, and ISO 8655 calibration service pricing anchored the trend analysis, supplemented by interviews with laboratory procurement managers, biomedical engineers at German research institutions, regulatory affairs leads at CDMOs, and precision instrument distribution channel partners. Secondary validation drew from FDA 510(k) filings for electronic pipette controllers, EMA MDR technical documentation databases, EU In Vitro Diagnostic Regulation implementation guidance, and SEC filings of diversified life science conglomerates. Bottom-up unit demand estimates triangulated against top-down pharmaceutical R&D spending allocations across the analysis window.
Input-output matrices mapped electronic versus manual controller adoption rates against end-user compliance requirements, application workflow intensity, and regional calibration infrastructure maturity. Segmentation dimensions spanned product type, end user archetype, application maturity, and technology architecture. CAGRs were derived from curve-fitting observed replacement cycles and penetration trajectories against biologics pipeline growth and MDR implementation timelines. Industry-specific forecast inputs included ISO 8655 technician certification density by metropolitan laboratory cluster and lithium-ion battery cost curves for portable controller power systems.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time CDSCO enforcement data and emerging-market calibration service pricing introduce uncertainty bands around India and Brazil penetration assumptions. Forecasts reflect documented assumptions regarding MDR implementation pace and biologics pipeline conversion to traceable dispensing requirements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Dialysis Device and Concentrates Market
Medical Devices
Peripheral Micro Catheters Market
Medical Devices
Europe Insulin Pumps Market
Medical Devices
Speech Generating Devices Market
Medical Devices
Chile Artificial Organs and Bionic Implants Market
Medical Devices
Air Oxygen Blender Market
Medical Devices
Bandage Contact Lenses Market
Medical Devices
Global Liposuction Surgery Devices Market
Medical Devices
Radiolucent Wrist Fixator Market
Medical Devices
France Minimally Invasive Surgery Devices Market
Medical Devices
Global Thoracic Drainage Devices Market
Medical Devices
Gutta Percha Obturator Market
Medical Devices
Stimulation Therapies Market
Medical Devices
Homecare Medical Devices Market
Medical Devices
North America Cardiac Rhythm Management Devices Market
Medical Devices
PDA Closure Devices Market