
 Mobile Continuous Patient Monitors Market | 2026-2036
Mobile Continuous Patient Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Continuous Patient Monitors Market Analytics
The capital-intensity divergence between sensor manufacturers and platform aggregators is redrawing competitive boundaries in mobile continuous patient monitors. Philips Healthcare leverages in-house semiconductor fabrication to control pulse-oximetry chip supply. Masimo sustains proprietary signal-processing algorithms that filter motion artifact from arterial waveforms. Medtronic anchors its position through captive distribution into integrated delivery networks.
Mobile continuous patient monitors are portable, network-connected physiological sensors that track vital signs—heart rate, blood oxygen saturation, respiratory rate, and electrocardiogram rhythm—through wearable patches, finger clips, or implantable leads, transmitting encrypted data to clinical dashboards via Bluetooth or cellular modems for real-time triage and longitudinal trend analysis. Wearable devices dominate unit volume due to low patient burden and rechargeable battery architectures, while implantable monitors capture premium margins from cardiac arrhythmia detection in ambulatory settings. Telehealth services represent the fastest-expanding delivery mode as synchronous video platforms integrate live biometric feeds from homebound patients.
FDA software-as-medical-device guidance and HIPAA security rule enforcement shape product architecture decisions, mandating end-to-end encryption and audit trails for cloud-based data storage. The EU MDR and GDPR impose parallel conformity requirements for European market access, extending clinical validation burdens and data-localization costs. Stakeholders must monitor evolving reimbursement granularity for remote physiologic monitoring CPT codes to align portfolio investment with sustainable revenue capture.
Market Dynamics
Reimbursement code granularity for remote physiologic monitoring is restructuring competitive economics, forcing vendors to align device portfolios with CPT billing pathways rather than clinical feature differentiation alone.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:Medicare CPT codes 99453-99458 in the United States establish sustainable revenue capture for home-based monitoring services, pulling capital into ambulatory sensor development.
- Wearable Form Factor Miniaturization:Low-power Bluetooth Low Energy chipsets enable multi-day battery life in patch-based monitors, reducing patient adherence barriers in post-acute cardiac recovery programs.
- FDA Software-as-Medical-Device Pathway:The 2021 guidance accelerates clearance timelines for algorithm-driven diagnostic features, compressing product development cycles for cloud-native monitoring platforms.
Market Restraints
- Semiconductor Supply Concentration:Pulse-oximetry photodiode fabrication concentrates in Taiwanese foundries, exposing device vendors to geopolitical disruption in advanced sensor component sourcing.
- Clinical Validation Burden:EU MDR requirements for equivalence demonstrations in Class IIa wearable monitors extend regulatory timelines by 12-18 months for European market entry.
- Motion Artifact Technical Ceiling:Proprietary signal-processing algorithms face fundamental noise-floor limits during patient ambulation, constraining diagnostic confidence in outpatient arrhythmia detection.
Strategic Opportunities
- Underpenetrated Rural Homecare:Federally Qualified Health Centers in the United States lack remote monitoring infrastructure, creating whitespace for cellular-enabled devices bypassing broadband dependency.
- AI-ECG Convergence:Deep learning classification of single-lead electrocardiogram streams enables automated atrial fibrillation detection without cardiologist overread, expanding addressable monitoring populations.
- Direct-to-Employer Channel:Self-insured corporations in Germany are piloting occupational health monitoring programs, circumventing traditional hospital procurement gatekeepers.
Industry Challenges
- Biomedical Signal Processing Talent Scarcity:The intersection of electrical engineering and clinical physiology expertise remains concentrated in Boston and Tel Aviv innovation clusters, constraining R&D scaling.
- Legacy EHR Integration Friction:Hospital information systems from Cerner and Epic require custom HL7 FHIR middleware development, extending deployment timelines and inflating professional services costs.
- Cloud Security Certification Delays:HIPAA-compliant infrastructure audits and SOC 2 Type II attestations add 6-9 months to commercial launch schedules for SaaS-native monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Continuous Patient Monitors Market |
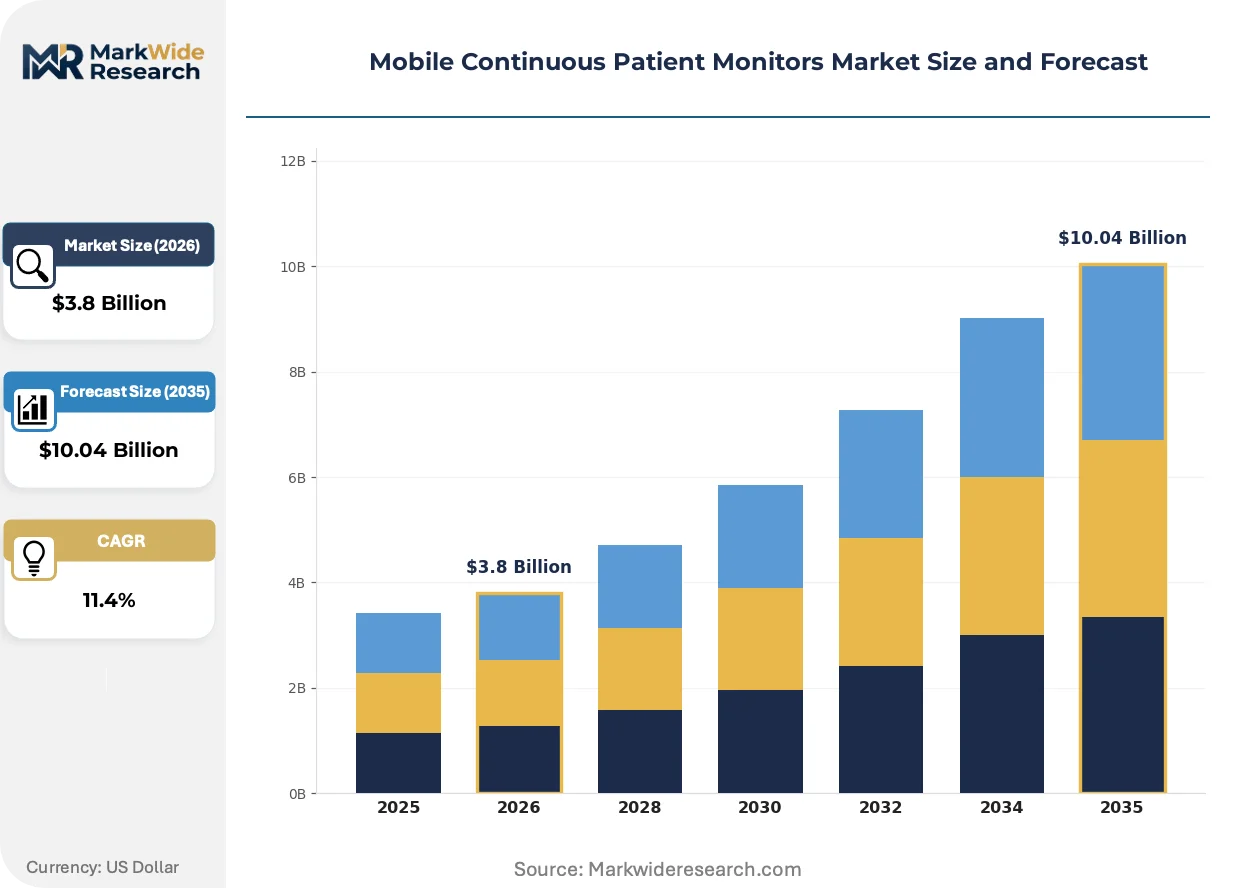
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Implantable Monitors, Handheld Units, Smartphone Applications Technology: Bluetooth, Wi-Fi, Cellular, NFC End User: Patients, Healthcare Providers, Homecare Agencies, Research Institutions Delivery Mode: Remote Monitoring, In-Hospital Systems, Telehealth Services, On-Demand Access |
| Companies Covered | Philips Healthcare, GE Healthcare, Medtronic, Masimo, Mindray Medical, Abbott Laboratories, Siemens Healthineers, Nihon Kohden Corporation, Drägerwerk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Continuous Patient Monitors Market Evolving Landscape
Algorithmic diagnostic autonomy is redrawing the boundary between consumer wellness devices and regulated medical monitors, compressing the traditional multi-year gap between fitness tracker adoption and clinical-grade clearance.
Photoplethysmography is fragmenting across application-specific implementations. Basic heart-rate variants dominate consumer wristbands from Apple and Fitbit. Medical-grade pulse-oximetry with motion compensation penetrates hospital-at-home programs. Transdermal glucose proxies using near-infrared spectroscopy attract diabetes management investment. Each variant optimizes for different signal-to-noise tradeoffs, preventing technology consolidation.
EU MDR post-market surveillance requirements mandate systematic literature review updates for Class IIa wearable monitors. Manufacturers must submit periodic safety reports to notified bodies, elevating clinical affairs staffing ratios. German and French vendors disproportionately absorb these compliance costs, reshaping competitive economics against US counterparts with simpler FDA 510(k) maintenance obligations.
Hospital procurement departments are unbundling device hardware from data platform subscriptions. Integrated delivery networks in Texas and Florida now source pulse-oximetry patches through group purchasing organizations while negotiating separate SaaS contracts for cloud analytics. This bifurcation exposes pure-play hardware vendors to margin compression while rewarding platform aggregators with recurring revenue visibility.
Mobile Continuous Patient Monitors Market Segmentation
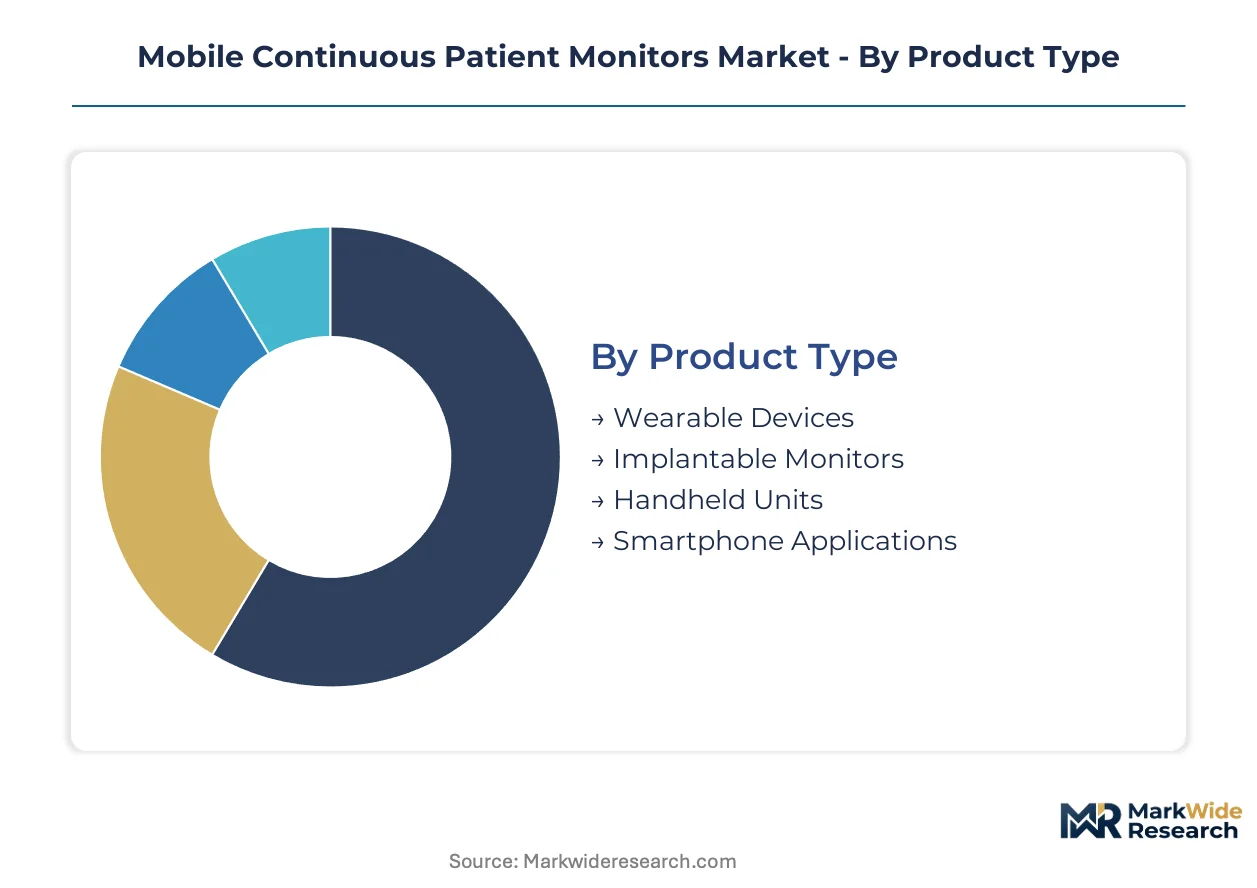
Segmentation in mobile continuous patient monitors determines reimbursement pathways and regulatory clearance requirements. Product architecture choices cascade through connectivity standards, end-user workflows, and delivery infrastructure investments.
Product Type:
FDA 510(k) clearance requirements vary sharply across form factors, with implantable devices facing PMA scrutiny while wearable patches navigate streamlined De Novo pathways.
- Wearable Devices:Patch-based sensors with rechargeable lithium-polymer batteries transmit photoplethysmography and single-lead ECG via Bluetooth Low Energy. Homecare agencies in the United States deploy these for post-acute cardiac recovery, drawn by Medicare CPT 99454 reimbursement for daily biometric transmission.
- Implantable Monitors:Subcutaneous leadless devices with decade-long battery life capture arrhythmia episodes through intracardiac electrogram analysis. Cardiology practices in Germany and France absorb premium device costs under statutory health insurance DRG carve-outs for unexplained syncope workups.
- Handheld Units:Finger-clip pulse oximeters with OLED displays serve intermittent spot-checking in Indian primary health centers lacking continuous infrastructure.
- Smartphone Applications:Camera-based heart rate variability tools operate in regulatory gray zones, awaiting FDA enforcement discretion for wellness-to-medical transitions.
Wearable devices handle the majority of throughput; smartphone applications are expanding most quickly on share as software-as-medical-device pathways mature.
Technology:
Connectivity choices determine geographic addressability and infrastructure dependency, with cellular modems unlocking rural penetration where broadband fails.
- Bluetooth:Dominates bedside and home-based deployments through low-power 2.4 GHz protocols, pairing with tablet-based clinical dashboards in Texas hospital-at-home programs.
- Cellular:LTE-M and NB-IoT chipsets enable direct-to-cloud transmission without patient smartphone dependency, penetrating Federally Qualified Health Center service areas with unreliable Wi-Fi.
- Wi-Fi:Hospital-grade 5 GHz implementations support high-frequency waveform streaming in intensive care step-down units, constrained by enterprise network security policies.
- NFC:Near-field pairing simplifies device onboarding for elderly patient populations in Japanese long-term care facilities, limiting range to centimeters.
Bluetooth anchors current installed base; cellular is climbing the fastest as rural reimbursement codes activate.
End User:
Procurement authority fragments across clinical settings, with homecare agencies wielding growing influence over device selection through value-based contracting.
- Healthcare Providers:Integrated delivery networks in Florida negotiate unbundled hardware and SaaS contracts, separating pulse-oximetry patch procurement from analytics platform subscriptions.
- Homecare Agencies:Post-acute specialists in the United States scale remote monitoring programs under Medicare Advantage capitation, absorbing upfront device costs against downstream readmission penalties.
- Patients:Direct-to-consumer purchases concentrate in fitness-adjacent heart rate monitoring, awaiting clinical validation for arrhythmia detection claims.
- Research Institutions:Academic medical centers in Boston and Tel Aviv deploy investigational device exemptions for algorithm training datasets, bridging premarket and commercial phases.
Healthcare providers command current revenue concentration; homecare agencies are gaining share fastest as post-acute monitoring shifts beyond hospital walls.
Delivery Mode:
Service architecture determines recurring revenue visibility and clinical workflow integration depth.
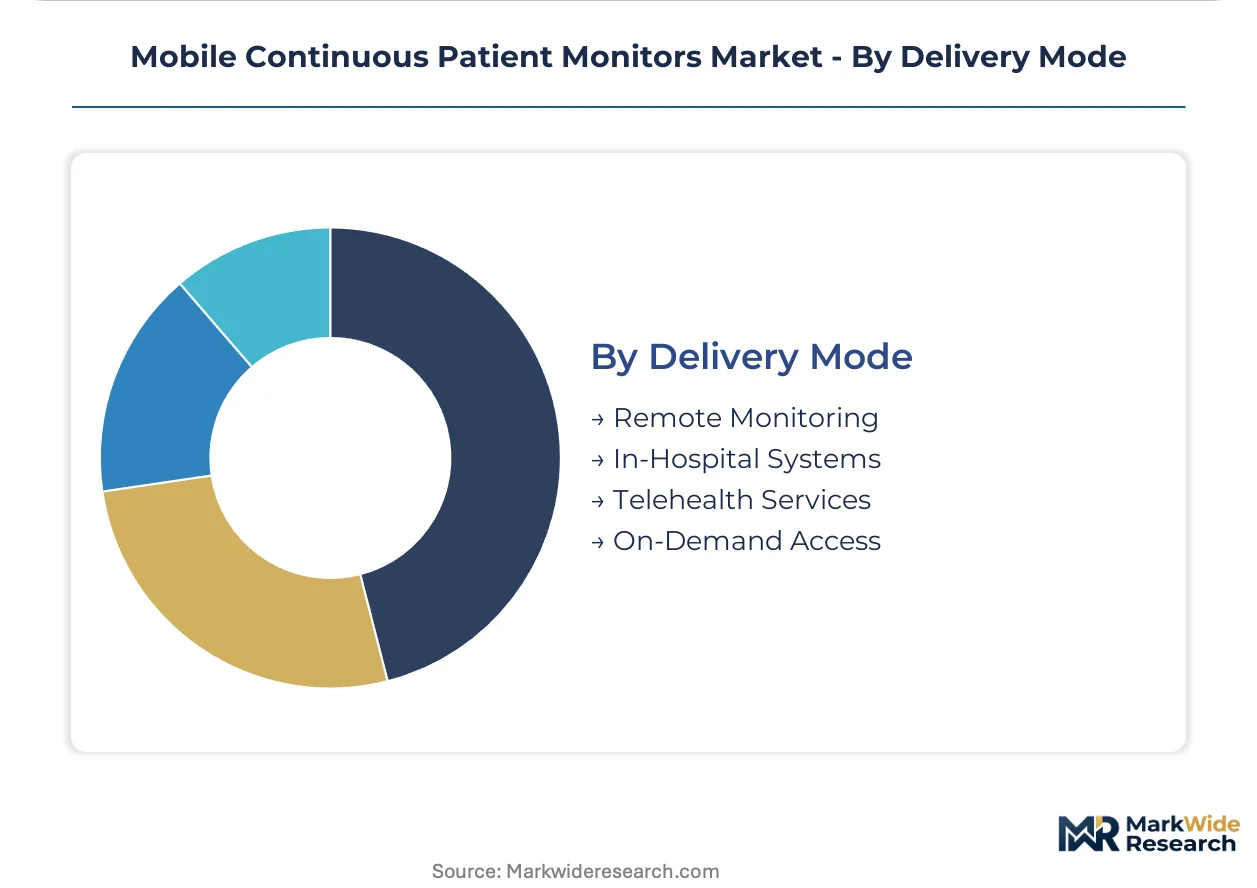
- Telehealth Services:Synchronous video platforms with live biometric overlay integrate remote patient monitoring into virtual visit billing, expanding fastest among Medicare Advantage plans in Arizona and Nevada.
- Remote Monitoring:Asynchronous data review by nursing staff captures chronic condition management revenue under CPT 99457-99458 time-based codes.
- In-Hospital Systems:Enterprise telemetry networks with centralized monitoring stations face margin pressure as step-down monitoring migrates to wearable alternatives.
- On-Demand Access:Event-activated monitoring for symptomatic patients operates outside preventive care reimbursement frameworks, limiting scale.
Remote monitoring handles current volume leadership; telehealth services show steepest expansion trajectory as platform consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in mobile continuous patient monitors diverges sharply between the United States and Germany, with Medicare reimbursement codes enabling premium capture in American homecare while EU MDR compliance costs compress margins for European vendors. This asymmetry shapes capital allocation toward regulatory arbitrage opportunities.
United States
Homecare agencies in Arizona and Nevada scale remote monitoring programs under Medicare Advantage capitation, absorbing upfront device costs against downstream readmission penalties. FDA 510(k) clearance pathways for software-as-medical-device compress development timelines for algorithm-driven platforms. The Boston-Tel Aviv innovation corridor concentrates biomedical signal processing talent, with academic medical centers deploying investigational device exemptions for training datasets.
Germany
Statutory health insurance DRG carve-outs for unexplained syncope workups sustain premium pricing for implantable cardiac monitors in cardiology practices. EU MDR post-market surveillance requirements mandate systematic literature review updates, elevating clinical affairs staffing ratios for domestic vendors. The Baden-Württemberg medical technology cluster absorbs disproportionate compliance costs, reshaping competitive economics against US counterparts.
China
NMPA regulatory harmonization with international standards accelerates market entry for multinational device manufacturers while domestic champions scale production of pulse-oximetry photodiodes. The Yangtze River Delta semiconductor foundry ecosystem supplies critical sensor components, though geopolitical exposure in Taiwanese fabrication concentrates supply risk. Shanghai-based integrated delivery networks pilot hospital-at-home programs with cellular-enabled monitoring.
Japan
PMDA reimbursement approvals for wearable cardiac monitors lag FDA timelines by 18-24 months, delaying product launches for multinational vendors. METI industrial policy prioritizes domestic production of medical-grade Bluetooth Low Energy chipsets. The Kanto region's long-term care facilities adopt NFC-enabled devices for elderly patient onboarding, limiting range but simplifying deployment.
India
Primary health centers in Maharashtra and Karnataka deploy handheld finger-clip pulse oximeters for intermittent spot-checking where continuous infrastructure remains absent. CDSCO medical device rules impose quality standards on imports while PLI scheme incentives attract domestic manufacturing investment. The Bangalore medical technology corridor develops low-cost wearable architectures for export to African markets.
Mobile Continuous Patient Monitors Market Competitive Landscape
Concentration sits with diversified health technology conglomerates that leverage captive distribution into integrated delivery networks. The vendor base spans three tiers: semiconductor-integrated manufacturers controlling sensor supply chains, algorithm specialists monetizing proprietary signal-processing IP, and platform aggregators capturing recurring SaaS revenue. Competitive dynamics center on unbundling hardware from analytics subscriptions and securing FDA clearance velocity for cloud-native diagnostic features.
Within the semiconductor-integrated tier, Philips Healthcare and Masimo exemplify divergent strategic postures. Philips anchors its position through in-house pulse-oximetry chip fabrication and enterprise telemetry infrastructure. Masimo occupies a specialist position centered on motion-compensation algorithms that filter artifact from arterial waveforms. Medtronic represents the implantable monitor archetype, leveraging cardiac rhythm management heritage into subcutaneous leadless devices for ambulatory arrhythmia detection.
| Leading Market Players |
|---|
| Philips Healthcare |
| GE Healthcare |
| Medtronic |
| Masimo |
| Mindray Medical |
| Abbott Laboratories |
| Siemens Healthineers |
| Nihon Kohden Corporation |
| Drägerwerk |
| Others |
Value Network & Pricing Analysis
Photoplethysmography chip migration from legacy CMOS to silicon-on-insulator architectures simultaneously redistributes fabrication demand toward Taiwanese foundries and compresses unit economics for pulse-oximetry vendors locked into older process nodes.
Pricing Analysis
The customization-premium spread in mobile continuous patient monitors separates configured-to-order implantable cardiac monitors from standard wearable patch configurations. Subscription-based SaaS pricing for cloud analytics platforms now dominates revenue capture, with FDA 510(k) certification tier and enterprise telemetry integration depth serving as primary price differentiation drivers. Cost compression in the wearable segment intensifies as group purchasing organizations consolidate procurement volume. Homecare agencies exhibit highest price sensitivity due to capitated reimbursement exposure, while cardiology practices absorb premium implantable device costs under DRG carve-outs.
Supply Chain Analysis
Taiwan Strait transit vulnerability underwrites supply security planning for photodiode-dependent device manufacturers. Pulse-oximetry sensor fabrication concentrates in Taiwan and South Korea, with lithium-polymer battery cell production anchored in China and Japan. Raw material flows draw from gallium arsenide substrates, indium phosphide wafers, and medical-grade silicone encapsulants. Single-source vulnerability in BLE chipset supply from Nordic Semiconductor and Qualcomm exposes vendors to allocation rationing during demand spikes. Distribution runs through integrated delivery network procurement committees and group purchasing organization contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of biomedical signal processing engineers fluent in both electrical engineering and clinical physiology constrains R&D scaling velocity across the vendor base, amplifying returns on captive talent acquisition.
For Market Incumbents: Secure algorithmic talent clusters in Boston and Tel Aviv through targeted acquisition of specialist engineering boutiques before compensation inflation erodes hiring economics. Backward integration into pulse-oximetry photodiode fabrication mitigates Taiwanese foundry concentration risk. Channel control through captive distribution into integrated delivery networks defends margin position against unbundling pressures from procurement departments. For New Entrants and Emerging Players: Rural Federally Qualified Health Center infrastructure gaps present immediate service-layer whitespace where cellular-enabled devices bypass broadband dependency. Direct-to-employer occupational health programs in Germany offer the most penetrable entry vector outside hospital procurement gatekeepers. SaaS-native platform positioning with automated ECG classification features enables rapid FDA 510(k) clearance velocity against legacy hardware incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed platform aggregators possessing recurring revenue visibility but lacking semiconductor integration depth. Long-term viability over the coming decade hinges on reimbursement code alignment rather than clinical feature differentiation alone. Watch Medicare CPT code granularity expansion for remote physiologic monitoring as the definitive demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Accelerates clearance timelines for algorithm-driven diagnostic platforms against PMA scrutiny. |
| Hospital System Partnership | Locks in enterprise telemetry infrastructure commitments from integrated delivery networks. |
| Reimbursement Strategy | Aligns device portfolios with Medicare CPT 99453-99458 billing pathways for sustainable revenue. |
| Backward Integration into Sensor Fabrication | Captures pulse-oximetry photodiode supply security against Taiwanese foundry concentration. |
| Software Companion Development | Enables AI-ECG convergence for automated atrial fibrillation detection without cardiologist overread. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committees and secondary validation through CMS Medicare reimbursement databases anchors the qualitative findings. Conversations with biomedical engineers, GPO contracts managers, and homecare agency operations directors inform procurement workflow dynamics. FDA 510(k) filings, EU MDR notified body submissions, and hospital procurement databases provide regulatory and commercial context. Bottom-up unit economics modeling triangulates against top-down market sizing from reimbursement code penetration analysis.
Sensitivity analysis across connectivity technology adoption curves and reimbursement code activation timelines shapes the analytical framework. Segmentation dimensions span form factor architecture, transmission protocol, end-user procurement authority, and delivery mode service structure. CAGRs derive from logistic diffusion modeling of wearable device penetration in post-acute cardiac recovery programs. Algorithmic diagnostic autonomy progression and EU MDR compliance cost trajectories serve as key forecast inputs across the projection horizon.
Forecasts assume regulatory continuity in FDA software-as-medical-device guidance and Medicare CPT code structures; material policy shifts would require re-modeling. Semiconductor supply concentration in Taiwanese fabrication and HIPAA security rule enforcement evolution represent specific revision triggers. Practitioners should keep alternative scenarios live as reimbursement granularity and cloud security certification requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market
Patient Monitoring
Europe Hemodynamic Monitoring Market
Patient Monitoring
Middle East and Africa Patient Monitoring Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
China ICU Patient Monitor Market
Patient Monitoring
Compartment Syndrome Monitoring Devices Market
Patient Monitoring
Middle-East and Africa Hemodynamic Monitoring Market
Patient Monitoring
Multi-Item Patient Monitor Market
Patient Monitoring
India Patient Monitoring Market
Patient Monitoring
South America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market
Patient Monitoring
MR Vital Sign Monitors Market
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
United States Cardiac Holter Monitor Market
Patient Monitoring
Respiratory Monitoring Market
Patient Monitoring
Global Patient Monitoring Market