
 Pediatric Chronic Rhinosinusitis Market | 2026-2036
Pediatric Chronic Rhinosinusitis Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Chronic Rhinosinusitis Market Analytics
Maintenance and monitoring service layers is rebalancing how pharmaceutical firms capture lifetime value from chronic pediatric therapies. Pfizer leverages its pediatric formulation expertise to sustain loyalty across multi-year treatment cycles. Novartis anchors its position through specialized biologic development for refractory cases. AstraZeneca competes on intranasal delivery innovation that reduces administration burden for caregivers.
Pediatric chronic rhinosinusitis denotes persistent sinonasal inflammation lasting beyond twelve weeks in patients under eighteen years, characterized by mucosal thickening, ostiomeatal complex obstruction, and biofilm formation that demands sustained therapeutic intervention. The condition serves commercial purpose by creating recurring pharmaceutical demand and procedural volumes in otolaryngology practices. Intranasal corticosteroids within the therapeutic approach dimension dominate current prescribing patterns due to established safety profiles in juvenile populations. The delivery mode category shows intranasal formats capturing disproportionate margin pools as device-drug combinations command premium positioning against generic oral alternatives.
FDA pediatric study requirements under PREA and BPCA direct manufacturer investment toward age-appropriate efficacy trials, while EMA's Paediatric Regulation mandates pediatric investigation plans before market authorization for new sinusitis therapies. These frameworks elevate development costs but simultaneously extend exclusivity periods and protect revenue streams for compliant sponsors. Stakeholders must track how real-world evidence requirements from these regulators reshape post-market study obligations and label expansion strategies.
Market Dynamics
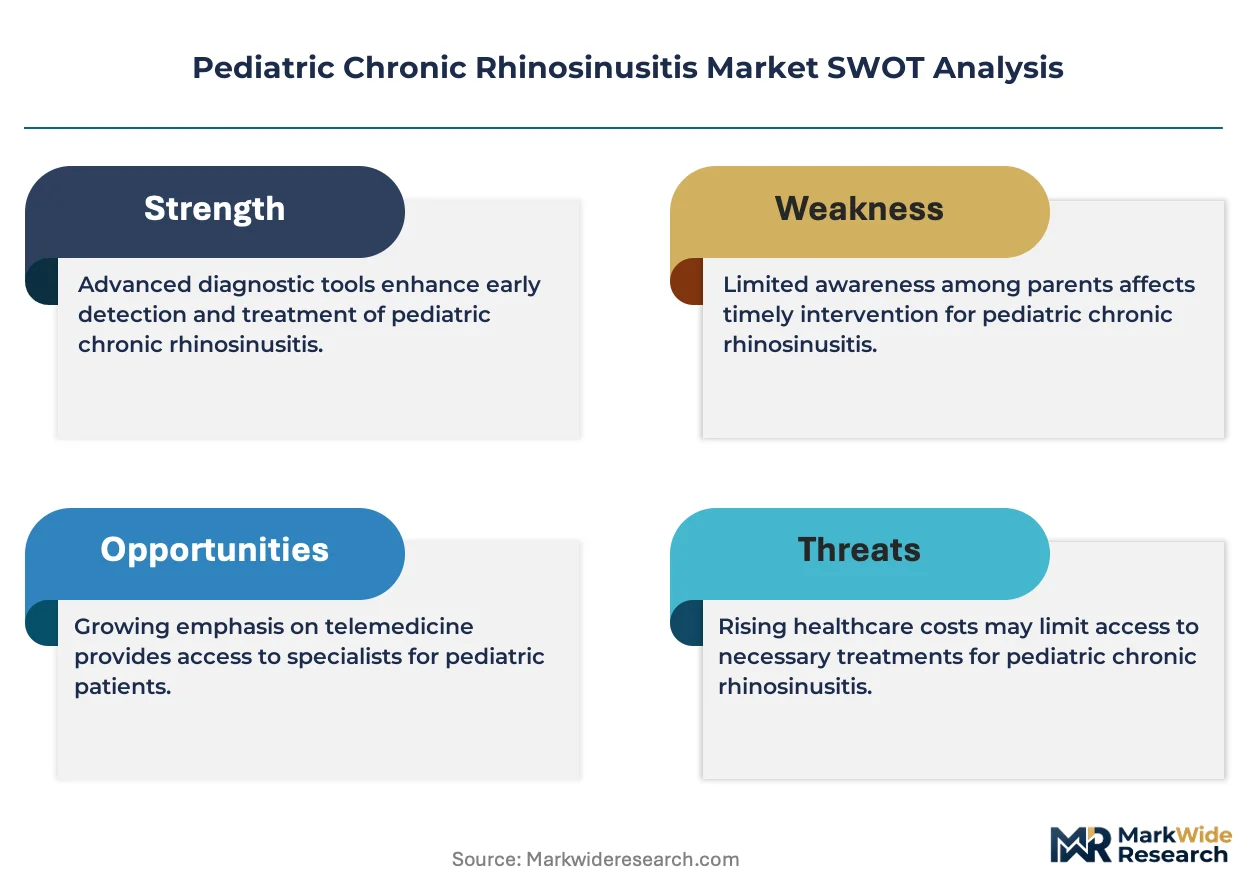
FDA pediatric exclusivity incentives and EMA orphan drug frameworks are redirecting clinical trial investment toward age-appropriate formulations, while intranasal device-drug combinations capture disproportionate margin pools against generic oral alternatives.
Growth Catalysts
- Pediatric ENT clinic expansion:Specialized otolaryngology practices in the United States and Germany are building dedicated pediatric sinusitis service lines that create recurring procedural volumes and pharmaceutical demand.
- PREA and BPCA frameworks:FDA pediatric study requirements extend exclusivity periods for compliant sponsors, protecting revenue streams and incentivizing development of juvenile-appropriate efficacy trials.
- Intranasal delivery innovation:Device-drug combination technologies reduce caregiver administration burden and command premium positioning in reimbursement pathways established across Japan and Germany.
Market Restraints
- Development cost escalation:Pediatric investigation plans mandated by EMA's Paediatric Regulation elevate trial expenses before market authorization for new sinusitis therapies.
- Biofilm persistence:Chronic mucosal colonization limits efficacy of standard intranasal corticosteroids, creating treatment resistance that compresses therapeutic response rates.
- Reimbursement fragmentation:Inconsistent coverage for biologic interventions across German statutory health insurance funds creates access barriers for refractory pediatric cases.
Strategic Opportunities
- Real-world evidence pathways:FDA and EMA post-market study requirements enable label expansion strategies based on pediatric registry data rather than de novo trials.
- Allergy center integration:Co-located rhinology and immunology services in United States academic medical centers create bundled intervention models for comorbid allergic rhinitis.
- Biologic refractory segments:Specialized development for cystic fibrosis-associated sinusitis opens orphan-designated pricing tiers under EMA frameworks.
Industry Challenges
- Pediatric trial recruitment:Age-stratified efficacy endpoints require extended enrollment timelines across juvenile cohorts, delaying readouts.
- Device-drug regulatory complexity:Combination product classification by FDA necessitates coordinated quality submissions spanning pharmaceutical and medical device divisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Chronic Rhinosinusitis Market |
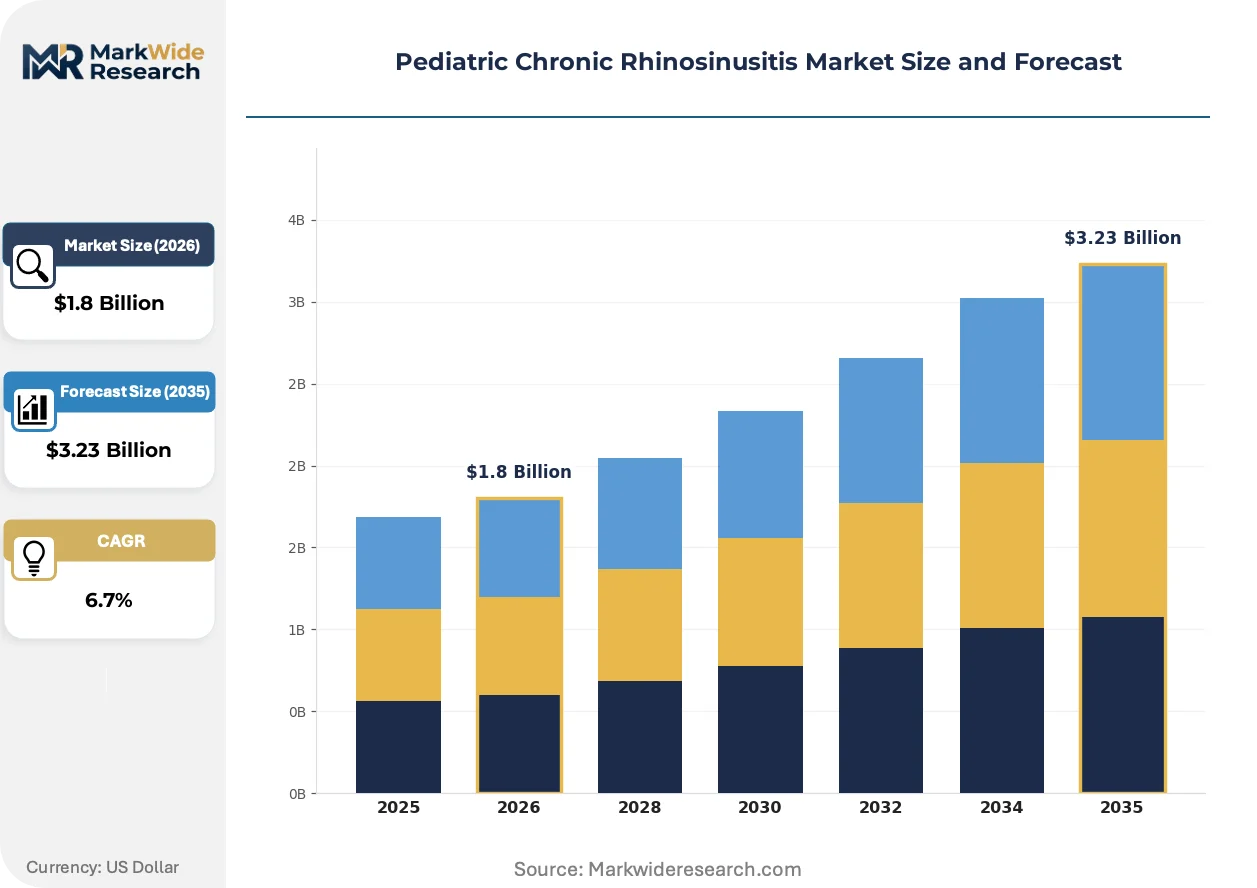
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication, Surgery, Lifestyle Changes, Immunotherapy Therapeutic Approach: Intranasal Corticosteroids, Antibiotics, Saline Irrigation, Antihistamines Delivery Mode: Oral, Intranasal, Injectable, Topical Patient Type: Infants, Toddlers, Young Children, Adolescents |
| Companies Covered | Pfizer, Bayer, Novartis, Sanofi, AstraZeneca, Teva Pharmaceutical, Sumitomo Dainippon Pharma, Cipla, Lyra Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Chronic Rhinosinusitis Market Evolving Landscape
Maintenance service layers and monitoring technologies are rebalancing how pharmaceutical firms capture lifetime value from chronic pediatric therapies, shifting competitive advantage toward adherence optimization and caregiver experience design.
Smart nebulizer systems with dose-tracking sensors are rewriting adherence monitoring in pediatric chronic rhinosinusitis management. Otolaryngology practices in the United States are piloting these devices for refractory cases requiring prolonged intranasal corticosteroid cycles. The technology is rewriting how pharmaceutical sponsors demonstrate real-world effectiveness to payers, compressing traditional reliance on episodic clinical endpoints.
EMA's evolving Paediatric Regulation enforcement is tightening pediatric investigation plan compliance timelines for new molecular entities targeting sinonasal inflammation. Manufacturers now face synchronized submissions across adult and juvenile development tracks, elevating portfolio planning complexity. Biologic developers targeting refractory pediatric cases are most affected, accelerating investment in age-appropriate pharmacokinetic modeling.
Caregiver-administered therapy monitoring is displacing clinic-dependent follow-up for stable pediatric patients. Digital symptom diaries and remote nasal endoscopy image sharing are replacing quarterly otolaryngology visits in Japanese and German reimbursement structures. This shift is most visible in allergy center networks where integrated electronic health records enable asynchronous specialist oversight.
Pediatric Chronic Rhinosinusitis Market Segmentation
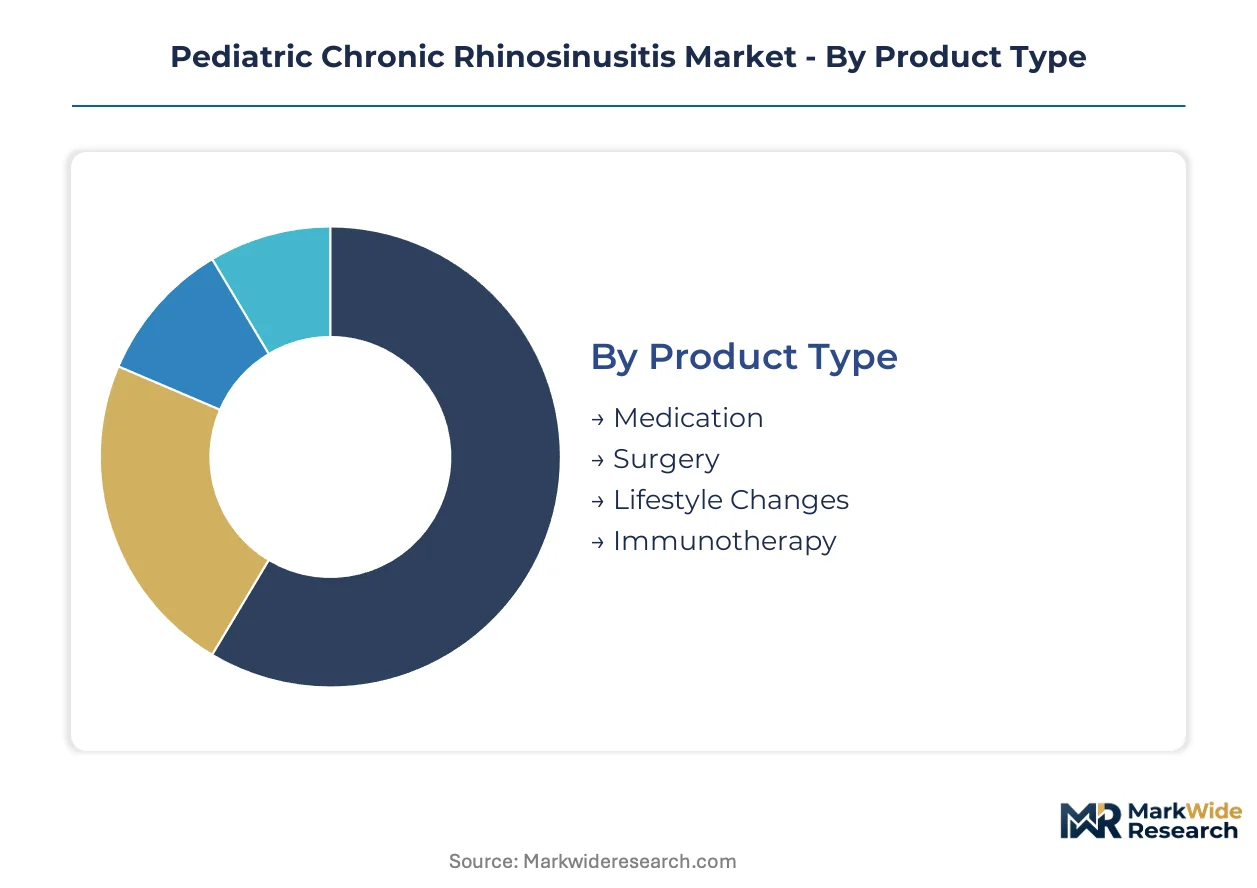
Pediatric chronic rhinosinusitis demands precise segmentation because treatment pathways diverge sharply by age-specific pharmacokinetics, biofilm burden, and caregiver administration capacity. Manufacturers must align formulation development with FDA PREA requirements and EMA pediatric investigation plans that vary across these divides.
Product Type:
FDA combination product classification and EMA orphan drug pathways impose distinct certification burdens: device-drug combinations face coordinated pharmaceutical and medical device division reviews, while biologic therapies trigger accelerated assessment frameworks for refractory cystic fibrosis-associated cases.
- Medication:Intranasal corticosteroids and antibiotic formulations dominate prescribing patterns due to established juvenile safety profiles. Demand concentrates in United States pediatric ENT clinics where maintenance therapy creates recurring pharmaceutical volumes.
- Surgery:Functional endoscopic sinus procedures address refractory cases with ostiomeatal complex obstruction. German statutory health insurance funds maintain established reimbursement pathways for pediatric otolaryngology interventions.
- Lifestyle Changes:Environmental modification protocols reduce allergen exposure in comorbid cases. Japanese allergy center networks integrate these protocols with digital symptom monitoring platforms.
- Immunotherapy:Sublingual and subcutaneous desensitization targets allergic rhinitis overlaps. EMA paediatric regulation compliance extends development timelines for age-appropriate dosing trials.
Leading the category by volume: Medication. Growing fastest: Immunotherapy.
Therapeutic Approach:
Cost tiers separate premium biologic interventions from standard-of-care pharmaceuticals, with intranasal corticosteroids occupying the mid-tier reimbursement band across Japanese and German health systems.
- Intranasal Corticosteroids:Fluticasone and mometasone formulations deliver targeted mucosal anti-inflammatory action with minimal systemic absorption. United States otolaryngology practices prescribe these as first-line maintenance for toddlers through adolescents.
- Antibiotics:Macrolide and beta-lactam courses target acute bacterial exacerbations. Biofilm persistence in pediatric sinuses limits efficacy and compresses therapeutic response rates.
- Saline Irrigation:Isotonic and hypertonic rinses provide mechanical biofilm disruption. Caregiver-administered protocols reduce clinic-dependent follow-up in stable patients.
- Antihistamines:Second-generation oral and intranasal formulations address allergic component overlaps. German allergy centers bundle these with corticosteroid protocols for comorbid presentations.
Intranasal corticosteroids capture the largest revenue share. Antibiotics face steepest pricing pressure from generic substitution.
Delivery Mode:
Application context determines device selection: acute exacerbations favor rapid-onset formats, while chronic maintenance prioritizes caregiver convenience and adherence monitoring integration.
- Oral:Liquid suspensions and chewable tablets accommodate infants and toddlers with undeveloped intranasal technique. United States pediatric formulations command premium positioning against generic alternatives.
- Intranasal:Metered-dose sprays and smart nebulizer systems deliver precise corticosteroid deposition. Japanese reimbursement pathways favor device-drug combinations with dose-tracking sensors.
- Injectable:Biologic monoclonal antibodies target refractory cases with cystic fibrosis or primary ciliary dyskinesia. EMA orphan frameworks enable designated pricing tiers.
- Topical:Antibiotic irrigations and compounded preparations address localized biofilm burden. Compounding pharmacy regulations vary across German federal states.
Intranasal formats dominate prescription volume. Injectable biologics expand most quickly in refractory segments.
Patient Type:
Development maturity separates established infant and toddler formulations from emerging adolescent protocols, with pharmacokinetic modeling gaps most pronounced in the youngest cohorts.
- Infants:Under 12 months present diagnostic ambiguity with viral upper respiratory infection overlap. FDA pediatric study requirements mandate dedicated efficacy trials for this vulnerable population.
- Toddlers:Ages 1-3 years require liquid formulations and caregiver-dependent administration. United States pediatric ENT clinics build specialized service lines for this high-utilization segment.
- Young Children:Ages 4-7 years achieve partial self-administration with device training. German kindergartens coordinate environmental modification protocols with regional allergy networks.
- Adolescents:Ages 12-17 years approach adult pharmacokinetics but retain distinct growth and compliance considerations. Japanese school-based health programs enable remote monitoring integration.
Toddlers generate the highest procedure volume. Adolescents show the steepest biologic therapy adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's pediatric otolaryngology corridor anchors North American demand for chronic sinusitis interventions, with Massachusetts General and Boston Children's Hospital driving protocol standardization that pharmaceutical sponsors reference in FDA submissions.
United States
Specialized pediatric ENT clinics in Philadelphia and Houston generate recurring procedural volumes and pharmaceutical demand. FDA PREA and BPCA frameworks extend exclusivity periods for compliant sponsors, protecting revenue streams. The Research Triangle Park cluster in North Carolina concentrates biologic development for refractory cystic fibrosis-associated cases.
Germany
Statutory health insurance funds in Bavaria and North Rhine-Westphalia maintain established reimbursement pathways for pediatric otolaryngology interventions. EMA's Paediatric Regulation mandates pediatric investigation plans before market authorization for new sinusitis therapies. The Heidelberg-Mannheim medical technology corridor advances intranasal device-drug combination manufacturing.
Japan
Allergy center networks in Tokyo and Osaka integrate digital symptom monitoring platforms with pharmaceutical maintenance protocols. METI reimbursement pathways favor device-drug combinations with dose-tracking sensors. The Kobe biomedical innovation cluster supports smart nebulizer system development for caregiver-administered therapy.
United Kingdom
Academic medical centers in London and Manchester create bundled intervention models for comorbid allergic rhinitis and chronic rhinosinusitis. MHRA alignment with EMA pediatric frameworks streamlines investigation plan submissions. The Cambridge-Oxford life sciences arc attracts biologic development for primary ciliary dyskinesia-associated refractory cases.
India
Pediatric ENT service lines in Mumbai and Delhi generate volume demand for intranasal corticosteroid formulations. CDSCO pediatric study requirements elevate development costs but extend market exclusivity for compliant domestic sponsors. The Hyderabad pharmaceutical manufacturing belt produces age-appropriate liquid suspensions for toddler segments.
Pediatric Chronic Rhinosinusitis Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the pediatric chronic rhinosinusitis landscape, with integrated pharmaceutical-device developers holding manufacturing depth against specialized biotech licensors. The market structure concentrates around three strategic tiers: multinational incumbents with pediatric formulation expertise, mid-cap biologic specialists targeting refractory segments, and regional generic manufacturers serving volume markets. Dominant competitive moves include vertical integration into intranasal delivery device production and strategic partnerships with academic medical centers for real-world evidence generation.
Among multinational incumbents, Pfizer and Novartis exemplify contrasting archetypes: the former leverages established pediatric formulation portfolios across multi-year treatment cycles, while the latter anchors position through specialized biologic development. AstraZeneca occupies a distinct tier focused on intranasal delivery innovation that reduces caregiver administration burden. These three entities collectively represent the competitive spectrum spanning maintenance therapy optimization, refractory case intervention, and administration experience design.
| Leading Market Players |
|---|
| Pfizer |
| Bayer |
| Novartis |
| Sanofi |
| AstraZeneca |
| Teva Pharmaceutical |
| Sumitomo Dainippon Pharma |
| Cipla |
| Lyra Therapeutics |
| Others |
Value Network & Pricing Analysis
Device-drug combination certification tiers bifurcate pediatric chronic rhinosinusitis supply economics, with FDA combination product pathways and EMA orphan designations creating divergent cost structures that concentrate premium manufacturing in Germany and Japan while generic formulation production anchors in India.
Pricing Analysis
Margin tightening in intranasal corticosteroid tiers reflects generic substitution pressure from Indian manufacturers. Three-tier pricing structure across premium device-drug combinations, standard metered-dose sprays, and economy oral suspensions dominates contracting. Pricing pressure stems from biofilm-resistant biologic development costs. Pediatric ENT clinics show lowest price sensitivity; retail pharmacy channels face highest substitution elasticity.
Supply Chain Analysis
Direct-to-hospital channels handle biologic demand from academic medical centers in the United States and United Kingdom. Active pharmaceutical ingredient sourcing concentrates in India and China, with device component manufacturing anchored in Germany and Japan. Supply chain risk centers on single-source dependency for pediatric-specific nebulizer sensors. Distribution runs through specialty pharmacy networks for maintenance therapy protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric chronic rhinosinusitis operates as a cost-of-compliance market where FDA PREA and EMA Paediatric Regulation requirements erect substantial barrier-to-entry moats favoring sponsors with established juvenile trial infrastructure.
For Market Incumbents: Deepen backward integration into smart nebulizer device production to capture margin pools from sensor-enabled adherence monitoring. Fortify positions against mid-cap biologic specialists by accelerating real-world evidence generation through academic medical center partnerships in Boston and Philadelphia. Prioritize EMA pediatric investigation plan synchronization across adult and juvenile development tracks. For New Entrants and Emerging Players: Enter via cystic fibrosis-associated refractory segments where EMA orphan frameworks enable designated pricing tiers with reduced competitive density. Target Japanese allergy center networks with device-drug combinations featuring METI-favored dose-tracking sensors. Deploy caregiver experience design as primary go-to-market differentiation against established intranasal corticosteroid incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with specialized biologic developers possessing age-appropriate pharmacokinetic modeling capabilities given EMA enforcement tightening on pediatric investigation plan timelines. Long-term viability favors sponsors with integrated formulation-device portfolios spanning multi-year treatment cycles. Monitor FDA post-market study requirement expansions as inflection indicator for real-world evidence infrastructure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Investigation Plan Synchronization | EMA compliance accelerates market authorization timelines across juvenile and adult cohorts simultaneously. |
| Smart Nebulizer Device Integration | Sensor-enabled adherence monitoring commands premium reimbursement positioning in Japanese METI pathways. |
| Real-World Evidence Registry Development | FDA post-market requirements enable label expansion without de novo pediatric trial investments. |
| Orphan Drug Designation Pursuit | EMA frameworks unlock designated pricing tiers for cystic fibrosis-associated refractory indications. |
| Academic Medical Center Partnership | Boston and Philadelphia clusters generate protocol standardization referenced in regulatory submissions. |
Research Methodology
Document review covered FDA PREA filings, EMA pediatric investigation plans, ClinicalTrials.gov registries, and Japanese METI reimbursement databases, complemented by interviews with pediatric otolaryngologists, regulatory affairs directors at pharmaceutical sponsors, formulary access specialists, and allergy center procurement managers. Bottom-up prescription volume modeling triangulated against top-down market size estimates from national health expenditure data.
Segment-level outputs across medication, surgery, lifestyle modification, and immunotherapy categories were generated through the analysis window, with patient age stratification and delivery mode preferences as core dimensions. CAGRs derived from historical procedure volumes in United States pediatric ENT clinics and pharmaceutical sales data from German statutory health insurance funds. Forecast inputs incorporated FDA exclusivity incentive utilization rates and EMA orphan designation approval velocities.
Revisions become necessary when regulatory enforcement timelines shift, biofilm-resistant therapeutic candidates demonstrate unexpected efficacy, or reimbursement pathways fragment across German federal states. Forecasts reflect documented assumptions regarding pediatric trial recruitment feasibility and caregiver adherence technology adoption curves. Practitioners should monitor FDA real-world evidence guidance evolution and EMA Paediatric Regulation enforcement patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Paediatric Influenza Treatment Market
Pediatrics
Paediatric Spasticity Treatment Market
Pediatrics
Middle East and Africa Pediatric Healthcare Market
Pediatrics
Global Pediatric Home Healthcare Services Market
Pediatrics
Pediatric Palliative Care Drugs Market
Pediatrics
Pediatric Dental Market
Pediatrics
Pediatric Craniosynostosis Treatment Market
Pediatrics
Pediatrics Medicine Market
Pediatrics
Global Pediatric Clinical Trials Market
Pediatrics
Pediatric Mattress Market
Pediatrics
OTC Pediatric Healthcare Market
Pediatrics
Global Cerebral Palsy Treatment Market
Pediatrics
Global Pediatric Radiology Market
Pediatrics
Pediatric HIV Infection Treatment Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
Pediatric Obesity Management Market