
 Power Smart Bed Market | 2026-2036
Power Smart Bed Market Size, Share, and Industry Trends Forecast 2026-2036
Power Smart Bed Market Insights
Embedded systems engineering talent scarcity is unwinding production timelines for advanced power smart beds, forcing manufacturers to recalibrate workforce pipelines. Stryker Corporation leverages its vertical integration into hospital capital equipment to sustain dominant channel access. Sleep Number Corporation differentiates through consumer-direct positioning and proprietary adjustable firmness technology. Paramount Bed Co., Ltd. anchors its competitive stance with specialized distribution across Japanese healthcare networks.
A power smart bed integrates electromechanical actuators, sensor arrays, and connectivity modules to enable automated position adjustment, sleep monitoring, and therapeutic interventions for residential and clinical users. Adjustable beds command the largest installed base while smart mattresses capture the fastest expansion as consumers prioritize embedded biometric tracking over passive furniture. IoT integration and sleep tracking technologies concentrate margin pools in firmware and data services rather than commodity frame production. Residential and hospital end users diverge sharply in procurement logic, with the former seeking wellness augmentation and the latter demanding fall prevention and pressure injury protocols.
FDA medical device cybersecurity guidance and FCC wireless equipment certification shape product development roadmaps for connected sleep systems in the United States. The EU MDR and CE marking framework impose clinical evidence requirements on therapeutic claims, filtering market access for non-European manufacturers. Japan's PMDA and METI coordinate standards for elderly care equipment, accelerating domestic adoption of sensor-embedded beds. Stakeholders must monitor regulatory divergence across these three jurisdictions when allocating R&D budgets and localization investments.
Market Dynamics
Embedded sensor miniaturization and FDA cybersecurity mandates are compressing development cycles while fragmenting vendor tiers between compliant incumbents and firmware-limited challengers.
Growth Catalysts
- Pressure injury protocols:Hospital reimbursement penalties for Stage III-IV pressure ulcers are accelerating procurement of automated repositioning beds in acute care wards.
- REACH material compliance:EU RoHS exemptions for medical electronics are tightening, pushing frame manufacturers toward recyclable aluminum alloys and bio-based foams.
- Actuator cost curves:Brushless DC motor production scaling in East Asian manufacturing clusters is reducing electromechanical component costs for mid-tier bed producers.
Market Restraints
- Rare earth magnet volatility:Neodymium price swings tied to Chinese export quotas are destabilizing actuator motor cost forecasting for European bed assemblers.
- Embedded firmware liability:Product liability insurers are excluding cyber-physical system failures from general liability coverage, forcing separate IoT risk policies.
- Legacy hospital infrastructure:2.4 GHz Wi-Fi saturation in aging US medical facilities is degrading real-time biometric transmission reliability.
Strategic Opportunities
- Home health pivot:Post-acute discharge acceleration in Germany is creating demand for rental-to-own smart bed models with remote nursing dashboards.
- CE-MDR clinical data gaps:Non-European manufacturers lacking PMCF studies face delayed market entry, creating acquisition targets for EU-registered competitors.
- Sleep-mattress convergence:Biometric tracking fabrics are miniaturizing, enabling sensor integration into standard mattress toppers without frame replacement.
Industry Challenges
- Firmware engineering scarcity:Real-time operating system developers with IEC 62304 medical software experience command premium compensation, stretching R&D budgets.
- Multi-jurisdiction certification:Simultaneous FDA 510(k), CE-MDR, and PMDA filings require redundant clinical testing protocols, extending time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Smart Bed Market |
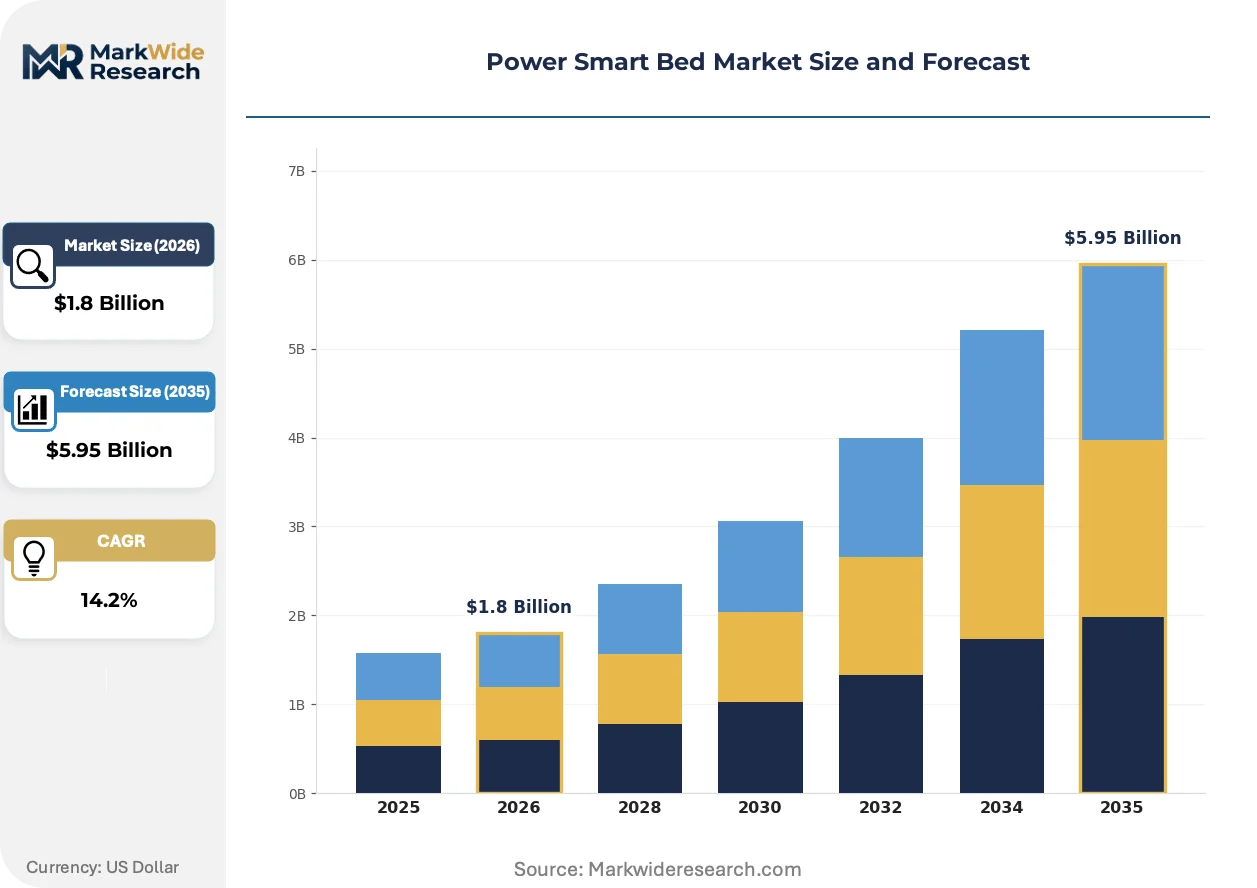
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adjustable Beds, Smart Mattresses, Bed Accessories, Bed Frames Technology: IoT Integration, Sleep Tracking, Remote Control, Adjustable Firmness End User: Residential, Hospitals, Senior Care Facilities, Hotels Feature: Temperature Regulation, Position Adjustment, Massage Function, Connectivity |
| Companies Covered | Stryker Corporation, Hill-Rom Holdings Inc., Invacare Corporation, Paramount Bed Co., Ltd., LINET Group SE, Joerns Healthcare, Getinge Group, Arjo AB, Sleep Number Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Smart Bed Market Trends and Innovations
Biometric sensing, regulatory cybersecurity hardening, and procurement model fragmentation are simultaneously elevating technical barriers and compressing margin structures across vendor tiers.
Capacitive pressure mapping arrays are miniaturizing from discrete sensor grids to woven textile substrates. Japanese senior care operators are piloting mattress-integrated systems that eliminate rigid frame electronics. This convergence is miniaturizing the distinction between adjustable beds and passive sleep surfaces, forcing frame manufacturers to defend value through actuator performance rather than sensor exclusivity.
FDA's premarket cybersecurity guidance for networked medical devices is mandating SBOM documentation and encrypted over-the-air update architectures. Device manufacturers must now embed hardware security modules and incident response protocols into firmware roadmaps. Hospital procurement committees in the United States are prioritizing vendors with documented FDA cyber consultations, filtering out smaller competitors lacking regulatory affairs capacity.
Acute care buyers are unbundling sleep surface procurement from capital equipment leases, treating mattresses as consumable inventory with 18-24 month replacement cycles. Group purchasing organizations are consolidating sensor-embedded bed contracts into multi-hospital frameworks that privilege scale over feature differentiation. This pattern is most pronounced in US health systems pursuing standardized fall-prevention protocols across affiliated nursing units.
Power Smart Bed Market Segmentation
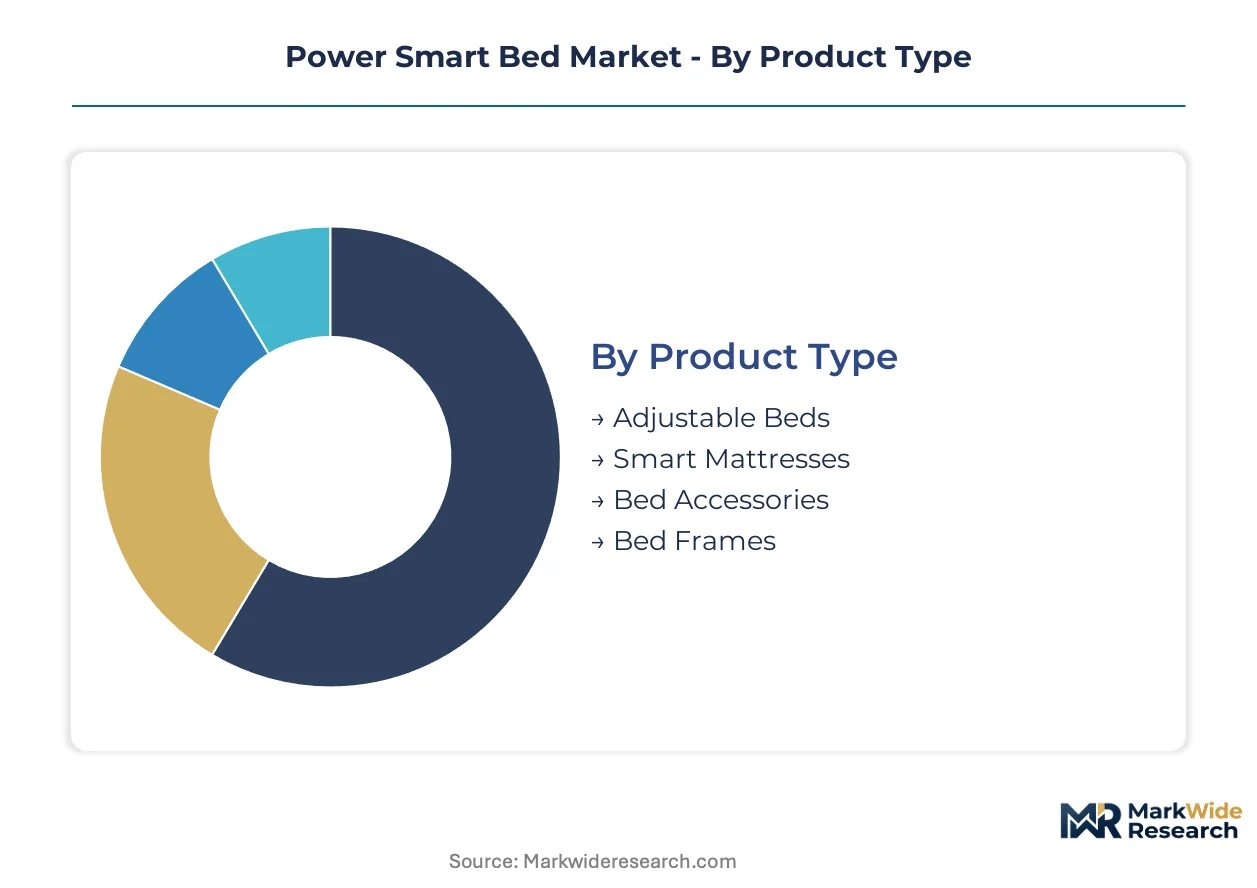
Channel economics in the power smart bed market diverge sharply between clinical procurement and consumer retail. Understanding segment-channel alignment reveals where margin pools concentrate and which technologies justify premium positioning.
Product Type:
Adjustable beds and smart mattresses flow through distinct channel architectures, with the former dominating hospital capital equipment tenders and the latter penetrating direct-to-consumer wellness platforms.
- Adjustable Beds:Electromechanical frames with motorized actuators enable automated position adjustment for pressure relief and respiratory support. Hospital procurement committees in the United States prioritize these systems for fall-prevention protocols, while German senior care facilities accelerate replacement cycles under clarified reimbursement frameworks.
- Smart Mattresses:Embedded sensor arrays and biometric tracking fabrics monitor sleep stages, heart rate variability, and respiratory patterns without rigid frame electronics. Consumer-direct channels in wellness-focused demographics are absorbing volume as miniaturized textile substrates displace discrete sensor grids.
- Bed Accessories:Add-on components including sensor toppers, remote modules, and connectivity bridges extend legacy bed functionality.
- Bed Frames:Structural platforms with minimal electromechanical integration serve price-sensitive residential segments and hospitality refurbishment cycles.
Adjustable beds dominate installed base. Smart mattresses are where expansion concentrates.
Technology:
Technology tiers stratify by certification burden, with FDA-cleared firmware commanding hospital premiums and consumer-facing features competing on algorithm sophistication.
- IoT Integration:Networked connectivity modules enable remote monitoring, over-the-air updates, and integration with hospital information systems. FCC wireless certification and FDA cybersecurity guidance are filtering vendor participation in US clinical channels, concentrating supply among firms with documented regulatory affairs capacity.
- Sleep Tracking:Biometric algorithms process accelerometer, pressure, and capacitive signals into sleep quality metrics. Wellness platforms in residential segments are absorbing these capabilities fastest as consumers prioritize embedded health monitoring over passive furniture.
- Remote Control:Wireless handsets and smartphone applications manage position and feature activation.
- Adjustable Firmness:Air chamber or mechanical systems modify surface support levels based on user preference or automated feedback loops.
IoT integration captures the steepest margin premiums in clinical procurement. Sleep tracking is climbing the fastest in consumer-direct channels.
End User:
End-user segments diverge in procurement logic, with hospitals demanding incident response protocols and residential buyers prioritizing wellness augmentation.
- Residential:Individual consumers purchase through retail, e-commerce, and direct-to-consumer platforms for sleep quality improvement and aging-in-place preparation. Post-acute discharge acceleration in Germany is creating rental-to-own demand with remote nursing dashboards.
- Hospitals:Acute care wards procure through capital equipment leases and group purchasing organization frameworks. US health systems are unbundling sleep surfaces from frame contracts, treating mattresses as consumable inventory with compressed replacement cycles.
- Senior Care Facilities:Long-term care operators in Japan are piloting textile-integrated sensor systems to eliminate rigid frame electronics in elderly care environments.
- Hotels:Hospitality chains deploy adjustable bases and connectivity features as wellness amenities in premium room categories.
Hospital procurement commands the highest average selling prices. Residential volume is expanding most quickly as biometric tracking democratizes.
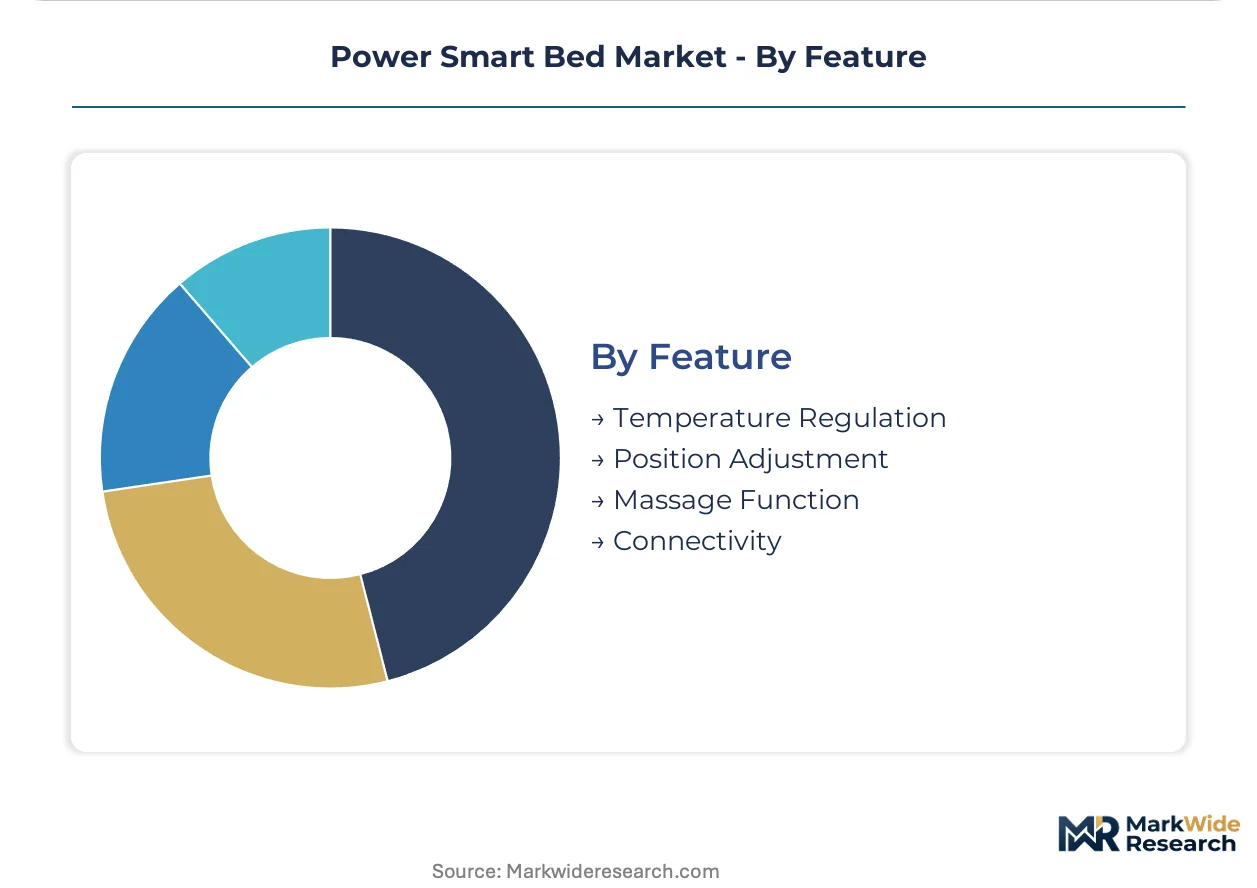
Feature:
Feature bundling reflects reimbursement logic, with clinical buyers prioritizing therapeutic outcomes and hospitality operators emphasizing guest experience differentiation.
- Temperature Regulation:Active heating and cooling systems manage microclimate for sleep quality and pressure injury prevention. US hospital reimbursement penalties for Stage III-IV pressure ulcers are accelerating automated thermal management adoption in acute care.
- Position Adjustment:Motorized articulation of head, foot, and height parameters supports respiratory therapy, circulation, and egress safety. German senior care facilities are standardizing these capabilities across replacement cycles.
- Massage Function:Vibration motors deliver therapeutic or relaxation protocols through programmable intensity patterns.
- Connectivity:Integration with smart home ecosystems, telehealth platforms, and nurse call systems enables data transmission and remote intervention.
Position adjustment anchors clinical procurement specifications. Temperature regulation is gaining share fastest as pressure injury protocols tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cybersecurity mandates are anchoring North American procurement specifications while PMDA-METI coordination accelerates Japanese adoption and EU MDR clinical evidence requirements filter non-European market access.
United States
Hospital reimbursement penalties for Stage III-IV pressure ulcers and post-acute discharge acceleration are driving automated repositioning bed procurement. FDA premarket cybersecurity guidance mandates SBOM documentation and encrypted over-the-air architectures for networked medical devices. Boston and Minneapolis medical device clusters concentrate firmware engineering talent for IEC 62304-compliant development.
Germany
Aging demographics and clarified reimbursement frameworks for senior care equipment are compressing replacement cycles in long-term care facilities. EU MDR clinical evidence requirements on therapeutic claims filter market access for manufacturers lacking PMCF studies. The Baden-Württemberg industrial corridor hosts precision actuator manufacturers supplying brushless DC motor assemblies.
Japan
Domestic adoption of sensor-embedded beds for elderly care environments is accelerating under coordinated PMDA-METI standards. METI elderly care equipment certification programs reduce regulatory friction for domestic manufacturers. Tokyo and Osaka healthcare networks pilot textile-integrated sensor systems eliminating rigid frame electronics.
China
Brushless DC motor production scaling in East Asian manufacturing clusters is reducing electromechanical component costs for mid-tier bed producers. NMPA medical device registration requirements and MIIT IoT security standards shape product development for connected sleep systems. The Yangtze River Delta concentrates actuator motor assembly capacity serving both domestic and export markets.
United Kingdom
Post-acute care restructuring and NHS procurement consolidation are shifting sleep surface procurement toward standardized fall-prevention protocols. MHRA alignment with EU MDR transitional provisions maintains clinical evidence requirements for therapeutic claims. The Southeast England medical technology corridor hosts firmware development operations serving European market access.
Power Smart Bed Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hospital capital equipment lessors and consumer-direct wellness platforms occupying distinct competitive vectors. The structure stratifies between FDA-cleared clinical vendors and firmware-limited residential challengers. Dominant archetypes include vertically integrated hospital equipment conglomerates, consumer biometric technology specialists, and regional healthcare fabricators with captive distribution. Competitive moves concentrate on M&A to secure regulatory affairs capacity and strategic partnerships to bridge firmware engineering gaps.
Within the integrated hospital equipment tier, Stryker Corporation and Hill-Rom Holdings Inc. exemplify scale-driven positioning through captive channel access and vertical control over capital equipment leasing networks. Sleep Number Corporation anchors the consumer-direct vector with proprietary adjustable firmness technology and wellness platform positioning. Paramount Bed Co., Ltd. occupies a specialized position within Japanese healthcare networks, representing the regional fabricator archetype with domestic distribution concentration.
| Leading Market Players |
|---|
| Stryker Corporation |
| Hill-Rom Holdings Inc. |
| Invacare Corporation |
| Paramount Bed Co., Ltd. |
| LINET Group SE |
| Joerns Healthcare |
| Getinge Group |
| Arjo AB |
| Sleep Number Corporation |
| Others |
Pricing and Supply Chain Analysis
Brushless DC motor substitution for brushed actuator systems is simultaneously shifting procurement geography toward East Asian manufacturing clusters and compressing electromechanical component premiums for mid-tier bed assemblers. This input transition enables frame manufacturers to defend margin structures while sensor-embedded mattresses capture firmware value pools.
Pricing Analysis
Price spreads between German acute care procurement and US consumer-direct channels exceed threefold for comparable frame specifications. Three-tier pricing structure across FDA-cleared clinical, CE-marked therapeutic, and residential wellness tiers reflects certification burden divergence. Pricing pressure stems from brushless DC motor cost compression in Chinese manufacturing zones. Residential wellness buyers exhibit highest price sensitivity; hospital GPOs prioritize cyber-hardened firmware over unit economics.
Supply Chain Analysis
Rare earth magnet processing chokepoints in Chinese export quota regimes tether actuator motor cost forecasting to geopolitical supply management. Component sourcing draws from China, South Korea, and Germany for precision motors, sensor substrates, and aluminum frame alloys. Neodymium price volatility constitutes the dominant structural risk. Distribution runs through hospital capital equipment lessors, consumer-direct wellness platforms, and senior care facility procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margin compression is accelerating service-attach economics, with remote nursing dashboards and over-the-air firmware subscriptions expanding faster than frame replacement cycles. Recurring revenue layers now justify customer acquisition premiums previously reserved for capital equipment.
For Market Incumbents: Compound channel control through captive hospital leasing networks and backward integration into brushless DC motor assemblies. Firmware engineering scarcity threatens margin structures; secure IEC 62304-compliant development capacity through targeted talent acquisition in Boston and Minneapolis medical device clusters.
For New Entrants and Emerging Players: Differentiate on textile-integrated biometric substrates that eliminate rigid frame electronics in Japanese senior care pilot programs. Target German post-acute rental-to-own models with remote monitoring attach rates. Pursue direct-to-consumer wellness positioning with algorithm-driven sleep coaching subscriptions.
For Investors and Strategic Acquirers: The market sits at a regulatory-hardening phase that favors EU-registered manufacturers with documented PMCF studies. Five-to-ten year viability hinges on cyber-physical system liability coverage and FDA cyber consultation documentation. Monitor PMDA-METI coordination on elderly care equipment standards as inflection indicator for Asia-Pacific adoption acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Consultation | Hospital procurement committees filter vendor pools based on documented SBOM and encrypted OTA architectures. |
| CE-MDR Clinical Evidence Investment | PMCF study completion enables market access for therapeutic claims in German senior care reimbursement frameworks. |
| Hospital System Partnership | GPO contract consolidation privileges scale vendors with standardized fall-prevention protocol deployment. |
| Software Companion Development | Remote nursing dashboards transform capital equipment into recurring revenue platforms for post-acute discharge. |
| Reimbursement Strategy | Pressure injury protocol alignment with US Medicare penalty structures accelerates automated repositioning bed procurement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across hospital purchasing committees, biomedical engineers, GPO contracts managers, and senior care facility procurement directors. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, CMS Medicare reimbursement databases, and hospital capital equipment lease records. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Across the analysis window, projections modeled product type segmentation, technology certification tiers, end-user procurement logic, and regional regulatory divergence. CAGRs derived from historical replacement cycle analysis and reimbursement trajectory assessment. Forecast inputs incorporated actuator cost curve trajectories and firmware engineering wage inflation patterns.
The analysis sits within stated boundaries; outcomes outside FDA cyber guidance enforcement intensity or rare earth export quota stability would require recalibration. Practitioners should keep alternative scenarios live as EU MDR transitional provisions and PMDA-METI coordination frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Veress Needle Market
Medical Devices
Neurodiagnostic and Monitoring Devices Market
Medical Devices
Global Operating Microscopes Market
Medical Devices
Steerable Needles Market
Medical Devices
Europe Insulin Pumps Market
Medical Devices
Veterinary Ultrasound Scanners Market
Medical Devices
Medical Mobility Aid Market
Medical Devices
Indonesia Devices Market
Medical Devices
Tourniquet Systems Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
US External Counterpulsation Devices Market
Medical Devices
APAC Ablation Devices Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Veterinary X-Ray Illuminators Market
Medical Devices
Global on-Body Injectors Market
Medical Devices
Global MRI Safe Cardiac Resynchronization Therapy Device Market