
 Orthodontic Headgear Market | 2026-2036
Orthodontic Headgear Market Size, Share, and Industry Trends Forecast 2026-2036
Orthodontic Headgear Market Outlook
Market Context
EU MDR compliance pressure is consolidating purchasing criteria around biocompatible materials and traceable supply chains for orthodontic headgear. G&H Orthodontics leverages its vertically integrated manufacturing to sustain cost advantages across metal and elastic component lines. 3M anchors premium positioning through proprietary adhesive and bonding technologies integrated into its headgear systems. Dentsply Sirona differentiates via digital workflow compatibility, connecting headgear prescriptions to intraoral scanning platforms.
Technical Definition and Segment Structure
Orthodontic headgear is an extraoral appliance comprising a facebow, neck strap or head cap, and elastic or spring force modules, typically delivering 150–350 grams of distalizing or restraining force to modify maxillary growth or anchor molar position. Its primary purpose is to correct Class II malocclusions, distalize maxillary molars, or reinforce anchorage during fixed appliance therapy in growing patients. Fixed headgear dominates volume due to treatment reliability in pediatric cases, while removable variants represent the fastest-growing category as patient compliance monitoring improves through smart strap sensors. Metal facebows retain the largest margin pool given alloy customization and durability requirements, though composite and elastic materials gain share where aesthetics and comfort drive parental selection.
Regulatory Frame and Outlook
FDA 510(k) clearance requirements, EU MDR Class IIa designation, and ISO 13485 quality management standards collectively elevate barriers for new orthodontic headgear entrants while accelerating incumbent investment in biocompatibility documentation. Japan's PMDA and China's NMPA impose additional material testing protocols that shape regional product configurations and registration timelines. Stakeholders must monitor evolving FDA guidance on patient-specific orthodontic devices and EU notified body capacity constraints that could delay market access for modified headgear designs.
Market Dynamics
EU MDR biocompatibility documentation requirements are forcing orthodontic headgear manufacturers to consolidate supply chains around certified polymer and alloy suppliers, compressing margins for mid-tier producers while elevating compliance costs across the value chain.
Growth Catalysts
- Pediatric Early Intervention Protocols:North American orthodontic associations now recommend Class II correction initiation at age 7–9, expanding addressable patient pools for cervical and high-pull headgear configurations.
- Smart Compliance Monitoring:Bluetooth-enabled force sensors embedded in neck straps transmit real-time wear-time data to orthodontist dashboards, improving treatment adherence and justifying premium pricing for connected systems.
- Japan PMDA Streamlined Registration:Reduced documentation timelines for Class IIa orthodontic devices accelerate product refresh cycles and incentivize iterative design improvements for Japanese manufacturers.
Market Restraints
- Nickel-Titanium Alloy Concentration:Specialty shape-memory wire production concentrates in a limited supplier base, exposing headgear facebow manufacturers to input volatility and qualification bottlenecks.
- Clear Aligner Substitution:Invisalign and competing transparent orthodontic systems capture mild-to-moderate Class II cases previously defaulting to headgear, narrowing the appliance's addressable indication range.
- EU Notified Body Capacity:MDR transition has reduced the pool of accredited conformity assessment bodies, extending headgear recertification timelines and freezing product modifications in European markets.
Strategic Opportunities
- Brazil ANVISA Expansion:Underpenetrated orthodontic infrastructure in São Paulo and Rio de Janeiro states creates whitespace for mid-priced headgear systems as private insurance coverage broadens.
- Digital Workflow Integration:Convergence of intraoral scanning with 3D-printed headgear components enables patient-specific facebow geometry, differentiating premium offerings from standardized catalogs.
- Direct-to-Practice E-Commerce:Specialized orthodontic supply platforms bypass traditional distributor markups, capturing margin compression value for manufacturers with established brand recognition.
Industry Challenges
- Biocompatibility Testing Expertise:ISO 10993 cytotoxicity and sensitization study execution requires specialized toxicology partnerships that smaller manufacturers struggle to secure at viable cost structures.
- Legacy Practice Management Integration:Smart headgear data streams must interface with entrenched orthodontic software ecosystems, creating API development burdens and customer onboarding friction.
Report Scope
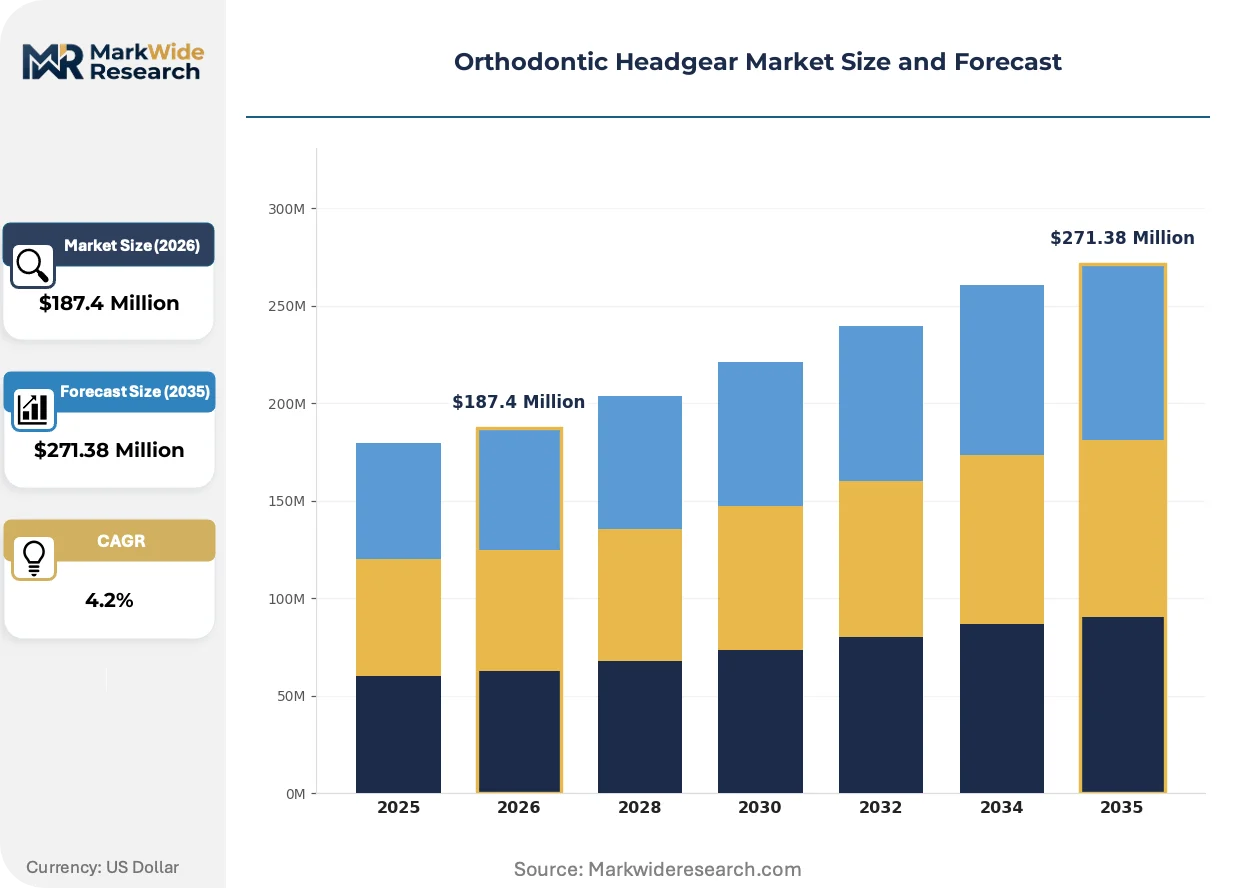
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthodontic Headgear Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Removable, Functional, Orthopedic Material: Metal, Plastic, Elastic, Composite End User: Pediatric Clinics, Dental Hospitals, Orthodontists, Private Practices Distribution Channel: Online Stores, Dental Supply Distributors, Clinics, Retail Pharmacies |
| Companies Covered | DB Orthodontics, G&H Orthodontics, 3M, American Orthodontics, Rocky Mountain Orthodontics, Ortho Kinetics Corporation, Dentsply Sirona, Great Lakes Dental Technologies, Ormco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthodontic Headgear Market Strategic Shifts
Orthodontic headgear is undergoing functional reinvention as digital dentistry infrastructure matures, with sensor integration and materials science advancing in parallel rather than sequentially.
Force-sensing elastomer modules are decentralizing treatment monitoring responsibility from periodic chairside visits to continuous remote data capture. Pediatric orthodontic practices in Germany and the United States are piloting these systems at 15–20% patient volume. The technology is decentralizing clinical oversight, compressing the traditional six-week adjustment cycle and enabling asynchronous orthodontist-patient communication.
EU MDR Annex I general safety and performance requirements now mandate clinical evidence for headgear claiming patient-specific fit, even for Class IIa devices previously cleared through equivalence. Manufacturers must commission prospective studies or systematic literature reviews to support modified designs. Small and mid-sized European producers are responding by withdrawing marginal SKUs and concentrating resources on flagship configurations with defensible clinical dossiers.
Parental purchasing influence is reshaping headgear specification criteria beyond clinical efficacy alone. Aesthetic considerations—low-visibility straps, skin-tone matching, and minimized facial protrusion—now dominate initial consultations in suburban United States practices. Digital-native millennial parents research appliance options via social media peer networks before orthodontist appointments, elevating brand awareness and online review visibility as competitive determinants.
Orthodontic Headgear Market Segmentation
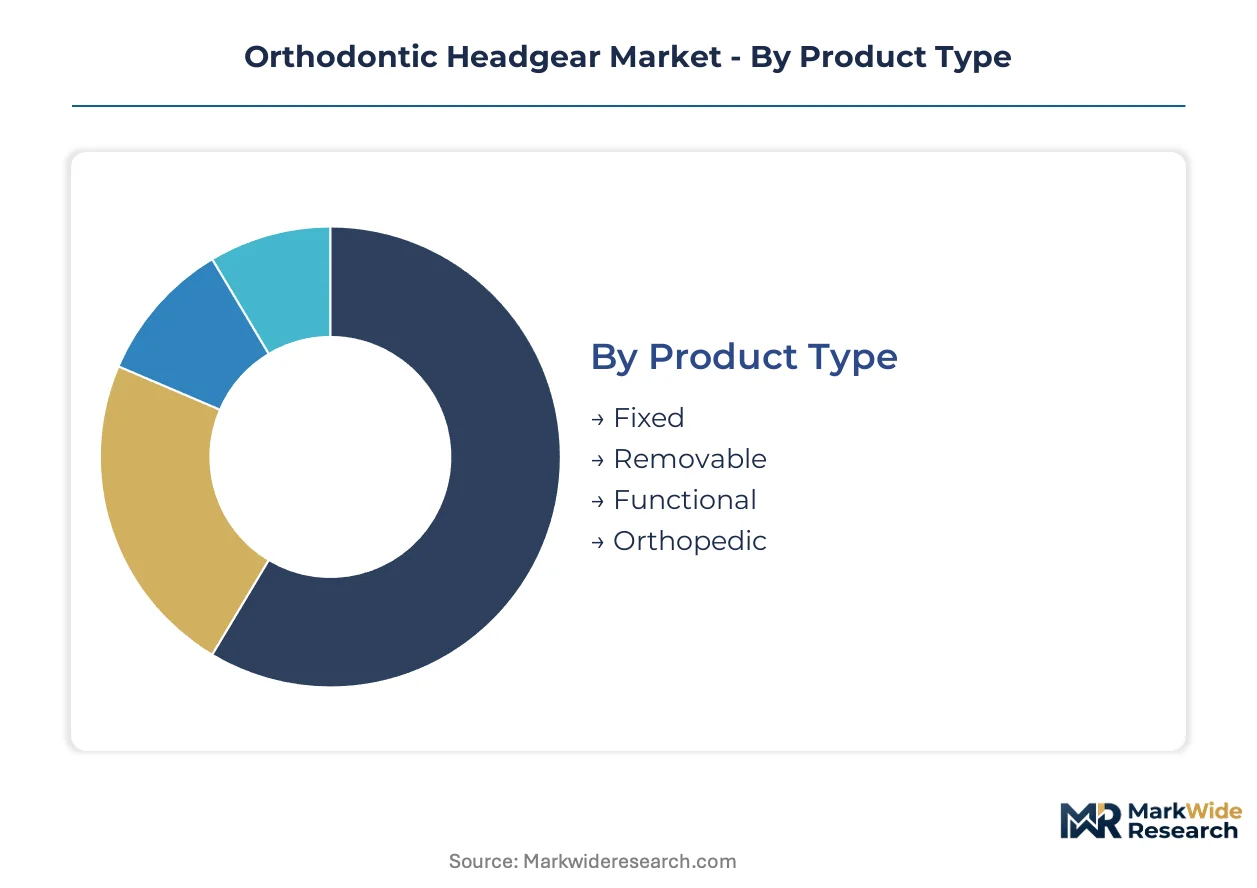
Orthodontic headgear segmentation reveals how technical specifications, material choices, and channel economics fragment purchasing decisions across pediatric and adolescent treatment pathways. Manufacturers align product portfolios against these axes to capture volume in high-throughput clinic networks while defending margin in customized applications.
Product Type:
Attachment mechanism and force delivery architecture distinguish commercial positioning across orthodontic practice workflows.
- Fixed:Permanently bonded or cemented appliances delivering continuous force through facebow-neck strap assemblies. Pediatric clinics in the United States and Germany default to fixed configurations for compliance reliability in patients aged 7–11.
- Removable:Patient-detachable systems with snap-fit or magnetic retention. Bluetooth-enabled compliance sensors embedded in neck straps are accelerating uptake among suburban United States practices where parental monitoring drives purchasing criteria.
- Functional:Appliances combining headgear force with mandibular repositioning for skeletal correction. German university hospitals concentrate demand for these hybrid systems in severe Class II cases.
- Orthopedic:High-force configurations exceeding 350 grams for maxillary restraint in craniofacial anomalies. Japanese orthodontic centers specializing in cleft palate protocols anchor this segment's specialized supply chains.
Fixed headgear leads on scale; removable configurations lead on momentum.
Material:
Cost-to-performance ratios and biocompatibility certification burdens reshape supplier economics across metal and polymer alternatives.
- Metal:Stainless steel and nickel-titanium alloys forming facebows, molar bands, and force modules. EU MDR Annex I general safety requirements now mandate enhanced cytotoxicity documentation for nickel-releasing alloys, compressing margins for uncertified European suppliers.
- Plastic:Medical-grade polycarbonate and polypropylene components in strap housings and aesthetic covers. Parental preference for low-visibility options concentrates demand in United States private practices serving image-conscious suburban demographics.
- Elastic:Latex-free elastomer force modules and strap tensioners. Japanese PMDA streamlined registration pathways are accelerating iterative improvements in force-degradation profiles for domestic manufacturers.
- Composite:Fiber-reinforced polymer facebows and hybrid metal-polymer assemblies. German orthodontic laboratories pilot these configurations for patient-specific 3D-printed geometries matched to intraoral scan data.
Metal alloys dominate revenue concentration; composite materials are expanding most quickly.
End User:
Patient volume throughput and reimbursement frameworks differentiate procurement patterns across clinical settings.
- Pediatric Clinics:High-volume practices specializing in early interceptive treatment. North American orthodontic association protocols recommending Class II correction initiation at age 7–9 are expanding addressable patient pools.
- Dental Hospitals:Academic medical centers handling complex craniofacial cases. Japan's national university hospitals anchor demand for orthopedic headgear configurations in cleft palate and syndromic patient populations.
- Orthodontists:Specialist practices with fixed appliance therapy integration. Digital workflow compatibility now filters purchasing decisions in German and United States markets where intraoral scanning platforms predominate.
- Private Practices:Independent clinics with direct patient relationships. Online review visibility and social media brand awareness are elevating competitive determinants in United States suburban markets.
Pediatric clinics lead on scale; private practices lead on momentum.
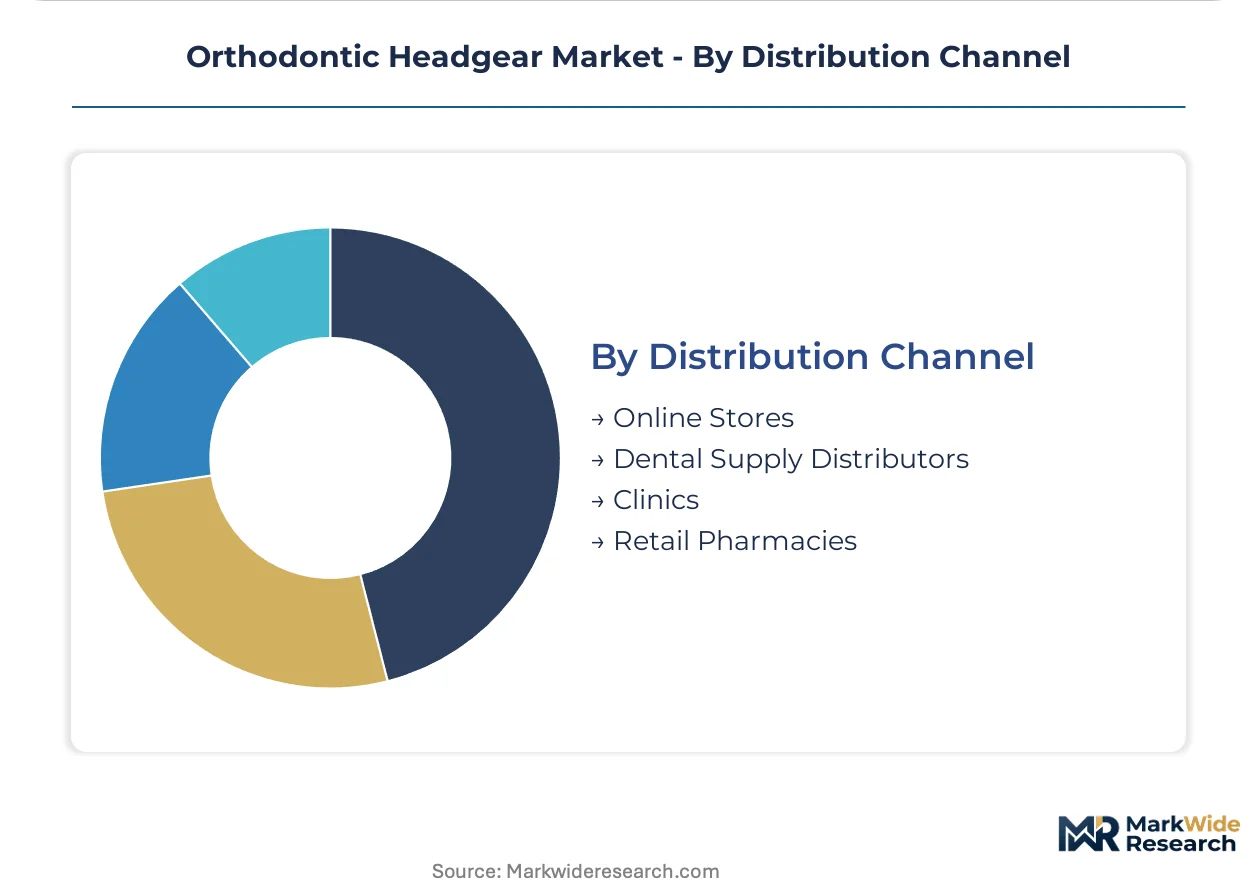
Distribution Channel:
Channel margin capture and customer onboarding economics are restructuring go-to-market architectures.
- Online Stores:Specialized orthodontic supply platforms and manufacturer-direct portals. Direct-to-practice e-commerce is bypassing traditional distributor markups for manufacturers with established brand recognition.
- Dental Supply Distributors:Full-line distributors with field sales representation and inventory financing. Legacy relationships dominate purchasing in smaller United States and European practices lacking procurement specialization.
- Clinics:Direct manufacturer agreements with high-volume orthodontic networks. German clinic chains and United States dental service organizations are consolidating procurement through centralized purchasing cooperatives.
- Retail Pharmacies:Limited presence for over-the-counter replacement straps and accessories. ANVISA regulatory expansion in Brazil's São Paulo and Rio de Janeiro states is testing pharmacy channel viability for mid-priced systems.
Dental supply distributors lead on scale; online stores lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orthodontic headgear first achieved clinical scale in mid-20th century United States university hospitals, where craniofacial research programs standardized extraoral appliance protocols for Class II malocclusion correction. This American foundation established the technical templates and training pathways that subsequently diffused to European and Asian orthodontic markets.
United States
Pediatric early intervention protocols now recommend headgear initiation at age 7–9, expanding addressable patient pools in suburban private practices. FDA 510(k) clearance requirements enforce biocompatibility documentation for nickel-releasing alloys. Greater Boston and Pacific Northwest orthodontic clusters concentrate demand for Bluetooth-enabled compliance monitoring systems.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia anchor European demand for functional and orthopedic headgear configurations in severe skeletal cases. EU MDR Class IIa designation mandates enhanced clinical evidence for patient-specific designs. Baden-Württemberg orthodontic laboratories pilot 3D-printed composite facebows matched to intraoral scan data.
Japan
National university hospitals in Tokyo and Osaka specialize in high-force orthopedic headgear for cleft palate and craniofacial anomaly protocols. PMDA streamlined registration pathways for Class IIa devices accelerate iterative design improvements. Kanto region manufacturers concentrate production of latex-free elastomer force modules with optimized degradation profiles.
Brazil
Private insurance coverage expansion in São Paulo and Rio de Janeiro states creates whitespace for mid-priced headgear systems. ANVISA regulatory frameworks are testing pharmacy channel viability for over-the-counter replacement straps. Southeast Brazilian orthodontic service organizations consolidate procurement through centralized purchasing cooperatives.
United Kingdom
NHS orthodontic contracts in London and Southeast England prioritize cost-efficient fixed headgear configurations for high-volume pediatric clinics. MHRA post-Brexit regulatory alignment with EU MDR standards maintains biocompatibility documentation requirements. Midlands dental hospitals concentrate academic research on smart compliance sensor integration.
Orthodontic Headgear Market Competitive Environment
Capital-heavy producers with in-house alloy foundries and polymer compounding operations compete with asset-light designers outsourcing component fabrication to certified contract manufacturers. The vendor base stratifies across three tiers: multinational dental conglomerates with orthodontic divisions, mid-cap specialists with captive European or North American production, and regional fabricators serving single-country markets. Two dominant competitive moves are reshaping positioning: backward integration into certified nickel-titanium wire supply, and API development partnerships with practice management software vendors to streamline smart headgear data integration.
Among North American orthodontic specialists, Rocky Mountain Orthodontics and American Orthodontics exemplify the mid-cap specialist archetype with concentrated domestic manufacturing footprints. Dentsply Sirona occupies a position representing multinational dental conglomerate diversification into digital workflow-integrated appliances. These three anchors illustrate how competitive positioning fragments across manufacturing scale, geographic focus, and technology platform strategies.
| Leading Market Players |
|---|
| DB Orthodontics |
| G&H Orthodontics |
| 3M |
| American Orthodontics |
| Rocky Mountain Orthodontics |
| Ortho Kinetics Corporation |
| Dentsply Sirona |
| Great Lakes Dental Technologies |
| Ormco Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive nickel-titanium wire production anchors supply positioning and pricing power for orthodontic headgear incumbents, with EU MDR biocompatibility documentation costs filtering through to end-user price points and compressing margins for outsourced competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Premium tiers command positioning through FDA 510(k) clearance and Bluetooth-enabled compliance sensors. Cost compression in the mid-tier intensifies because EU MDR Annex I requirements force biocompatibility study investments. Pediatric clinics in Germany exhibit the highest price sensitivity due to centralized purchasing cooperatives, while Japanese university hospitals prioritize performance over cost.
Supply Chain Analysis
Specialty shape-memory alloy supply rests on Japanese and German metallurgical producers with ISO 13485 certification. Nickel-titanium wire, medical-grade polycarbonate, and latex-free elastomer modules constitute critical input dependencies. Single-source vulnerability concentrates in certified nickel-releasing alloy suppliers qualified under EU MDR. Distribution runs through dental supply distributors with field sales representation, though direct-to-practice e-commerce channels are gaining momentum.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orthodontic headgear functions as a stable compounder, with pediatric early intervention protocols driving steady patient pool expansion across North America and Europe.
For Market Incumbents: Deploy backward integration into certified nickel-titanium wire supply to secure input stability against alloy concentration risk. Deepen API development partnerships with practice management software vendors to streamline smart headgear data integration and defend against clear aligner substitution threats. For New Entrants and Emerging Players: Capture whitespace in Brazil's São Paulo and Rio de Janeiro states where private insurance expansion meets underpenetrated orthodontic infrastructure. Target mid-priced fixed headgear configurations through direct-to-practice e-commerce platforms to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs exceed smaller European producers' capital access. The 5-10 year viability window favors asset-light designers with certified contract manufacturing relationships over capital-heavy foundry operators. Watch FDA guidance evolution on patient-specific orthodontic devices as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Accelerates market access for biocompatible material configurations in German and UK markets. |
| Smart Sensor Integration | Enables premium pricing through Bluetooth-enabled compliance monitoring in US suburban practices. |
| Direct-to-Practice E-Commerce | Bypasses distributor markups for manufacturers with established brand recognition. |
| 3D-Printed Component Development | Supports patient-specific facebow geometry matched to intraoral scan data. |
| Brazil ANVISA Registration | Opens pharmacy channel viability for mid-priced systems in Southeast Brazilian states. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged orthodontists, pediatric clinic procurement managers, biomedical engineers at university hospitals, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EU MDR notified body guidance documents, PMDA registration databases, and hospital procurement records. Bottom-up patient volume estimates triangulated against top-down manufacturer shipment data.
Segment-weighting across product type, material composition, end-user setting, and distribution channel anchored the analytical framework. CAGRs derived from fitted growth curves applied to pediatric demographic projections and orthodontic association protocol adoption timelines. Force-sensing technology penetration curves and clear aligner substitution elasticities informed scenario boundaries.
Regulatory timeline delays, alloy supply disruptions, and clear aligner indication expansion are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about MDR notified body capacity and PMDA streamlining continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Endometrial Ablation Devices Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
Global Surgical Visualization Products Market
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Meniscus Repair Systems Market
Medical Devices
Global Pulse Oximetry Market
Medical Devices
Global Large Volume Wearable Injectors Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Market
Medical Devices
Europe Mobility Aids Market
Medical Devices
Global Patient-Controlled Analgesic Pumps Market
Medical Devices
Next Generation Nebulizers Market
Medical Devices
Nerve Repair and Regeneration Market
Medical Devices
Vascular Boot Market
Medical Devices
South Africa Minimally Invasive Surgical Devices Market
Medical Devices
Ventricular Restoration Systems Market
Medical Devices
Global Dry Powder Inhaler (DPI) Market