
 Vial Box Market | 2026-2036
Vial Box Market Size, Share, and Industry Trends Forecast 2026-2036
Vial Box Market Analytics
Pharmaceutical wholesale distribution is tilting toward direct-to-manufacturer fulfillment models as cold chain integrity demands intensify. Gerresheimer AG leverages vertical integration from glass tubing to finished vial boxes, sustaining quality control across temperature-sensitive logistics. SCHOTT AG anchors its position through borosilicate glass technology leadership, while Thermo Fisher Scientific competes by extending its life sciences distribution network into specialized packaging services.
A vial box is a protective container engineered to house glass or polymer vials during pharmaceutical storage, transport, and distribution, typically incorporating cushioning inserts, moisture barriers, and thermal insulation rated for specific temperature ranges. These units prevent breakage, contamination, and thermal excursion for injectable drugs, vaccines, and biologics. Pre-filled vials command premium margins due to integrated delivery convenience, while recyclable box formats gain traction as pharmaceutical companies face ESG compliance pressure. Glass material segments dominate volume, though polymer alternatives are displacing traditional formats in mRNA and cell therapy applications where breakage risk must be minimized.
FDA serialization requirements under the Drug Supply Chain Security Act, EU MDR traceability mandates, and WHO prequalification standards for vaccine packaging collectively elevate barrier-to-entry for vial box suppliers. The EU F-Gas Regulation further constrains refrigerant choices in temperature-controlled packaging, redirecting R&D toward passive thermal systems. Stakeholders must monitor how evolving pharmacopeial standards for extractables and leachables will redefine material qualification timelines and supplier certification requirements.
Market Dynamics
Cold chain integrity requirements are compressing supplier margins while elevating qualification barriers for temperature-assured packaging across biopharmaceutical logistics networks.
Growth Catalysts
- EU MDR traceability mandates:Serialization requirements under the EU Medical Device Regulation are forcing wholesale distributors to upgrade packaging infrastructure, creating pull for integrated vial box systems with embedded tracking.
- Cell therapy manufacturing expansion:Commercial-scale production of CAR-T and regenerative therapies requires polymer vial formats that minimize breakage risk during cryogenic handling and transport.
- German glass tubing clusters:Concentrated specialized glass production around Mainz and Müllheim anchors regional supply security for high-performance borosilicate vial manufacturing.
Market Restraints
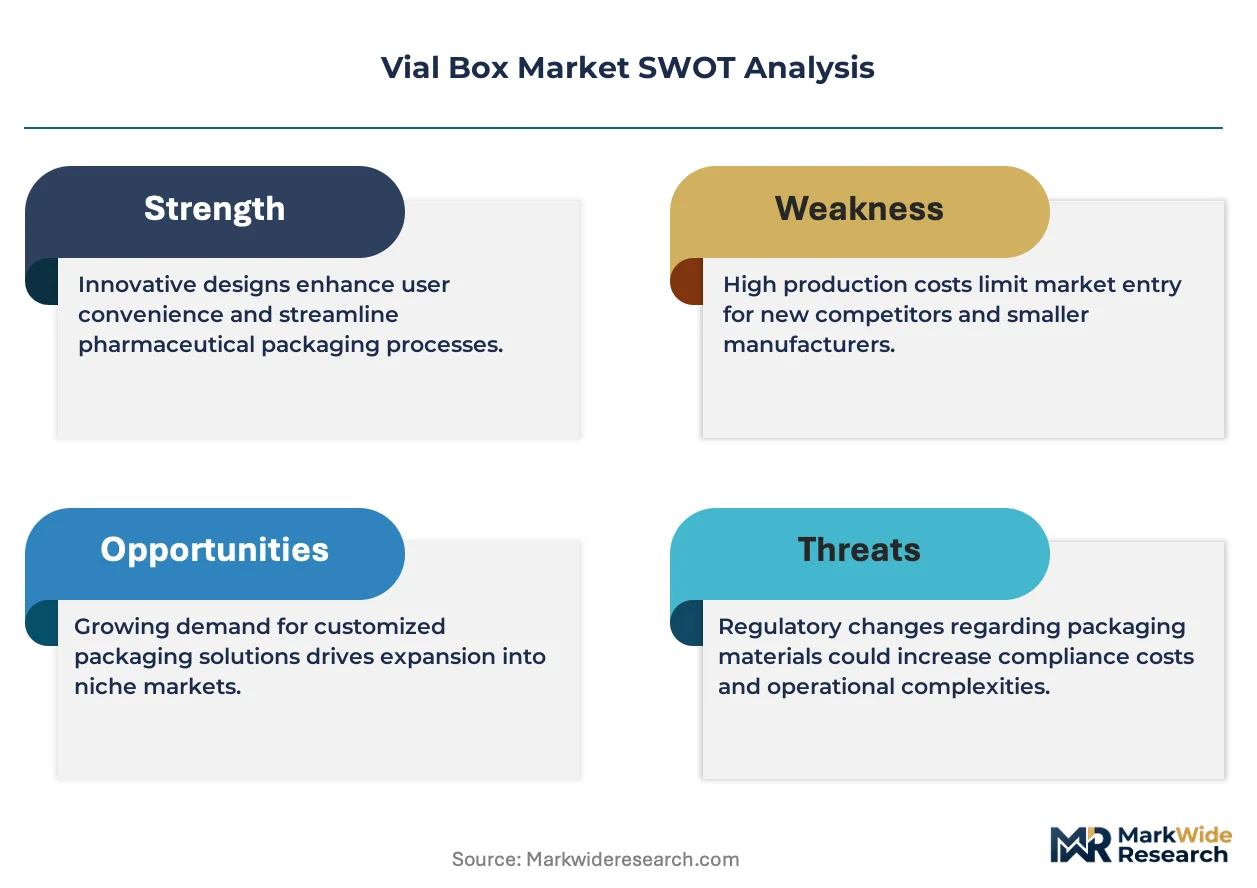
- Specialized borosilicate supply concentration:Three European tubing suppliers control critical raw material flows for Type I glass vials, creating vulnerability to energy cost shocks or export restrictions.
- EU F-Gas refrigerant constraints:Phase-down schedules under the F-Gas Regulation limit active cooling options for temperature-controlled boxes, forcing costly redesign toward passive thermal systems.
- Polymer substitution ceiling:Extractables and leachables testing requirements under USP <1664> and EP 3.2.2 prolong qualification timelines for plastic alternatives in parenteral applications.
Strategic Opportunities
- India cold chain infrastructure buildout:CDSCO's expanding vaccine export certification requirements and government-funded storage networks create demand for WHO-prequalified passive thermal packaging.
- Pre-filled vial integration:Device manufacturers seeking combined drug-delivery systems represent a channel bypassing traditional pharmaceutical wholesale distribution.
- CSRD-driven ESG reporting:Corporate Sustainability Reporting Directive obligations are redirecting procurement toward recyclable fiber-based cushioning and reusable box formats with verified carbon footprints.
Industry Challenges
- Extractables toxicology expertise scarcity:Qualified analytical chemists capable of designing USP <1664> and ISO 10993-12 compliant testing protocols command premium compensation, constraining supplier expansion.
- Serialization system integration:DSCSA-compliant track-and-trace hardware requires capital deployment across packaging lines, with payback periods extending beyond typical contract renewal cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vial Box Market |
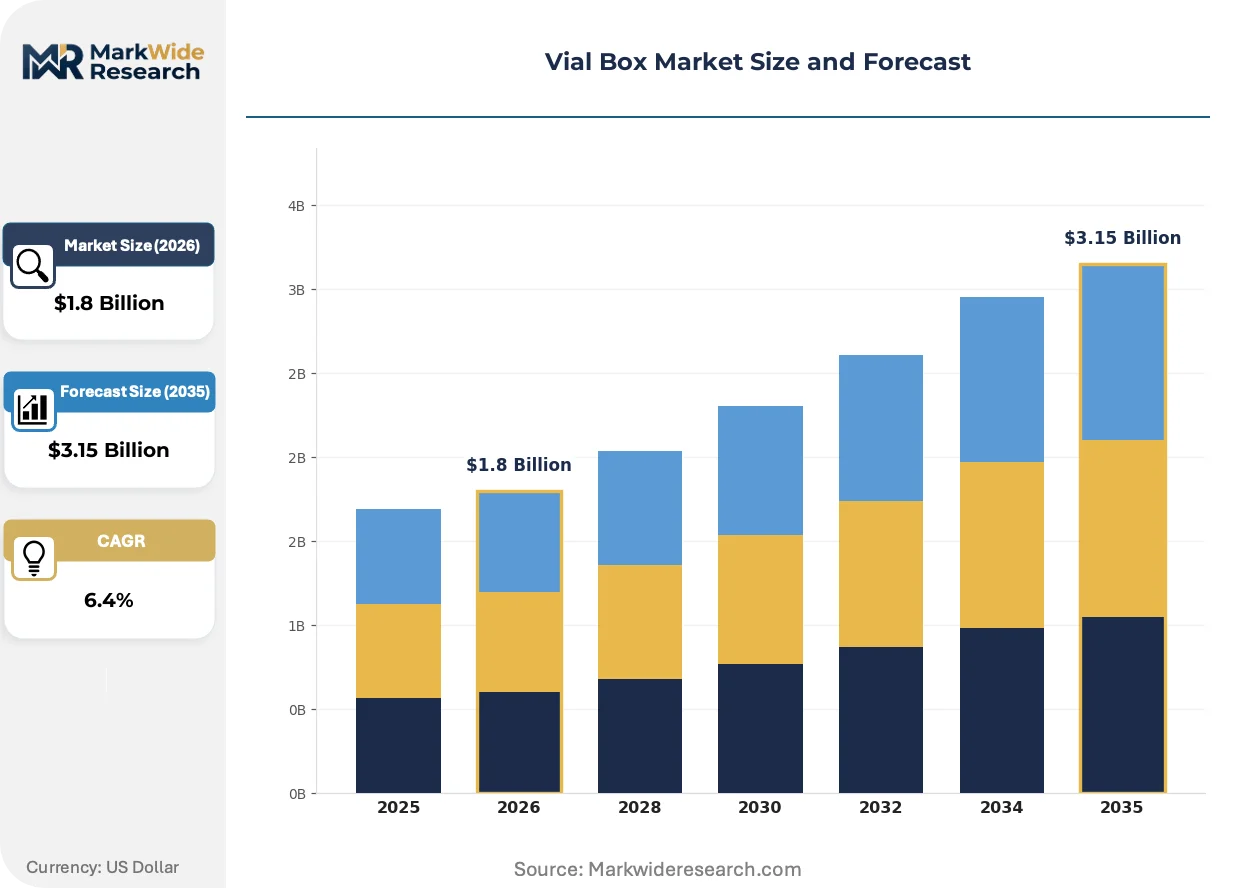
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Vials, Single Dose Vials, Multi Dose Vials, Pre-filled Vials Material: Glass, Plastic, Rubber, Metal End User: Pharmaceutical Companies, Biotechnology Firms, Research Laboratories, Hospitals Packaging Type: Standard Boxes, Customized Boxes, Tamper Evident Boxes, Recyclable Boxes |
| Companies Covered | Gerresheimer AG, SCHOTT AG, Thermo Fisher Scientific, West Pharmaceutical Services, Corning Incorporated, Stevanato Group, DWK Life Sciences, Amcor plc, Nipro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vial Box Market Evolving Landscape
Digital twin technology and sustainable material science are converging to redefine how pharmaceutical packaging is specified, validated, and monitored across distributed manufacturing networks.
Phase-change material (PCM) formulations with tunable melting points are virtualizing traditional active refrigeration for 2-8°C and -20°C shipment lanes. Biologics manufacturers in Belgium and the Netherlands are piloting these systems for international distribution, compressing total cost of ownership by eliminating compressor maintenance and hazardous goods documentation.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances (PFAS) are forcing moisture barrier redesign across European vial box production. Suppliers are accelerating qualification of bio-based coatings and plasma-treated fiberboards to maintain performance without fluorinated chemistries, with CDMOs in Ireland and Switzerland facing the earliest compliance deadlines.
Direct contracting between packaging engineers and biopharma quality assurance departments is displacing traditional procurement through group purchasing organizations. This pattern concentrates specification authority with technical buyers in Massachusetts and North Carolina, compressing vendor negotiation cycles and elevating technical service capabilities as a competitive discriminator.
Vial Box Market Segmentation
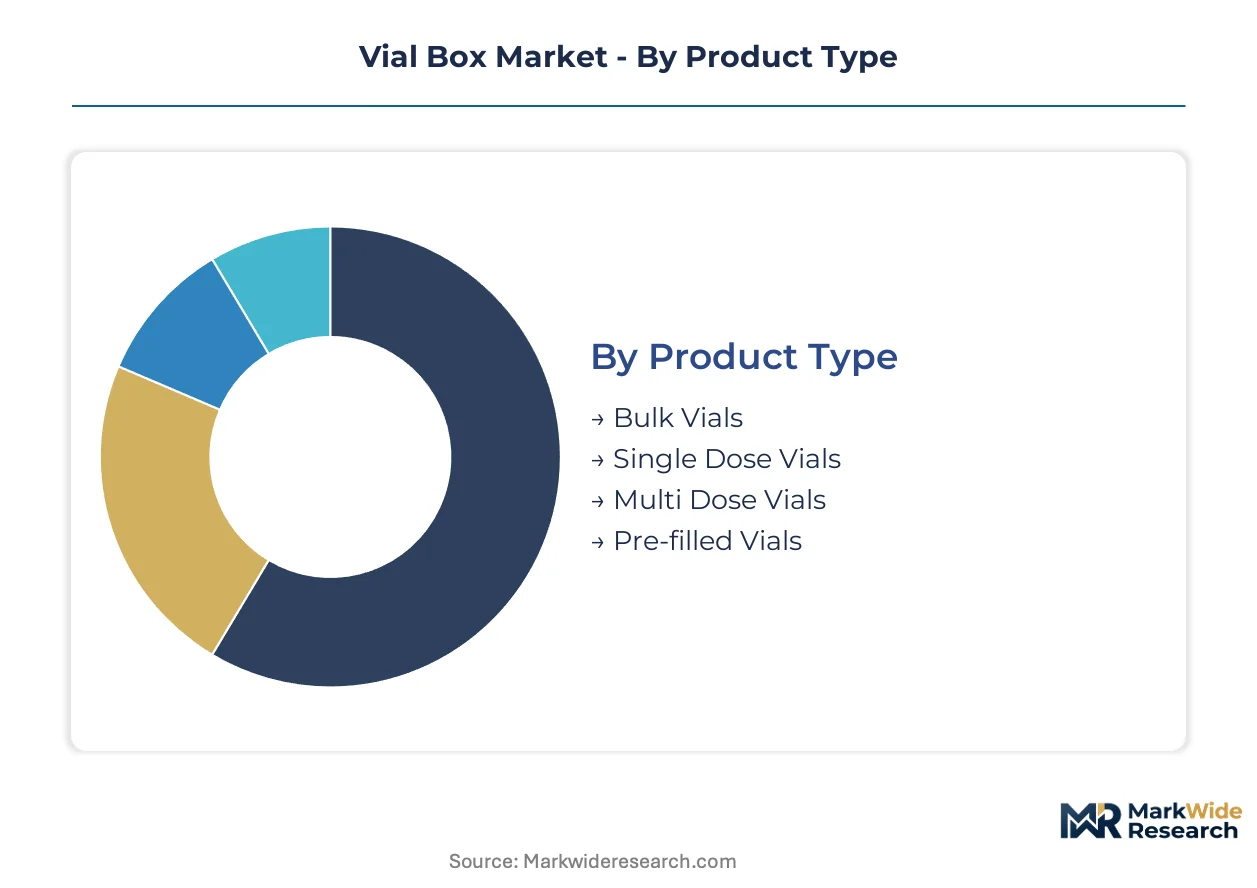
Vial box segmentation reveals how packaging specifications diverge across therapeutic categories and handling protocols. Material selection and product format choices directly determine thermal performance, breakage tolerance, and regulatory qualification pathways for biopharmaceutical distribution.
Product Type:
Volume scale and dosing convenience define how pharmaceutical manufacturers specify vial box configurations for commercial distribution.
- Pre-filled Vials:These units integrate drug product with primary container closure, requiring specialized cushioning geometries that accommodate integrated needle shields or Luer lock interfaces. Demand concentrates among device manufacturers in Massachusetts and North Carolina seeking combined drug-delivery systems that bypass traditional wholesale channels. The format commands premium positioning due to reduced preparation time and dosing error risk.
- Single Dose Vials:Individual-unit packaging for injectable therapies demands precise cavity tolerances and moisture barrier ratings calibrated to specific drug stability profiles. Oncology and vaccine applications in Belgium and the Netherlands are rotating toward polymer alternatives that minimize breakage during cryogenic handling. Unit-dose serialization requirements under EU MDR and DSCSA elevate barrier-to-entry for suppliers serving this segment.
- Multi Dose Vials:Multi-pull configurations for chronic therapies utilize standardized cavity arrays with shared thermal mass.
- Bulk Vials:Unfilled vial shipments for compounding pharmacies and contract manufacturing organizations emphasize stack density and pallet-level thermal protection.
Pre-filled vials hold installed capacity. Single dose vials are rotating up the share rankings.
Material:
Application-specific performance requirements and regulatory constraints govern material substitution patterns across parenteral packaging.
- Glass:Borosilicate Type I tubing from German clusters around Mainz and Müllheim supplies the dominant substrate for parenteral applications, with SCHOTT and Gerresheimer controlling critical raw material flows. Extractables and leachables qualification under USP 1664 and EP 3.2.2 prolongs approval timelines for alternatives, reinforcing glass's incumbent position in high-value biologics.
- Plastic:Cyclic olefin polymer and copolymer formats are displacing traditional glass in mRNA and cell therapy applications where cryogenic breakage risk must be eliminated. CDMOs in Ireland and Switzerland face accelerated qualification deadlines as REACH Annex XVII PFAS restrictions force moisture barrier redesign.
- Rubber:Elastomeric closure components for vial sealing require specialized formulation to minimize protein aggregation and particulate generation.
- Metal:Aluminum crimp seals and overcaps provide tamper evidence and needle penetration guidance in pre-filled syringe-vial hybrid formats.
Glass dominates revenue contribution. Plastic is gaining share fastest in regenerative therapy segments.
End User:
Customer type determines specification authority, procurement channel, and technical service intensity for vial box suppliers.
- Pharmaceutical Companies:Large-scale manufacturers of small-molecule injectables and established biologics drive standardization programs that favor qualified supplier lists and long-term contract structures. Direct contracting between packaging engineers and quality assurance departments is displacing traditional group purchasing organization channels, compressing negotiation cycles.
- Biotechnology Firms:Emerging developers of cell and gene therapies require polymer vial formats with customized thermal profiles for cryogenic logistics. These customers prioritize technical collaboration over unit cost, elevating supplier R&D capabilities as a competitive discriminator.
- Research Laboratories:Academic and government research centers purchase lower volumes with higher specification variability.
- Hospitals:Health system pharmacies emphasize tamper evidence and unit-of-use packaging for medication safety protocols.
Pharmaceutical companies anchor procurement volume. Biotechnology firms are expanding most quickly as commercial cell therapy manufacturing scales.
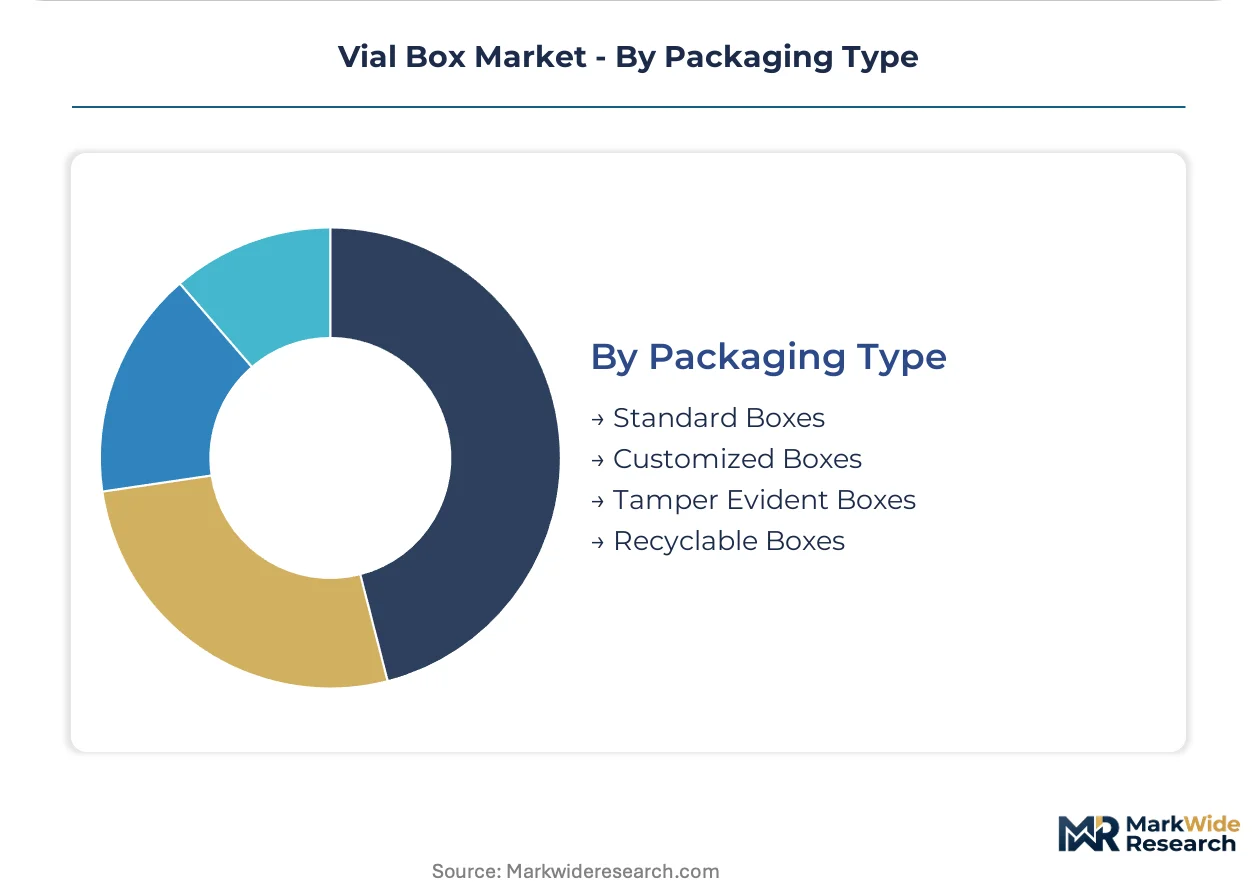
Packaging Type:
ESG compliance pressure and serialization mandates are reshaping how vial box formats are specified across distribution networks.
- Recyclable Boxes:Fiber-based cushioning and reusable formats with verified carbon footprints are redirecting procurement decisions as CSRD obligations take effect. Suppliers are accelerating qualification of bio-based coatings and plasma-treated fiberboards to maintain moisture barrier performance without fluorinated chemistries.
- Tamper Evident Boxes:Integrated tear tapes, holographic seals, and breakaway closures satisfy DSCSA and EU MDR traceability requirements while providing visual authentication at point of dispensing. Serialization system integration demands capital deployment across packaging lines.
- Customized Boxes:Application-specific cavity geometries and thermal insulation ratings serve niche biologics with non-standard stability profiles.
- Standard Boxes:Catalog configurations for high-volume generic injectables emphasize cost efficiency and supply security.
Tamper evident boxes hold regulatory-mandated volume. Recyclable boxes are climbing the fastest as sustainability procurement criteria harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing for borosilicate tubing, while India competes on cost for passive thermal packaging. This asymmetry shapes procurement flows across pharmaceutical distribution networks.
United States
Massachusetts and North Carolina biotech clusters drive demand for polymer vial formats in cell therapy logistics. FDA serialization requirements under DSCSA compress supplier qualification timelines. Greater Boston anchors pre-filled vial device manufacturing, with direct contracting between packaging engineers and quality departments displacing traditional procurement channels.
Germany
Mainz and Müllheim glass tubing clusters supply critical raw materials for Type I borosilicate vials. EU MDR traceability mandates force wholesale distributors to upgrade packaging infrastructure with embedded tracking systems. Baden-Württemberg CDMOs face accelerated qualification deadlines as REACH Annex XVII PFAS restrictions force moisture barrier redesign.
India
CDSCO's expanding vaccine export certification requirements create demand for WHO-prequalified passive thermal packaging. Government-funded cold chain infrastructure buildout redirects procurement toward temperature-assured formats. Maharashtra and Gujarat pharmaceutical manufacturing zones anchor regional packaging specification authority.
Switzerland
Swissmedic oversight of biologics packaging elevates extractables and leachables testing requirements under ISO 10993-12. Basel-based pharmaceutical manufacturers prioritize technical collaboration over unit cost in supplier selection. Irish and Swiss CDMOs face the earliest compliance deadlines for fluorinated chemistry phase-out.
Belgium
Biologics manufacturers pilot phase-change material systems for 2-8°C and -20°C international distribution lanes. EMA pharmacopeial standards for parenteral packaging redefine material qualification timelines. Flanders pharmaceutical logistics hubs compress total cost of ownership by eliminating compressor maintenance and hazardous goods documentation.
Vial Box Market Competitive Landscape
Specialized glass fabricators and diversified life sciences conglomerates split the market along vertical integration lines. German tubing suppliers control critical raw material flows through captive borosilicate production, while North American distributors compete by extending logistics networks into packaging services. Three archetypes dominate: upstream-integrated tubing-to-vial manufacturers, device-integrated drug-delivery specialists, and distribution-network packaging service providers. Competitive moves concentrate on backward integration into glass tubing supply and geographic expansion into Indian cold chain infrastructure.
Within the upstream-integrated tier, Gerresheimer AG and SCHOTT AG exemplify archetypes built on captive borosilicate supply. Thermo Fisher Scientific occupies a position representing distribution-network diversification into specialized packaging services. These three anchors illustrate how quality control across temperature-sensitive logistics, technology leadership in glass formulation, and life sciences distribution extension each define viable competitive positions.
| Leading Market Players |
|---|
| Gerresheimer AG |
| SCHOTT AG |
| Thermo Fisher Scientific |
| West Pharmaceutical Services |
| Corning Incorporated |
| Stevanato Group |
| DWK Life Sciences |
| Amcor plc |
| Nipro Corporation |
| Others |
Value Network & Pricing Analysis
Frankfurt-Mumbai air freight corridors absorb escalating fuel surcharges that cascade through borosilicate tubing supply chains, compressing margins for standard-format vial boxes while amplifying price premiums for configured-to-order thermal packaging. This cost dynamic concentrates pricing power with German glass clusters that control captive feedstock production, forcing downstream buyers to accept longer contract terms or absorb spot-market volatility.
Pricing Analysis
The customization-premium spread separates standard catalog vial boxes from application-specific thermal configurations by a factor reflecting design engineering and qualification burden. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by ISO 10993-12 certification grade and volume scale. Cost compression in the standard tier intensifies because Indian passive thermal packaging competes aggressively on unit economics. Biotechnology firms demonstrate least price sensitivity due to cryogenic handling requirements, while generic injectables manufacturers anchor the most price-sensitive segment.
Supply Chain Analysis
Upstream borosilicate glass tubing feeds from concentrated German production clusters around Mainz and Müllheim, with secondary sourcing from limited European specialty suppliers. The supply chain draws from high-purity silica sand, pharmaceutical-grade soda ash, and specialized platinum-lined melting furnaces as critical inputs. Single-source vulnerability around Type I glass tubing creates exposure to energy cost shocks or export licensing restrictions. Distribution runs through qualified pharmaceutical wholesale networks with embedded serialization infrastructure, bypassing traditional group purchasing organization channels for high-value biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across cell therapy formats and regional cold chain buildouts creates specialist niches that reward focused capability development over scale chasing. The shift toward direct contracting between packaging engineers and quality assurance departments elevates technical service intensity as a competitive discriminator.
For Market Incumbents: Build regulatory qualification moats by deepening backward integration into borosilicate tubing supply and accelerating USP 1664 extractables testing capabilities. Threatened by polymer substitution in mRNA applications, incumbents should anchor capacity expansion in German clusters while securing CDSCO prequalification for Indian vaccine export corridors. Certification investment in REACH Annex XVII-compliant moisture barriers represents the critical lever for defending premium positioning. For New Entrants and Emerging Players: Establish a beachhead in India's WHO-prequalified passive thermal packaging segment, where government-funded cold chain infrastructure buildout outpaces domestic supply capability. The most penetrable white space sits in recyclable fiber-based cushioning formats for ESG-driven European procurement. A go-to-market angle emphasizing verified carbon footprints and plasma-treated fiberboard barriers bypasses incumbent fluorinated chemistry expertise. For Investors and Strategic Acquirers: Specialized analytical chemistry laboratories with ISO 10993-12 and USP 1664 compliant testing protocols represent the priority acquisition archetype, given extractables toxicology expertise scarcity constraining supplier expansion. Long-term viability hinges on positioning for pharmacopeial standard evolution rather than commodity volume capture. The signal to watch is CDSCO's expanding vaccine export certification requirements, which will accelerate consolidation around prequalified packaging suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Tubing | Gerresheimer and SCHOTT anchor supply security through captive German glass production clusters. |
| CDSCO Prequalification Investment | WHO-prequalified status unlocks government-funded Indian vaccine cold chain procurement. |
| REACH Annex XVII Compliance Acceleration | PFAS-free moisture barrier qualification protects European market access for Irish and Swiss CDMOs. |
| Direct Contracting Channel Development | Technical collaboration with Massachusetts and North Carolina biotech clusters bypasses GPO intermediaries. |
| Phase-Change Material Formulation R&D | Belgian and Dutch biologics manufacturers pilot PCM systems to eliminate compressor maintenance costs. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with packaging engineers, regulatory affairs leads, pharmaceutical quality assurance directors, and cold chain logistics specialists; and secondary validation against FDA DSCSA guidance documents, EMA MDR implementation records, CDSCO vaccine export certifications, and REACH Annex XVII restriction timelines. Bottom-up triangulation across product-level shipment data and top-down reconciliation against national pharmaceutical production statistics anchored volume estimates.
Forecast inputs considered material substitution rates, serialization infrastructure deployment curves, and regional cold chain investment flows across the projection horizon. Segmentation dimensions modeled include product format, material substrate, end-user archetype, packaging type, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating therapeutic pipeline maturation and biopharmaceutical manufacturing capacity expansion.
Stress conditions across energy cost volatility, borosilicate supply disruption, and polymer qualification timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU MDR enforcement consistency and CDSCO certification throughput. Cross-checking against WHO prequalification database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Topical Drugs Packaging Market
Pharmaceutical Packaging
Pharmaceutical Ampoules Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Vials Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
Pharmaceutical HDPE Bottle Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Pharmaceutical Packaging Equipment Market
Pharmaceutical Packaging
Dispensing Pharmacy Packaging Machine Market
Pharmaceutical Packaging
Prescription Pharmacy Bags Market
Pharmaceutical Packaging
Anti-Counterfeit Pharmaceutical Packaging Market
Pharmaceutical Packaging
Plastic Vials and Ampoules Market
Pharmaceutical Packaging
Nutraceutical Packaging Market