
 Pharmaceutical Tubes Market | 2026-2036
Pharmaceutical Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Tubes Market Analytics
Buyer concentration across hospital procurement networks is rebalancing toward decentralized homecare channels. Essel Propack leverages its laminated tube expertise to serve high-volume dermatology contracts. Hoffmann Neopac anchors European demand through aluminum tube specialization for sensitive formulations. Albea Group competes on multi-material platforms that span plastic, laminate, and sustainable substrate options.
Pharmaceutical tubes are cylindrical primary packaging containers, typically manufactured from aluminum, plastic polymers, or multi-layer laminates with internal lacquer barriers, designed to dispense semi-solid drug formulations through controlled squeeze or twist mechanisms. Their core commercial purpose centers on product protection, dosing precision, and patient compliance for topical and mucosal therapeutics. Laminated tubes command margin pools due to barrier performance against oxygen and moisture ingress, while aluminum tubes retain structural dominance in efficacious preservative-free segments. Homecare end users represent the fastest-growing channel as self-administration of topical therapies expands beyond institutional settings.
FDA compliance requirements govern material biocompatibility and extractables testing for tubes entering the United States, while Europe's MDR framework imposes stricter post-market surveillance and traceability obligations on packaging suppliers. The EU AI Act introduces emerging documentation standards for automated quality inspection systems used in tube manufacturing lines. Stakeholders must monitor how dual regulatory pressure from FDA polymer validation and MDR technical documentation reshapes supplier qualification timelines and capital allocation toward compliance infrastructure.
Market Dynamics
Europe's MDR traceability mandates are compressing supplier qualification timelines while simultaneously fragmenting procurement authority from centralized hospital networks toward dispersed homecare channels.
Growth Catalysts
- Homecare channel expansion:Self-administered dermatological therapies are displacing institutional dispensing, creating pull-through demand for patient-friendly tube formats with ergonomic squeeze mechanisms.
- REACH-compliant barrier laminates:Advanced multi-layer structures incorporating EVOH and aluminum oxide coatings satisfy oxygen ingress specifications for preservative-free formulations.
- Germany's pharmaceutical packaging corridor:Concentrated converter capacity in Baden-Württemberg and Bavaria reduces logistics friction for European pharma contract manufacturers.
Market Restraints
- Aluminum price volatility:Primary metal input costs swing with LME trading patterns, compressing margin stability for traditional aluminum tube specialists.
- MDR technical documentation burden:European notified body backlogs extend supplier requalification cycles to 18-24 months, freezing new vendor entry.
- Flexible pouch substitution:Stand-up pouches with precision spouts capture share in high-volume OTC segments where tube rigidity offers limited functional advantage.
Strategic Opportunities
- Biopolymer substrate convergence:Polylactic acid and bio-based polyethylene developments align with EU Green Deal procurement preferences for carbon-reduced packaging.
- AI-driven quality inspection:Machine vision systems integrated with EU AI Act documentation standards enable real-time defect detection without human sampling bottlenecks.
- Indian OTC expansion:Domestic Ayurvedic and dermocosmetic brands seek compliant tube supply as CDSCO strengthens packaging material biocompatibility requirements.
Industry Challenges
- Extractables validation expertise:FDA polymer validation protocols require specialized analytical chemistry capabilities scarce among mid-scale tube converters.
- Legacy line retrofit costs:MDR-mandated serialization and aggregation equipment demands capital deployment that strains family-owned European suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Tubes Market |
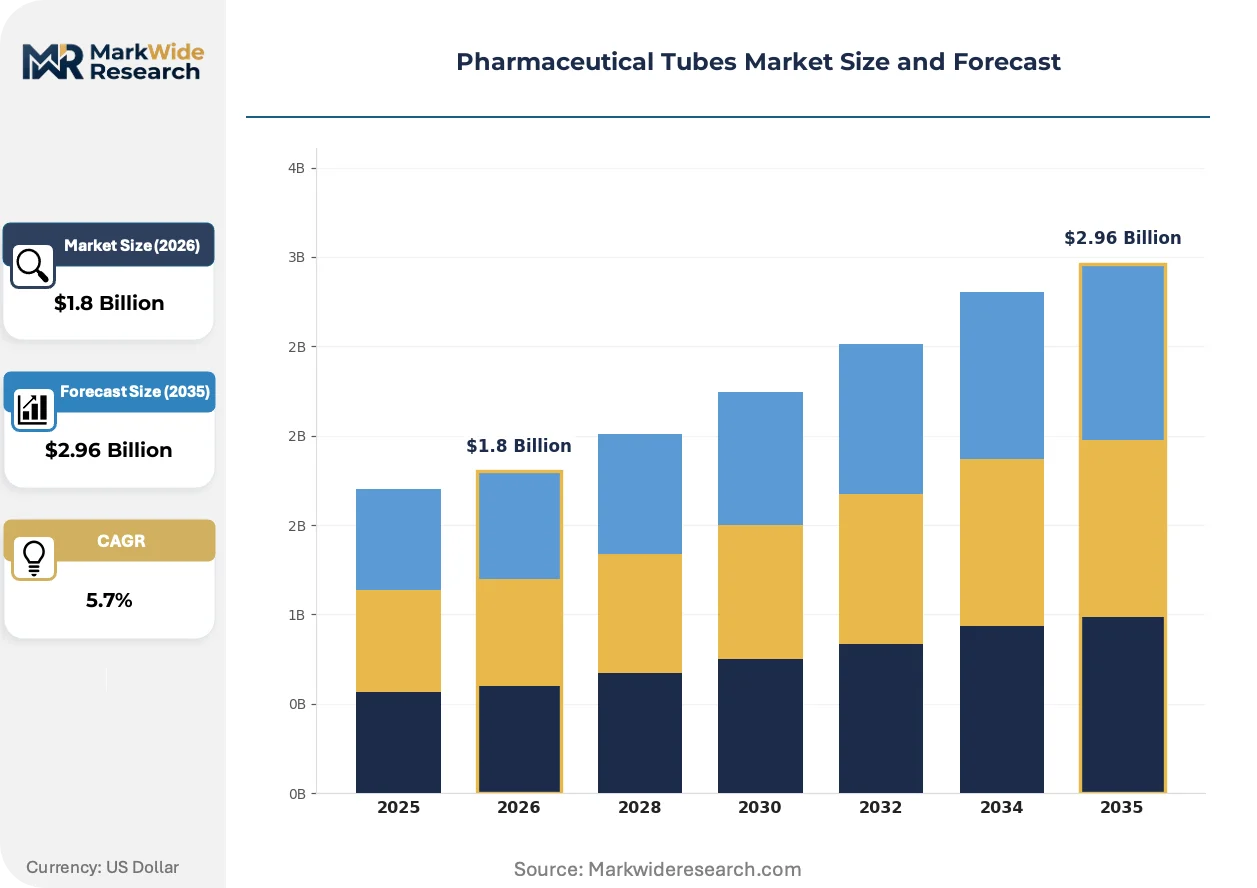
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Tubes, Aluminum Tubes, Laminated Tubes, Glass Tubes Application: Ointments, Creams, Gels, Pastes End User: Pharmacies, Hospitals, Clinics, Homecare Packaging Type: Sealed, Caped, Twist-off, Squeeze |
| Companies Covered | Albea Group, Essel Propack, Hoffmann Neopac, Huhtamaki, Montebello Packaging, ALLTUB, CCL Industries, Unette Corporation, Romaco Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Tubes Market Evolving Landscape
Digital manufacturing integration and material science advances are compressing development cycles while regulatory documentation requirements expand. Three forces dominate near-term competitive positioning.
Smart manufacturing platforms are modularizing production workflows across tube forming, printing, and quality stations. Mid-scale converters in Germany and Italy deploy these systems to batch-size flexibility without line changeover penalties. The technology is modularizing contract manufacturing economics, enabling shorter-run pharmaceutical contracts previously uneconomical.
EU AI Act documentation standards for automated inspection systems impose algorithmic transparency requirements on quality control software. Tube manufacturers must maintain training data records and bias audit trails for machine vision deployments. German packaging corridors face the steepest compliance curves given their concentration of AI-enabled high-speed lines.
Hospital procurement networks are fragmenting as pharmacy benefit managers and direct-to-patient channels capture topical therapy dispensing. Homecare buyers prioritize ergonomic design and child-resistant closure integration over institutional bulk pricing. This behavioral pivot concentrates in German and French markets where reimbursement policies accelerate self-administration incentives.
Pharmaceutical Tubes Market Segmentation
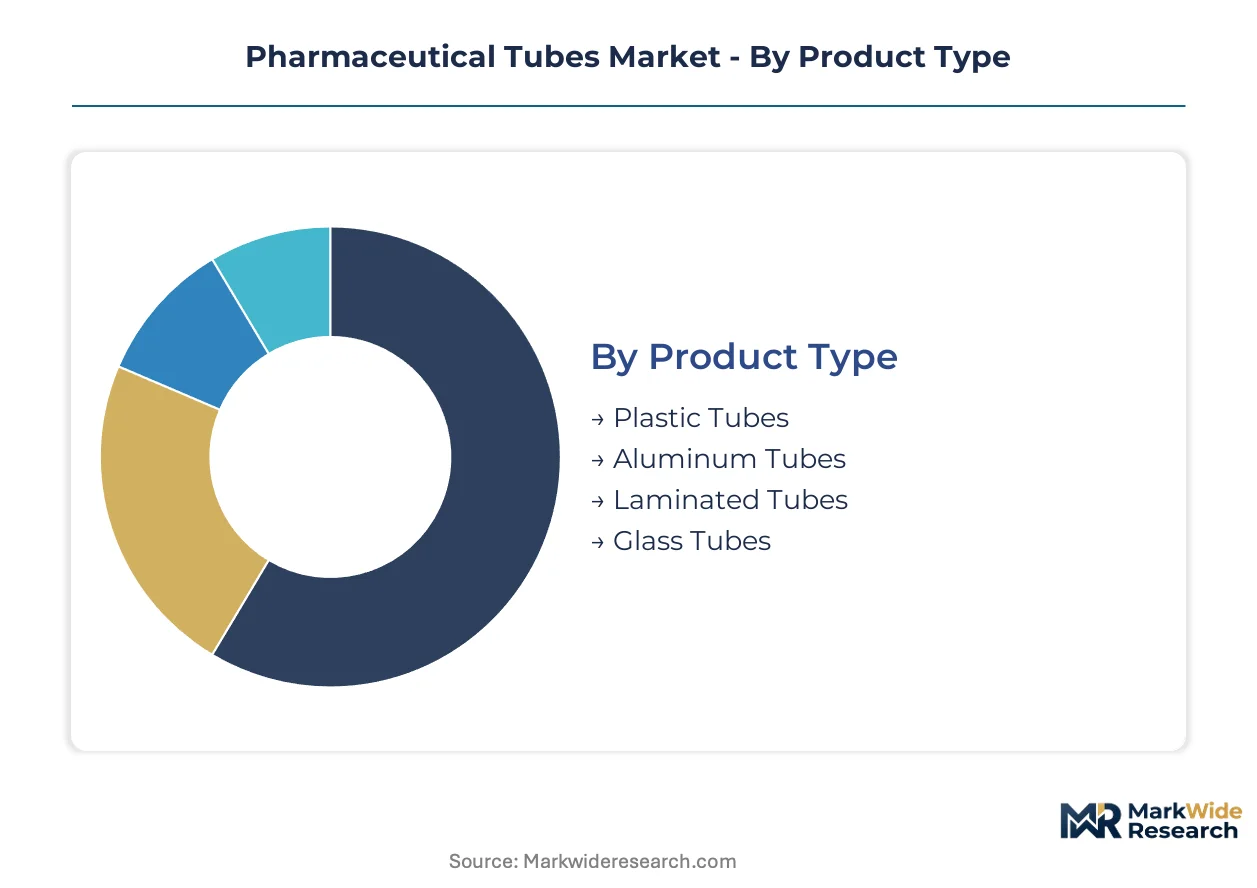
Tube material selection and dispensing mechanism design directly determine barrier performance, patient compliance rates, and regulatory qualification pathways. Segmentation in pharmaceutical tubes reflects divergent technical requirements across dermatology, ophthalmology, and mucosal therapeutics.
Product Type:
Customization intensity spans from commodity polymer extrusions to engineered multi-layer laminates with oxygen scavenging functionality.
- Laminated Tubes:Multi-layer structures incorporating aluminum foil barriers, EVOH, and polyethylene deliver sub-0.1 cc/m²/day oxygen transmission rates for preservative-free formulations. Demand concentrates in German dermatology contract manufacturing where MDR traceability requirements favor qualified laminate suppliers with validated adhesive systems.
- Aluminum Tubes:Collapsible aluminum with internal epoxy-phenolic lacquer coatings provide absolute light and gas barrier for efficacious sensitive APIs. European compounding pharmacies specify aluminum for hyaluronic acid and corticosteroid preparations where polymer interaction risks disqualify plastic alternatives.
- Plastic Tubes:Mono-layer and co-extruded polyethylene or polypropylene tubes serve high-volume OTC segments with cost-optimized barrier properties.
- Glass Tubes:Borosilicate and soda-lime glass containers address ophthalmic and diagnostic reagent applications requiring inert contact surfaces.
Leading the category by volume: Plastic Tubes. Expanding most quickly: Laminated Tubes.
Application:
Formulation viscosity and active ingredient stability requirements segment tube specifications across semi-solid drug categories.
- Creams:Oil-in-water emulsions with intermediate viscosity demand tubes with controlled memory recovery to prevent dose variability. Homecare dispensing of emollient therapies in France and Germany drives preference for ergonomic squeeze tubes with flip-top closures.
- Ointments:Hydrophobic petrolatum-based formulations require chemically resistant internal lacquers to prevent polymer degradation and extractables migration. Hospital procurement networks in Bavaria specify aluminum tubes for antibiotic ointments where sterility maintenance is paramount.
- Gels:Aqueous and alcoholic gel formulations with shear-thinning behavior suit precision nozzle tubes for targeted topical application.
- Pastes:High-viscosity zinc oxide and protective pastes require wide-mouth tube formats with robust crimp seals.
Creams dominate current procurement volumes. Gels are gaining share fastest through dermocosmetic brand expansion.
End User:
Channel-specific compliance documentation and patient interface requirements fragment tube specifications across institutional and retail dispensing.
- Homecare:Direct-to-patient channels prioritize child-resistant closures, tactile dosing feedback, and printed instructions for use. German pharmacy reimbursement reforms accelerating self-administration of topical therapies expand this segment beyond traditional institutional boundaries.
- Hospitals:Centralized procurement networks demand bulk packaging formats with aggregation-level serialization for MDR traceability compliance.
- Pharmacies:Retail dispensing emphasizes shelf differentiation through offset and flexographic decoration with tamper-evident features.
- Clinics:Outpatient dermatology and wound care centers specify mid-volume tubes with sterile peelable seals.
Hospitals lead institutional volume. Homecare demonstrates the steepest expansion trajectory as reimbursement shifts toward self-administration.
Packaging Type:
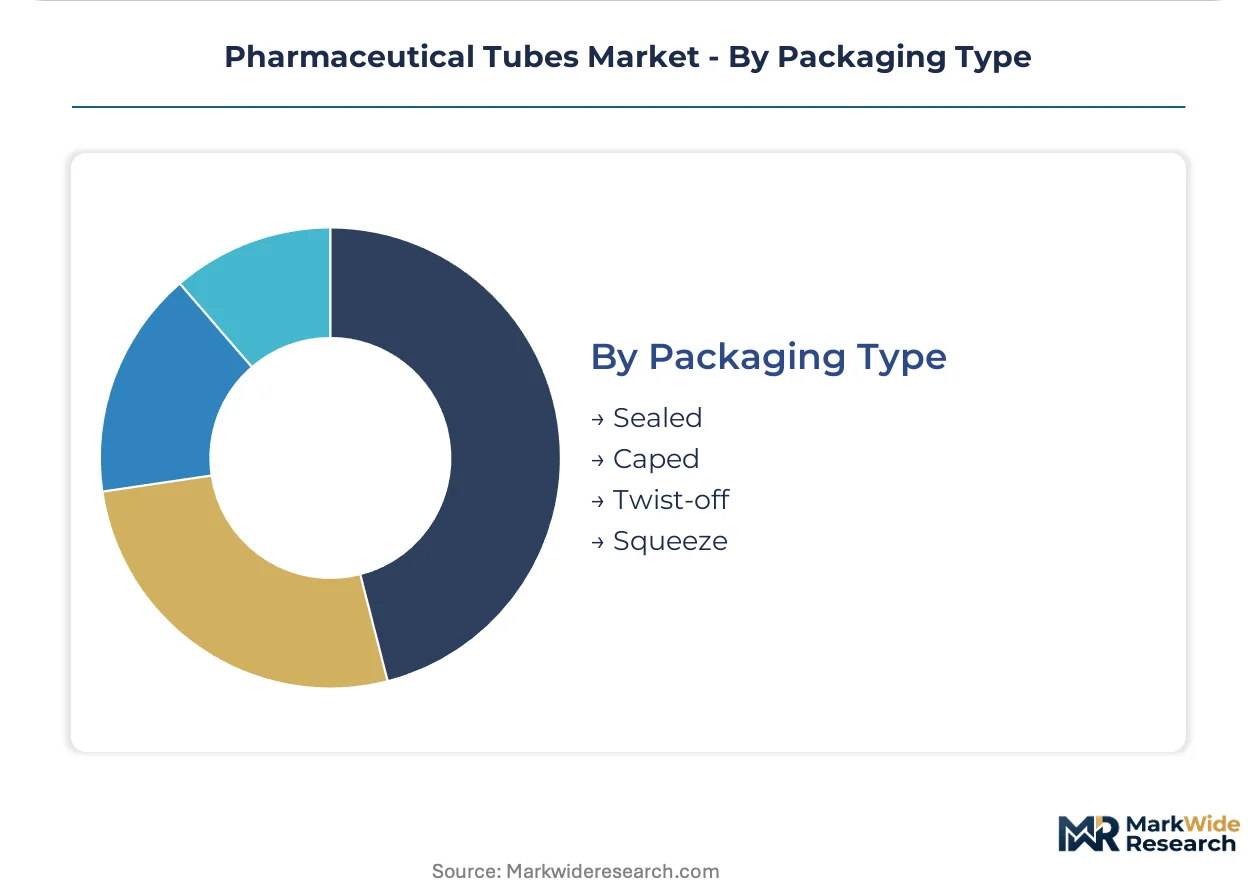
Dispensing mechanism selection balances dosing precision against manufacturing complexity and patient dexterity requirements.
- Squeeze:Conventional tube bodies with variable wall thickness enable controlled product extrusion through applied pressure. German converters optimize squeeze tube economics through continuous extrusion lines with inline printing for high-volume dermatology contracts.
- Twist-off:Pre-scored neck membranes provide tamper evidence and controlled initial opening for single-use or preservative-free formulations. French hospital pharmacies specify twist-off aluminum tubes for sterile ophthalmic preparations where contamination control is critical.
- Caped:Screw-on, snap-on, and flip-top closures enable resealability for multi-dose regimens with varying child-resistance options.
- Sealed:Permanent crimp or heat-sealed tubes deliver unit-dose formats for clinical trial supplies and travel-size OTC products.
Caped formats lead by installed base. Twist-off designs are climbing the fastest through preservative-free formulation growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates pharmaceutical tube procurement through its Baden-Württemberg and Bavaria packaging corridors, while homecare channel expansion reshapes demand geography across multiple markets.
United States
FDA polymer validation protocols and extractables testing requirements govern tube material qualification for topical drug entrants. Hospital procurement networks fragment as pharmacy benefit managers capture dispensing authority. New Jersey and Pennsylvania host concentrated pharmaceutical packaging converter capacity serving Northeast contract manufacturers.
Germany
MDR traceability mandates compress supplier qualification timelines while accelerating homecare channel preference for ergonomic tube formats. EMA technical documentation requirements and notified body backlogs extend requalification cycles. Stuttgart and Munich anchor the pharmaceutical packaging corridor where laminate tube specialists serve dermatology contract manufacturers.
India
CDSCO packaging material biocompatibility requirements strengthen as domestic Ayurvedic and dermocosmetic brands scale compliant tube sourcing. Maharashtra and Gujarat concentrate converter investments serving Western pharmaceutical formulation clusters.
France
ANSM post-market surveillance obligations align with MDR traceability standards for tube suppliers entering hospital pharmacy networks. Reimbursement reforms accelerate self-administration of topical therapies. Paris and Lyon procurement networks fragment toward direct-to-patient channels.
Switzerland
Swissmedic quality system requirements impose stringent documentation burdens on tube suppliers serving precision pharmaceutical formulation houses. Basel and Zurich host concentrated pharmaceutical packaging demand from global headquarters operations.
Pharmaceutical Tubes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sustainable substrate specialization and AI-enabled quality systems. The supplier base concentrates among laminated tube specialists, aluminum tube fabricators, and multi-material platform operators. Three archetypes dominate: barrier laminate engineers serving preservative-free formulations, aluminum tube specialists anchoring sensitive API segments, and diversified packaging conglomerates spanning plastic, laminate, and sustainable alternatives. Capacity expansion in Germany's packaging corridor and strategic partnerships for Indian OTC market access represent the dominant competitive vectors.
Among diversified packaging platforms, Albea Group and Essel Propack occupy positions spanning multiple material technologies, while Hoffmann Neopac represents the aluminum tube specialization archetype serving European sensitive formulation demand.
| Leading Market Players |
|---|
| Albea Group |
| Essel Propack |
| Hoffmann Neopac |
| Huhtamaki |
| Montebello Packaging |
| ALLTUB |
| CCL Industries |
| Unette Corporation |
| Romaco Group |
| Others |
Value Network & Pricing Analysis
Aluminum ingot costs on the London Metal Exchange transmit directly through to tube converter pricing tiers, with laminate specialists in Germany's Baden-Württemberg corridor commanding premium positioning over commodity polymer extruders serving high-volume OTC segments.
Pricing Analysis
Volume concentration in plastic tubes for mass-market dermatology runs against margin capture by laminate and aluminum specialists serving preservative-free formulations. Pricing stratifies across premium, standard, and economy tiers based on barrier performance certification and MDR traceability documentation depth. Cost compression in standard-grade polymer tubes is intensifying as flexible pouch substitutes capture share in price-sensitive OTC segments. Hospital procurement networks demonstrate lowest price sensitivity due to compliance-driven vendor lock-in, while direct-to-patient homecare channels prioritize ergonomic design premiums over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from EMA-notified body audits compel pharmaceutical contract manufacturers to qualify laminate suppliers across Germany, Italy, and Switzerland simultaneously. Raw material flows draw from aluminum smelters in Norway and Iceland, EVOH resin producers in Japan, and polyethylene converters in the Netherlands. Single-source vulnerability concentrates in specialized adhesive systems for multi-layer barrier laminates where FDA extractables validation creates 18-24 month qualification freezes. Distribution runs through regional converter hubs serving formulation clusters in Stuttgart, Munich, and Basel with direct logistics integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European MDR notified body capacity constraints are propping laminate tube pricing as requalification backlogs freeze new vendor entry, creating a supply-constrained window for qualified incumbents.
For Market Incumbents: Anticipate flexible pouch substitution pressure in high-volume OTC segments by deepening barrier laminate R&D for preservative-free dermocosmetic contracts. Anchor position through backward integration into EVOH and aluminum oxide coating supply to defend margin stability against raw material volatility. Prioritize AI-enabled quality inspection documentation to satisfy EU AI Act algorithmic transparency requirements ahead of mid-scale competitors.
For New Entrants and Emerging Players: Enter via Ayurvedic and dermocosmetic tube supply to India's CDSCO-strengthening market, where domestic brand scaling creates white-space demand for compliant packaging partners. Target Maharashtra and Gujarat formulation clusters with biopolymer substrate offerings aligned to EU Green Deal procurement preferences. Leverage sustainable material specialization as differentiation lever against established multi-material platforms.
For Investors and Strategic Acquirers: EMA notified body backlog clearance rates are the leading indicator that MDR requalification cycle compression will ease, opening acquisition windows for distressed mid-scale European converters. Frame long-term viability around 5-10 year biopolymer substrate transition curves and AI-driven manufacturing automation adoption. Target acquisition archetype: family-owned German laminate specialists with validated adhesive systems but strained capital for serialization equipment deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Traceability Compliance Investment | Notified body qualification accelerates vendor lock-in for laminate specialists serving EMA-regulated formulations. |
| Biopolymer Substrate Development | Polylactic acid and bio-based polyethylene align with EU Green Deal procurement preferences in German hospital networks. |
| AI-Driven Quality Inspection Deployment | Machine vision systems with EU AI Act documentation enable real-time defect detection without human sampling bottlenecks. |
| Indian OTC Market Partnership | CDSCO biocompatibility requirements create compliant tube demand from scaling Ayurvedic and dermocosmetic brands. |
| Backward Integration into Barrier Materials | Captive EVOH and aluminum oxide coating supply defends margin stability against LME aluminum price volatility. |
Research Methodology
Document review covered FDA 510(k) filings, EMA technical documentation databases, and MDR notified body audit records, complemented by interviews with tube converter operations directors, pharmaceutical packaging procurement managers, regulatory affairs specialists at formulation houses, and quality control leads at laminate adhesive suppliers. Secondary validation drew from customs trade data for aluminum and polymer inputs, SEC filings of diversified packaging conglomerates, and EU AI Act implementation guidance. Bottom-up demand modeling from dermatology and ophthalmic formulation pipelines was triangulated against top-down supply capacity assessments across Germany's packaging corridor.
Segment-level volume and value estimates were produced through multi-dimensional modeling across material type, barrier performance tier, dispensing mechanism, and end-user channel, with CAGRs derived from regression analysis of historical qualification cycle lengths and procurement pattern shifts. Forecast inputs incorporated MDR implementation timeline assumptions, aluminum price volatility bands, and homecare reimbursement policy trajectories in France and Germany.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended notified body backlog scenarios or accelerated flexible pouch substitution in OTC segments. Deviation in EMA audit throughput rates or CDSCO enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Packaging Market
Pharmaceutical Packaging
APAC Pharmaceutical Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Middle East and West Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Pots Market
Pharmaceutical Packaging
Polymer Vials Market
Pharmaceutical Packaging
Glass Medicine Bottles Market
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Topical Drugs Packaging Market
Pharmaceutical Packaging
Plastic Pharma Tray Market
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market