
 North America Ampoules Packaging Market | 2026-2036
North America Ampoules Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ampoules Packaging Market Foresight
Subscription-based predictive maintenance for forming-line equipment is decoupling capital expenditure from operational budgets across ampoule packaging operations. SCHOTT AG leverages its specialty glass expertise to sustain premium positioning in borosilicate ampoule supply for North American biologics manufacturers. Gerresheimer AG anchors its regional footprint through controlled manufacturing scale across multiple US production sites. James Alexander Corporation specializes in plastic and polymer ampoule alternatives, competing on break-resistance for point-of-care diagnostics applications.
North America ampoules packaging denotes hermetically sealed single-dose containers, typically fabricated from borosilicate glass tubing via flame-forming processes achieving wall thickness uniformity of 0.8–1.2mm, designed to preserve sterility and chemical stability of parenteral pharmaceuticals. Glass ampoules retain dominant share in high-value biologics where inertness and barrier performance remain non-negotiable, though polymer alternatives capture growth in pre-filled diagnostic reagents and field-deployable vaccines. Snap-off closure formats lead in emergency medicine and military logistics for rapid access, while crimped configurations dominate institutional pharmacy settings where tamper evidence supersedes speed of administration. Research laboratories represent the fastest-growing end-user channel as cell and gene therapy workflows multiply single-use sterile dosing requirements.
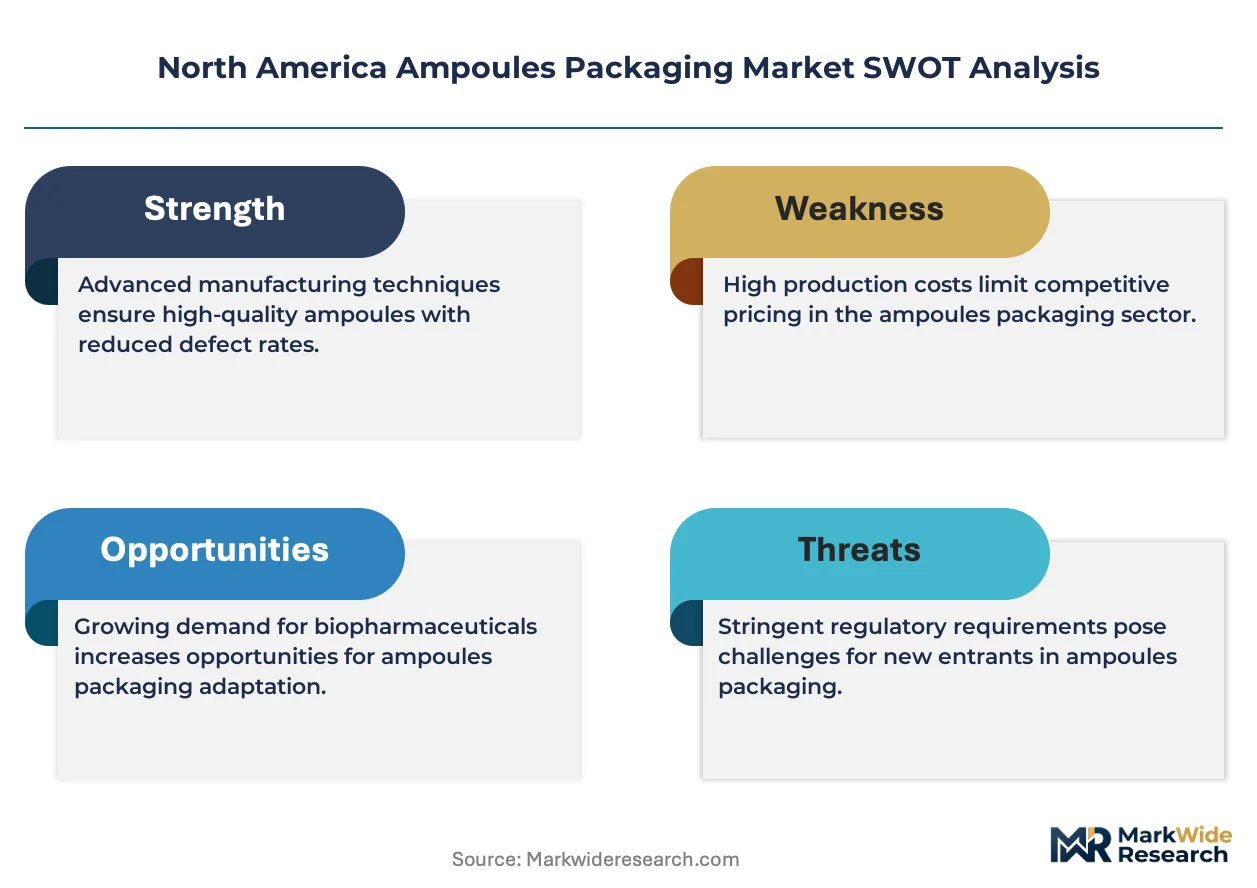
The US FDA enforces container closure integrity testing under guidance for sterile drug products, while Health Canada applies ICH Q3D elemental impurity limits to glass contact surfaces, collectively elevating supplier qualification barriers and consolidation incentives. The EPA's emissions standards for glass-melting furnaces and OSHA silica exposure limits add operational compliance costs that favor larger integrated manufacturers over fragmented converters. Stakeholders must monitor evolving USP <660> glass characterization requirements and state-level pharmaceutical waste regulations as these will determine material substitution timelines and retrofit investment priorities.
Market Dynamics
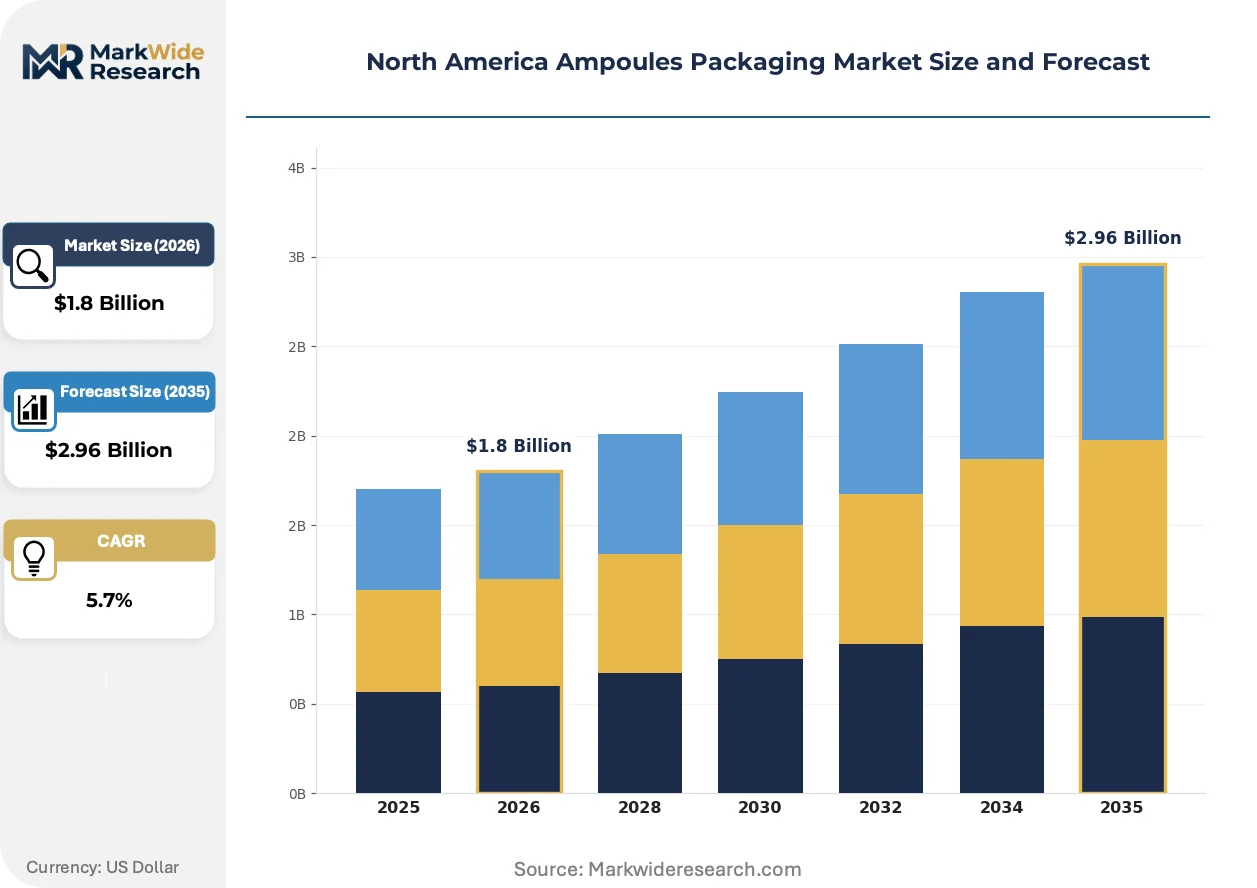
The US FDA's updated container closure integrity guidance is forcing pharmaceutical manufacturers to requalify glass suppliers, compressing the approved vendor list and amplifying pricing power for integrated borosilicate producers with in-house forming capabilities.
Growth Catalysts
- Biologics pipeline expansion:Cell and gene therapy manufacturing in the US Northeast pharmaceutical corridor multiplies single-dose sterile containment requirements.
- Health Canada ICH Q3D alignment:Elemental impurity limits on glass contact surfaces drive premium material upgrades across Canadian parenteral drug packaging.
- Flame-forming automation:Robotic vision systems in borosilicate tubing conversion cut defect rates below 0.3 percent, accelerating throughput for high-value injectables.
Market Restraints
- Energy cost volatility:Natural gas prices for glass-melting furnaces in the US Midwest and Southeast fluctuate 40-60 percent annually, squeezing converter margins.
- Silica supply concentration:High-purity quartz sand for pharmaceutical-grade glass concentrates in limited Appalachian and Canadian Shield deposits.
- Polymer substitution in diagnostics:Cyclic olefin copolymers capture point-of-care reagent applications where break-resistance outweighs barrier performance.
Strategic Opportunities
- Mexico nearshoring:US pharmaceutical manufacturers relocate sterile fill-finish operations to Baja California and Mexico City corridors, creating localized ampoule demand.
- Pre-filled reagent kits:Molecular diagnostics laboratories adopt polymer ampoules for CRISPR-based testing workflows.
- OSHA silica exposure mandates:Stricter workplace safety rules favor suppliers with automated forming lines and enclosed material handling systems.
Industry Challenges
- Glass delamination expertise shortage:Analytical chemists capable of USP <660> surface characterization and predictive modeling command 35-50 percent salary premiums.
- Multi-site qualification complexity:Pharmaceutical buyers require synchronized audits across three to five production facilities for supply security, extending vendor onboarding to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ampoules Packaging Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Plastic, Polymer, Biodegradable End User: Pharmaceuticals, Biotechnology, Diagnostics, Research Laboratories Closure Type: Crimped, Screw Cap, Twist-off, Snap-off Capacity: 1ml, 2ml, 5ml, 10ml |
| Companies Covered | DWK Life Sciences, James Alexander Corporation, SCHOTT AG, SGD Pharma, ESSCO Glass, Gerresheimer AG, Stevanato Group, Adelphi Healthcare Packaging, Nipro Pharma Packaging International NV, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ampoules Packaging Market Shifts & Advancements
Forming-line digitization and predictive analytics are compressing defect detection cycles from batch sampling to real-time intervention, while regulatory stringency on container closure integrity elevates material traceability requirements.
Machine vision systems integrated with flame-forming robotics are automating wall thickness uniformity control during borosilicate ampoule production. US biologics manufacturers with high-speed fill-finish lines adopt these systems to eliminate 100 percent manual inspection bottlenecks. The technology is automating quality assurance labor out of high-volume operations while enabling sub-millimeter precision for complex geometries.
Health Canada's adoption of ICH Q3D elemental impurity limits for glass contact surfaces is elevating supplier qualification barriers. Manufacturers must now document batch-level traceability for boron, aluminum, and alkali metal content. Canadian parenteral drug producers are consolidating vendor relationships to three to five approved suppliers with in-house analytical capabilities.
Subscription-based predictive maintenance contracts for forming equipment are displacing traditional capex ownership models among mid-sized US pharmaceutical packaging operations. Equipment vendors bundle sensor analytics with spare parts logistics, converting upfront investment into operational expenditure. The model is most visible in New Jersey and Massachusetts manufacturing clusters where facility consolidation limits capital allocation flexibility.
North America Ampoules Packaging Market Segmentation
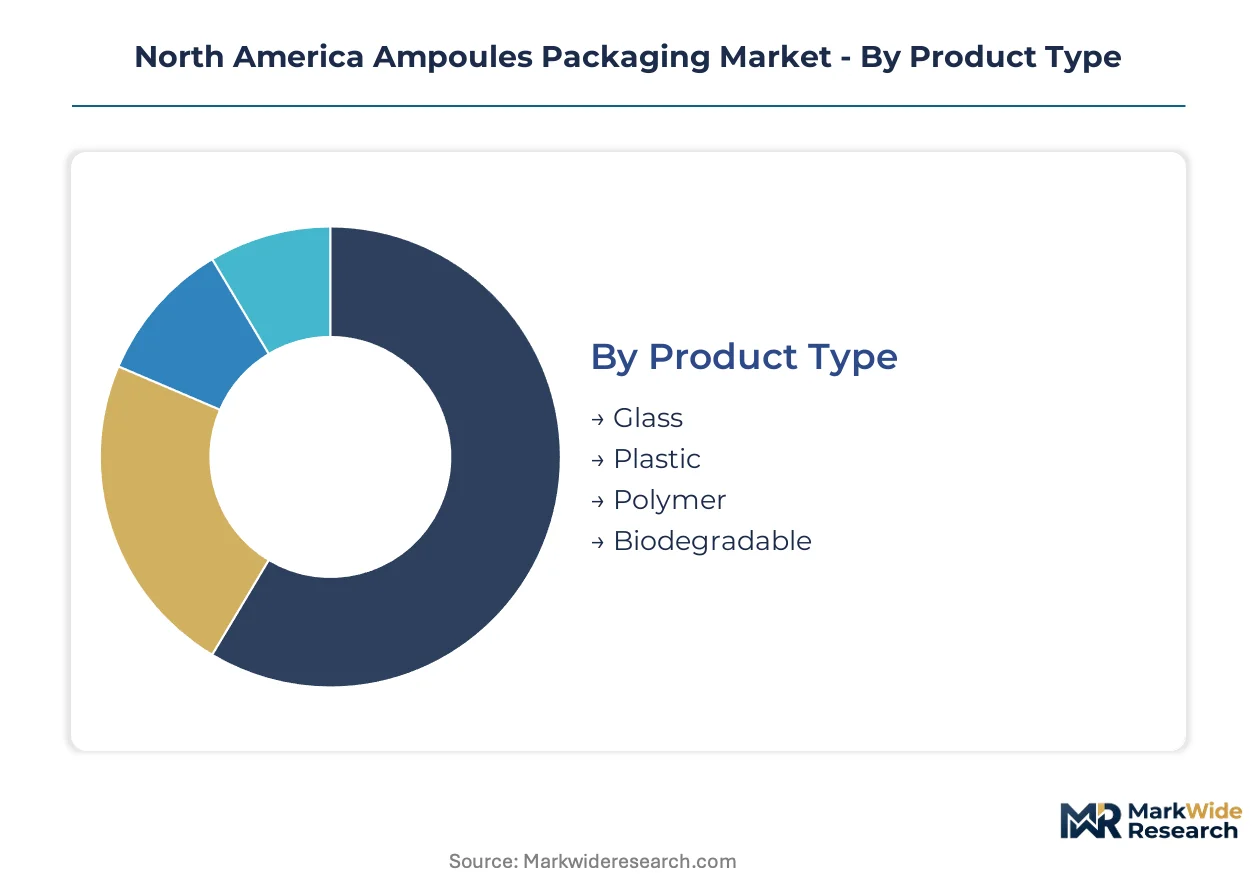
Segmentation in North America ampoules packaging reveals how material science, regulatory compliance, and end-use sterility requirements fragment supply capabilities. Manufacturers must align forming-line investments with specific segment qualification barriers rather than pursuing universal coverage.
Product Type:
Supply concentration in borosilicate glass tubing conversion favors integrated manufacturers with captive sand-to-ampoule capabilities, while polymer alternatives attract specialized compounders with medical-grade resin expertise.
- Glass:Borosilicate formulations achieve wall thickness uniformity of 0.8–1.2mm through flame-forming processes. US Northeast biologics manufacturers demand this segment for parenteral stability where USP <660> surface characterization is mandatory. FDA container closure integrity guidance compresses approved vendor lists toward suppliers with in-house delamination testing.
- Plastic:Cyclic olefin copolymers and polypropylene variants compete on break-resistance for field-deployable applications. Point-of-care diagnostics in Massachusetts and New Jersey manufacturing corridors drive procurement where barrier performance requirements are relaxed.
- Polymer:Specialized barrier coatings on thermoplastic substrates target pre-filled reagent kits. Molecular diagnostics laboratories in the US adopt these for CRISPR-based testing workflows requiring single-use sterility.
- Biodegradable:Emerging polylactic acid and starch-based formulations face qualification barriers for pharmaceutical contact. Research laboratory applications in Canadian cell therapy facilities represent early adoption channels.
Today's leader: Glass. Tomorrow's challenger: Polymer.
End User:
Cost tier differentiation separates validated pharmaceutical supply from research-grade procurement, with biotechnology occupying the premium middle ground requiring GMP compliance without full commercial scale.
- Pharmaceuticals:Sterile injectables manufacturers in New Jersey and Massachusetts corridors impose the most stringent supplier qualification protocols. FDA enforcement of container closure integrity testing extends vendor onboarding to 18–24 months across multi-site audits.
- Biotechnology:Cell and gene therapy producers multiply single-dose containment requirements with smaller batch sizes. US Northeast manufacturing clusters concentrate demand for borosilicate precision where flame-forming automation cuts defect rates below 0.3 percent.
- Diagnostics:Molecular testing laboratories prioritize break-resistance over barrier performance. Polymer ampoules capture growth in pre-filled reagent applications where point-of-care deployment frequency matters.
- Research Laboratories:Cell and gene therapy workflows drive the steepest expansion trajectory in sterile single-use dosing. Canadian and US academic medical centers scale procurement for CRISPR, CAR-T, and stem cell protocols.
Volume concentrates in Pharmaceuticals. Margin concentrates in Biotechnology.
Closure Type:
Application context dictates closure selection, with speed of administration competing against tamper evidence and resealability requirements across institutional versus field settings.
- Crimped:Aluminum seal configurations dominate hospital pharmacy and institutional settings where tamper evidence supersedes access speed. US FDA guidance on container closure integrity favors this format for high-value biologics storage.
- Screw Cap:Threaded polymer or metal closures enable multi-dose access for reagent applications. Diagnostics manufacturers in the US Northeast specify these for laboratory workflows requiring repeated sampling.
- Twist-off:Scored metal or plastic bands balance security with tool-free opening. Military and emergency medicine logistics in the US specify these for rapid field deployment scenarios.
- Snap-off:Pre-scored glass or polymer necks deliver fastest access for single-dose emergency use. First responder and battlefield medicine applications in Canada and the US drive specialized procurement.
Institutional preference: Crimped. Field preference: Snap-off.
Capacity:
Volume scale aligns with dosing standardization in pharmaceutical development, with 2ml and 5ml formats capturing the majority of clinical and commercial fill-finish automation.
- 1ml:Micro-dosing formats serve pediatric vaccines and potent biologics requiring precise unit-dose control. US Northeast biologics manufacturers specify these for high-concentration monoclonal antibody formulations.
- 2ml:Standard clinical trial dosing format aligns with fill-finish line automation across New Jersey and Massachusetts contract manufacturing organizations. This capacity captures the highest procurement volume in pharmaceutical development pipelines.
- 5ml:Commercial scale injectables and vaccine doses concentrate demand in this format. US and Canadian fill-finish operations standardize around 5ml for high-speed production lines.
- 10ml:Larger volume applications include diluents, contrast media, and multi-dose reconstitution scenarios. Hospital pharmacy compounding in the US specifies these for admixture preparation workflows.
Automation standardization centers on 2ml and 5ml. Pediatric and potent dosing drives 1ml specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the dominant share of North American ampoule demand, while Canada and Mexico occupy specialized niches shaped by distinct regulatory frameworks and manufacturing migration patterns.
United States
Cell and gene therapy manufacturing in the Northeast pharmaceutical corridor multiplies single-dose sterile containment requirements. FDA container closure integrity guidance compresses approved vendor lists toward integrated borosilicate producers. New Jersey and Massachusetts manufacturing clusters concentrate fill-finish automation investments for high-value biologics.
Canada
Health Canada ICH Q3D alignment drives premium material upgrades across Canadian parenteral drug packaging. Elemental impurity limits on glass contact surfaces elevate supplier qualification barriers. Toronto and Montreal biologics facilities consolidate vendor relationships to approved suppliers with in-house analytical capabilities.
Mexico
Nearshoring momentum relocates sterile fill-finish operations to Baja California and Mexico City corridors, creating localized ampoule demand. Mexican pharmaceutical regulators align with international GMP standards to attract US contract manufacturing. Tijuana and Querétaro industrial parks host expanding medical device and packaging operations.
North America Ampoules Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated glass producers commanding premium positioning in biologics while polymer converters capture diagnostics niches. The vendor base concentrates around three strategic archetypes: captive sand-to-ampoule integrated manufacturers, specialized tubing converters with forming-line automation, and polymer compounders with medical-grade resin expertise. Dominant competitive moves include backward integration into high-purity quartz sourcing and technology licensing for flame-forming robotics.
Among European-origin integrated manufacturers, SCHOTT AG and Gerresheimer AG exemplify the captive production archetype with in-house borosilicate capabilities. James Alexander Corporation represents the polymer specialization vector, occupying a position in break-resistant alternatives for point-of-care applications. These three anchors demonstrate how geographic origin and material focus stratify competitive positioning across pharmaceutical and diagnostic end-uses.
| Leading Market Players |
|---|
| DWK Life Sciences |
| James Alexander Corporation |
| SCHOTT AG |
| SGD Pharma |
| ESSCO Glass |
| Gerresheimer AG |
| Stevanato Group |
| Adelphi Healthcare Packaging |
| Nipro Pharma Packaging International NV |
| Others |
Supply & Pricing Matrix
USP <660> certification tiers bifurcate the North America ampoules packaging market into premium borosilicate supply for biologics manufacturers and commodity-grade alternatives for diagnostics. This certification ladder manifests in three-tier pricing across premium, standard, and economy levels, while simultaneously concentrating supply chain control among integrated glass producers with captive analytical capabilities.
Pricing Analysis
Capacity additions in Mexico and the US Southeast are reshaping price floors for standard-grade polymer ampoules. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated borosilicate for cell therapy from break-resistant cyclic olefin copolymers for point-of-care diagnostics. Cost compression in the standard tier intensifies because Mexican nearshoring expands localized fill-finish capacity. Biotechnology manufacturers show least price sensitivity where USP <660> compliance is mandatory, while diagnostics laboratories prioritize unit economics over barrier performance.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical buyer demand across New Jersey and Massachusetts manufacturing clusters. High-purity quartz sand for pharmaceutical-grade glass concentrates in Appalachian deposits and Canadian Shield mining operations. Borosilicate tubing and flame-forming equipment feed from German and Japanese specialized manufacturers. Single-source vulnerability in high-purity silica supply elevates risk exposure for integrated glass producers. Distribution runs through validated pharmaceutical packaging distributors with temperature-controlled logistics capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America ampoules packaging offers margin expansion through flame-forming automation that compresses defect rates below 0.3 percent, enabling premium pricing for precision biologics containment.
For Market Incumbents: Anticipate polymer substitution threats in molecular diagnostics by deepening backward integration into high-purity quartz sourcing. Consolidate multi-site qualification capabilities to extend vendor onboarding timelines and lock out emerging competitors. Prioritize subscription-based predictive maintenance bundling to convert capital expenditure into recurring revenue streams. For New Entrants and Emerging Players: Begin with biodegradable polylactic acid formulations for Canadian cell therapy research laboratories where pharmaceutical contact barriers remain lowest. Target Mexico nearshoring corridors in Baja California where US pharmaceutical manufacturers seek localized sterile fill-finish partnerships. Lead with break-resistance value propositions for field-deployable vaccine applications. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-site audit requirements extend vendor qualification to 18–24 months, favoring scaled incumbents with analytical chemistry expertise. Five-to-ten year viability hinges on flame-forming robotics capabilities and Health Canada ICH Q3D compliance infrastructure. Target acquisition archetypes include specialized tubing converters with automated forming lines. Watch OSHA silica exposure mandate enforcement as inflection indicator for operational compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Quartz | Captive silica supply secures USP <660> batch traceability for FDA-validated biologics customers. |
| Flame-Forming Robotics Deployment | Machine vision automation eliminates manual inspection bottlenecks for high-speed fill-finish lines. |
| Subscription Predictive Maintenance Launch | Sensor analytics bundling converts capex to opex for capital-constrained New Jersey packaging operations. |
| Mexico Nearshoring Partnership | Baja California sterile fill-finish expansion captures localized demand from US pharmaceutical relocations. |
| Health Canada ICH Q3D Compliance Investment | In-house elemental impurity testing elevates supplier qualification barriers for Toronto biologics facilities. |
Research Methodology
Coverage spans the United States Northeast pharmaceutical corridor, Canada Toronto-Montreal biologics clusters, and Mexico Baja California nearshoring zones, with primary inputs from each. Drug development executives, regulatory affairs leads at FDA and Health Canada, hospital procurement managers, and GPO contracts managers contributed structured interviews. Secondary validation drew from FDA container closure guidance filings, Health Canada ICH Q3D implementation notices, USP <660> glass characterization standards, and OSHA silica exposure regulatory updates. Bottom-up demand modeling triangulated against top-down pharmaceutical production capacity assessments.
Granularity-level framing applied product type segmentation across glass, polymer, and biodegradable formats; end-user segmentation across pharmaceutical, biotechnology, diagnostics, and research laboratory channels; and closure type segmentation across crimped, screw cap, twist-off, and snap-off configurations. CAGRs were derived through volume-weighted growth rate aggregation across these dimensions. Forecast inputs incorporated biologics pipeline expansion trajectories and flame-forming automation adoption curves throughout the projection horizon.
Several conditions sit outside the modeled scope, including potential USP <660> standard revisions, state-level pharmaceutical waste regulation divergence, and natural gas price volatility impacts on glass-melting furnace economics. Forecasts reflect base-case assumptions about regulatory stability and supply chain continuity. Periodic stress-testing of base assumptions is recommended given energy cost volatility and silica supply concentration risks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Pharmaceutical Container Market
Pharmaceutical Packaging
Plastic Vials and Ampoules Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Vials Market
Pharmaceutical Packaging
Medical Flexible Packaging Market
Pharmaceutical Packaging
Single Dose Dispensers Market
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
Pharmaceutical Unit Dose Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmacy Repackaging Systems Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Pots Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Materials Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market