
 Snap Single Dose Dispensers Market | 2026-2036
Snap Single Dose Dispensers Market Size, Share, and Industry Trends Forecast 2026-2036
Snap Single Dose Dispensers Market Analytics
Capital-intensity divergence between automated blow-fill-seal lines and semi-manual thermoforming stations is bifurcating competitive tiers in snap single dose dispensers. AptarGroup, Inc. leverages multi-cavity mold technology to sustain high-volume pharmaceutical contracts across North American and European facilities. Easysnap Co-Packing S.r.l. anchors its position through proprietary snap-open pouch architecture that dominates liquid and semi-solid unit-dose formats in European personal care and pharma co-packing.
Snap single dose dispensers are single-use packaging systems engineered from multi-layer polymer films or pharmaceutical-grade plastics, typically 0.5–5.0 ml in fill volume, designed to deliver pre-measured product through a snap-induced rupture mechanism. Their primary purpose is to eliminate dosing error, extend shelf stability via hermetic seals, and reduce contamination risk in clinical and consumer settings. Manual dispensers occupy the largest volume share due to minimal tooling cost and universal compatibility with existing fill-lines, while Smart formats integrate NFC tags and temperature sensors that command premium positioning in cold-chain biologics. Bio-based material formulations, though nascent, attract capital as pharmaceutical brands face Scope 3 packaging targets under EU Green Deal procurement rules.
The FDA enforces unit-dose labeling and child-resistance standards under 21 CFR, while the EU MDR mandates traceability and material biocompatibility for dispensers contacting implantable or injectable drugs. REACH and RoHS constrain plasticizer and additive selection, pushing converters toward medical-grade PP and cyclic olefin copolymers that satisfy both migration limits and snap-actuation durability. Stakeholders must monitor evolving ESG disclosure requirements under CSRD and decide whether to absorb bio-based resin cost premiums or pass them through contract renegotiations with hospital purchasing consortia.
Market Dynamics
Hospital purchasing consortia in Germany, France, and Italy are consolidating procurement volumes for unit-dose medication protocols, compressing vendor margins while elevating compliance requirements for hermetic seal integrity and child-resistance certification.
Growth Catalysts
- EU MDR traceability mandates:Medical device regulations now require unique device identification on implantable drug contact surfaces, driving dispenser converters toward laser-etched polymer substrates that satisfy both serialization and snap-actuation durability standards.
- Contract packaging networks:European pharmaceutical OEMs are outsourcing precision-dose format production to specialized co-packers with validated blow-fill-seal lines, expanding addressable unit volumes without captive capital deployment.
- Cyclic olefin copolymers:Advanced polymer formulations with ultra-low extractables are penetrating parenteral and ophthalmic applications where glass ampoules previously dominated, enabled by improved moisture barrier performance.
Market Restraints
- Medical-grade PP resin concentration:Feedstock supply for pharmaceutical-compliant polypropylene concentrates among three European petrochemical clusters, exposing converters to force majeure allocation risk during cracker maintenance cycles.
- F-Gas Regulation phase-down:Banned hydrofluorocarbon blowing agents for expanded polystyrene cushioning increase cold-chain shipping costs for temperature-sensitive biologics in unit-dose formats, compressing gross margins on low-value liquid fills.
- Glass ampoule substitution ceiling:Regulatory inertia in Japan's PMDA and China's NMPA maintains preference for borosilicate glass in high-potency injectables, limiting polymer dispenser penetration in Asia-Pacific markets.
Strategic Opportunities
- Smart dispenser convergence:Integration of NFC temperature loggers with snap-rupture mechanisms enables cold-chain verification for mRNA vaccines and cell therapies, commanding 4-6x price premiums over standard formats in biologics distribution.
- Bio-based resin procurement rules:EU Green Deal Scope 3 packaging targets create first-mover advantage for converters with validated PLA and bio-PP supply chains, particularly in hospital purchasing tenders with mandatory sustainability weighting.
- Semi-solid topical expansion:Dermatology and wound care segments in France and Spain are adopting gel and cream-filled snap pouches for outpatient chronic care, displacing traditional tube formats in pharmacy-dispensed regimens.
Industry Challenges
- Multi-cavity mold commissioning timelines:Validation protocols for pharmaceutical-grade blow-fill-seal tooling extend 18-24 months from design freeze to commercial qualification, delaying revenue recognition on capital-intensive line expansions.
- REACH substance inventory alignment:Rapid regulatory updates to restricted substance lists force reformulation of polymer additives mid-contract, requiring re-validation of migration profiles and snap-force consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snap Single Dose Dispensers Market |
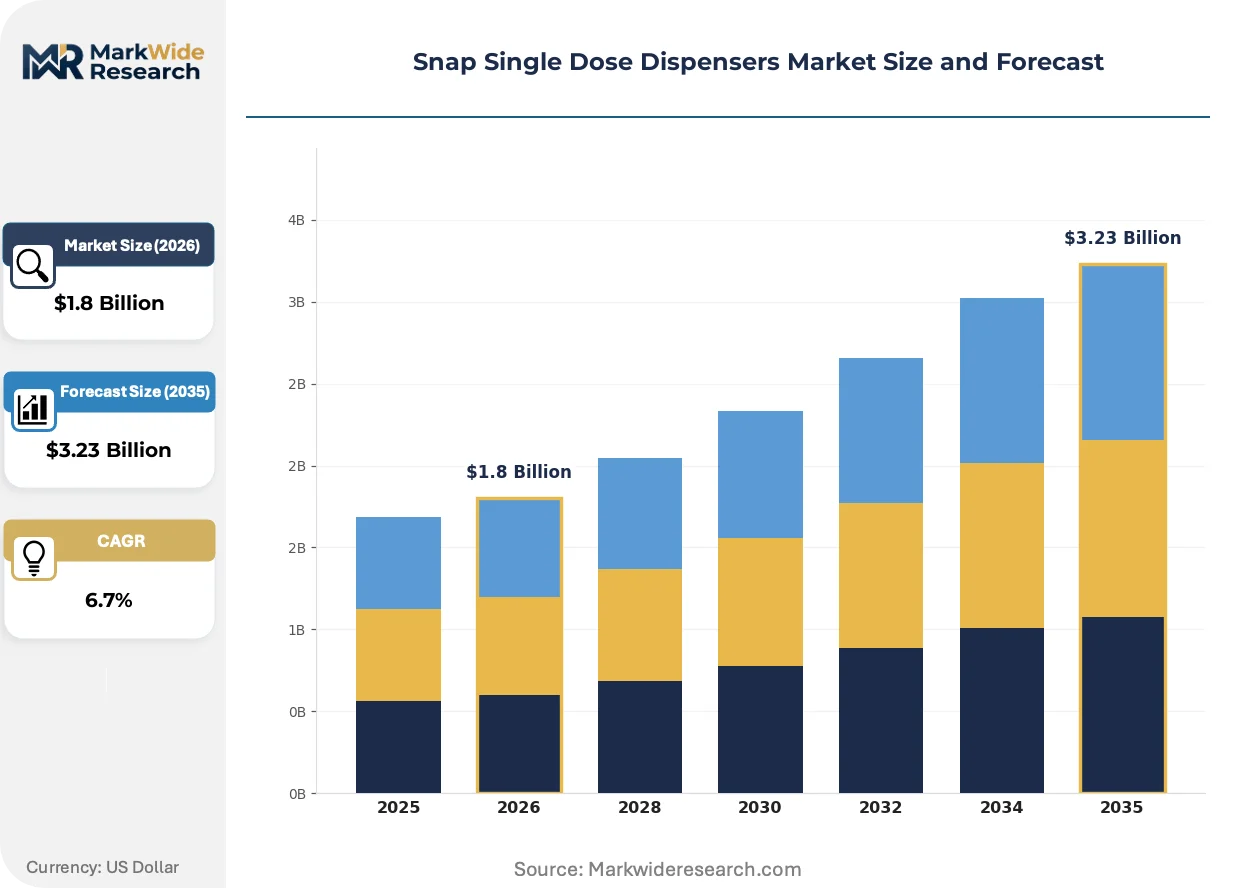
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electronic, Smart, Reusable End User: Hospitals, Clinics, Pharmacies, Home Care Material: Plastic, Glass, Metal, Bio-based Capacity: 1 Dose, 2 Doses, 5 Doses, 10 Doses |
| Companies Covered | Synchpack, Easysnap Co-Packing S.r.l., GH Verpackungen Vertriebs GmbH, Esko, Brand Solutions, KEED AUTOMATIC PACKAGE MACHINERY CO., LTD, AptarGroup, Inc., Unit Pack Company Inc., Gerresheimer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snap Single Dose Dispensers Market Evolving Landscape
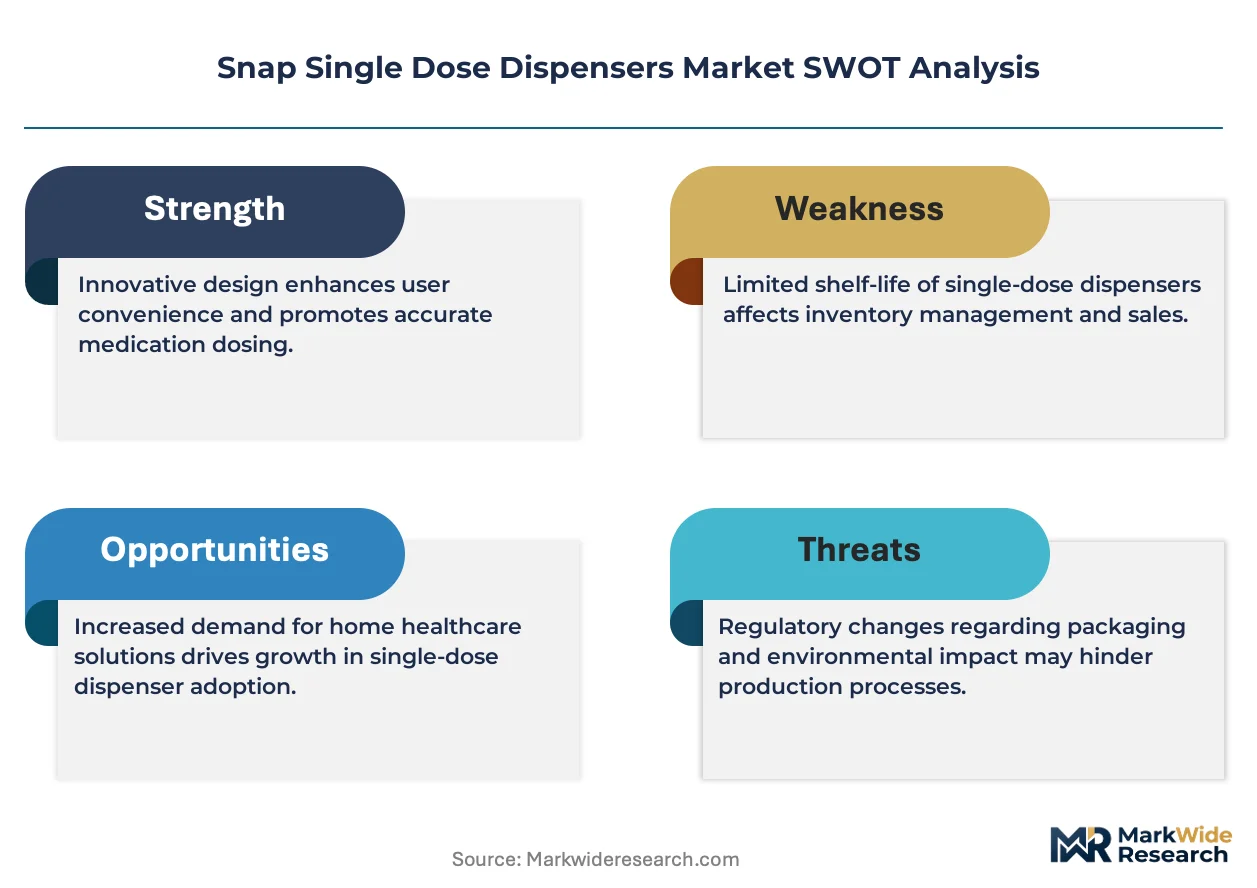
Material science advances and digital integration are reconfiguring the value architecture of single-use dispensing, shifting competitive advantage from pure manufacturing scale toward validated performance data and circular material credentials.
Multi-layer coextrusion with ethylene vinyl alcohol barriers is displacing monolayer polyethylene in moisture-critical pharmaceutical applications. German hospital pharmacies are specifying these structures for hygroscopic tablet packaging, eliminating desiccant sachets and reducing kit complexity. The technology is compressing total cost of ownership for high-value oral solids while extending shelf stability claims.
REACH Annex XVII restrictions on phthalate plasticizers are forcing converters toward citrate and polyester alternatives in flexible snap-pouch formulations. The industrial consequence is elevated raw material cost and reformulation validation burden, particularly for legacy product lines. French and Italian contract packers are responding with dedicated regulatory affairs teams embedded in customer quality agreements.
Hospital purchasing consortia are consolidating supplier panels from 12-15 vendors to 3-4 strategic partners with full-service capabilities. The segment being disrupted is fragmented regional converters without in-house laboratory testing or ESG certification. This concentration is most visible in Germany's university hospital networks, where multi-year framework agreements now mandate carbon footprint disclosure and secondary packaging take-back programs.
Snap Single Dose Dispensers Market Segmentation
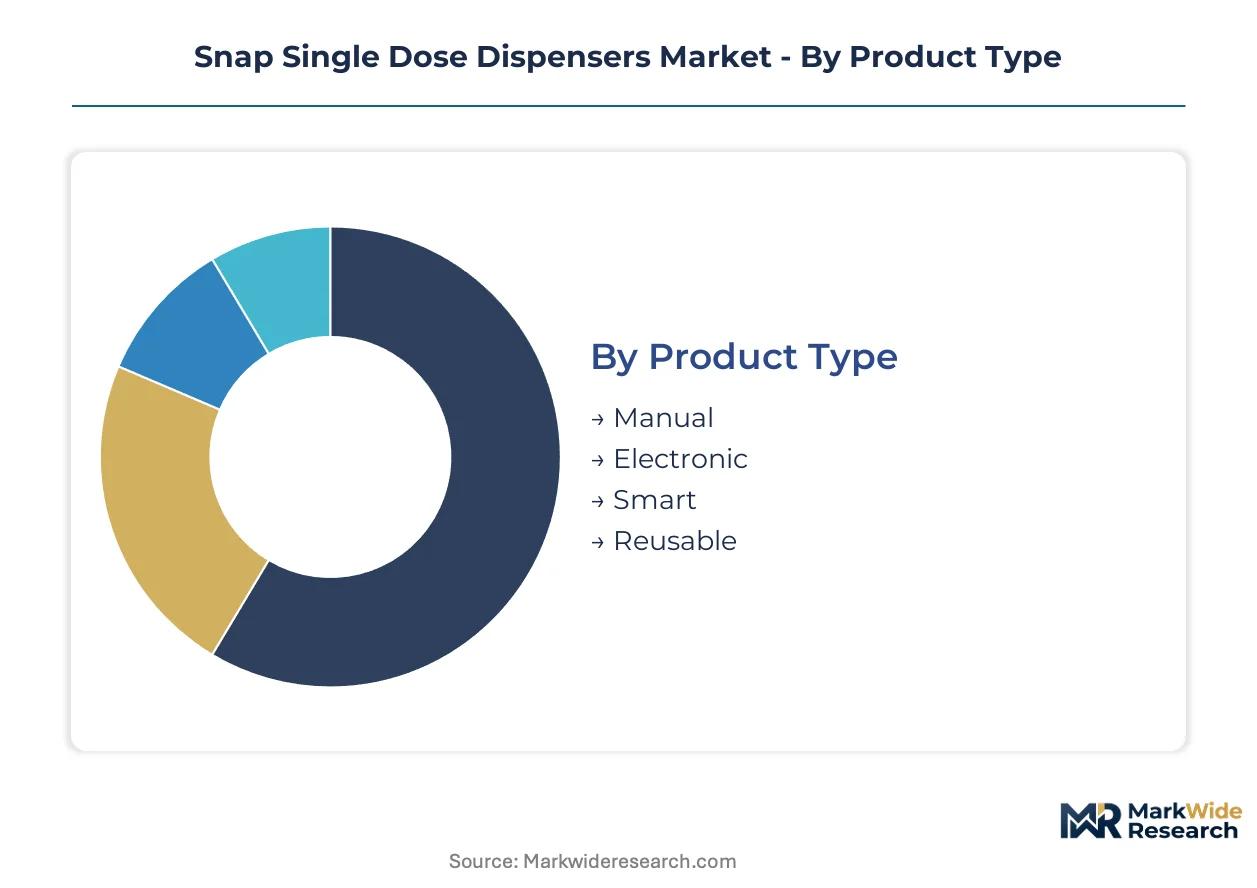
Segmentation in snap single dose dispensers reveals how procurement priorities diverge between cost-sensitive hospital consortia and premium biologics distributors. Margin capture depends on matching material compliance, actuation technology, and dose capacity to specific therapeutic workflows.
Product Type:
Margin pools concentrate in formats that balance validation burden with premium positioning for cold-chain and connected health applications.
- Manual:Polymer pouches and ampoules rely on finger-pressure snap rupture without electronic components. Hospital purchasing consortia in Germany specify these for generic oral solids where tooling simplicity and universal fill-line compatibility compress unit costs.
- Smart:NFC-enabled dispensers integrate temperature loggers and rupture sensors for mRNA vaccine distribution. Cold-chain biologics networks in France and Switzerland absorb 4-6x price premiums for chain-of-custody verification that replaces external data loggers.
- Electronic:Battery-actuated mechanisms with dose confirmation feedback serve ophthalmic and inhalation therapies where patient compliance tracking is mandated. Regulatory validation timelines extend commercialization cycles.
- Reusable:Refillable cartridge systems with replaceable snap-rupture membranes target chronic disease management in outpatient settings. Sustainability credentials attract ESG-weighted tenders.
Manual dispensers hold installed capacity. Smart formats are rotating up the share rankings.
End User:
Volume concentration tracks national healthcare procurement centralization, with framework agreement scale determining converter plant allocation decisions.
- Hospitals:University medical centers and regional hospital networks in Germany, France, and Italy drive standardization toward unit-dose protocols that reduce medication errors and pharmacy labor. EU MDR traceability mandates elevate compliance costs for smaller vendors.
- Home Care:Self-administered chronic therapies in France and Spain adopt gel-filled snap pouches for dermatology and wound care, displacing tube formats with precise-dose convenience.
- Clinics:Outpatient surgical centers prioritize rapid-turn inventory with minimal cold-chain infrastructure, favoring manual formats over connected alternatives.
- Pharmacies:Community dispensing faces margin pressure from centralized hospital procurement, limiting adoption to niche over-the-counter wellness applications.
Hospitals anchor current volume. Home care is expanding most quickly as chronic disease management decentralizes.
Material:
Feedstock selection determines migration profile validation burden and circular economy qualification for EU Green Deal procurement.
- Plastic:Medical-grade polypropylene and cyclic olefin copolymers dominate parenteral and ophthalmic applications with ultra-low extractables. REACH-constrained plasticizer selection forces reformulation cycles that extend validation timelines.
- Bio-based:Polylactic acid and bio-polypropylene variants attract capital as pharmaceutical brands face Scope 3 packaging targets. Early supply chain validation creates first-mover advantage in sustainability-weighted hospital tenders.
- Glass:Borosilicate ampoules retain regulatory preference in Japan and China for high-potency injectables, limiting polymer substitution in Asia-Pacific distribution.
- Metal:Aluminum blister formats serve moisture-critical oral solids with superior barrier performance, though snap-actuation durability lags polymer alternatives.
Plastic maintains production scale. Bio-based formulations are climbing the fastest as procurement rules harden.
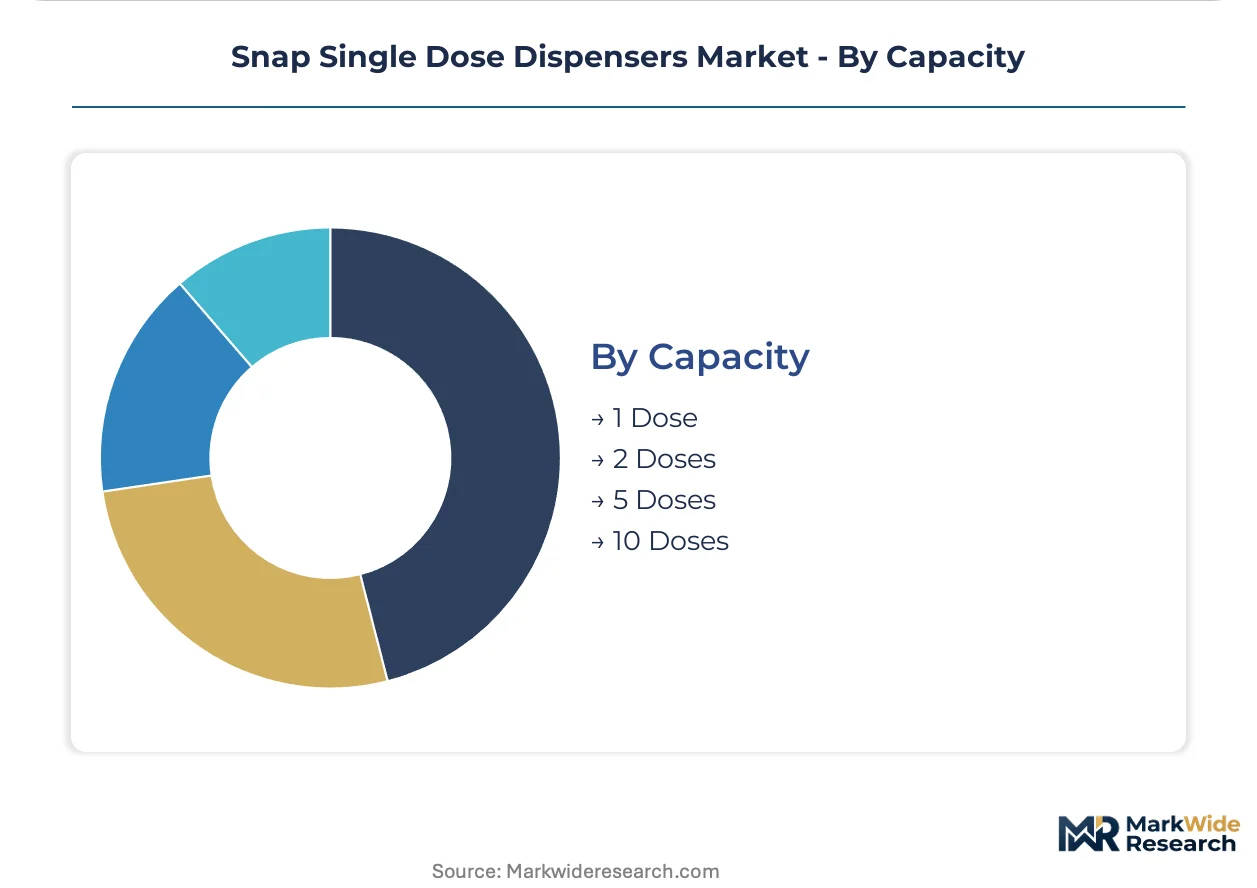
Capacity:
Dose-per-unit configuration aligns with therapy duration and inventory velocity requirements across acute and chronic care pathways.
- 1 Dose:Single-use ampoules and pouches eliminate cross-contamination risk in hospital acute care and vaccine campaigns. Hermetic seal integrity validation supports shelf stability claims for biologics.
- 2 Doses:Twin-chamber formats serve combination therapies and initial titration protocols in outpatient cardiology and endocrinology.
- 5 Doses:Multi-dose cards balance convenience with controlled substance tracking requirements in pain management and psychiatric applications.
- 10 Doses:Extended-supply formats target stable chronic regimens where pharmacy labor reduction outweighs per-unit packaging cost.
Single-dose units command premium positioning. Five-dose formats are gaining share fastest in chronic care cost containment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's hospital purchasing consortia, while Italian contract packers absorb margin compression from precision-dose format standardization. This asymmetry shapes converter plant allocation across European manufacturing networks.
Germany
University hospital networks in North Rhine-Westphalia and Bavaria consolidate procurement volumes for unit-dose medication protocols. The EU MDR traceability mandates elevate compliance costs for hermetic seal integrity and laser-etched polymer substrates. Blow-fill-seal tooling clusters in Baden-Württemberg sustain high-volume pharmaceutical contracts through multi-cavity mold technology.
France
Dermatology and wound care segments in Île-de-France adopt gel-filled snap pouches for outpatient chronic care, displacing traditional tube formats. REACH Annex XVII restrictions on phthalate plasticizers force reformulation toward citrate alternatives in flexible pouch production. Contract packaging networks around Lyon serve pharmaceutical OEMs with validated precision-dose capabilities.
Italy
Easysnap Co-Packing S.r.l. anchors proprietary snap-open pouch architecture for liquid and semi-solid unit-dose formats in European personal care and pharma co-packing. The F-Gas Regulation phase-down increases cold-chain shipping costs for temperature-sensitive biologics. Emilia-Romagna's packaging machinery corridor hosts specialized converters with blow-fill-seal validation expertise.
United States
FDA enforcement of unit-dose labeling and child-resistance standards under 21 CFR shapes material selection for polymer substrates. Cold-chain biologics distributors absorb premium positioning for smart dispenser formats with integrated temperature verification. New Jersey and Massachusetts clusters concentrate pharmaceutical packaging innovation for mRNA vaccine distribution.
China
NMPA regulatory inertia maintains preference for borosilicate glass in high-potency injectables, limiting polymer dispenser penetration. Domestic converters scale medical-grade polypropylene production for ophthalmic and parenteral applications. Yangtze River Delta manufacturing hubs supply cyclic olefin copolymers with ultra-low extractables profiles.
Snap Single Dose Dispensers Market Competitive Landscape
Concentration sits with diversified packaging conglomerates and specialized co-packing contractors. The vendor base separates into automated blow-fill-seal operators and semi-manual thermoforming stations, bifurcating competitive tiers by capital intensity. Three archetypes dominate: multi-cavity mold technology holders, proprietary snap-architecture specialists, and full-service pharmaceutical converters with integrated regulatory affairs. M&A activity targets validated production capacity, while strategic partnerships secure bio-based resin supply chains for EU Green Deal compliance.
Among European specialists, Easysnap Co-Packing S.r.l. and GH Verpackungen Vertriebs GmbH exemplify the proprietary architecture tier, occupying positions defined by validated snap-rupture mechanisms. AptarGroup, Inc. represents the diversified conglomerate archetype with multi-regional facility networks. Gerresheimer AG anchors the pharmaceutical-grade materials segment, reflecting heritage in medical packaging compliance. Synchpack and KEED AUTOMATIC PACKAGE MACHINERY CO., LTD sit within the machinery and automation supply tier, supporting converter capacity expansion without direct dispenser manufacturing exposure.
| Leading Market Players |
|---|
| Synchpack |
| Easysnap Co-Packing S.r.l. |
| GH Verpackungen Vertriebs GmbH |
| Esko |
| Brand Solutions |
| KEED AUTOMATIC PACKAGE MACHINERY CO., LTD |
| AptarGroup, Inc. |
| Unit Pack Company Inc. |
| Gerresheimer AG |
| Others |
Value Network & Pricing Analysis
Cyclic olefin copolymer substitution for borosilicate glass in parenteral applications simultaneously redraws supply geography toward German polymer clusters and compresses pricing economics for legacy glass-dependent converters. Hospital purchasing consortia exploit this feedstock transition to extract contract concessions from vendors lacking validated COC supply chains.
Pricing Analysis
The customization-premium spread between standard manual dispensers and smart NFC-enabled formats reaches 4-6x multiples in cold-chain biologics distribution. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EU MDR traceability mandates. Cost compression in economy tiers is intensifying because German hospital consortia consolidate vendor panels from 12-15 suppliers to 3-4 strategic partners. Generic oral solid dispensers face acute price sensitivity from centralized procurement, while connected health formats command pricing power from biologics distributors absorbing chain-of-custody premiums.
Supply Chain Analysis
Germany, Belgium, and the Netherlands anchor pharmaceutical-grade polymer compounding and multi-cavity mold fabrication for blow-fill-seal lines. Medical-grade polypropylene, cyclic olefin copolymers, and ethylene vinyl oxygen barrier films constitute critical input dependencies. Single-source vulnerability concentrates in European petrochemical clusters for pharmaceutical-compliant resin grades. Distribution runs through validated contract packaging networks serving pharmaceutical OEMs with precision-dose capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to hospital capital expenditure normalization following EU MDR compliance investment peaks. Procurement consolidation cycles create entry windows for specialized converters.
For Market Incumbents: Secure bio-based resin supply chain validation ahead of EU Green Deal Scope 3 procurement mandates tightening across German university hospital networks. Defensive consolidation of blow-fill-seal capacity in Baden-Württemberg and Emilia-Romagna insulates against margin compression from REACH-driven reformulation cycles. Multi-cavity mold technology holders should deepen regulatory affairs embedding in customer quality agreements to extend contract tenures.
For New Entrants and Emerging Players: Regulatory compliance outsourcing gaps in French and Spanish contract packaging networks present white-space entry points for specialized converters with validated laboratory testing. Home care dermatology segments in Île-de-France and Madrid demonstrate penetrable demand for gel-filled snap pouch formats displacing traditional tubes. Go-to-market positioning through pharmacy-dispensed chronic care pathways bypasses hospital procurement concentration.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap converters with captive multi-cavity mold validation expertise and established pharmaceutical OEM relationships. Long-term viability across the projection horizon rests on circular material credentialing and smart dispenser integration capabilities. The inflection signal to monitor is hospital tender sustainability weighting thresholds crossing mandatory bio-based content floors.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Cavity Mold Capacity Expansion | Baden-Württemberg tooling clusters sustain high-volume pharmaceutical contracts through validated blow-fill-seal lines. |
| Bio-Based Resin Supply Agreement | Polylactic acid and bio-polypropylene procurement secures first-mover advantage in EU Green Deal hospital tenders. |
| Smart Dispenser Platform Integration | NFC temperature logger convergence with snap-rupture mechanisms commands premium positioning in mRNA vaccine distribution. |
| Regulatory Affairs Team Embedding | Dedicated compliance units in French and Italian contract packers accelerate REACH-driven reformulation validation cycles. |
| Hospital System Partnership Framework | Multi-year agreements with German university networks lock in carbon footprint disclosure and secondary packaging take-back programs. |
Research Methodology
Desk research of FDA 510(k) filings, EMA medical device registrations, and REACH substance inventory databases preceded structured interviews with hospital pharmacy procurement directors, pharmaceutical packaging engineers, and contract manufacturing quality leads. Primary fieldwork across German university hospital networks, French dermatology clinics, and Italian co-packing facilities validated secondary trade data and customs records. Bottom-up unit volume estimates from blow-fill-seal line capacity utilization triangulated against top-down pharmaceutical packaging expenditure models.
Variance decomposition across product type, material grade, end-user segment, and regional regulatory cluster shaped the analytical framework. CAGRs derived from logistic adoption curves for smart dispenser formats and linear extrapolation for mature manual segments. Modeled inputs included EU MDR traceability mandate implementation timelines, F-Gas Regulation phase-down cost pass-through coefficients, and hospital procurement consortium consolidation rates.
Underlying assumptions cover sustained polymer substitution momentum in parenteral applications, with deviation risk concentrated in NMPA regulatory inertia prolonging glass ampoule preference in China. Forecasts reflect these conditions with sensitivity bands around bio-based resin cost premium absorption. Recalibration cycles align with material shifts in EU Green Deal procurement rule enforcement and REACH Annex XVII substance restriction updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Roll-On Bottles Market
Packaging Containers
Hinged Food Containers Market
Packaging Containers
Global Food Re Close Pack Market
Packaging Containers
Euro Box Market
Packaging Containers
Can Holders Market
Packaging Containers
Plasma Bottle Market
Packaging Containers
Monobloc Aerosol Cans Market
Packaging Containers
Wide Mouth Bottles Market
Packaging Containers
Non-Corrugated Boxes Market
Packaging Containers
Dispensing Trays Market
Packaging Containers
Pillow Pack Packaging Market
Packaging Containers
Foldable Mailer Box Market
Packaging Containers
Glass Vape Cartridge Market
Packaging Containers
Shipping Mailers Market
Packaging Containers
Cooler Box Market
Packaging Containers
Bottles Market