
 Decoys and Dispensers Market | 2026-2036
Decoys and Dispensers Market Size, Share, and Industry Trends Forecast 2026-2036
Decoys and Dispensers Market Insights
Composite materials are rebalancing traditional metal construction in military decoy systems, trimming weight while preserving aerodynamic stability during high-G dispensing maneuvers. Rheinmetall AG sustains European platform integration leadership through captive flare and chaff production lines in Germany. Elbit Systems Ltd leverages Israeli defense procurement relationships to dominate Middle Eastern countermeasure upgrade cycles. Lacroix Defense anchors naval dispenser architecture with NATO-standard 130mm payload compatibility across frigate programs.
Decoys and dispensers comprise engineered payload delivery mechanisms and simulative targets designed to deceive, distract, or neutralize threat acquisition systems through electromagnetic, infrared, or acoustic signature manipulation. Military-grade dispensers typically integrate with aircraft survivability equipment via MIL-STD-1553 or MIL-STD-1760 databus interfaces, enabling programmable ripple-fire sequences against radar-guided and heat-seeking missiles. Automatic dispensers command the largest installed base among product types due to platform-integrated fire-control automation on fourth- and fifth-generation combat aircraft. Military exercises represent the fastest-growing application segment as joint-force training incorporates live countermeasure expenditure to validate tactics against peer adversary missile simulations. Plastic and polymer-composite materials increasingly displace legacy aluminum housings where weight reduction extends platform range-payload tradeoffs.
The US Department of Defense mandates FAA airworthiness certification for dispenser carriage on military aircraft operating in controlled airspace, while NATO STANAG standards harmonize 55mm and 1x1 inch payload formats across allied inventories. EASA and national European military airworthiness authorities enforce comparable qualification protocols for dispenser integration on Eurofighter Typhoon and Rafale platforms. Stakeholders must monitor evolving threat signatures in hypersonic and dual-band seeker architectures to align decoy spectral output with intelligence community threat assessments.
Market Dynamics
Hypersonic missile proliferation is compressing decoy response timelines and forcing dispenser architectures toward sub-millisecond ripple-fire sequencing against Mach 5+ threats.
Growth Catalysts
- Fifth-generation fighter procurement:F-35 and FC-31 programs drive automatic dispenser integration with integrated avionics suites via MIL-STD-1760 databus protocols.
- Electronic warfare survivability mandates:NATO STANAG 4687 standardization harmonizes payload formats across allied rotary-wing and fixed-wing platforms.
- Live-fire training expansion:Joint-force exercises validate countermeasure tactics against peer-adversary missile simulations, accelerating peacetime expenditure cycles.
Market Restraints
- Specialized pyrotechnic input concentration:Magnesium-Teflon-Viton flare compositions depend on Chinese rare earth processing for spectral output consistency.
- Airworthiness certification friction:FAA certification requirements for military aircraft operating in controlled airspace extend dispenser integration timelines by 18-24 months.
- Dual-band seeker substitution threat:Russian and Chinese missile programs field simultaneous radar-infrared homing that reduces single-spectral decoy effectiveness.
Strategic Opportunities
- Naval platform underpenetration:Surface combatant dispenser retrofit programs lag aviation counterparts, creating upgrade cycles for 130mm NATO-standard naval architectures.
- Directed infrared countermeasure convergence:Laser-based jamming systems paired with kinetic decoys offer layered defense against imaging infrared seekers.
- US Department of Defense electronic warfare modernization:The Department's emphasis on survivability equipment procurement prioritizes platform-integrated dispenser suites in budget cycles.
Industry Challenges
- Systems integration talent scarcity:MIL-STD-1553 and MIL-STD-1760 databus programming expertise concentrates among legacy defense contractors, constraining new entrant participation.
- Hypersonic threat intelligence latency:Decoy spectral output calibration depends on classified threat signature databases with restricted distribution timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decoys and Dispensers Market |
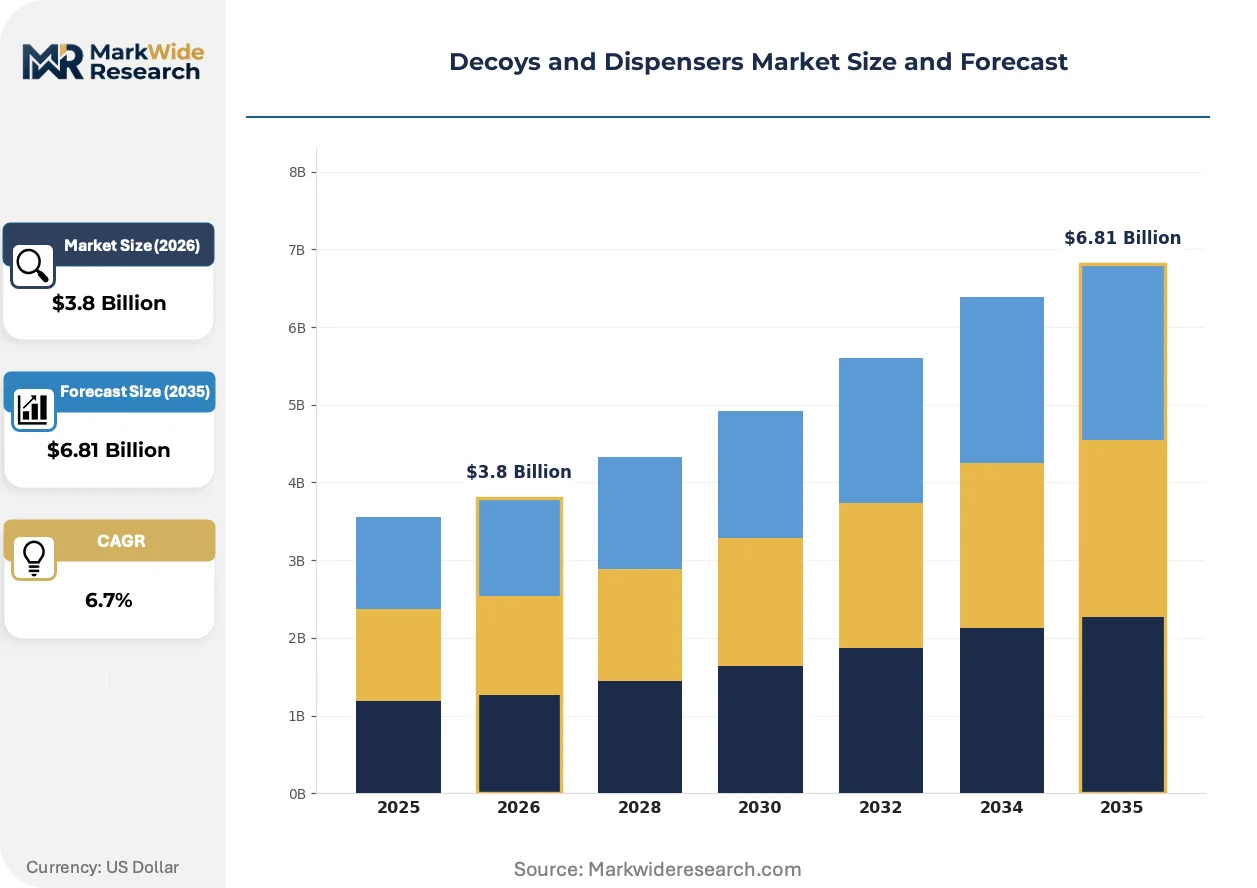
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Decoys, Automatic Dispensers, Manual Dispensers, Motion Decoys End User: Hunting Enthusiasts, Wildlife Conservation, Military Personnel, Research Institutions Material: Plastic, Metal, Wood, Foam Application: Hunting, Wildlife Observation, Training, Military Exercises |
| Companies Covered | BAE Systems plc, Chemring Group PLC, Elbit Systems Ltd, Rheinmetall AG, Armtec Defense Technologies, Leonardo SpA, Lacroix Defense, Northrop Grumman, Raytheon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decoys and Dispensers Market Trends and Innovations
Signature manipulation technologies are bifurcating toward multispectral coherence and miniaturized payload dispersion, redefining platform survivability architectures across combat aviation and naval surface fleets.
Polymer-composite dispenser housings are expanding into fourth-generation fighter upgrade programs and unmanned combat air vehicle designs. Rheinmetall and Elbit Systems have accelerated composite adoption in German and Israeli platform retrofits. This material transition is expanding into high-G maneuver envelopes previously restricted to aluminum construction, compressing weight-payload tradeoffs for extended-range missions.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing reformulation of pyrotechnic binder chemistries in European decoy production. Manufacturers face reformulation costs for Teflon-based flare compositions while maintaining NATO-standard spectral signatures. French and German defense procurement agencies are responding with accelerated qualification protocols for alternative binder materials in Rafale and Eurofighter Typhoon programs.
Platform operators are consolidating countermeasure procurement under fleet-wide performance-based logistics contracts. Traditional transactional ammunition purchases are yielding to availability-guaranteed service models in US Air Force and Royal Air Force sustainment frameworks. This consolidation is most visible in F-35 program dispenser logistics, where Lockheed Martin primes now bundle decoy resupply with airframe maintenance cycles.
Decoys and Dispensers Market Segmentation
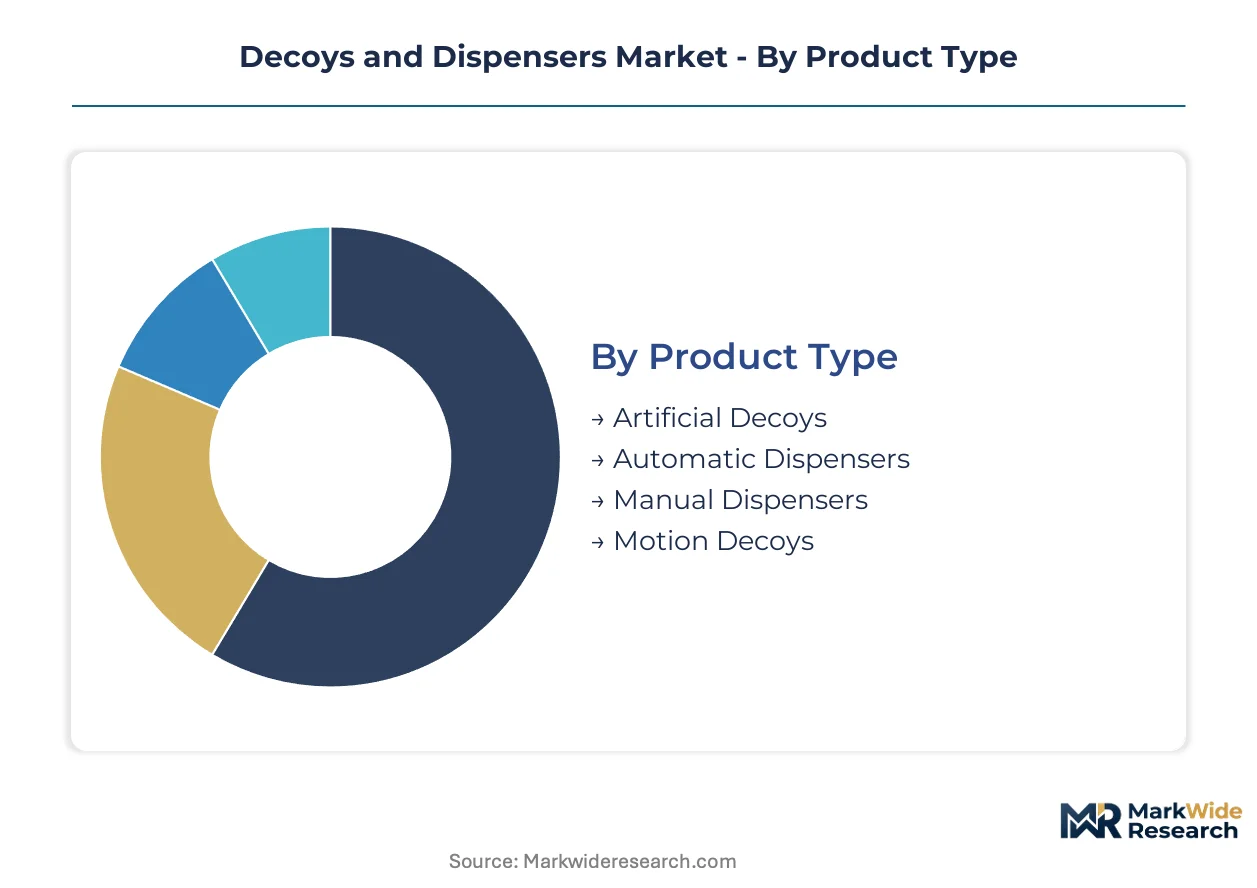
Segmentation in the decoys and dispensers market reveals divergent engineering requirements across civilian and defense applications. Upgrade cycles for platform-integrated military systems operate on fundamentally different timelines than consumable hunting products. Understanding these structural divides illuminates where procurement budgets concentrate and where material innovations transfer across segments.
Product Type:
Replacement cycles vary dramatically between manually operated field equipment and platform-integrated automatic systems, with defense procurement driving premium dispenser architectures.
- Automatic Dispensers:These systems integrate with aircraft avionics via MIL-STD-1553 or MIL-STD-1760 databus interfaces, enabling programmable ripple-fire sequences against radar-guided and heat-seeking missiles. Demand concentrates in United States fighter jet and rotary-wing fleet modernization programs, where the Department of Defense mandates electronic warfare survivability equipment. Fifth-generation platform integration requirements sustain procurement momentum despite extended airworthiness certification timelines.
- Artificial Decoys:Engineered simulative targets manipulate electromagnetic, infrared, or acoustic signatures to deceive threat acquisition systems. Military exercises across NATO members represent the fastest-growing demand source as joint-force training incorporates live countermeasure expenditure to validate tactics against peer adversary missile simulations.
- Manual Dispensers:Hand-deployed countermeasure systems serve rotary-wing and legacy fixed-wing platforms lacking integrated avionics suites.
- Motion Decoys:Kinetic target simulators replicate platform movement signatures for advanced seeker training scenarios.
Automatic dispensers sit at the top of the volume ranking, with artificial decoys climbing the fastest.
End User:
Cost tier stratification separates defense procurement with multi-year platform integration contracts from discretionary consumer purchases with seasonal demand patterns.
- Military Personnel:Defense procurement programs sustain demand for advanced countermeasure dispensers through platform-integrated fire-control automation on fourth- and fifth-generation combat aircraft. The United States anchors volume concentration, where prime contractors bundle decoy resupply with airframe maintenance cycles under performance-based logistics frameworks.
- Hunting Enthusiasts:Consumer-grade decoy systems for game attraction operate on annual replacement cycles with price-sensitive demand elasticity. North American waterfowl and big-game hunting seasons drive concentrated procurement windows, with plastic and polymer-composite materials displacing legacy wood construction for weight and durability advantages.
- Wildlife Conservation:Non-lethal deterrence and population management applications deploy acoustic and visual decoys for species-specific behavioral modification.
- Research Institutions:Academic and governmental wildlife studies utilize standardized decoy protocols for controlled observation methodologies.
Military personnel command the premium pricing tier, while hunting enthusiasts generate the highest transaction frequency.
Material:
Supply concentration in polymer-composite feedstocks is compressing metal's historical dominance across both defense and civilian applications.
- Plastic:Polymer formulations enable rapid manufacturing scalability for high-volume civilian decoy production with weather-resistant properties. Injection molding infrastructure concentrates in East Asian manufacturing clusters serving North American hunting equipment distributors.
- Metal:Aluminum and steel housings persist in high-G military dispenser applications where structural integrity under maneuver stress remains critical. European platform integration programs specify metal construction for captive flare and chaff production lines.
- Wood:Traditional carving materials retain niche demand in artisanal hunting decoy segments with heritage craft associations.
- Foam:Expanded polymer cores reduce shipping costs for bulk civilian decoy distribution with field-assemble designs.
Plastic materials lead production volume, with polymer-composite hybrids gaining share fastest in military weight-reduction programs.
Application:
Customer type divergence between institutional procurement with extended qualification cycles and individual purchase behavior shapes go-to-market architectures.
- Military Exercises:Live-fire training validates countermeasure tactics against peer-adversary missile simulations, accelerating peacetime expenditure cycles. NATO joint-force exercises sustain demand concentration, with the United States Department of Defense prioritizing survivability equipment procurement in budget allocations.
- Hunting:Seasonal game attraction applications drive recurring replacement demand with price-elastic consumer behavior. North American market concentration reflects established hunting culture participation rates and regulatory frameworks governing game management.
- Wildlife Observation:Non-invasive species documentation deploys camouflaged observation decoys for behavioral research protocols.
- Training:Military and civilian instructional programs utilize expendable decoy systems for technique demonstration and skill development.
Military exercises anchor the value concentration, with hunting delivering the broadest geographic distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rheinmetall's production complex in Unterlüss anchors European supply chains for platform-integrated countermeasure systems, while Elbit Systems leverages Israeli procurement relationships to dominate Middle Eastern upgrade cycles. Defense procurement concentration in the United States sustains the largest national market for automatic dispenser integration on fifth-generation combat aircraft.
United States
Fifth-generation fighter fleet modernization and rotary-wing survivability upgrades drive automatic dispenser demand through the Department of Defense's electronic warfare procurement mandates. FAA airworthiness certification requirements extend dispenser integration timelines for military aircraft operating in controlled airspace. Prime contractors in the Dallas-Fort Worth aerospace cluster bundle decoy resupply with F-35 airframe maintenance cycles under performance-based logistics frameworks.
Germany
Captive flare and chaff production lines sustain platform integration leadership for NATO-standard dispenser architectures across Eurofighter Typhoon programs. EU F-Gas Regulation restrictions on fluorinated greenhouse gases force reformulation of pyrotechnic binder chemistries in domestic decoy manufacturing. Rheinmetall's Unterlüss facility anchors composite material adoption in fourth-generation fighter retrofits and unmanned combat air vehicle designs.
Israel
Defense procurement relationships concentrate countermeasure upgrade cycles for Middle Eastern platform operators seeking integrated survivability equipment. National military airworthiness authorities enforce qualification protocols comparable to NATO STANAG standards for dispenser integration on indigenous and imported combat aircraft. Elbit Systems leverages Tel Aviv-area engineering clusters to accelerate composite dispenser housing development for high-G maneuver envelopes.
France
Rafale platform integration requirements sustain demand for NATO-standard 130mm payload compatibility across naval and aviation dispenser programs. Accelerated qualification protocols from the national defense procurement agency address alternative binder materials for EU F-Gas Regulation compliance. Lacroix Defense anchors naval dispenser architecture development from its Saint-Nazaire-area production base for NATO frigate retrofit programs.
United Kingdom
Performance-based logistics consolidation in Royal Air Force sustainment frameworks shifts countermeasure procurement from transactional ammunition purchases to availability-guaranteed service models. Ministry of Defence electronic warfare survivability mandates align with NATO STANAG 4687 standardization for payload format harmonization across allied inventories. BAE Systems' Rochester facility concentrates systems integration expertise for MIL-STD-1553 and MIL-STD-1760 databus programming on fourth-generation combat aircraft.
Decoys and Dispensers Market Competitive Landscape
Global majors compete with regional champions across platform integration capabilities, with consolidated supply chains in aerospace-defense conglomerates coexisting alongside specialized countermeasure producers. Tiered competitive dynamics separate vertically integrated prime contractors from component specialists focused on pyrotechnic payload formulation or dispenser mechanism engineering. Strategic archetypes include systems integrators bundling decoy logistics with airframe maintenance, captive flare producers controlling upstream material supply, and naval architecture specialists dominating maritime dispenser retrofits. Dominant competitive moves encompass backward integration into rare earth processing for spectral consistency and geographic expansion through NATO alliance procurement harmonization.
Among European-based defense conglomerates, Rheinmetall AG and Leonardo SpA exemplify platform integration archetypes spanning captive production and systems engineering. Elbit Systems Ltd represents the Middle Eastern specialist model leveraging regional procurement relationships. BAE Systems plc anchors the Anglo-American systems integrator position. These three companies illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic actions or market shares.
| Leading Market Players |
|---|
| BAE Systems plc |
| Chemring Group PLC |
| Elbit Systems Ltd |
| Rheinmetall AG |
| Armtec Defense Technologies |
| Leonardo SpA |
| Lacroix Defense |
| Northrop Grumman |
| Raytheon Technologies |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FAA airworthiness-qualified military dispensers and commercial off-the-shelf hunting decoys manifests in pricing power concentration among prime contractors with databus integration expertise, while supply chains bifurcate between rare earth-dependent pyrotechnic feedstocks and injection-molded polymer distribution networks serving seasonal consumer demand.
Pricing Analysis
Input-cost pass-through from magnesium-Teflon-Viton flare compositions to finished decoy pricing intensifies as Chinese rare earth processing concentration limits alternative sourcing. Three-tier pricing structure across platform-integrated automatic systems, retrofit upgrade kits, and expendable training rounds reflects certification burden differentiation. Pricing pressure stems from EU F-Gas Regulation reformulation mandates forcing non-recurring engineering costs onto European manufacturers. Military procurement offices exhibit lowest price sensitivity due to survivability equipment budget priority, while hunting enthusiasts demonstrate high elasticity around seasonal replacement cycles.
Supply Chain Analysis
Workforce availability constraints in Tel Aviv-area engineering clusters and Dallas-Fort Worth aerospace corridors concentrate MIL-STD-1553 programming expertise among legacy defense contractors. Manufacturing gravity centers on Germany for Eurofighter Typhoon dispenser architectures, the United States for F-35 integrated suites, and Israel for Middle Eastern upgrade programs. Rare earth oxide supply draws from Chinese processing dominance with single-source vulnerability in spectral consistency inputs. Distribution runs through performance-based logistics frameworks for military end-users and wholesale sporting goods channels for civilian segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Decoys and Dispensers Market compounds steadily as NATO electronic warfare survivability mandates sustain procurement momentum across multi-year platform integration cycles.
For Market Incumbents: Hedge against dual-band seeker substitution threats by accelerating directed infrared countermeasure convergence investments. Lock in rare earth supply through captive offtake arrangements or alternative spectral formulation R&D. Deepen vertical integration into polymer-composite housing production to capture weight-reduction value in unmanned combat air vehicle programs.
For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for alternative pyrotechnic binder qualification as incumbent reformulation costs create temporary supply gaps. Target naval platform retrofit segments where 130mm NATO-standard dispenser architectures remain underpenetrated relative to aviation counterparts. Pursue qualification partnerships with national military airworthiness authorities as the primary go-to-market mechanism.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier systems integrators possessing MIL-STD-1760 databus programming capabilities and existing platform integration relationships. Long-term viability hinges on electronic warfare modernization budget continuity rather than cyclical ammunition procurement. Monitor hypersonic threat intelligence declassification timelines as the critical inflection signal for spectral output calibration technology valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Processing | Captive supply of magnesium-Teflon-Viton spectral formulations reduces Chinese dependency for NATO flare production. |
| Naval Dispenser Retrofit Program Capture | Surface combatant upgrade cycles lag aviation counterparts, creating white-space for 130mm architecture specialists. |
| Composite Housing Manufacturing Scale-Up | Polymer-composite adoption in German and Israeli unmanned combat air vehicle designs compresses weight-payload tradeoffs. |
| Performance-Based Logistics Contract Consolidation | Availability-guaranteed service models displace transactional ammunition purchases in US Air Force and Royal Air Force frameworks. |
| Alternative Binder Material Qualification | EU F-Gas Regulation compliance accelerates French and German defense agency protocols for Teflon-free flare compositions. |
Research Methodology
Coverage spans the United States, Germany, Israel, France, and the United Kingdom, with primary inputs from each defense procurement jurisdiction. Defense procurement officers, platform integration engineers at prime contractors, pyrotechnic formulation chemists, and military airworthiness qualification specialists contributed structured interviews. Secondary validation drew from Department of Defense budget justification documents, NATO STANAG publication archives, EU F-Gas Regulation implementation guidance, and national military airworthiness authority filing records. Bottom-up platform installation forecasts triangulated against top-down defense electronics procurement trend analysis.
Granularity-level modeling disaggregated automatic dispenser demand by fighter jet versus rotary-wing platform type, artificial decoy expenditure by live-fire training versus operational deployment application, and material adoption by aluminum versus polymer-composite housing specification. CAGRs derived from logistic curve fitting against historical procurement cycle patterns and projected fleet modernization timelines. Hypersonic threat response requirements and directed infrared countermeasure pairing adoption served as scenario-weighting inputs across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under classified threat signature database access restrictions or rare earth export control escalations. Assumptions reflect sustained NATO electronic warfare survivability equipment budget priority and continued FAA certification requirement applicability for military aircraft in controlled airspace. Material deviation in hypersonic missile proliferation timelines or dual-band seeker fielding rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Vacuum Skin Packaging Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
Packaging Solutions Market
Packaging Solutions
North America Child Resistant Packaging Market
Packaging Solutions
Strawless Lids Market
Packaging Solutions
India Packaging Market
Packaging Solutions
Middle East and Africa Contract Packaging Market
Packaging Solutions
Anti-Counterfeit Clothing Packaging Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Europe Modified Atmosphere Packaging Market
Packaging Solutions
North America E-Commerce Packaging Market
Packaging Solutions
Stretch Sleeves and Shrink Sleeves Market
Packaging Solutions
Single Dose Packaging Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
Global Shelf Ready Packaging Market
Packaging Solutions
Promotional Packaging Market