
 Pharma Trays Market | 2026-2036
Pharma Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Pharma Trays Market Analytics
European thermoforming capacity is shifting toward high-barrier pharmaceutical grades as cold-chain biologics expand. Amcor plc leverages integrated film-tray platforms to anchor North American supply security. Gerresheimer AG sustains glass-to-plastic conversion programs for parenteral tray formats. Berry Global competes through multi-layer coextrusion scale across Midwestern converting assets.
Pharma trays are thermoformed or die-cut receptacles engineered from PVC, PETG, PP, or aluminum laminates, designed to present, protect, and track unit-dose medications through automated filling lines and distribution networks. Blister trays dominate volume due to compatibility with high-speed form-fill-seal equipment and established barrier validation protocols, while custom trays capture expanding margin pools from personalized medicine and complex combination product presentations. Plastic materials lead unit economics, though aluminum laminates are displacing conventional formats in moisture-sensitive oncology and hormone therapies where WVTR specifications tighten.
FDA 21 CFR Part 211 cGMP requirements and EU MDR technical documentation standards govern tray sterility assurance, material biocompatibility, and lot-level traceability, with EMA notified bodies intensifying post-market surveillance of packaging system changes. The EPA and REACH frameworks restrict phthalate plasticizers and heavy-metal pigments, forcing reformulation of legacy PVC compounds. Stakeholders must monitor evolving pharmacopeial extractables testing protocols and decide whether to internalize tray converting or secure dual-source contract arrangements before qualification timelines lengthen.
Market Dynamics
FDA serialization mandates and EU MDR traceability requirements are compressing qualification timelines and forcing material specification upgrades across pharmaceutical packaging supply chains.
Growth Catalysts
- Cold-chain biologics expansion:Cell and gene therapies requiring ultra-low temperature stability are pulling demand for high-barrier coextruded trays with validated thermal performance.
- EU MDR Article 10 technical documentation:Enhanced post-market surveillance obligations are mandating lot-level traceability systems that integrate directly with tray-level serialization.
- Germany's pharmaceutical manufacturing corridor:Active ingredient production scale in Hesse and Baden-Württemberg tracks directly with blister tray consumption intensity.
Market Restraints
- Specialty resin supply concentration:Cyclo-olefin polymer and high-clarity PETG feedstocks concentrate among Asian petrochemical complexes, exposing converters to freight volatility and allocation limits.
- REACH Annex XVII phthalate restrictions:Legacy PVC compound reformulation requires full requalification of extractables profiles, extending validation cycles by 12-18 months.
- Aluminum laminate cost premium:Moisture-sensitive oncology formulations face 40-60% tray cost escalation versus conventional plastic formats, constraining adoption in price-sensitive therapeutic categories.
Strategic Opportunities
- Personalized medicine packaging:Small-batch combination products and patient-specific dosing regimens are creating margin pools for custom tray formats with integrated compliance features.
- US IRA domestic manufacturing incentives:Production tax credits for pharmaceutical packaging reshoring are attracting thermoforming investment to Midwestern converting corridors.
- RFID-NFC convergence:Embedded sensor trays enabling real-time cold-chain monitoring are opening subscription revenue models beyond commodity unit sales.
Industry Challenges
- Extractables testing protocol evolution:USP <1664> and EP 3.2.2 guideline updates are forcing redundant analytical studies across multiple pharmacopeial jurisdictions.
- Automated line integration complexity:Tray handling system retrofits on legacy form-fill-seal equipment demand specialized mechatronics expertise scarce among contract packagers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharma Trays Market |
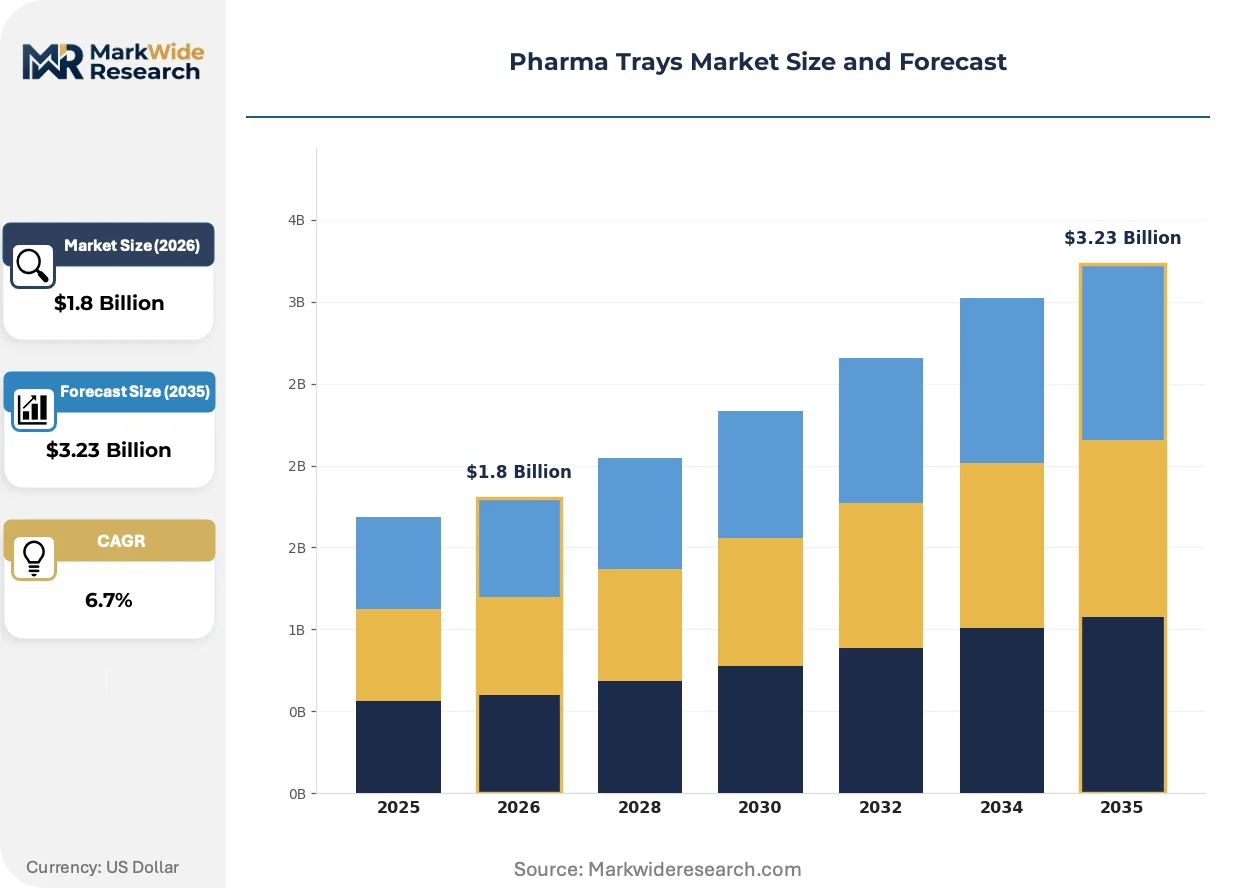
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Trays, Die Cut Trays, Folding Trays, Custom Trays Material: Plastic, Cardboard, Aluminum, Glass End User: Pharmaceutical Companies, Contract Packaging, Research Laboratories, Hospitals Application: Drug Packaging, Sample Distribution, Clinical Trials, Patient Education |
| Companies Covered | Amcor plc, Gerresheimer AG, Schott AG, AptarGroup, Inc., Berry Global, West Pharmaceutical Services, Inc., Sonoco Products Company, Winpak Ltd., Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharma Trays Market Evolving Landscape
Material science advances and regulatory digitization are compressing development cycles while elevating functional performance requirements for pharmaceutical tray systems.
Multi-layer coextrusion with ethylene vinyl alcohol barrier cores is rewriting moisture and oxygen ingress specifications for parenteral and oral solid dose applications. Biologics manufacturers in Switzerland and Massachusetts are specifying these structures for 24-month shelf life targets previously requiring aluminum cold-form foils. The technology is compressing the premium gap between plastic and metal barrier systems.
EU MDR 2017/745 Annex I general safety and performance requirements are mandating design dossier documentation that traces packaging system changes through post-market surveillance. Notified bodies in Germany and the Netherlands are intensifying scrutiny of tray material substitutions previously handled through technical file updates. Mid-sized contract packagers are building regulatory affairs capabilities in-house rather than relying on notified body consultants.
Pharmaceutical procurement teams are consolidating supplier panels around integrated film-tray-platform providers capable of single-source barrier validation. Large molecule manufacturers in Ireland and Singapore are disqualifying converters without in-house analytical testing laboratories. The shift privileges vertically integrated material suppliers over standalone thermoformers in qualification-heavy therapeutic categories.
Pharma Trays Market Segmentation
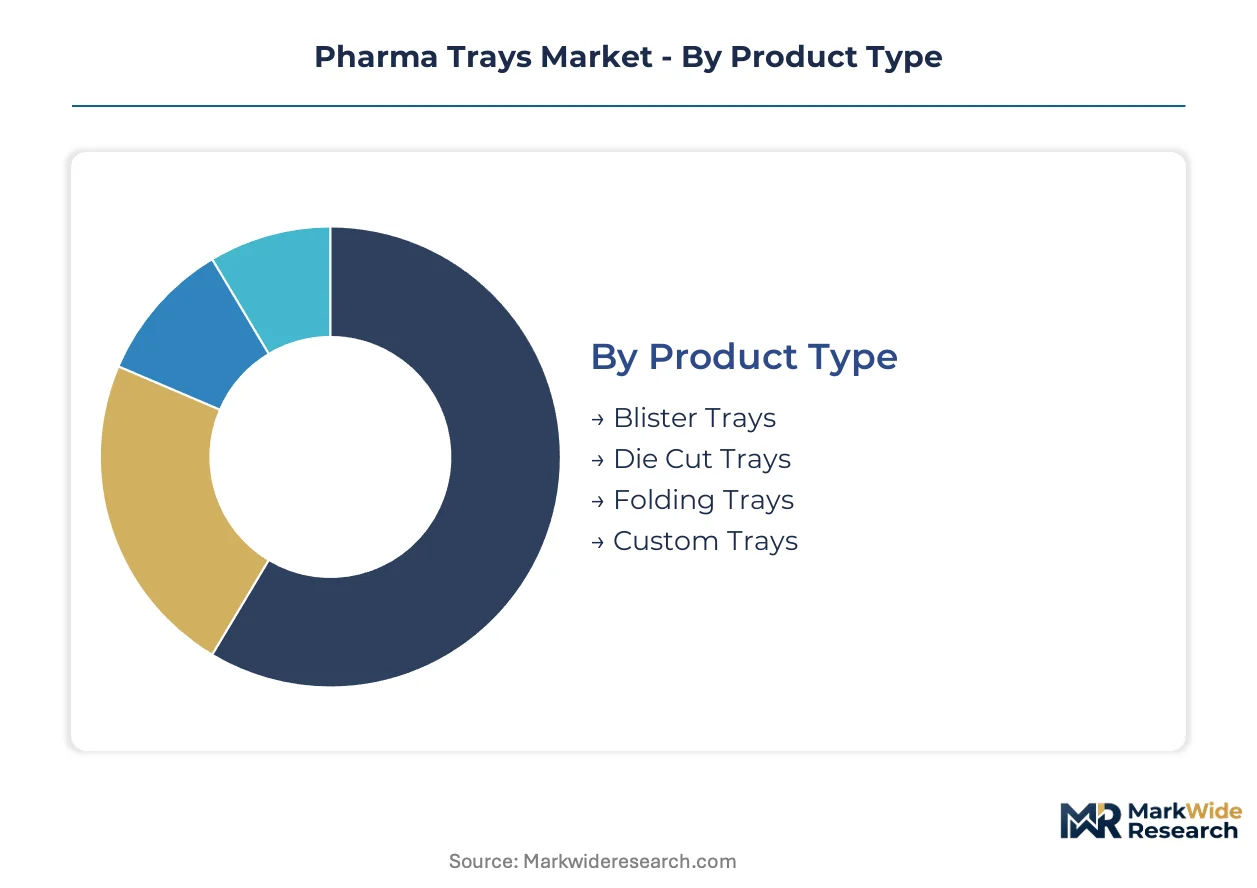
Pharma tray specifications diverge sharply across therapeutic categories and distribution channels. Segment selection determines barrier validation protocols, automation compatibility, and margin capture potential for converters and packagers alike.
Product Type:
Capital deployment varies dramatically by forming technology, with thermoforming lines demanding seven-figure tooling investments versus die-cut alternatives.
- Blister Trays:Thermoformed PVC, PETG, or PP cavities sealed to lidding foil dominate high-volume oral solid dose production. Form-fill-seal automation in Germany's Hesse corridor consumes these formats at rates exceeding 600 units per minute.
- Custom Trays:Patient-specific combination products and complex biologic presentations require bespoke cavity geometries and integrated compliance features. Massachusetts cell therapy manufacturers are specifying these for autologous treatment workflows.
- Die Cut Trays:Flat-sheet converting with pressure-sensitive assembly suits low-volume specialty pharmaceuticals.
- Folding Trays:Carton-based formats serve sample distribution and physician detailing kits.
Blister trays absorb the bulk of installed capacity; custom trays are expanding most quickly.
Material:
Raw material selection locks in barrier performance tiers and regulatory qualification pathways.
- Plastic:Multi-layer coextrusions with EVOH barrier cores are displacing monolayer structures in moisture-sensitive applications. Swiss biologics manufacturers specify these for 24-month shelf life targets.
- Aluminum:Cold-form laminates deliver sub-0.01 g/m²/day WVTR for oncology and hormone therapies. The 40-60% cost premium over plastic constrains adoption outside high-value therapeutic categories.
- Cardboard:SBS and CUK grades support secondary packaging and educational inserts.
- Glass:Borosilicate and molded formats persist in parenteral applications requiring inert contact surfaces.
Plastic commands the widest installed base; aluminum is gaining share fastest in barrier-critical segments.
End User:
Procurement sophistication and volume scale separate customer tiers.
- Pharmaceutical Companies:Integrated manufacturers in Ireland and Singapore are consolidating supplier panels around film-tray platform providers with in-house analytical laboratories. Direct qualification of barrier systems reduces supply chain risk for large molecule portfolios.
- Contract Packaging:Mid-sized packagers in the US Midwest are retrofitting automated tray handling systems to capture serialization-mandated volume. EPA and FDA cGMP compliance investments are widening competitive moats.
- Research Laboratories:Preclinical and Phase I material handling drives small-batch demand.
- Hospitals:Unit-dose repackaging for pharmacy operations requires compliance-ready formats.
Pharmaceutical companies anchor volume commitments; contract packaging is climbing the fastest as outsourcing accelerates.
Application:
Use case determines sterility assurance levels and traceability integration depth.
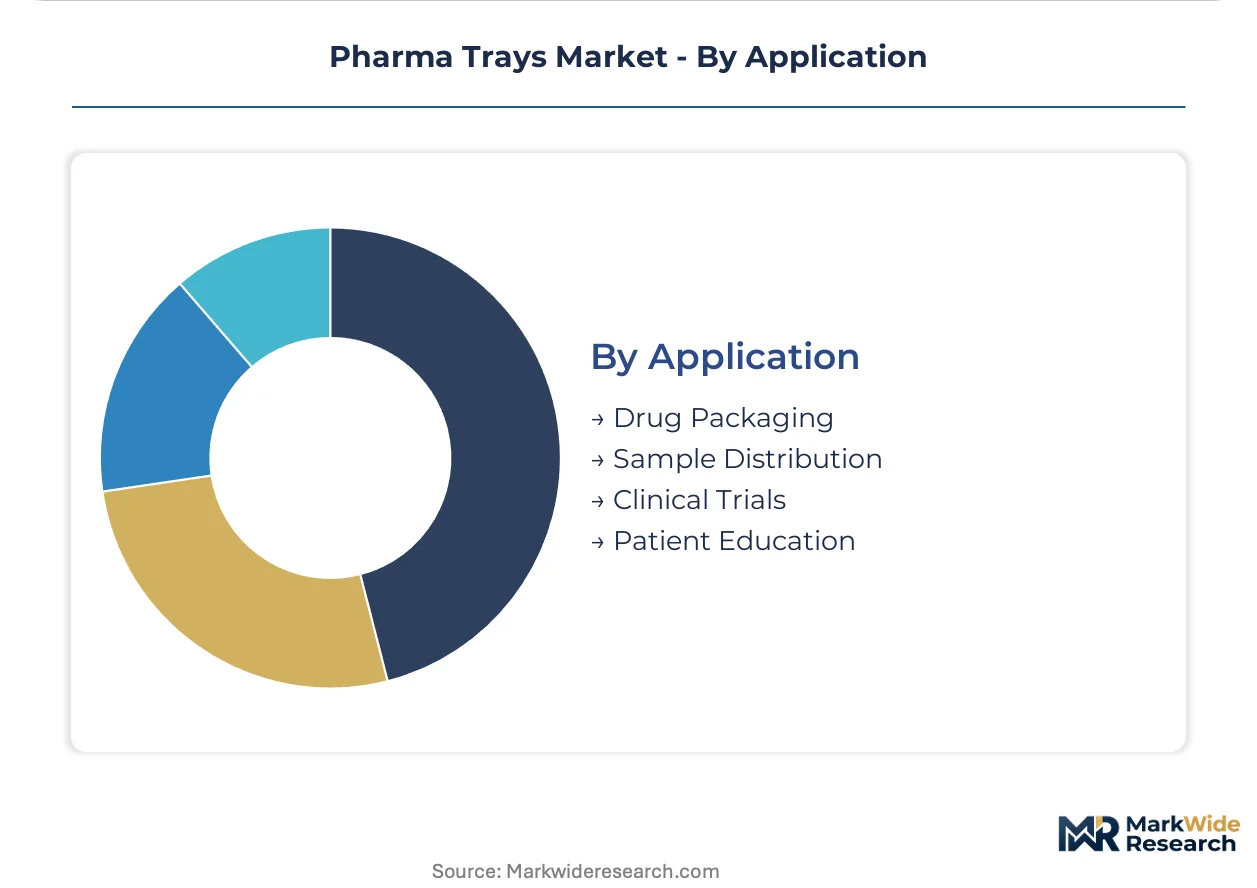
- Drug Packaging:Commercial oral solid dose and parenteral presentations must satisfy FDA 21 CFR Part 211 and EU MDR Annex I requirements. Serialization mandates are forcing lot-level traceability system upgrades across all formats.
- Clinical Trials:Investigational medicinal product supply chains demand patient-specific dosing and blinding capabilities. Temperature excursion logging is becoming standard for biologic trial materials.
- Sample Distribution:Physician detailing kits prioritize shelf presence and compliance messaging.
- Patient Education:Adherence packaging integrates dosing calendars and instructional graphics.
Drug packaging dominates revenue contribution; clinical trials show the steepest expansion trajectory as trial complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty resin feedstocks for pharmaceutical-grade thermoforming concentrate in Germany's chemical corridor and the US Gulf Coast petrochemical complex, with downstream converting capacity clustering near major drug manufacturing hubs.
United States
FDA serialization mandates under DSCSA and IRA domestic manufacturing incentives are accelerating thermoforming investment in Midwestern converting corridors. The EPA's evolving extractables testing guidance is extending qualification timelines for new material introductions. Massachusetts cell therapy manufacturers are specifying custom tray formats for autologous treatment workflows.
Germany
EMA notified bodies in Germany are intensifying post-market surveillance of packaging system changes under EU MDR 2017/745. REACH Annex XVII phthalate restrictions are forcing legacy PVC compound reformulation across Hesse and Baden-Württemberg. Blister tray consumption in these states tracks directly with active ingredient production scale.
Switzerland
Swissmedic's stringent pharmacopeial standards are elevating barrier performance requirements for biologics manufacturers. The country's dual focus on precision manufacturing and cold-chain logistics is pulling demand for high-barrier coextruded trays. Basel's pharmaceutical cluster specifies EVOH-core structures for 24-month shelf life targets.
India
CDSCO's alignment with ICH Q1A stability guidelines is elevating packaging validation protocols for export-oriented formulations. The PLI scheme for pharmaceutical manufacturing is expanding domestic blister packaging capacity. Gujarat and Maharashtra are emerging as thermoforming hubs serving both domestic and European markets.
Singapore
The Health Sciences Authority's adoption of FDA-equivalent cGMP standards is attracting large molecule manufacturers requiring integrated film-tray platforms. The country's biologics manufacturing tax incentives are consolidating supplier panels around converters with in-house analytical laboratories. Tuas Biomedical Park anchors regional demand for serialization-ready formats.
Pharma Trays Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized barrier technologies and regional contract packaging partnerships. The vendor base stratifies between integrated material suppliers with captive resin streams and standalone thermoformers dependent on merchant feedstock. Three archetypes dominate: film-tray platform integrators, high-barrier specialists, and regional contract packaging networks. Competitive moves concentrate on M&A for analytical testing capabilities and capacity expansion near IRA-incentivized US manufacturing zones.
Among integrated packaging conglomerates, Amcor plc and Berry Global exemplify the film-tray platform model with upstream control over multi-layer coextrusion assets. Gerresheimer AG occupies a position bridging glass-to-plastic conversion expertise with parenteral format specialization. These three anchors represent divergent strategic postures—global scale integration, regional manufacturing density, and therapeutic-category depth—rather than direct segment overlap.
| Leading Market Players |
|---|
| Amcor plc |
| Gerresheimer AG |
| Schott AG |
| AptarGroup, Inc. |
| Berry Global |
| West Pharmaceutical Services, Inc. |
| Sonoco Products Company |
| Winpak Ltd. |
| Sealed Air Corporation |
| Others |
Value Network & Pricing Analysis
Barrier-performance certification tiers split the market into three distinct purchasing strata, with FDA-validated aluminum laminates commanding substantial premiums over standard PVC formats and forcing buyers into dual-source qualification strategies that reshape supplier relationships. This divergence propagates through supply chains as pharmaceutical manufacturers consolidate purchasing around integrated film-tray platforms capable of single-source validation, while commodity converters face margin compression from REACH-mandated reformulation cycles.
Pricing Analysis
Warranty and validation-bundling separates pricing tiers, with premium suppliers including extractables testing documentation and lot-level traceability systems in contracted rates while economy converters unbundle these as add-on services. Three-tier pricing structure across premium, standard, and economy levels reflects barrier performance specifications and regulatory certification depth. Cost compression in standard plastic tiers is intensifying because REACH Annex XVII phthalate restrictions force legacy compound reformulation. Contract packaging organizations exhibit highest price sensitivity due to thin margins on high-volume oral solid dose contracts, while cell therapy manufacturers in Massachusetts show lowest sensitivity given patient-specific workflow requirements.
Supply Chain Analysis
Reverse-logistics for tray returns and material recovery remains underdeveloped, with most converters lacking closed-loop infrastructure for post-industrial scrap from thermoforming operations. Geographic supply concentration centers on Germany's chemical corridor for specialty resin feedstocks, the US Gulf Coast for petrochemical derivatives, and China's Yangtze River Delta for high-clarity PETG. Raw material dependencies draw from cyclo-olefin polymer, ethylene vinyl alcohol barrier resins, and pharmaceutical-grade PVC compounds. Single-source vulnerability concentrates in Asian petrochemical complexes for specialty grades. Distribution runs through direct mill relationships for large pharmaceutical manufacturers and regional distributors for mid-sized contract packagers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Upstream control over multi-layer coextrusion assets and captive analytical testing laboratories defines the current vertical-integration race, as qualification-heavy therapeutic categories reward converters with in-house barrier validation capabilities.
For Market Incumbents: Lock in pharmaceutical company relationships by securing dual-source qualification status before EU MDR timelines lengthen, and expand thermoforming capacity in IRA-incentivized Midwestern corridors to capture domestic manufacturing reshoring volume. Emerging entrants with RFID-NFC embedded sensor capabilities threaten premium positioning. Backward integration into specialty resin streams anchors margin defense. For New Entrants and Emerging Players: Launch via direct partnerships with Massachusetts and Basel cell therapy manufacturers seeking custom tray formats for autologous treatment workflows. Patient-specific combination products represent the most penetrable white-space segment. Target mid-sized contract packagers retrofitting automated handling systems for serialization compliance as the initial beachhead. For Investors and Strategic Acquirers: Re-rating potential sits with converters possessing in-house USP <1664> extractables testing laboratories given EMA intensification of post-market surveillance. Long-term viability favors vertically integrated film-tray platforms over standalone thermoformers. Watch for CDSCO alignment with ICH stability guidelines as inflection signal for Indian export-oriented capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-layer Coextrusion Capacity Expansion | Swiss biologics manufacturers specify EVOH-core structures for extended shelf life targets. |
| Backward Integration into Specialty Resins | Cyclo-olefin polymer supply concentration in Asian complexes creates captive sourcing advantages. |
| In-house Analytical Laboratory Buildout | Irish and Singaporean large molecule manufacturers disqualify converters without USP <1664> capabilities. |
| RFID-NFC Embedded Sensor Development | Real-time cold-chain monitoring opens subscription revenue models beyond commodity unit sales. |
| Midwestern US Manufacturing Footprint | IRA production tax credits attract thermoforming investment near pharmaceutical packaging reshoring zones. |
Research Methodology
Multi-period observation of FDA 483 inspection trends, EU MDR notified body guidance updates, and pharmaceutical packaging capex announcements anchored the trend analysis, supplemented by interviews with regulatory affairs directors, contract packaging operations managers, and pharmaceutical procurement leads. Secondary validation drew from FDA 510(k) filings, EMA post-market surveillance reports, and SEC 10-K disclosures from integrated packaging conglomerates. Bottom-up thermoforming capacity estimates and top-down pharmaceutical production value allocations were triangulated to cross-check segment sizing.
Segment-weighting across product type, material grade, end-user sophistication, and therapeutic application governed the analytical framework. CAGRs were derived from regression analysis of historical volume relationships with active ingredient production indices across the analysis window. Forecast inputs incorporated cold-chain biologics pipeline data and serialization mandate implementation timelines by regulatory jurisdiction.
The model assumes a particular technology adoption path for multi-layer coextrusion; alternative pathways for aluminum cold-form foil displacement would alter the outlook for plastic barrier penetration. Forecasts reflect assumptions regarding REACH enforcement consistency and IRA incentive continuity. Material deviation in CDSCO regulatory alignment or specialty resin allocation limits warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market
Pharmaceutical Packaging
North America Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Vial Fillers Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Vials Market
Pharmaceutical Packaging
Pharmaceutical Tubes Market
Pharmaceutical Packaging
Pharmaceutical Plastic Pots Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
Polymer Vials Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Pharmaceutical Secondary Packaging Market
Pharmaceutical Packaging
Temperature Controlled Pharmaceutical Containers Market
Pharmaceutical Packaging
Pharmaceutical Labeling Market
Pharmaceutical Packaging
Pharmaceutical Vials Market