
 Recycled Prescription Bag Market | 2026-2036
Recycled Prescription Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Prescription Bag Market Analytics
Pharmaceutical wholesaler networks are rewriting procurement standards for single-use pharmacy packaging. Novolex leverages captive recycling infrastructure to secure long-term contracts with national drugstore chains. Smurfit Kappa anchors European supply through integrated paperboard mills serving hospital dispensaries. Huhtamaki competes in biodegradable plastic laminates for temperature-sensitive prescriptions.
Recycled prescription bags are engineered from post-consumer paper pulp or reprocessed polyethylene resin, typically incorporating tamper-evident seals and moisture-resistant barrier coatings to protect medication integrity during patient transport. Paper-based designs dominate hospital system tenders where FDA packaging guidance favors fiber-based alternatives, while biodegradable plastic variants are gaining fastest in online pharmacy cold-chain shipments requiring grease and moisture resistance. Flat bags occupy the mature volume tier for standard tablet dispensing, whereas zippered configurations capture margin pools in specialty pharmacy segments handling controlled substances.
FDA packaging guidance shapes material selection for US pharmacy chains, while the EU Green Deal drives fiber-content minimums across German and French dispensaries. Japan's METI circular economy standards enforce post-consumer recycled ratios for retail pharmacy bags. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and decide between regional material certification or unified global formulation strategies.
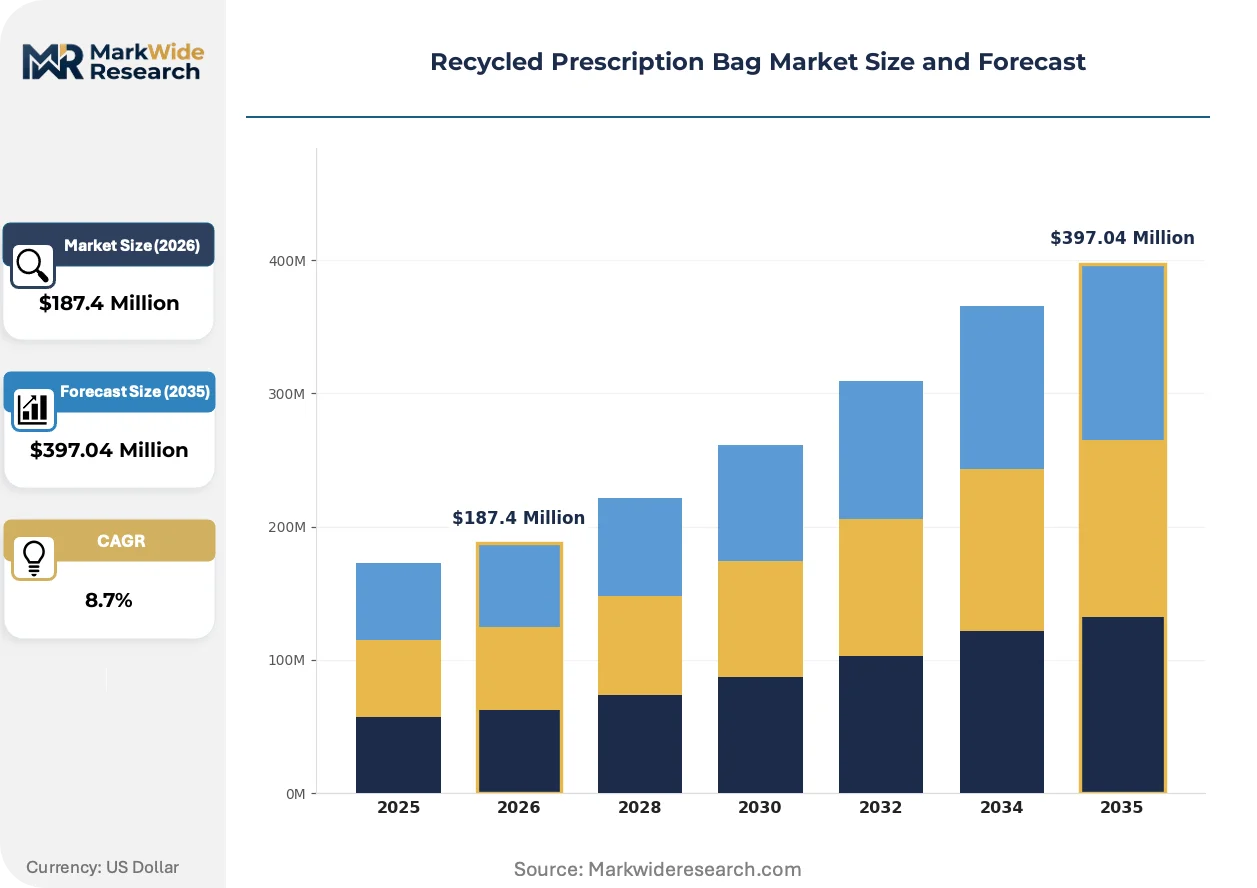
Market Dynamics
Chain pharmacy procurement mandates are forcing material specification changes across the recycled prescription bag supply base. Hospital systems and retail dispensaries now require certified post-consumer content thresholds that filter supplier eligibility before price negotiation begins.
Growth Catalysts
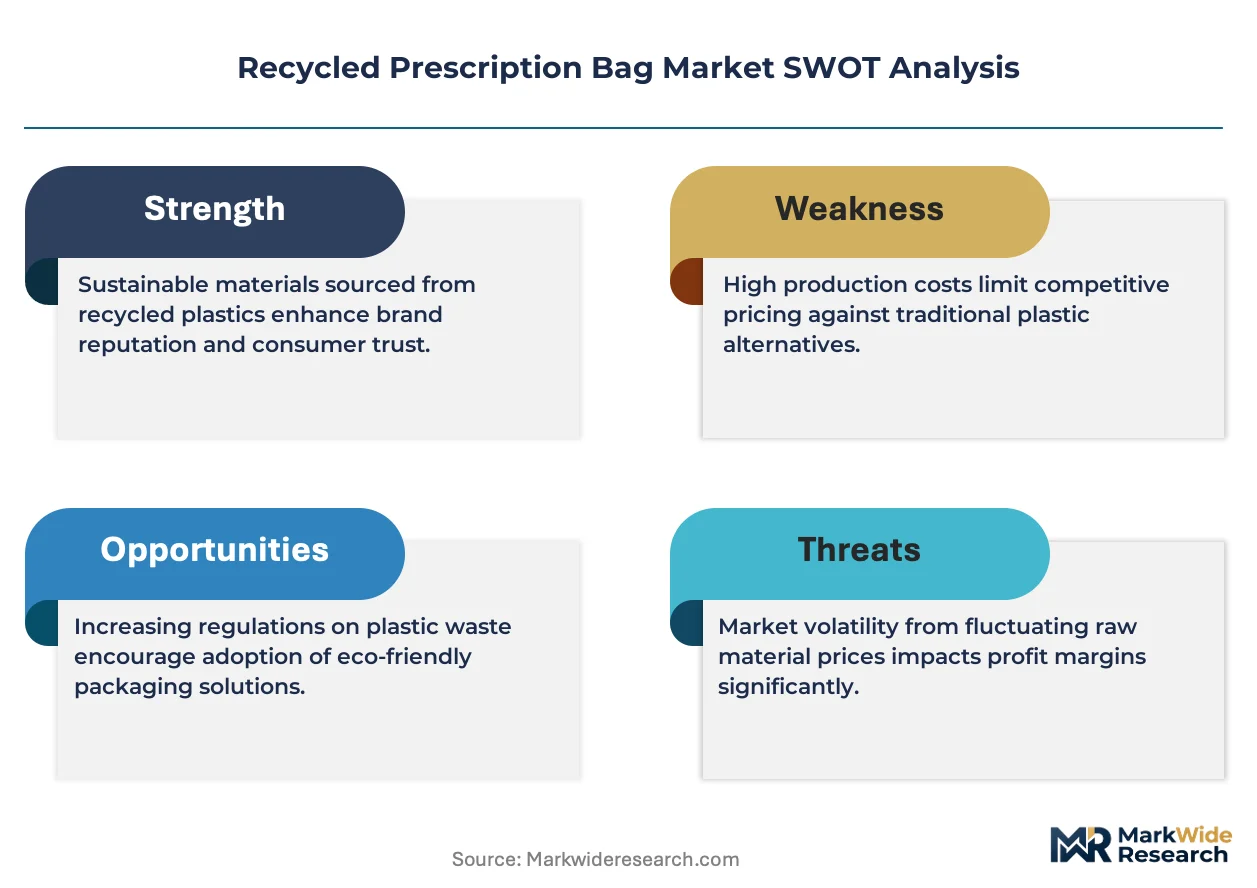
- EU Green Deal fiber mandates:German and French dispensaries must meet minimum recycled paper content thresholds, redirecting procurement toward certified suppliers.
- Specialty pharmacy cold-chain expansion:Temperature-sensitive biologics shipments require grease-resistant biodegradable laminates that standard paper cannot provide.
- Japan METI circular standards:Post-consumer recycled ratio requirements for retail pharmacy bags are accelerating domestic reprocessing capacity investments.
Market Restraints
- Post-consumer resin price volatility:Reprocessed polyethylene feedstock costs fluctuate with crude oil benchmarks and collection infrastructure gaps in North America.
- FDA packaging guidance compliance friction:Tamper-evident seal validation timelines extend product qualification cycles for new material formulations.
- Competing flexible packaging substitutes:Reusable rigid containers gain traction in hospital central fill operations where transport distance is short.
Strategic Opportunities
- Online pharmacy direct-to-patient channels:Home delivery growth creates demand for moisture-barrier zippered configurations with printed dosing instructions.
- Biodegradable plastic-paper hybrid convergence:Laminates combining cellulose fiber with bio-based sealants address both FDA fiber preferences and cold-chain performance needs.
- State-level extended producer responsibility frameworks:Emerging US state laws mandate retailer-funded collection infrastructure, creating captive feedstock pools for regional bag manufacturers.
Industry Challenges
- Multi-certification timeline compression:Suppliers must simultaneously secure FDA packaging guidance validation, EU Green Deal compliance documentation, and Japan METI recycled content verification.
- Barrier coating R&D skill scarcity:Formulation chemists with expertise in both moisture resistance and compostability are concentrated among packaging multinationals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Prescription Bag Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paper, Biodegradable Plastic, Recycled Polyethylene, Recycled Paper End User: Pharmacies, Healthcare Facilities, Retailers, Online Pharmacies Design Type: Flat Bags, Stand-Up Pouches, Zippered Bags, Perforated Bags Distribution Channel: Direct Sales, Online Sales, Wholesalers, Retail Sales |
| Companies Covered | Novolex, BioBag, WestRock, Pudumjee Paper Products, PaperPak, Mondi Group, Smurfit Kappa, Huhtamaki, Eco-Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Prescription Bag Market Evolving Landscape
Material science convergence is blurring the boundary between fiber-based and polymer-based pharmacy packaging. Suppliers now engineer multi-layer structures that satisfy competing regulatory preferences while maintaining medication integrity across diverse distribution temperatures.
Barrier-coated paper substrates are hybridizing with bio-based sealant technologies to create cold-chain-compatible prescription bags. Hospital systems in Germany and the United States are piloting these structures for temperature-sensitive shipments. The technology is hybridizing procurement categories that previously separated paper and plastic suppliers into distinct competitive sets.
Japan's METI circular economy standards now enforce post-consumer recycled content disclosure at the retail point of sale. Dispensaries must document supply chain provenance or face penalty structures. Specialty pharmacy segments handling controlled substances are responding fastest, as zippered bag configurations already require enhanced traceability systems that accommodate recycled content tracking.
Hospital pharmacy buying consortia are consolidating supplier panels around certified circular material providers. National health system tenders in France and Germany now pre-qualify vendors based on reprocessing facility ownership rather than unit pricing. This consolidation is most visible in German hospital networks where EU Green Deal compliance has become a non-negotiable gate for contract participation.
Recycled Prescription Bag Market Segmentation
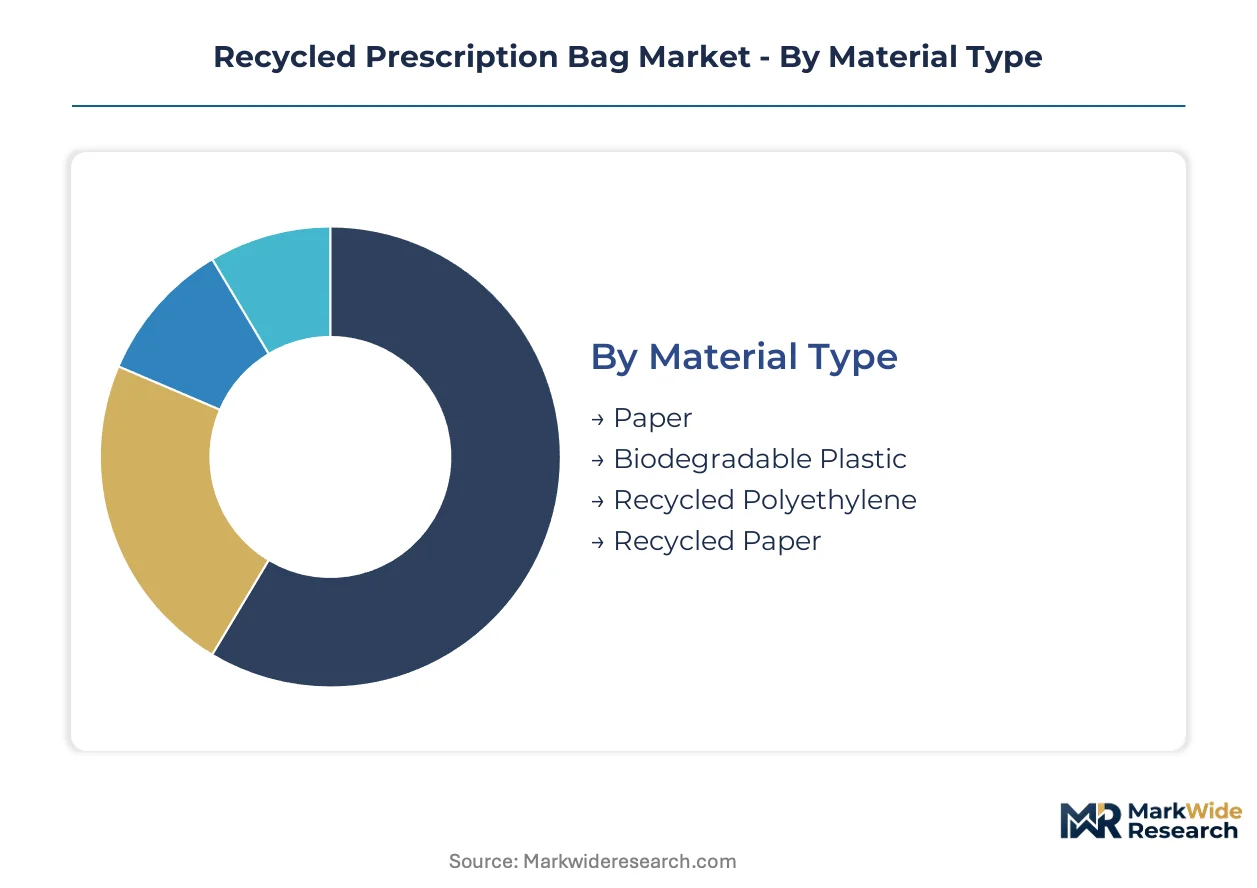
Material specifications and design configurations segment the recycled prescription bag market into distinct procurement tiers. Hospital systems prioritize fiber-based formats under FDA packaging guidance, while online pharmacies drive demand for moisture-resistant polymer variants. Each segment carries unique certification burdens and barrier performance requirements.
Material Type:
Cost tier determines supplier eligibility for chain pharmacy tenders and hospital system contracts.
- Paper:Engineered from post-consumer pulp with tamper-evident seals and moisture-resistant coatings. German hospital dispensaries favor this format under EU Green Deal fiber mandates, though cold-chain limitations constrain biologics applications.
- Biodegradable Plastic:Bio-based laminates combining grease resistance with compostability certification. Online pharmacy cold-chain shipments in Japan and the United States rotate toward this segment as METI circular standards and FDA packaging guidance tighten simultaneously.
- Recycled Polyethylene:Reprocessed resin formulations meeting post-consumer content thresholds for retail pharmacy chains.
- Recycled Paper:Lower-grade fiber streams serving cost-sensitive dispensaries with shorter transport distances.
Paper holds installed capacity. Biodegradable Plastic is rotating up the share rankings.
End User:
Application context shapes barrier specifications, traceability requirements, and procurement consolidation patterns.
- Pharmacies:Chain drugstores and independent dispensaries drive volume procurement of flat bags for standard tablet dispensing. EU Green Deal compliance documentation now filters supplier panels before price negotiation begins in France and Germany.
- Healthcare Facilities:Hospital central fill operations and outpatient clinics require certified post-consumer content with tamper-evident validation. FDA packaging guidance extends qualification timelines for new material formulations entering this segment.
- Retailers:Supermarket pharmacies and mass merchandisers with in-house dispensaries.
- Online Pharmacies:Direct-to-patient channels demanding zippered configurations with printed dosing instructions and moisture barriers.
Pharmacies hold installed capacity. Online Pharmacies is rotating up the share rankings.
Design Type:
Volume scale and margin capture separate mature commodity formats from specialty pharmacy configurations.
- Flat Bags:Single-layer paper or polyethylene structures for standard prescription fulfillment. German and French hospital systems procure this format at scale under EU Green Deal minimum fiber content rules.
- Zippered Bags:Reclosable configurations with enhanced traceability for controlled substances. Specialty pharmacy segments in the United States and Japan adopt these for temperature-sensitive biologics requiring repeated access.
- Stand-Up Pouches:Gusseted bases for bulk prescription or multi-month supplies.
- Perforated Bags:Tear-away formats for unit-dose or sample distribution.
Flat Bags hold installed capacity. Zippered Bags is rotating up the share rankings.
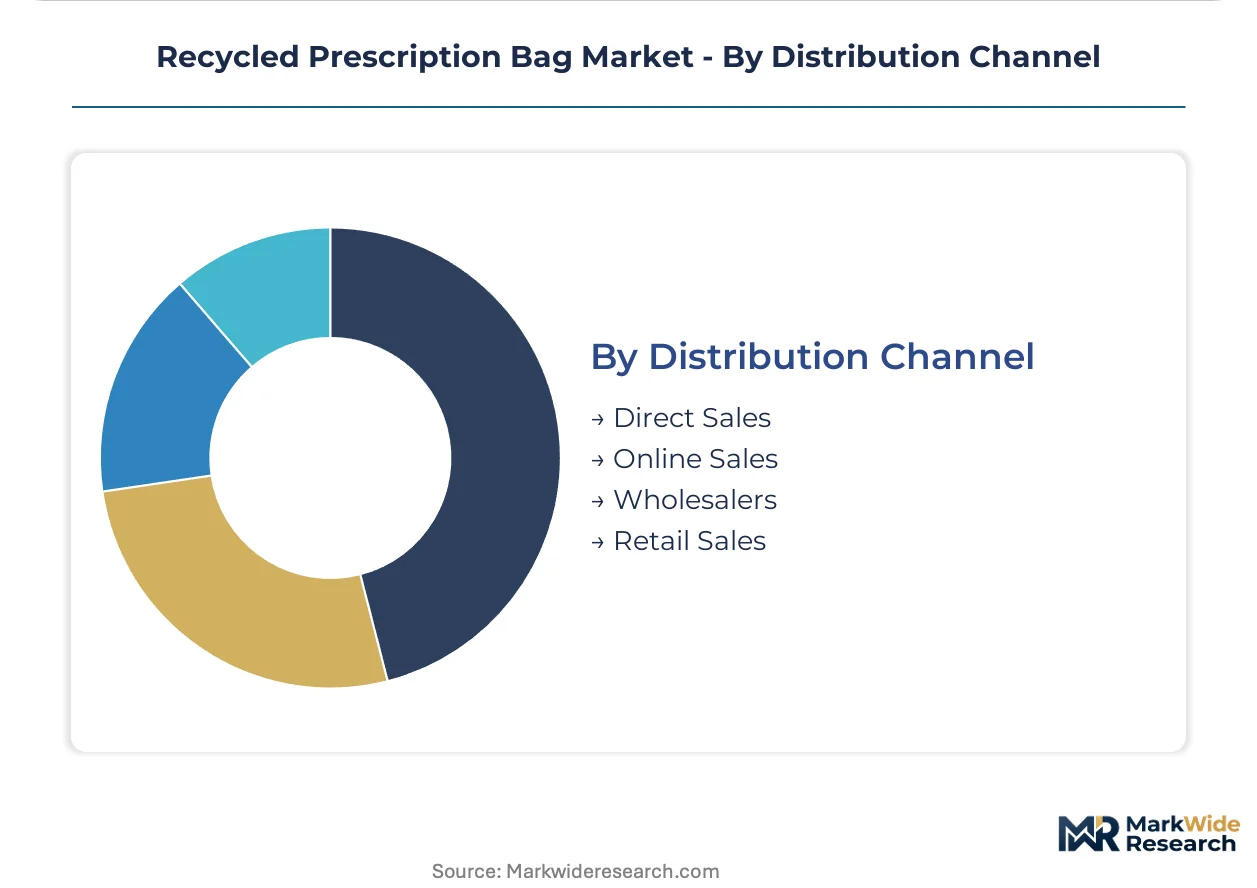
Distribution Channel:
Customer type and order scale determine whether procurement flows through consolidated wholesaler networks or direct manufacturer relationships.
- Direct Sales:National drugstore chains and hospital buying consortia negotiate long-term contracts with certified circular material providers. German hospital networks now pre-qualify vendors based on reprocessing facility ownership.
- Wholesalers:Pharmaceutical distributor networks aggregate demand from independent pharmacies. FDA packaging guidance compliance documentation travels through these intermediaries to fragmented end-users.
- Online Sales:E-commerce platforms serving small dispensaries and specialty pharmacies with configurable order quantities.
- Retail Sales:Over-the-counter procurement by individual pharmacies bypassing consolidated contracts.
Wholesalers hold installed capacity. Direct Sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's circular materials hub underwrites European supply chain density for post-consumer fiber streams serving German hospital networks.
United States
Walgreens and CVS Health procurement mandates drive certified recycled content thresholds for retail pharmacy bags. FDA packaging guidance extends tamper-evident seal validation timelines for new material formulations. Chicago-area hospital buying consortia now pre-qualify vendors based on reprocessing facility ownership rather than unit pricing.
Germany
EU Green Deal fiber-content minimums redirect hospital dispensary procurement toward certified paper suppliers. ANSM and national pharmacy regulators enforce documentation standards for post-consumer provenance. The Rhine-Ruhr industrial corridor concentrates reprocessing capacity investments serving French cross-border hospital networks.
Japan
Specialty pharmacy cold-chain expansion for temperature-sensitive biologics accelerates biodegradable laminate adoption. METI circular economy standards enforce post-consumer recycled ratio disclosure at retail point of sale. Osaka-Kobe manufacturing clusters integrate bio-based sealant R&D with domestic pharmaceutical packaging demand.
France
Hospital central fill operations consolidate supplier panels around EU Green Deal-compliant circular material providers. ECHA REACH documentation requirements filter eligibility before price negotiation begins. Lyon-Grenoble pharmacy logistics hubs pilot barrier-coated paper substrates for temperature-sensitive shipments.
United Kingdom
Online pharmacy direct-to-patient channels create demand for moisture-barrier zippered configurations with printed dosing instructions. NHS sustainable procurement frameworks elevate recycled content verification above cost metrics. Manchester-Leeds distribution corridors attract pharmaceutical wholesaler network investments in certified bag inventory.
Recycled Prescription Bag Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying certified fiber streams and barrier coating formulations. The vendor base stratifies across three tiers: multinational packaging conglomerates with captive recycling infrastructure, regional paperboard mills serving hospital consortia, and biodegradable plastic laminate specialists targeting cold-chain segments. Two dominant competitive moves define positioning: backward integration into post-consumer collection infrastructure and technology licensing for bio-based sealant formulations.
Among North American packaging conglomerates, Novolex and WestRock exemplify the integrated-platform archetype, leveraging captive recycling assets to secure long-term contracts with national drugstore chains. Smurfit Kappa anchors the European mill-based tier through integrated paperboard operations serving German and French hospital dispensaries.
| Leading Market Players |
|---|
| Novolex |
| BioBag |
| WestRock |
| Pudumjee Paper Products |
| PaperPak |
| Mondi Group |
| Smurfit Kappa |
| Huhtamaki |
| Eco-Products |
| Others |
Value Network & Pricing Analysis
Post-consumer resin price volatility determines both tier spreads and supply chain configuration in recycled prescription bag procurement. Buyers face widening cost differentials between certified fiber streams and virgin alternatives as crude oil benchmarks fluctuate, while suppliers hedge through backward integration into captive collection infrastructure.
Pricing Analysis
Volume-discount tiering structures separate national drugstore chains from independent dispensaries in contract negotiations. Three-tier pricing stratifies across premium certified-post-consumer, standard recycled-content, and economy virgin-blend levels. Price differentiation hinges on EU Green Deal compliance documentation and FDA packaging guidance validation tiers. Pricing pressure stems from hospital buying consortia pre-qualifying vendors on reprocessing facility ownership before unit-cost discussion. Chain pharmacies exhibit lowest price sensitivity due to mandated sustainable sourcing policies; independent retailers remain most exposed to resin cost swings.
Supply Chain Analysis
Supplier-financing facilities from packaging conglomerates extend payment terms to hospital buying consortia, locking in multi-year offtake commitments. Geographic supply concentrates in Germany, the United States, and Japan where reprocessing infrastructure clusters around pharmaceutical distribution hubs. Raw material dependencies center on post-consumer paper pulp, reprocessed polyethylene resin, and bio-based sealant formulations. Single-source vulnerability runs through certified fiber streams controlled by integrated mill operators. Distribution runs through pharmaceutical wholesaler networks aggregating fragmented independent pharmacy demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recycled prescription bag adoption sits in early-cycle expansion as EU Green Deal fiber mandates and FDA packaging guidance simultaneously tighten compliance thresholds across major pharmacy markets.
For Market Incumbents: Build certification moats by securing simultaneous FDA packaging guidance validation, EU Green Deal compliance documentation, and Japan METI recycled content verification before competitors complete multi-certification timelines. Novolex and Smurfit Kappa anchor positions through captive recycling infrastructure; challengers must match upstream control or exit hospital system tenders. Threat vectors include biodegradable plastic-paper hybrid technologies displacing pure-fiber formats in cold-chain segments. For New Entrants and Emerging Players: Build out specialty pharmacy zippered bag configurations for temperature-sensitive biologics, the fastest-rotating share tier where barrier-coated paper substrates create white-space between established paper and plastic suppliers. Online pharmacy direct-to-patient channels offer penetrable entry points with configurable order quantities bypassing consolidated wholesaler networks. Go-to-market angle: bio-based sealant R&D partnerships with Osaka-Kobe or Lyon-Grenoble manufacturing clusters. For Investors and Strategic Acquirers: EU Green Deal enforcement reshapes the acquisition landscape toward certified circular material providers with reprocessing facility ownership rather than toll-manufacturing models. Long-term viability favors platform integrators commanding system-tier procurement relationships over component specialists supplying fiber streams. Signal to watch: state-level extended producer responsibility framework passage creating captive feedstock pools for regional bag manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | Novolex secures long-term supply contracts with national drugstore chains through captive recycling assets. |
| Multi-Certification Timeline Compression | Suppliers simultaneously pursue FDA, EU Green Deal, and METI validation to qualify for consolidated hospital tenders. |
| Bio-Based Sealant R&D Partnership | Huhtamaki develops biodegradable plastic-paper hybrid laminates for Japan's temperature-sensitive biologics shipments. |
| Hospital Buying Consortia Pre-Qualification | German networks filter vendor panels on reprocessing facility ownership before price negotiation begins. |
| State EPR Framework Positioning | Regional manufacturers capture retailer-funded collection infrastructure under emerging US extended producer responsibility laws. |
Research Methodology
A spread of perspectives from hospital pharmacy procurement managers, pharmaceutical distributor network heads, packaging R&D directors, and regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA packaging guidance documents, EU Green Deal compliance frameworks, Japan METI circular economy standards, and pharmaceutical wholesaler procurement disclosures. Bottom-up segment sizing triangulated with top-down market reconstruction across material type, end user, design configuration, and distribution channel dimensions.
Demand-supply-balance framing anchored the forecast framework across the analysis window. Segmentation modeling incorporated material specifications, barrier performance tiers, certification grade, and regional regulatory cluster variations. CAGRs derived from trend extrapolation of procurement mandate adoption curves and reprocessing capacity expansion timelines. Industry-specific inputs included hospital system tender award patterns and online pharmacy shipment growth trajectories.
Stress conditions across post-consumer resin price volatility, multi-certification timeline delays, and biodegradable plastic-paper hybrid technology substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement intensity and sustainable sourcing mandate penetration. Macroeconomic contraction, regulatory rollback, or breakthrough compostable barrier technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Intravenous Packaging Market
Pharmaceutical Packaging
Glass Medicine Bottles Market
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
Tablet Bottle Market
Pharmaceutical Packaging
Global Ampoules Packaging Market
Pharmaceutical Packaging
Laboratory Consumables Primary Packaging Market
Pharmaceutical Packaging
APAC Pharmaceutical Packaging Market
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
Philippines Pharmaceutical Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Vaccine Vial Rubber Stopper Market
Pharmaceutical Packaging
Global Biodegradable Pharmaceutical Packaging Market
Pharmaceutical Packaging
Anti-Counterfeit Pharmaceutical Packaging Market
Pharmaceutical Packaging
Injection Bottles Market