
 Asia-Pacific Pharmaceutical Plastic Bottles Market | 2026-2036
Asia-Pacific Pharmaceutical Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pharmaceutical Plastic Bottles Market Insights
Recyclability-as-a-service is decoupling bottle procurement from virgin resin dependency across Asia-Pacific pharmaceutical supply chains. Amcor Group GmbH leverages its Asia-Pacific extrusion footprint to anchor multilayer PET programs for liquid medicine formats. Alpha Packaging Pvt Ltd specializes in child-resistant closure integration for topical formulation bottles distributed through Indian contract manufacturers. Berry Global Inc controls high-volume HDPE output for hospital-system oral solution contracts across Southeast Asia.
Asia-Pacific pharmaceutical plastic bottles are blow-molded or injection-stretch blow-molded containers, typically 10 ml to 1000 ml in nominal volume, fabricated from resins meeting pharmacopeial extractables and leachables thresholds for drug contact. These vessels store, dispense, and protect liquid, semi-solid, and solid oral dosage forms from moisture ingress and UV degradation. PET dominates value contribution due to its oxygen barrier and clarity in oral solutions and liquid medicines, while HDPE sustains volume leadership in cost-sensitive topical formulations and large-format hospital stock. Child-resistant closure systems command premium positioning as pediatric safety regulations harden across the region.
India's CDSCO enforces Schedule M packaging integrity standards, while China's NMPA mandates registration of primary packaging materials under drug master file protocols; both frameworks elevate compliance costs for uncertified converters. Japan's PMDA and South Korea's MFDS align with ICH Q3D elemental impurity guidelines, creating harmonized testing burdens for exporters. Stakeholders must monitor evolving extended producer responsibility schemes and bio-based resin certification pathways before committing to capacity expansion or material platform shifts.
Market Dynamics
Multilayer PET migration is compressing conventional single-layer bottle margins as India's CDSCO and China's NMPA ratchet down extractables thresholds for liquid medicine formats. This material transition is redrawing converter specialization maps across the Asia-Pacific pharmaceutical packaging base.
Growth Catalysts
- Schedule M packaging integrity standards:India's CDSCO enforcement is accelerating certified HDPE converter consolidation in Maharashtra-Gujarat pharmaceutical clusters.
- Oral solution volume expansion:Community pharmacy dispensing of liquid medicines is driving 10 ml to 500 ml PET bottle demand across Southeast Asian hospital systems.
- Child-resistant closure mandates:Pediatric safety regulations in Japan and South Korea are premiumizing closure system specifications for topical formulation bottles.
Market Restraints
- Virgin PET resin price volatility:Crude-linked feedstock costs are squeezing margin structures for converters without backward integration into recycled flake supply.
- Drug master file registration burdens:China's NMPA primary packaging material protocols are extending commercialization timelines for uncertified HDPE grades by 12-18 months.
- Glass substitution in high-barrier biologics:Cyclic olefin polymer and borosilicate glass are capturing parenteral and sensitive biologic formats from plastic converters.
Strategic Opportunities
- Indonesia's underpenetrated hospital pharmacy network:Oral solution stock-keeping unit expansion in Java-based distributor channels offers first-mover positioning for multilayer PET converters.
- Extended producer responsibility alignment:Australia's TGA and New Zealand's MedSafe are piloting post-consumer recycled content thresholds that reward certified circular resin programs.
- Bio-based PE/PP certification pathways:ISCC PLUS and RSB standards are creating premium pricing tiers for pharmaceutical bottles in Japanese and South Korean ethical drug supply chains.
Industry Challenges
- Extractables and leachables testing capacity:ICH Q3D elemental impurity compliance is bottlenecking at third-party analytical laboratories across the Asia-Pacific region.
- Multilayer coextrusion equipment lead times:European and Japanese blow-molding line manufacturers are quoting 14-18 month delivery windows for nine-layer PET systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pharmaceutical Plastic Bottles Market |
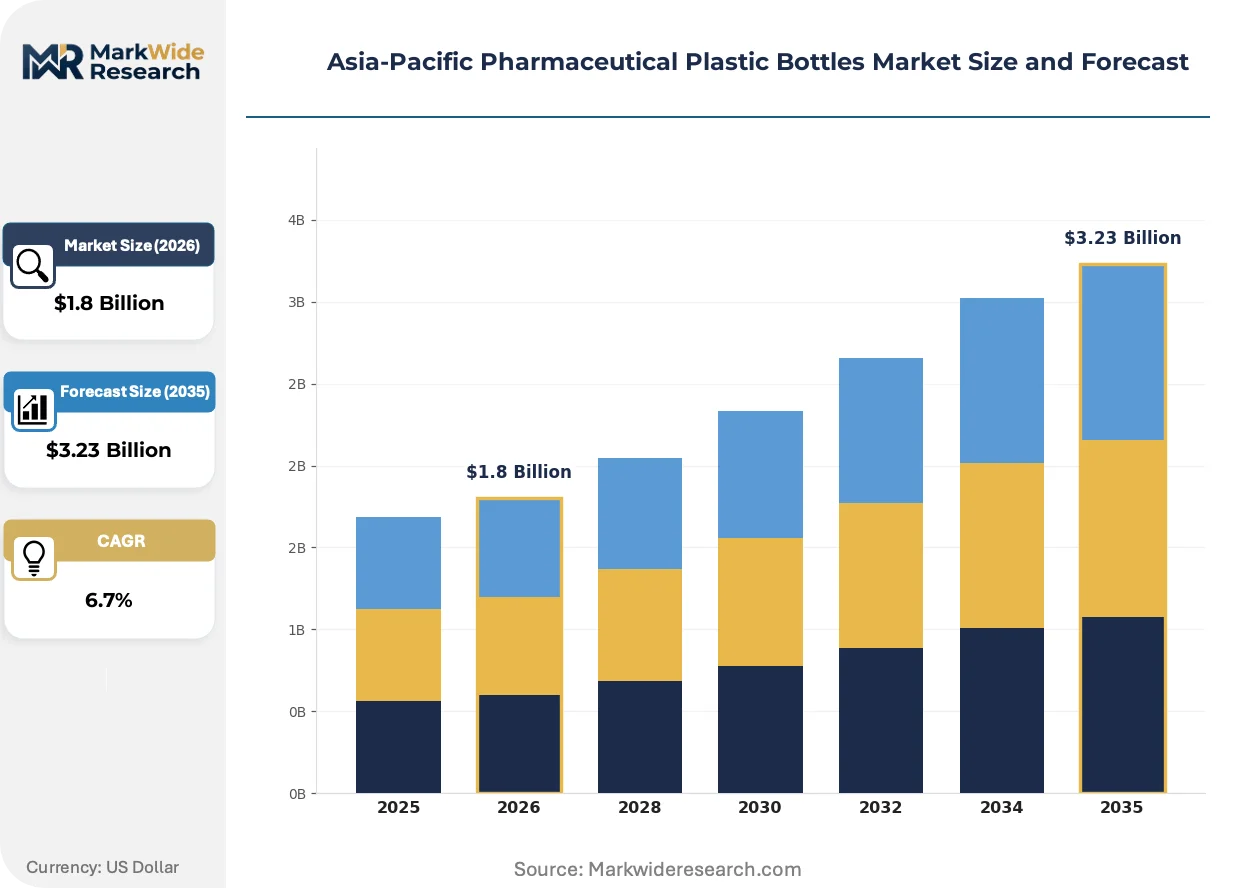
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LDPE, HDPE, PET, PVC Application: Oral Solutions, Liquid Medicines, Injectable Solutions, Topical Formulations Closure Type: Screw Cap, Dropper, Pump, Child-Resistant End User: Pharmacies, Hospitals, Clinics, Contract Manufacturers |
| Companies Covered | AptarGroup Inc, ALPLA Werke Alwin Lehner GmbH & Co KG, Amcor Group GmbH, Alpha Packaging Pvt Ltd, Chemco Group, Gerresheimer AG, Silgan Holdings Inc, Supple Pack (India) Private Limited, Berry Global Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pharmaceutical Plastic Bottles Market Trends and Innovations
Material science convergence with regulatory chemistry is redefining pharmaceutical bottle performance specifications. Converters are racing to bridge barrier property gaps without sacrificing recyclability credentials.
Multilayer PET with oxygen-scavenging interlayers is overtaking conventional monolayer structures in oral solution applications. Japanese ethical drug manufacturers are specifying nine-layer configurations for 24-month shelf-life products. This technology is compressing single-layer PET converter margins in liquid medicine segments.
China's NMPA drug master file protocols for primary packaging materials are forcing dual-registration strategies for exporters. Converters must now maintain separate technical dossiers for domestic and international pharmaceutical clients. Southeast Asian contract manufacturers are absorbing compliance costs through longer-term supply agreements.
Hospital-system oral solution procurement is consolidating around direct converter relationships, bypassing traditional distributor tiers. India's Maharashtra-Gujarat pharmaceutical cluster is witnessing volume concentration at three to five approved bottle suppliers per therapeutic category. Australian public hospital formulary committees are mirroring this pattern for 500 ml and 1000 ml stock formats.
Asia-Pacific Pharmaceutical Plastic Bottles Market Segmentation
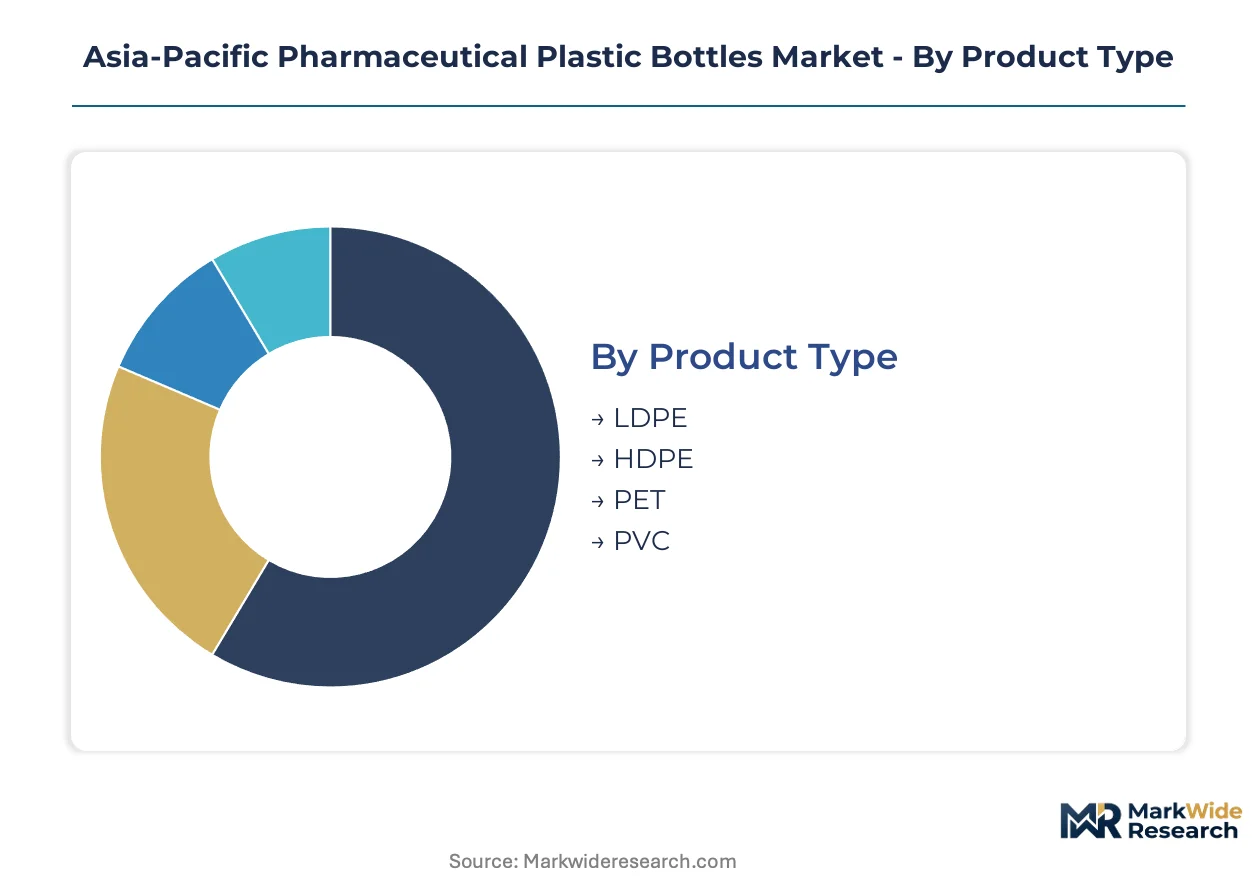
Pharmaceutical plastic bottle procurement in Asia-Pacific fragments across resin chemistry, dosage form requirements, and safety specifications. Each segment carries distinct regulatory burdens that shape converter certification investments and customer qualification timelines.
Product Type:
CDSCO Schedule M and NMPA drug master file protocols impose tiered extractables testing burdens that vary sharply by resin platform. PET and multilayer configurations demand the most extensive analytical dossiers.
- PET:Polyethylene terephthalate dominates oral solution packaging through its oxygen barrier and optical clarity. Maharashtra-Gujarat pharmaceutical clusters specify nine-layer coextruded structures for 24-month shelf-life liquid medicines as CDSCO tightens migration limits.
- HDPE:High-density polyethylene sustains volume leadership in cost-sensitive topical formulations and large-format hospital stock bottles. Jiangsu-Zhejiang corridor converters consolidate around certified grades to meet NMPA registration protocols for domestic and export supply.
- LDPE:Low-density polyethylene serves squeeze-dropper applications in ophthalmic and nasal spray formats requiring flexible wall compliance.
- PVC:Polyvinyl chloride persists in limited intravenous solution packaging where plastizer-free formulations satisfy MFDS elemental impurity thresholds.
Leading the category by volume: HDPE. Growing fastest: multilayer PET configurations.
Application:
Dosage form chemistry dictates barrier specifications, with liquid and semi-solid formats driving the most demanding material transitions across the region.
- Oral Solutions:Cough syrups, antacids, and pediatric suspensions require oxygen-scavenging interlayers to prevent oxidative degradation. Southeast Asian hospital systems are consolidating 10 ml to 500 ml PET bottle procurement around direct converter relationships.
- Liquid Medicines:Prescription ethical drugs command premium multilayer structures with 24-month stability validation. Japanese PMDA-aligned manufacturers specify EVOH-barrier configurations that compress single-layer converter margins.
- Injectable Solutions:Parenteral formats face displacement by cyclic olefin polymer and glass as biologic sensitivity requirements harden.
- Topical Formulations:Creams, lotions, and gels utilize HDPE bottles with child-resistant closure integration for contract manufacturing supply to Indian and Chinese exporters.
Volume concentrates in oral solutions. Steepest expansion trajectory: liquid medicines in ethical drug channels.
Closure Type:
Pediatric safety mandates in Japan and South Korea are restructuring procurement specifications around certified child-resistant mechanisms.
- Child-Resistant:Push-and-turn and squeeze-and-turn mechanisms command 15-25% price premiums over standard closures. Alpha Packaging specializes in CR certification integration for topical bottles distributed through Indian contract manufacturers.
- Screw Cap:Standard continuous thread closures dominate hospital-system oral solution stock where cost minimization overrides safety specifications.
- Dropper:Integrated bulb droppers serve ophthalmic and pediatric vitamin applications requiring precise dose control.
- Pump:Metered-dose pumps capture topical foam and gel formats in dermatology and wound care segments.
Screw caps lead by unit volume. Child-resistant closures gain share fastest on regulatory mandates.
End User:
Procurement authority is shifting from distributor tiers toward direct hospital-system and contract manufacturing relationships.
- Hospitals:Australian public hospital formulary committees consolidate 500 ml and 1000 ml HDPE oral solution procurement around three to five approved suppliers per therapeutic category. Berry Global anchors high-volume contracts across Southeast Asian hospital networks.
- Contract Manufacturers:Indian and Chinese CDMOs absorb NMPA and CDSCO compliance costs through long-term supply agreements with certified converters. Amcor leverages its Asia-Pacific extrusion footprint to anchor multilayer PET programs for liquid medicine formats.
- Pharmacies:Community pharmacy dispensing drives 10 ml to 100 ml bottle demand for over-the-counter liquid medicines.
- Clinics:Outpatient facilities source smaller stock-keeping units through regional distributor channels with limited direct converter engagement.
Contract manufacturers represent the fastest-expanding procurement channel. Hospitals retain the largest absolute volume position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in China's Jiangsu-Zhejiang corridor and India's Maharashtra-Gujarat cluster, while consumption spreads across Southeast Asian hospital systems and Australian formulary networks. This geographic split shapes converter location strategies and regulatory compliance investments.
China
Jiangsu-Zhejiang corridor converters supply multilayer PET for liquid medicine formats to domestic ethical drug manufacturers. NMPA drug master file protocols extend commercialization timelines for uncertified HDPE grades. Suzhou and Hangzhou host the dominant extrusion and blow-molding operations serving both domestic and export pharmaceutical clients.
India
Maharashtra-Gujarat pharmaceutical clusters drive certified HDPE demand for topical formulations and oral solutions. CDSCO Schedule M packaging integrity standards accelerate converter consolidation around approved suppliers. Ahmedabad and Mumbai house the primary blow-molding capacity feeding contract manufacturing exports to Southeast Asia and Africa.
Japan
Ethical drug manufacturers specify nine-layer PET configurations with 24-month stability validation for premium liquid medicines. PMDA alignment with ICH Q3D elemental impurity guidelines creates harmonized testing burdens for domestic and imported packaging. Osaka and Tokyo pharmaceutical corridors source barrier-grade bottles through direct converter relationships bypassing distributor tiers.
South Korea
MFDS pediatric safety regulations premiumize child-resistant closure specifications for topical formulation bottles. Seoul-Incheon pharmaceutical manufacturing bases procure certified multilayer structures for OTC and prescription liquid medicines. Busan-based converters serve Japanese ethical drug exporters with EVOH-barrier configurations.
Australia
Public hospital formulary committees consolidate 500 ml and 1000 ml HDPE oral solution procurement around three to five approved suppliers per therapeutic category. TGA pilot programs for post-consumer recycled content thresholds reward certified circular resin programs. Sydney and Melbourne distribution hubs direct volume toward direct converter relationships rather than traditional distributor channels.
Asia-Pacific Pharmaceutical Plastic Bottles Market Competitive Landscape
Capital-heavy converters with captive extrusion assets compete with asset-light specialists outsourcing resin procurement and blow-molding operations. Market structure tilts toward consolidation at the high-volume hospital-system tier while fragmenting across specialty pediatric and ophthalmic formats. Three archetypes dominate: integrated resin-to-bottle multilayer specialists, certified HDPE volume producers for topical applications, and child-resistant closure integrators. Competitive moves center on backward integration into recycled flake supply chains and long-term supply agreements absorbing NMPA and CDSCO compliance costs.
Among Asia-Pacific-based fabricators, Amcor Group GmbH and Alpha Packaging Pvt Ltd exemplify the integrated specialist archetype, while Berry Global Inc anchors the high-volume hospital-system tier. Chemco Group and Supple Pack (India) Private Limited occupy positions within the certified converter base serving contract manufacturing export channels. ALPLA Werke Alwin Lehner GmbH & Co KG represents European-origin technical capability positioned for premium ethical drug specifications. Gerresheimer AG and Silgan Holdings Inc sit within the diversified packaging conglomerate tier leveraging cross-segment resin purchasing power.
| Leading Market Players |
|---|
| AptarGroup Inc |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Amcor Group GmbH |
| Alpha Packaging Pvt Ltd |
| Chemco Group |
| Gerresheimer AG |
| Silgan Holdings Inc |
| Supple Pack (India) Private Limited |
| Berry Global Inc |
| Others |
Pricing and Supply Chain Analysis
Multilayer PET coextrusion adoption simultaneously escalates capital equipment costs and consolidates converter pricing power around certified Jiangsu-Zhejiang and Maharashtra-Gujarat suppliers. CDSCO Schedule M and NMPA drug master file protocols erect compliance moats that compress margin structures for uncertified competitors while premiumizing validated supply.
Pricing Analysis
Margin tightening in single-layer PET reflects virgin resin feedstock volatility and migration toward nine-layer barrier configurations. Three-tier pricing structure across premium multilayer, certified standard, and uncertified economy levels separates CDSCO-validated converters from commodity HDPE suppliers. Price differentiation rests on ICH Q3D testing dossier completeness and direct hospital-system contract access. Cost-down pressure on economy-tier converters accelerates because Southeast Asian contract manufacturers consolidate procurement around approved supplier lists.
Supply Chain Analysis
Regional distribution centers in Mumbai, Suzhou, and Singapore anchor hub-and-spoke patterns serving hospital-system formularies across Southeast Asia. Geographic supply concentration centers on China, India, and South Korea for extrusion-grade resin and blow-molding capacity. Raw material dependencies draw from PTA/MEG feedstocks and EVOH barrier resin imports. Supply chain risk traces to single-source vulnerability in nine-layer coextrusion equipment from European and Japanese manufacturers. Distribution runs through direct converter relationships bypassing traditional pharmaceutical distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where CDSCO Schedule M packaging integrity standards erect barrier-to-entry moats favoring certified incumbents over uncertified aspirants.
For Market Incumbents: Deepen backward integration into recycled PET flake supply to defend margin position against virgin resin volatility. Anchor capacity expansion in Maharashtra-Gujarat clusters to capture CDSCO consolidation benefits. Fortify direct hospital-system relationships before formulary committees freeze approved supplier lists. For New Entrants and Emerging Players: Capture Indonesia's underpenetrated hospital pharmacy network where oral solution SKU expansion outpaces certified converter supply. Penetrate Java-based distributor channels with multilayer PET technical validation. Pursue long-term supply agreements absorbing NMPA registration timelines as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified packaging conglomerates seeking pharmaceutical certification assets. Five-to-ten year viability hinges on regulatory compliance durability rather than commodity resin exposure. Target acquisition archetype: mid-cap converters with captive multilayer extrusion and CDSCO/NMPA dual registration. Watch ICH Q3D testing capacity bottlenecks as the inflection signal for valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Flake Supply | Mitigates virgin PET price volatility for Maharashtra-Gujarat converters serving CDSCO-regulated clients. |
| Dual Registration Dossier Maintenance | Enables simultaneous NMPA domestic and export supply from Jiangsu-Zhejiang corridor operations. |
| Direct Hospital-System Contracting | Bypasses distributor margin extraction in Australian public hospital formulary procurement. |
| Nine-Layer Coextrusion Capacity Addition | Captures 24-month shelf-life liquid medicine specifications from Japanese PMDA-aligned manufacturers. |
| Child-Resistant Closure Certification Investment | Premiumizes topical formulation bottles under South Korea MFDS pediatric safety mandates. |
Research Methodology
Independent corroboration across converter operations managers, pharmaceutical regulatory affairs leads, hospital procurement directors, and resin supply specialists underwrites the qualitative findings. Primary fieldwork combined with secondary validation from CDSCO Schedule M compliance databases, NMPA drug master file registries, and Asia-Pacific customs trade records anchors supply-side concentration claims. Bottom-up facility capacity assessments triangulate against top-down pharmaceutical packaging demand estimates across the analysis window.
Rate-of-change decomposition separates volume growth drivers by resin platform, dosage form application, closure safety specification, and end-user procurement channel. Segmentation modeling incorporates treatment line differentiation, regional regulatory cluster alignment, and converter certification tier. CAGRs derive from facility-level capacity utilization trajectories and hospital formulary expansion patterns. Forecast inputs include multilayer PET adoption curves and ICH Q3D testing laboratory capacity constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA registration timeline shifts and extended producer responsibility scheme implementation. Forecasts reflect documented assumptions around resin price stability and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Tubes Market
Pharmaceutical Packaging
Advanced Empty Capsule Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Parenteral Drugs Packaging Market
Pharmaceutical Packaging
Laboratory Consumables Primary Packaging Market
Pharmaceutical Packaging
Pharmaceutical Container Market
Pharmaceutical Packaging
Global Ampoules Packaging Market
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
Global Temperature Controlled Packaging Solutions for Pharmaceuticals Market
Pharmaceutical Packaging
Nutraceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Printed Cartons Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Materials Market
Pharmaceutical Packaging
Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Topical Drugs Packaging Market
Pharmaceutical Packaging
Pharmacy Repackaging Systems Market
Pharmaceutical Packaging
Prescription Bottles Market