
 Europe Single-Ply Membrane Market | 2026-2036
Europe Single-Ply Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Single-Ply Membrane Market Foresight
Distributor networks serving roofing contractors is narrowing across Northern Europe as large building-material merchants consolidate shelf space for certified systems. Sika AG leverages its adhesives and membrane portfolio to control specification conversations with specifiers. Kingspan Group anchors insulated panel and membrane bundling across the United Kingdom and Ireland. Soprema Group competes through its bitumen and single-ply hybrid solutions in French commercial projects.
Single-ply membrane denotes a flexible roofing sheet manufactured from synthetic polymers such as TPO, EPDM, or PVC, typically calendered or extruded to thicknesses between 30 mil and 80 mil, and installed via mechanical attachment, adhesion, or ballast to provide weatherproofing and thermal protection for low-slope structures. TPO formulations lead volume in new commercial construction across Germany and the Netherlands due to heat-weldability and reflectivity ratings. EPDM sustains margin pools in refurbishment applications where building owners prioritize membrane longevity over first-cost. PVC occupies institutional segments requiring chemical resistance and fire-performance certification.
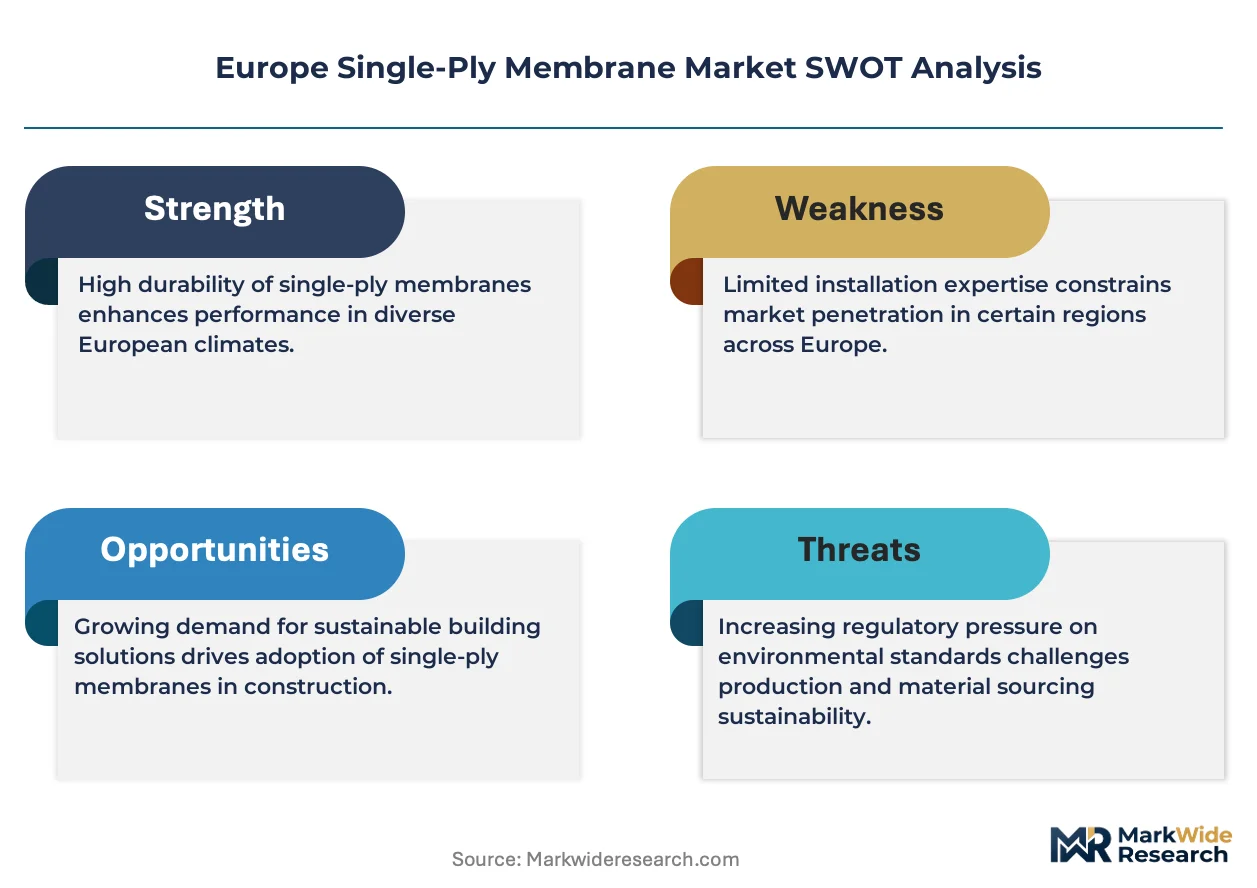
REACH compliance and the EU Green Deal's building-renovation targets are tightening permissible plasticizer content and mandating recycled-content disclosures, forcing reformulation investments by manufacturers seeking CE marking access. ECHA substance evaluations and national building codes in France and Germany are diverging on fire-test protocols, fragmenting product-approval pathways. Stakeholders must monitor whether the EU AI Act's eventual extension to building-energy modeling alters specification workflows for membrane selection.
Market Dynamics
REACH substance evaluations and divergent national fire-test protocols across France and Germany are fragmenting product-approval pathways, forcing manufacturers to maintain parallel certification portfolios for CE marking access.
Growth Catalysts
- EU Green Deal renovation targets:Mandatory thermal efficiency upgrades across commercial building stock are accelerating membrane replacement cycles in France and Germany.
- TPO heat-weldability:Thermoplastic polyolefin formulations enable faster installation speeds and reduced labor hours for roofing contractors bidding fixed-price commercial projects.
- Building-material merchant consolidation:Narrowed distributor networks in Northern Europe are privileging certified membrane systems with bundled technical support.
Market Restraints
- Plasticizer feedstock volatility:Phthalate and bio-based plasticizer price swings compress PVC membrane margins during formulation transitions.
- EPDM supply concentration:Ethylene propylene diene monomer sheet production clusters in specific polymer processing regions, exposing contractors to lead-time volatility.
- Fire-test protocol divergence:French CSTB and German DIBt certification requirements for single-ply systems lack mutual recognition, doubling compliance costs.
Strategic Opportunities
- Polish commercial construction acceleration:Warsaw and Krakow office development pipelines remain underpenetrated by specified membrane systems relative to Western European saturation.
- Recycled-content disclosure mandates:EU Green Deal building-renovation reporting requirements create first-mover advantage for manufacturers with validated post-consumer feedstock chains.
- Adhesive-membrane bundling:Integrated specification conversations with commercial roofing contractors displace standalone membrane bidding.
Industry Challenges
- Certified welder scarcity:TPO heat-welding proficiency gaps among installation crews in Southern Europe delay project handovers and trigger warranty disputes.
- Legacy bitumen system integration:Hybrid refurbishment projects requiring single-ply overlay on existing built-up roofs demand specialized detailing expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Single-Ply Membrane Market |
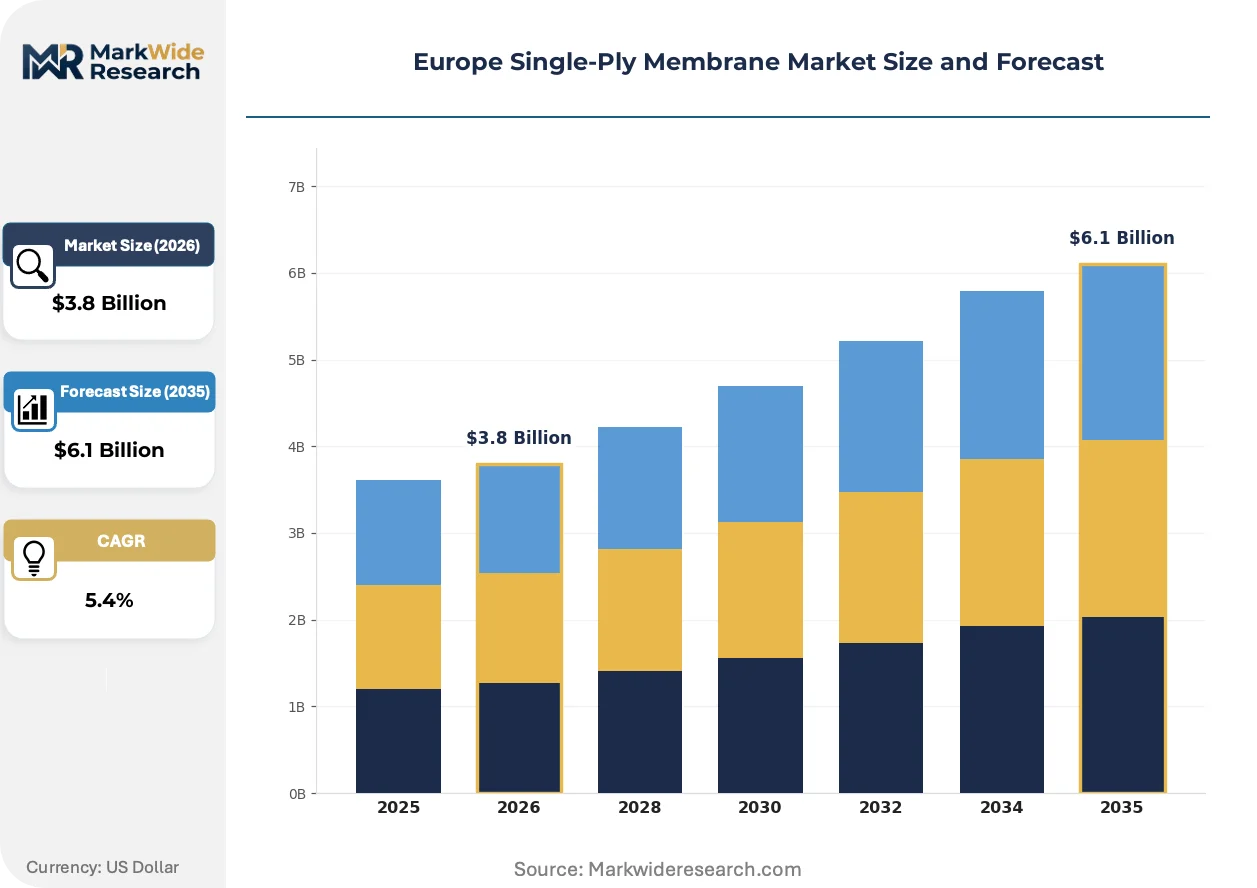
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TPO, EPDM, PVC, Others End User: Commercial, Residential, Industrial, Institutional Thickness: 30 mil, 40 mil, 60 mil, 80 mil Installation Method: Adhered, Mechanically Attached, Ballasted, Others |
| Companies Covered | Holcim, Kingspan Group, Sika AG, RENOLIT SE, GAF Materials Corporation, Soprema Group, Standard Industries Inc., BMI Group, Carlisle Construction Materials, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Single-Ply Membrane Market Shifts & Advancements
Reformulation investments are accelerating across polymer suppliers as ECHA substance evaluations and recycled-content mandates reshape membrane composition standards and manufacturing footprints.
Co-extruded TPO cap sheets with enhanced UV stabilizers are migrating from standard commercial roofing toward agricultural and industrial applications requiring extended service intervals. Dairy processing facilities in the Netherlands specify these formulations for chemical resistance alongside thermal performance. The technology is migrating from premium commercial specifications into mid-tier refurbishment segments as contractors seek to differentiate on warranty terms rather than first-cost.
REACH Annex XVII restrictions on short-chain chlorinated paraffins are forcing PVC membrane producers to validate alternative plasticizer systems ahead of sunset dates. German manufacturers face compressed reformulation timelines as ECHA evaluations outpace national building-code update cycles. French commercial specifiers are responding by prioritizing TPO alternatives where fire-performance certifications permit material substitution.
Specification authority is concentrating with large roofing contractors capable of offering design-build warranties across membrane and insulation systems. Independent distributors in the United Kingdom are losing shelf-space leverage as Kingspan and Sika direct-sell bundled panel-membrane packages to tier-one contractors. This concentration is most visible in London commercial renovation where single-source accountability clauses dominate procurement documents.
Europe Single-Ply Membrane Market Segmentation
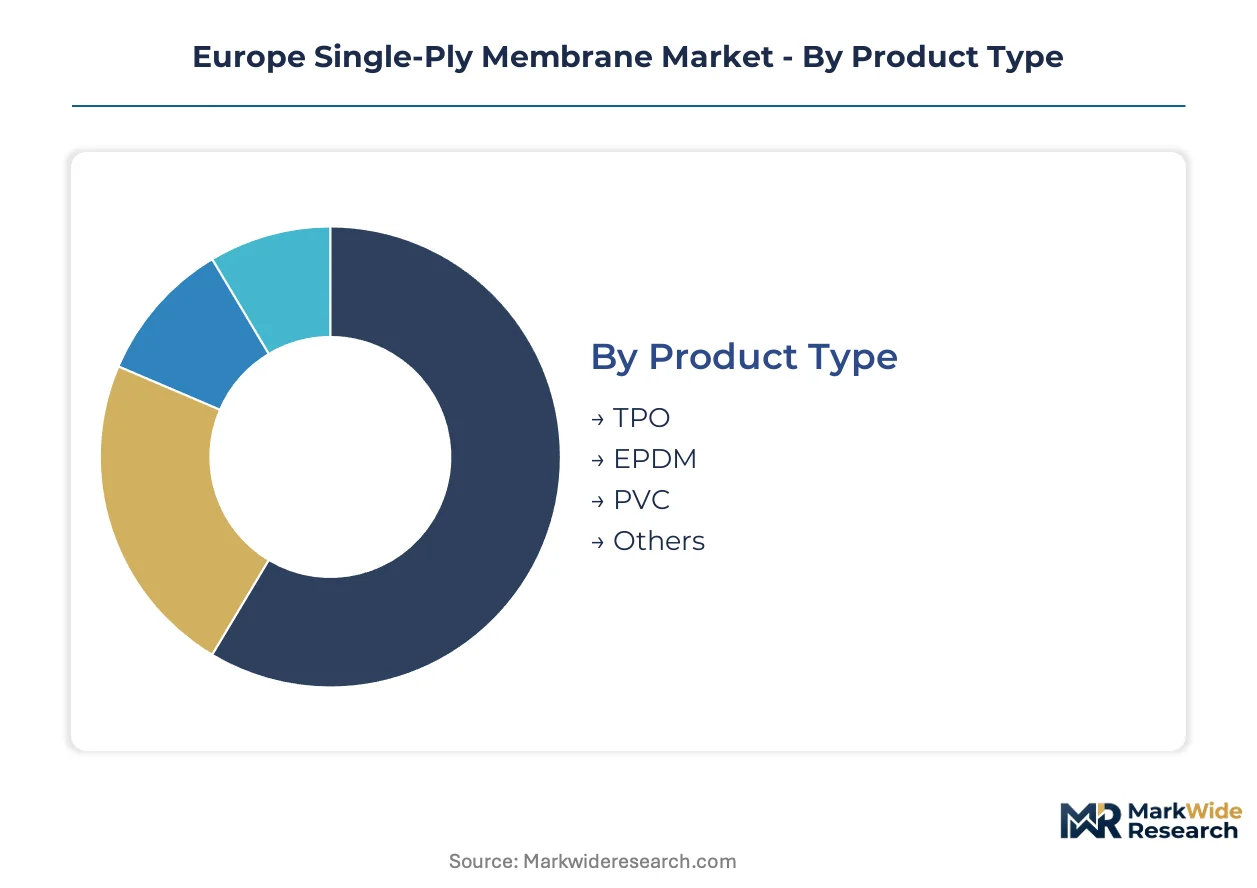
Single-ply membrane specification in Europe fragments across polymer chemistry, building typology, and installation logistics. Contractors and specifiers navigate trade-offs between thermal weldability, fire certification, and labor productivity that vary sharply by project scale and national code interpretation.
Product Type:
Thermoplastic polyolefin dominates new commercial specifications across Germany and the Netherlands, while ethylene propylene diene monomer retains refurbishment margins where longevity premiums offset first-cost sensitivity.
- TPO:Heat-weldable thermoplastic formulation with high solar reflectance ratings. German commercial roofing contractors specify TPO for fixed-price bids where installation speed determines margin. REACH-compliant plasticizer-free composition eases regulatory navigation versus PVC alternatives.
- EPDM:Synthetic rubber membrane manufactured from ethylene propylene diene monomer with exceptional UV and ozone resistance. French building owners prioritize EPDM in refurbishment applications where membrane service life exceeds 30 years. Supply concentration in specific polymer processing regions exposes contractors to lead-time volatility.
- PVC:Flexible vinyl formulation incorporating plasticizers for low-temperature flexibility. Chemical resistance and established fire-performance certification sustain specification in hospital and laboratory segments across France and Germany.
- Others:Niche formulations including modified bitumen hybrids and emerging bio-based polymers. Limited penetration outside specialized agricultural and heritage building applications.
The dominant share belongs to TPO, while EPDM is closing the gap fastest in renovation-heavy markets.
End User:
Building typology dictates membrane specification authority, with commercial developers driving volume and institutional clients demanding certified fire performance.
- Commercial:Office, retail, and logistics facilities constitute the primary volume segment. Kingspan and Sika bundle membrane-insulation packages for London and Frankfurt commercial renovation projects where single-source accountability clauses dominate procurement.
- Residential:Multi-family and single-family low-slope applications. Limited penetration relative to commercial due to steeper roof pitches and alternative material competition.
- Industrial:Manufacturing facilities, warehouses, and processing plants. Dairy processing facilities in the Netherlands specify co-extruded TPO cap sheets for chemical resistance alongside thermal performance.
- Institutional:Healthcare, education, and government buildings. French CSTB and German DIBt fire-test divergence forces parallel certification portfolios for hospital and school projects.
Commercial commands absolute volume leadership, with institutional segments expanding most quickly under EU Green Deal renovation mandates.
Thickness:
Membrane gauge selection balances material cost against puncture resistance and warranty term negotiation.
- 30 mil:Entry specification for cost-sensitive refurbishment. Limited penetration in Northern Europe where building codes favor heavier gauges.
- 40 mil:Standard commercial specification balancing material economy with installation durability. Dominates German and French new construction where contractor warranty terms drive gauge selection.
- 60 mil:Premium specification for high-traffic roofs and extended warranty coverage. Agricultural and industrial applications in the Netherlands favor this gauge for service interval extension.
- 80 mil:Heavy-duty specification for ballasted systems and extreme weather exposure. Limited to specialized applications where mechanical protection requirements override cost considerations.
Forty-mil membranes hold the installed base majority, while sixty-mil specifications are climbing the fastest in warranty-driven commercial segments.
Installation Method:
Attachment methodology determines crew skill requirements, equipment investment, and project scheduling flexibility.
- Adhered:Full-surface bonding with solvent-based or water-based adhesives. Sika leverages its adhesives portfolio to control specification conversations, bundling membrane-adhesive systems for tier-one contractors.
- Mechanically Attached:Fastener-based securing with plates and screws. Preferred for high-wind zones and projects requiring rapid installation turnaround. TPO heat-weldability enables seam integrity without adhesive cure times.
- Ballasted:Loose-laid membrane secured with gravel or concrete pavers. EPDM sustains share here due to membrane dimensional stability under loose-laid stress.
- Others:Induction welding, rhino-bond systems, and emerging adhesive-free technologies. Limited adoption pending long-term performance validation.
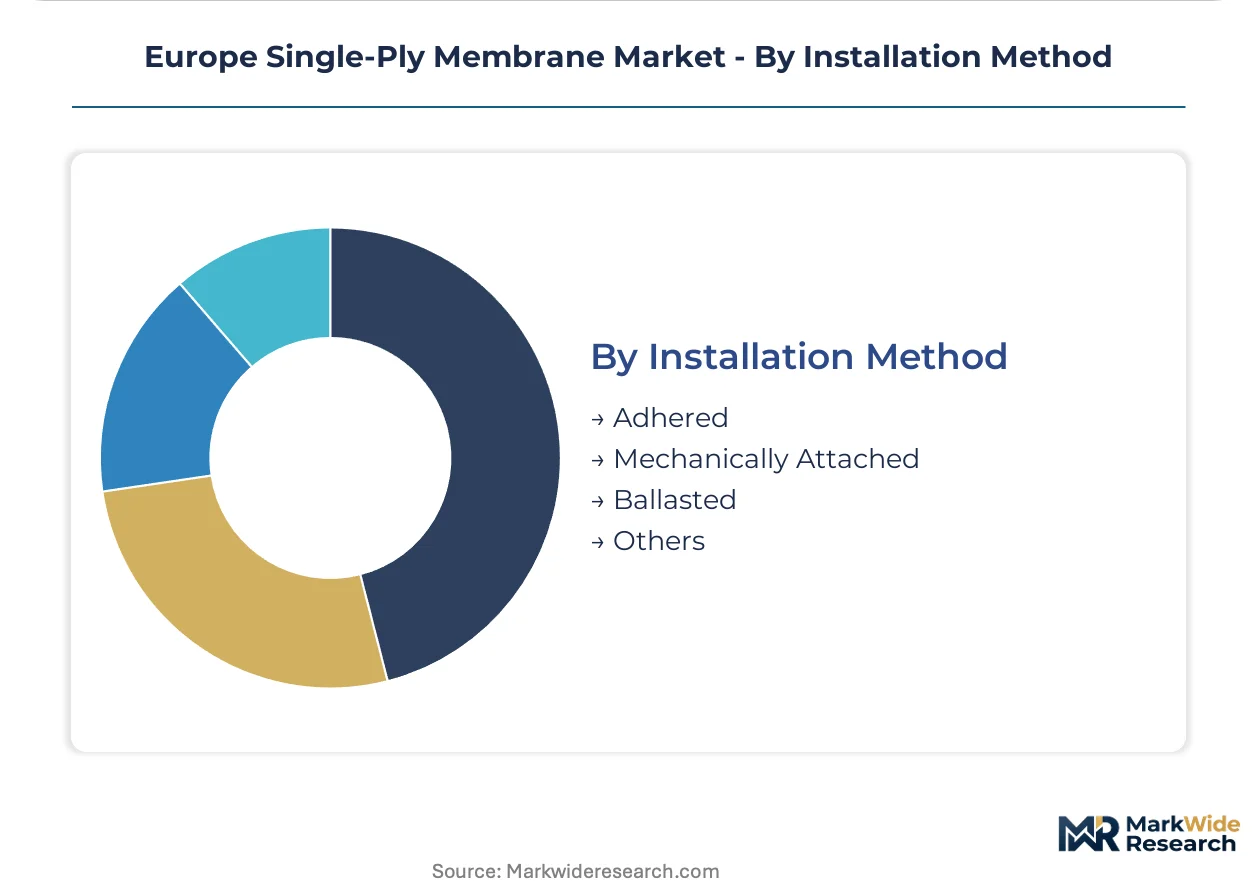
Mechanically attached systems lead by installed volume, though adhered methods are gaining share fastest through adhesive-membrane bundling strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight rail network channels building materials from German manufacturing basins into French and Benelux commercial construction zones. This logistics spine underwrites membrane distribution economics across Northern Europe's renovation-dense markets.
Germany
Frankfurt and Munich office refurbishment pipelines drive TPO specification volume. DIBt fire-test protocols diverge from French CSTB standards, forcing manufacturers to maintain parallel certification portfolios. The Ruhr industrial belt hosts polymer processing clusters supplying calendered sheet to roofing contractors bidding EU Green Deal-mandated thermal upgrades.
France
Paris commercial renovation concentrates specification authority among design-build contractors. The revised Energy Performance of Buildings Directive accelerates membrane replacement cycles in aging office stock. Lyon and Marseille logistics hubs channel Southern European distribution, though certified welder scarcity delays project handovers in these markets.
United Kingdom
London's single-source accountability clauses privilege bundled panel-membrane procurement. Kingspan anchors insulated panel and membrane packaging across Greater London and the Southeast. Birmingham and Manchester distribution networks narrow as building-material merchants consolidate shelf space for certified systems.
Netherlands
Rotterdam port infrastructure imports polymer feedstocks for domestic membrane extrusion. Dairy processing facilities in Friesland specify co-extruded TPO cap sheets for chemical resistance. Amsterdam commercial construction favors mechanically attached systems where high wind exposure demands rapid installation turnaround.
Poland
Warsaw and Krakow office development pipelines remain underpenetrated by specified membrane systems relative to Western European saturation. National building code harmonization with EU Green Deal targets lags, creating specification education gaps among local contractors. Poznan logistics clusters emerge as distribution gateways for Central European expansion.
Europe Single-Ply Membrane Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying polymer formulations and adhesive chemistries. The vendor base organizes around three strategic archetypes: diversified building-material conglomerates with membrane portfolios, pure-play roofing-system specialists, and chemical manufacturers leveraging adhesives expertise into membrane specification. Consolidation pressures concentrate specification authority with tier-one contractors capable of offering design-build warranties. M&A activity targets adhesive-membrane bundling capabilities; geographic expansion focuses on underpenetrated Central European markets.
Among diversified building-material conglomerates, Holcim exemplifies the platform-integrator archetype spanning cement, aggregates, and roofing systems. Kingspan Group and Sika AG occupy positions at the membrane-system tier, with Sika leveraging its adhesives heritage to control specification conversations. Soprema Group represents the hybrid-solution specialist, competing through bitumen and single-ply combinations in French commercial projects. These three anchors illustrate how competitive positioning stratifies between chemical-origin and construction-origin market entry paths.
| Leading Market Players |
|---|
| Holcim |
| Kingspan Group |
| Sika AG |
| RENOLIT SE |
| GAF Materials Corporation |
| Soprema Group |
| Standard Industries Inc. |
| BMI Group |
| Carlisle Construction Materials |
| Others |
Supply & Pricing Matrix
REACH plasticizer restrictions function as a regulatory chokepoint that compresses PVC membrane margins while simultaneously forcing supply chain restructuring toward TPO feedstock diversification. This regulatory pressure widens pricing spreads between compliant premium formulations and legacy PVC alternatives, while polymer processing investments concentrate in German and Benelux manufacturing basins.
Pricing Analysis
Volume-discount tiering structures dominate procurement between building-material merchants and tier-one roofing contractors bidding EU Green Deal-mandated renovation projects. Three-tier pricing stratifies across certified systems with bundled technical support, standard membrane-only specifications, and economy-grade refurbishment alternatives. Cost compression in entry-tier PVC formulations is intensifying because ECHA substance evaluations outpace reformulation timelines. Commercial developers in France exhibit lowest price sensitivity due to single-source accountability clauses, while Polish contractors remain most cost-conscious as specification education gaps persist.
Supply Chain Analysis
Tariff exposure between German polymer processing regions and French commercial construction zones dominates supply chain risk assessment for membrane distributors. Raw material sourcing draws from ethylene-propylene feedstock clusters in the Ruhr industrial belt, plasticizer suppliers in Benelux chemical corridors, and UV stabilizer specialists in Swiss pharmaceutical-chemical hubs. Single-source vulnerability concentrates in EPDM sheet production where specific polymer processing regions expose contractors to lead-time volatility. Distribution runs through consolidated building-material merchant networks that privilege certified membrane systems with direct manufacturer technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Single-Ply Membrane Market operates as a defensive-moat story where regulatory entrenchment creates durable competitive advantages. CE marking pathways and divergent national fire-test protocols erect switching costs that protect incumbent positions.
For Market Incumbents: Build certification moats by accelerating parallel DIBt and CSTB portfolio maintenance ahead of EU Green Deal enforcement deadlines. Threats from emerging bio-based polymer substitutes demand preemptive R&D allocation toward post-consumer feedstock validation. Channel control through adhesive-membrane bundling displaces standalone membrane bidding in London and Frankfurt commercial renovation corridors. For New Entrants and Emerging Players: Mid-market commercial buildings in Warsaw and Krakow represent the most penetrable entry point given specification education gaps among Polish contractors relative to Western European saturation. Agricultural processing facilities in the Netherlands offer secondary white-space for co-extruded TPO cap sheet differentiation. A go-to-market angle anchored on certified welder training partnerships addresses the capability scarcity delaying project handovers in Southern Europe. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified building-material conglomerates with existing membrane portfolios. Long-term viability hinges on backward integration into polymer formulation capabilities and captive adhesive supply chains. Acquisition target archetypes include regional distributors with direct contractor relationships in underpenetrated Central European markets. The signal to watch is Polish national building code harmonization velocity with EU Green Deal thermal efficiency mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Formulation | Captive TPO feedstock supply insulates margin compression from plasticizer volatility. |
| Certified Welder Training Partnerships | Sika and Kingspan contractor certification programs accelerate specification lock-in. |
| Adhesive-Membrane Bundling Expansion | Integrated specification conversations displace standalone membrane bidding in London. |
| Post-Consumer Feedstock Validation | Recycled-content disclosure mandates create first-mover advantage under EU Green Deal. |
| Central European Distribution Gateway Establishment | Poznan logistics clusters channel membrane supply into underpenetrated Polish construction. |
Research Methodology
A standing panel of commercial roofing contractors, building-material merchant procurement leads, polymer R&D directors, and French CSTB certification officials provided ongoing calibration across the study period. Primary interview data combined with secondary validation from ECHA substance evaluation databases, DIBt technical approvals, EU customs trade records, and national building code registries. Bottom-up project pipeline tracking across Frankfurt, Paris, and Warsaw commercial construction zones triangulated against top-down manufacturer shipment analysis.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling polymer chemistry splits, installation method adoption curves, and thickness specification trends alongside regional regulatory divergence patterns. CAGRs derived from elasticity-adjusted replacement cycle modeling incorporating EU Green Deal thermal upgrade mandates and commercial building stock age distributions. Industry-specific forecast inputs included certified welder availability indices and building-material merchant consolidation velocity.
Macroeconomic conditions sit as an overlay; deviation in construction sector lending rates, polymer feedstock commodity indices, or EU carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and contractor specification behavior. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Polyolefin Elastomer Market
Elastomeric Membrane
North America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Europe Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Bio-Based Elastomers Market
Elastomeric Membrane
Global Acrylic Elastomers Market
Elastomeric Membrane
Water Soluble Elastomers Market
Elastomeric Membrane
Polyisoprene Elastomers Market
Elastomeric Membrane
Industrial PU Elastomer Market
Elastomeric Membrane
Global Elastomeric Sealants Market
Elastomeric Membrane
Elastomeric Membrane Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market
Elastomeric Membrane
Vinyl Terminated Polydimethylsiloxane Market
Elastomeric Membrane
Polysulfide Elastomers Market
Elastomeric Membrane
High Temperature Elastomers Market
Elastomeric Membrane
Global Fluoroelastomers Market