
 Ethylene Propylene Elastomers Market | 2026-2036
Ethylene Propylene Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylene Propylene Elastomers Market Analysis
Automotive OEMs is bifurcating from general industrial buyers as the dominant demand archetype for ethylene propylene elastomers. ExxonMobil Corporation leverages its Baytown complex to sustain captive propylene feedstock integration across EPDM and specialty elastomer lines. Dow anchors North American supply through its Plaquemine operations, while Kumho Polychem competes on cost-optimized TPO grades for Korean and Southeast Asian automakers.
Ethylene propylene elastomers are synthetic rubbers produced through Ziegler-Natta or metallocene catalysis of ethylene and propylene monomers, yielding saturated backbone structures with exceptional ozone, heat, and chemical resistance for sealing and insulation duties. EPDM dominates volume consumption in automotive coolant systems and weatherstripping, where sulfur-vulcanized grades tolerate continuous exposure to glycol and road salts. TPO compounds represent the fastest-expanding product category as lightweighting mandates displace PVC and conventional rubber in interior and exterior automotive panels. SEBS maintains premium positioning in medical tubing and soft-touch overmolding applications where thermoplastic processability intersects with biocompatibility requirements.
EPA tailpipe standards and NHTSA fuel-economy regulations in the United States are accelerating reformulation of under-hood elastomers toward higher-temperature grades that endure turbocharged engine environments. REACH restrictions on polycyclic aromatic hydrocarbons in Europe compel compounders to certify extender oils and carbon black feedstocks through ECHA-registered supply chains. China's GB standards for vehicle interior air quality, enforced by SAMR, limit volatile organic compound emissions from automotive elastomer components. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance with one geography's chemical restrictions does not guarantee market access in another.
Market Dynamics
Automotive thermal management intensification is restructuring ethylene propylene elastomer procurement, as turbocharged powertrains and electric vehicle battery cooling systems demand grades rated for sustained exposure above 150°C.
Growth Catalysts
- NHTSA fuel-economy mandates:US automakers reformulate under-hood seals and gaskets toward higher-temperature EPDM grades to accommodate downsized turbocharged engines without thermal degradation.
- Shanghai-Busan manufacturing corridor:Tire and auto-parts clusters in these East Asian hubs source compounded elastomer grades locally, compressing logistics costs and shortening compounder-to-molder lead times.
- Metallocene catalysis:Advanced polymerization technology yields EPDM with narrower molecular weight distribution, enabling thinner-gauge extrusion for lightweight automotive weatherstripping applications.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking economics and refinery output shifts expose EPDM producers to input cost swings that resist full pass-through to contract automotive customers.
- Carbon black supply concentration:Furnace-grade carbon black for reinforcing compounds concentrates among a limited set of suppliers, creating vulnerability when EPA enforcement or plant maintenance disrupts North American availability.
- REACH extender-oil restrictions:ECHA-registered supply chain requirements for low-PAH oils add certification overhead that smaller compounders struggle to absorb without scale economies.
Strategic Opportunities
- Indian automotive expansion:Domestic OEMs and joint-venture assemblers in Chennai and Pune are localizing coolant hose production, creating demand for certified EPDM compounds previously imported from East Asia.
- TPO interior panel penetration:Thermoplastic olefin compounds are capturing share from PVC and conventional rubber in dashboard skins and door panels as OEMs pursue interior air-quality compliance with lower-VOC formulations.
- China GB standards enforcement:SAMR's vehicle interior air-quality regulations limit VOC emissions from elastomer components, favoring suppliers with validated low-emission compound formulations.
Industry Challenges
- Compounder-formulator coordination:Automotive OEMs now require lot-level traceability from raw monomer through vulcanized finished part, forcing tier suppliers to upgrade ERP and quality-management systems.
- Multi-jurisdiction certification timelines:EPDM grades validated for EPA durability testing in the United States require separate REACH dossier review for European market entry, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylene Propylene Elastomers Market |
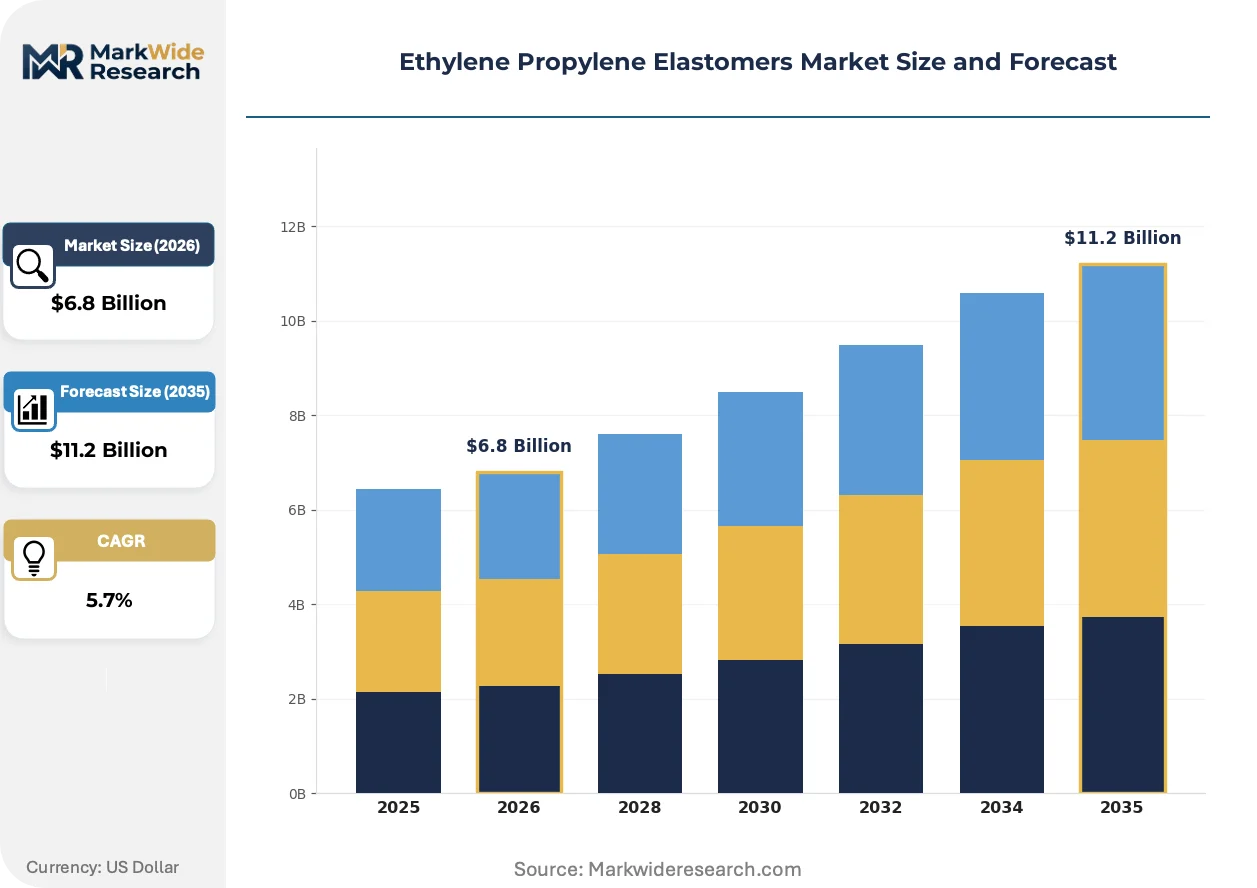
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPDM, EPM, TPO, SEBS End Use Industry: Automotive, Construction, Footwear, Electrical Application: Seals, Hoses, Gaskets, Coatings Form: Granules, Sheets, Compounds, Blends |
| Companies Covered | ARLANXEO, ExxonMobil Corporation, Dow, Versalis S.p.A., PetroChina Company Limited, Lion Elastomers, Mitsui Chemicals, Inc., Kumho Polychem, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylene Propylene Elastomers Market Emerging Trajectories
Polymer architecture innovation and regulatory chemistry restrictions are converging to redefine performance specifications and supply chain qualification protocols across automotive and industrial elastomer applications.
Advanced TPO compounds with dynamically vulcanized EPDM domains are displacing conventional thermoset rubber and rigid thermoplastics in bumper fascias, airbag covers, and interior trim. Korean and German automakers specify these materials for weight reduction and recycling compatibility. The shift is compressing demand for conventional EPDM in non-sealing exterior applications.
REACH restrictions on polycyclic aromatic hydrocarbons in extender oils and carbon black feedstocks are forcing compounders to requalify supply chains through ECHA-registered pathways. European automotive suppliers now require mill certificates documenting PAH content below 10 ppm for all elastomer components. This regulatory friction favors large integrated producers with dedicated analytical laboratories over smaller regional compounders.
Automotive buyers are consolidating supplier panels and demanding compounders assume inventory risk through vendor-managed stock programs at tier-one molding facilities. Japanese OEMs pioneered this procurement compression, which now extends to North American transplant operations. The model concentrates volume among compounders with regional warehousing capabilities and penalizes distant suppliers unable to meet 48-hour replenishment cycles.
Ethylene Propylene Elastomers Market Segmentation
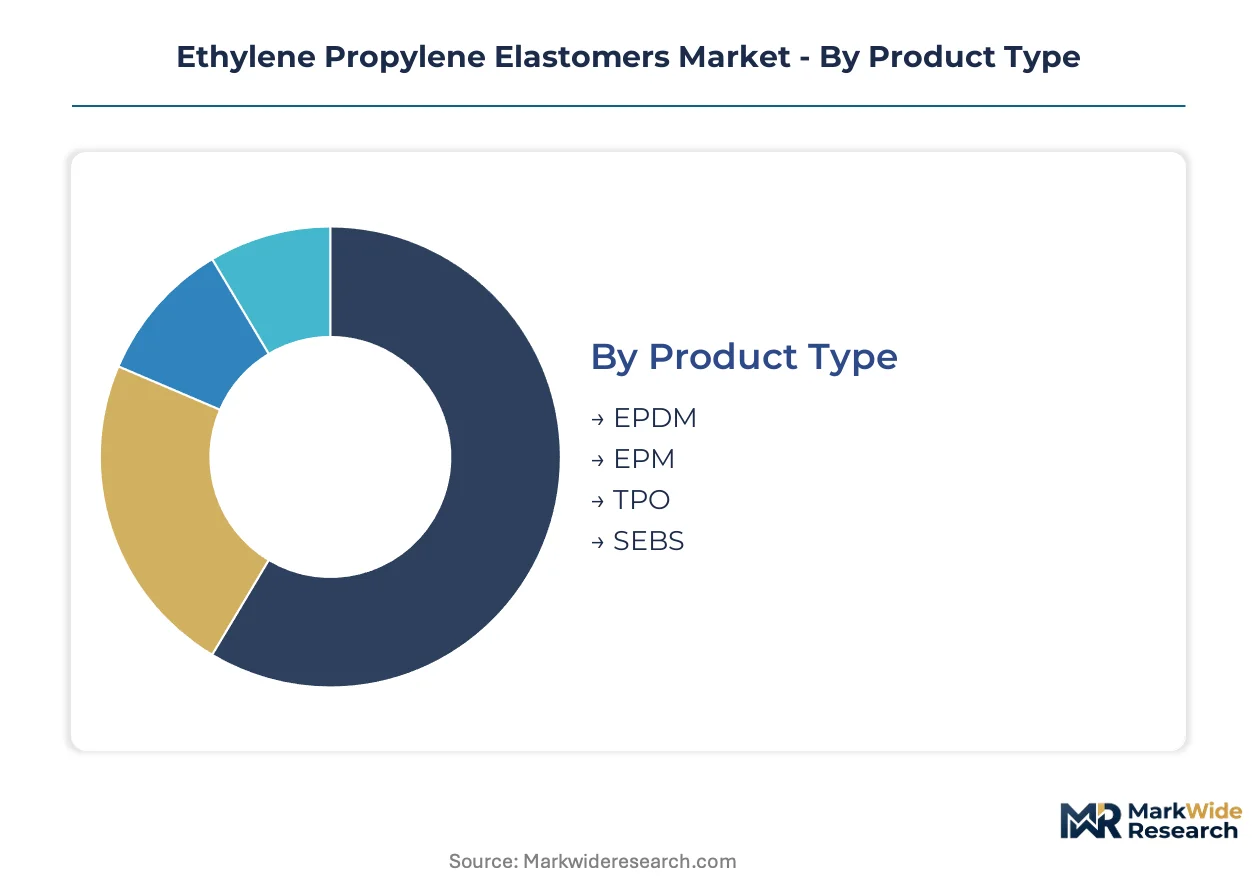
Ethylene propylene elastomer procurement patterns diverge sharply across product chemistries and end-use specifications. Automotive thermal management requirements and regional regulatory frameworks reshape demand concentration within each segment category.
Product Type:
EPDM and TPO dominate export-oriented supply chains serving multinational automotive platforms, while EPM and SEBS concentrate in domestically consumed specialty formulations.
- EPDM:Sulfur-vulcanized terpolymer with ethylidene norbornene or dicyclopentadiene diene monomers enabling crosslink density control. Demand concentrates in Chinese and Indian automotive coolant systems where GB standards and BIS certifications govern glycol resistance specifications.
- TPO:Dynamically vulcanized blends of polypropylene with dispersed EPDM rubber domains deliver thermoplastic processability with elastomeric recovery. Korean automakers in the Busan corridor specify these compounds for bumper fascias and interior panels under vendor-managed inventory programs.
- EPM:Saturated copolymer without reactive diene sites requires peroxide curing systems for crosslink formation.
- SEBS:Hydrogenated styrene block copolymer combining thermoplastic handling with medical-grade biocompatibility.
EPDM holds the largest share; momentum sits with TPO as lightweighting mandates accelerate thermoplastic displacement of conventional thermoset rubber.
End Use Industry:
Customer scale and certification burden separate volume-driven automotive procurement from fragmented construction and footwear buying patterns.
- Automotive:OEM-directed specifications for under-hood seals, weatherstripping, and battery cooling hoses demand lot-level traceability from monomer through vulcanized part. NHTSA fuel-economy regulations and EPA tailpipe standards in the United States compress development cycles for higher-temperature grades.
- Construction:Roofing membranes, window gaskets, and waterproofing sheets consume medium-viscosity EPDM compounds with less stringent lot certification than automotive tiers.
- Footwear:Midsole and outsole applications favor SEBS and TPO for abrasion resistance and colorability in athletic and casual segments.
- Electrical:Cable insulation and connector seals require flame-retardant compounded grades meeting IEC and country-specific safety standards.
Automotive commands the highest compounder margins; construction delivers steadiest volume through project-driven replacement cycles.
Application:
Functional performance requirements and failure-mode consequences determine whether specifications trend toward commodity or engineered compound grades.
- Seals:Static and dynamic sealing applications in engine compartments and battery enclosures specify compression set resistance below 20 percent after 1000 hours at 150°C. Chinese OEMs in Shanghai manufacturing clusters source these grades locally to compress logistics exposure.
- Hoses:Coolant and charge-air ducting demands burst pressure ratings and permeation resistance validated through OEM-specific test protocols.
- Gaskets:Flange and cover seals tolerate broader compound viscosity ranges than dynamic seals.
- Coatings:Spray-applied and dip-coated EPDM layers protect substrates from ozone and UV degradation.
Seals generate the most stringent specification burden; hoses are climbing fastest as electric vehicle thermal management architectures proliferate.
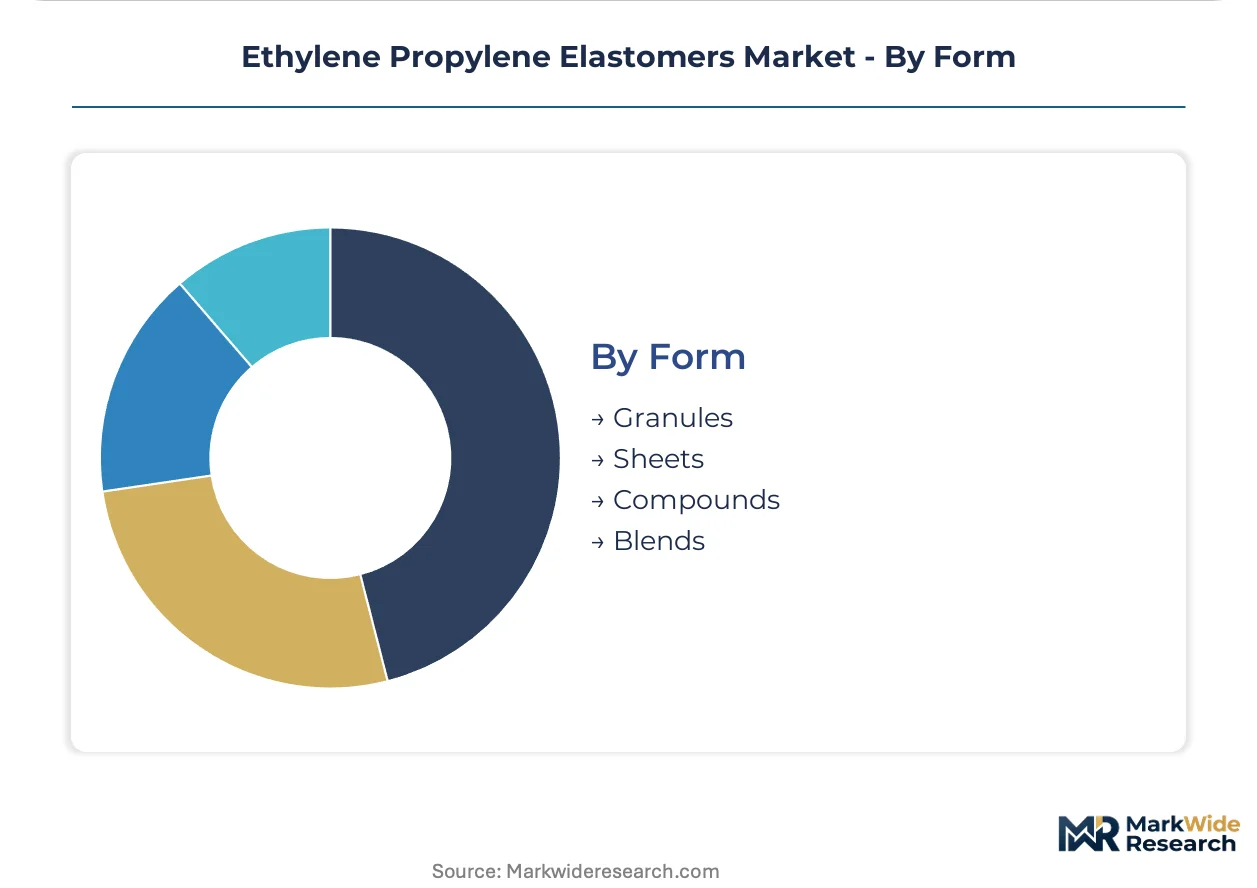
Form:
Processing method and compounder value-add separate raw polymer forms from finished formulations ready for molding or extrusion.
- Granules:Uncompounded EPDM pellets ship in bulk to compounders for custom oil and filler loading. ExxonMobil's Baytown complex and Dow's Plaquemine operations distribute these through regional warehouses serving North American automotive molders.
- Sheets:Calendered EPDM and TPO rolls supply construction membrane fabricators with consistent gauge control.
- Compounds:Pre-formulated grades with curated curative packages and reinforcing fillers arrive ready for injection or compression molding.
- Blends:Customer-specific polymer alloys combine EPDM with polyolefins or thermoplastics for property tuning.
Compounds capture the highest value per kilogram; granules remain the volume foundation for integrated compounder operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai deep-water port and Yangtze River Delta logistics network anchor Asia's ethylene propylene elastomer trade, while Rotterdam's Europoort complex underwrites European compound distribution to automotive clusters.
United States
NHTSA fuel-economy mandates and EPA tailpipe standards accelerate reformulation of under-hood seals toward 150°C-rated EPDM grades. The Plaquemine industrial corridor along the Mississippi River sustains integrated polymer production serving Detroit and Southern transplant automakers. Gulf Coast propylene supply from steam crackers feeds captive elastomer output with pipeline connectivity to Midwest molding facilities.
Germany
REACH extender-oil restrictions and ECHA-registered supply chain requirements compress procurement options for automotive compounders. The Cologne-Düsseldorf-Ruhr manufacturing belt concentrates EPDM compounding capacity serving BMW, Mercedes-Benz, and Volkswagen sealing specifications. KBA vehicle-type approval protocols validate compound grades for EU-wide market access.
China
GB standards for vehicle interior air quality enforced by SAMR limit VOC emissions from automotive elastomer components. The Shanghai-Ningbo manufacturing corridor sources compounded grades locally for tire and battery cooling hose production. MIIT new-energy vehicle mandates expand thermal management elastomer demand beyond conventional powertrain applications.
India
BIS certification requirements for automotive coolant hoses localize EPDM procurement previously imported from East Asia. The Chennai-Pune automotive belt concentrates joint-venture assembly and tier-one molding operations. PLI scheme incentives for auto component manufacturing accelerate compounder investment in domestic compounding facilities.
South Korea
MFDS material safety standards and automaker vendor-managed inventory programs compress compounder-to-molder lead times. The Busan-Ulsan industrial complex anchors TPO production for bumper fascia and interior panel applications. Korean OEMs specify dynamically vulcanized grades for weight reduction and recycling compatibility targets.
Ethylene Propylene Elastomers Market Vendor Landscape
Concentration sits with integrated petrochemical majors controlling captive ethylene and propylene feedstock positions. The competitive structure stratifies across three tiers: global polymer producers with metallocene technology platforms, regional compounders serving automotive vendor-managed inventory programs, and specialty elastomer houses focused on medical-grade SEBS formulations. Capacity expansion and strategic raw material partnerships constitute the dominant competitive moves, with producers securing long-term naphtha or propane supply agreements to buffer feedstock volatility.
Within the integrated producer tier, ExxonMobil Corporation and Dow exemplify the feedstock-anchored archetype with Gulf Coast manufacturing positions, while Kumho Polychem represents the Asia-Pacific cost-optimized compounder serving Korean and Southeast Asian automakers. ARLANXEO and Versalis S.p.A. occupy positions within the European specialty elastomer segment, with the former reflecting the Lanxess-Saudi Aramco joint venture structure and the latter embodying the Mediterranean-based petrochemical integration model. These named entities serve as anchors for understanding how geographic feedstock access and regulatory compliance capabilities determine competitive positioning across automotive, construction, and industrial end-use segments.
| Leading Market Players |
|---|
| ARLANXEO |
| ExxonMobil Corporation |
| Dow |
| Versalis S.p.A. |
| PetroChina Company Limited |
| Lion Elastomers |
| Mitsui Chemicals, Inc. |
| Kumho Polychem |
| SABIC |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Gulf Coast steam crackers shapes both the supply concentration among integrated petrochemical majors and the price floors that resist full pass-through to automotive contract customers. Naphtha-cracking economics and refinery output shifts expose EPDM producers to input cost volatility that compresses margins during propylene feedstock spikes.
Pricing Analysis
Volume-discount tiering separates automotive OEM annual contracts from spot purchases by regional construction compounders. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and thermal performance grade, with REACH-validated compounds commanding spreads over general-purpose roofing grades. Pricing pressure stems from propylene feedstock volatility that resists contractual pass-through mechanisms. Construction membrane fabricators exhibit highest price sensitivity due to project-driven procurement, while automotive tier suppliers absorb premiums for lot-level traceability.
Supply Chain Analysis
Strait of Malacca transit routes underpin carbon black feedstock flows from Southeast Asian furnace-grade producers to East Asian compounding hubs. Supply concentrates in the United States, China, and South Korea, with each anchoring distinct technology platforms: metallocene catalysis, cost-optimized TPO grades, and dynamically vulcanized compounds respectively. Raw material dependencies center on propylene monomer, furnace-grade carbon black, and ECHA-registered extender oils. Single-source vulnerability concentrates in carbon black reinforcing agents where EPA enforcement actions disrupt North American availability. Distribution runs through vendor-managed inventory programs at tier-one molding facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ethylene propylene elastomers market sits in a cyclical recovery phase as automotive production normalization and electric vehicle thermal management intensification restock channel inventories. NHTSA fuel-economy mandates provide the cyclical impetus by accelerating specification upgrades across under-hood applications.
For Market Incumbents: Consolidate supplier panel positions by deepening captive propylene integration at Gulf Coast and Shanghai corridor manufacturing complexes. Defend against TPO displacement threats in non-sealing exterior applications by accelerating metallocene platform investments for thinner-gauge extrusion. Channel control through vendor-managed inventory programs at Korean and Japanese transplant operations preserves volume concentration.
For New Entrants and Emerging Players: Anchor in Indian domestic compounding capacity where PLI scheme incentives and BIS certification requirements localize procurement previously imported from East Asia. White-space targets include certified EPDM compounds for Chennai-Pune coolant hose production and low-VOC formulations for SAMR GB standards compliance. Go-to-market execution should prioritize technical partnership with domestic OEM joint ventures over direct tier-one competition.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with validated REACH dossiers and ECHA-registered supply chains over raw polymer producers exposed to feedstock volatility. Long-term viability across the analysis window hinges on thermal management grade portfolios aligned with electric vehicle battery cooling architectures. Acquisition screening should target regional compounders with automotive certification infrastructure. The signal to watch is MIIT new-energy vehicle mandate acceleration as inflection indicator for specialty grade demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstock | Captive naphtha-cracking capacity at Baytown and Plaquemine insulates margin compression from refinery output swings. |
| Metallocene Catalysis Platform Expansion | Narrower molecular weight distribution enables thinner-gauge extrusion for NHTSA-driven lightweighting mandates. |
| REACH Supply Chain Requalification | ECHA-registered extender oil pathways satisfy KBA vehicle-type approval for BMW and Mercedes-Benz sealing specifications. |
| Vendor-Managed Inventory Programs | Japanese OEM procurement compression concentrates volume among compounders with 48-hour Busan-Ulsan replenishment cycles. |
| Indian Domestic Compounding Investment | PLI scheme incentives accelerate Chennai-Pune capacity to capture BIS-certified coolant hose localization. |
Methodological Framework
Initial hypotheses were tested against primary input from EPDM plant managers, automotive tier supplier procurement leads, construction membrane fabricators, and technical R&D directors at compounder operations, then refined against customs trade data, ACC and Cefic industry reports, SEC 10-K polymer segment disclosures, and vehicle production databases. Bottom-up volume builds from grade-specific consumption rates triangulated against top-down market sizing from integrated producer capacity announcements.
Variance decomposition across the projection horizon isolates feedstock cost pass-through elasticity, regulatory compliance burden effects, and automotive platform content-per-vehicle shifts. Segmentation dimensions modeled include product chemistry tier, end-use industry vertical, thermal performance grade, and regional production hub clustering. CAGRs derive from elasticity-adjusted demand curves and capacity utilization trajectories, with specific inputs from MIIT new-energy vehicle production schedules and EPA tailpipe standard implementation timelines.
Material uncertainties — propylene feedstock volatility spikes, REACH extender oil restriction enforcement intensity, and automotive platform thermal management architecture shifts — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as SAMR GB standards enforcement and NHTSA fuel-economy mandate calibration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Polyurethane Elastomers Market
Elastomeric Membrane
High Temperature Elastomers Market
Elastomeric Membrane
Middle-East and Africa (EMEA) Elastomers Market
Elastomeric Membrane
Specialty Elastomer Market
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Global Fluoroelastomers Market
Elastomeric Membrane
UV Stabilized Thermoplastic Elastomer Market
Elastomeric Membrane
Global Acrylic Elastomers Market
Elastomeric Membrane
Elastomeric Foam Insulation Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Modified Silicone Fluids Market
Elastomeric Membrane
Elastic Laminates Market
Elastomeric Membrane
Europe Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Europe Single-Ply Membrane Market
Elastomeric Membrane
Medical Styrenic Block Copolymer (SBC) Market
Elastomeric Membrane
Cold Cast Elastomers Market