
 Elastomeric Membrane Market | 2026-2036
Elastomeric Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Elastomeric Membrane Market Analysis
FM Global 4470 approval is collapsing as the decisive qualification gate for commercial roofing membrane suppliers, effectively filtering out regional formulators lacking fire-performance testing infrastructure. Soprema Group leverages its integrated bitumen and polymer supply chain to sustain specification dominance across North American commercial projects. Dow anchors the silicone elastomer segment through captive silane chemistry and vertical control over raw siloxane feedstocks. GAF competes aggressively on contractor channel access, operating one of the largest certified installer networks in residential and light commercial roofing.
Elastomeric membranes are synthetic polymer sheets or liquid-applied coatings engineered from ethylene-propylene-diene monomer, thermoplastic polyolefin, or polyurethane resins, typically formulated to achieve elongation exceeding 300% and tensile strength above 7 MPa for seamless waterproofing of roofs, foundations, and industrial surfaces. Their primary commercial purpose is to prevent moisture ingress while accommodating structural movement and thermal cycling across decades of service life. Thermoplastic elastomers and polyurethane product categories dominate current volume, with silicone membranes commanding premium positioning in high-temperature and chemically exposed environments where standard formulations degrade prematurely. Waterproofing and membranes applications absorb the majority of demand, while coatings represent the fastest-growing application as building owners shift from full replacement to restorative overlay strategies that extend existing roof service life.
FM Global 4470, Underwriters Laboratories 2218, and ASTM D6878 collectively shape product development priorities by mandating specific fire-resistance, puncture, and weathering performance thresholds for market access in commercial construction. The US Department of Energy's cool-roof requirements and California Title 24 energy standards directly accelerate specification of white-reflective TPO and PVC membranes by tying building permit approval to solar reflectance index thresholds. Stakeholders must monitor evolving polymer feedstock volatility and tightening per- and polyfluoroalkyl substance regulations, as these forces will determine which chemistries retain cost competitiveness and regulatory acceptability across the next specification cycle.
Market Dynamics
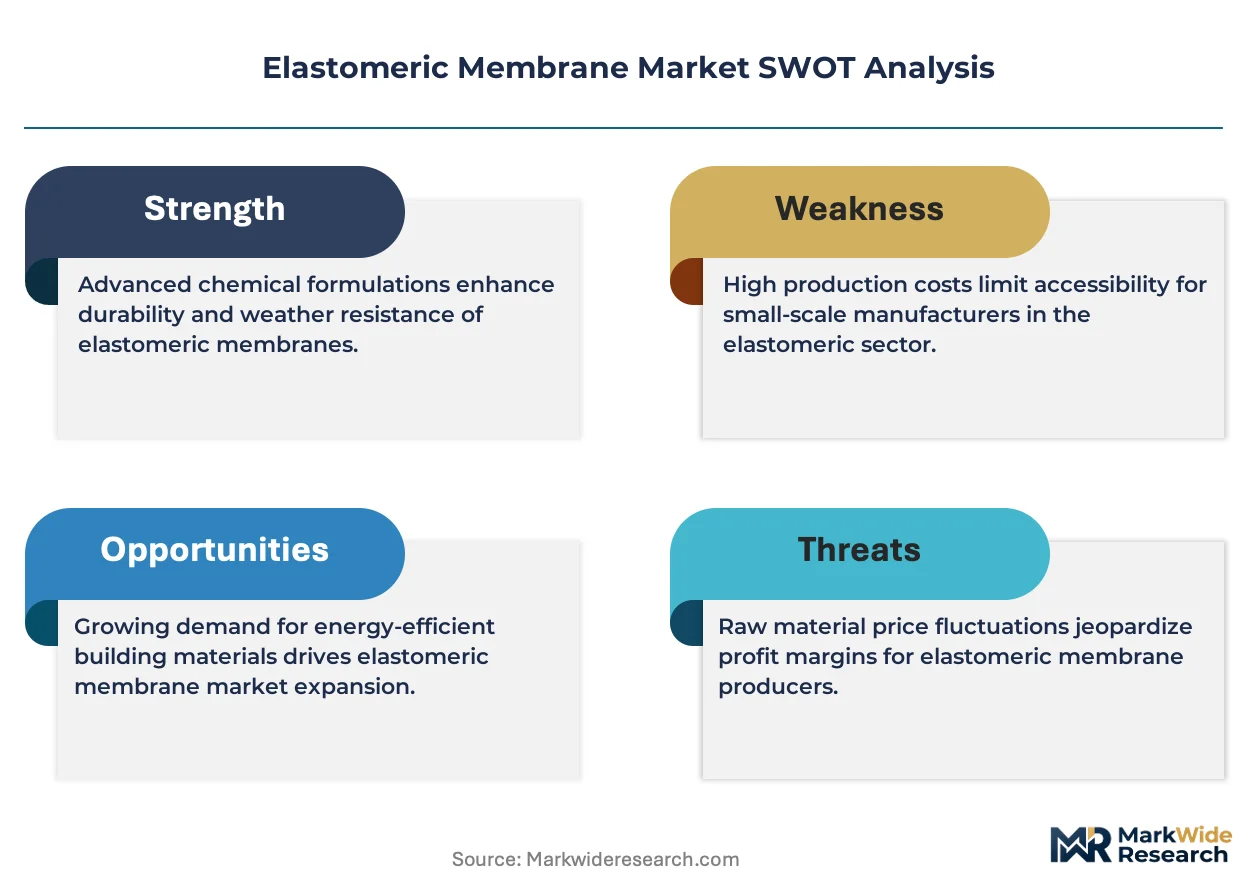
FM Global 4470 approval requirements are compressing the supplier base for commercial roofing membranes, forcing regional formulators to either build fire-performance testing infrastructure or exit specification-grade markets entirely.
Growth Catalysts
- California Title 24 cool-roof mandates:Building permit approvals now hinge on solar reflectance index thresholds, accelerating specification of white-reflective TPO and PVC membranes across commercial construction.
- Infrastructure renewal spending:Federal and state-level building envelope upgrade programs are driving membrane replacement cycles in aging commercial and institutional facilities.
- EPDM formulation advances:Enhanced UV stabilizers and seam-tape technologies are extending service life claims beyond 30 years, reinforcing specification preference in long-durability applications.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and propylene monomer prices fluctuate with crude oil markets, compressing margin predictability for TPO and EPDM membrane producers.
- PFAS regulatory scrutiny:Per- and polyfluoroalkyl substance restrictions under EPA and state-level frameworks threaten certain membrane additive chemistries with reformulation costs or discontinuation.
- Silicone raw material concentration:Siloxane feedstock production clusters in China and Germany, creating geographic supply risk for high-temperature silicone membrane formulators.
Strategic Opportunities
- Restorative overlay coatings:Building owners are shifting from full roof replacement to liquid-applied elastomeric overlays, opening service-life extension contracts for coating specialists.
- Industrial cold-storage facilities:Thermal shock resistance requirements in refrigerated warehouses favor polyurethane spray foam and membrane hybrid systems with specialized contractors.
- US Department of Energy cool-roof incentives:Tax credit extensions for reflective roofing materials are pulling TPO and white EPDM into federal building retrofit specifications.
Industry Challenges
- Certified installer scarcity:FM Global 4470 and manufacturer warranty programs require trained applicator networks, constraining project throughput where certification density lags demand.
- Legacy substrate compatibility:Adhesion chemistry must accommodate aged asphalt, metal, and single-ply surfaces in restoration applications, complicating specification standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elastomeric Membrane Market |
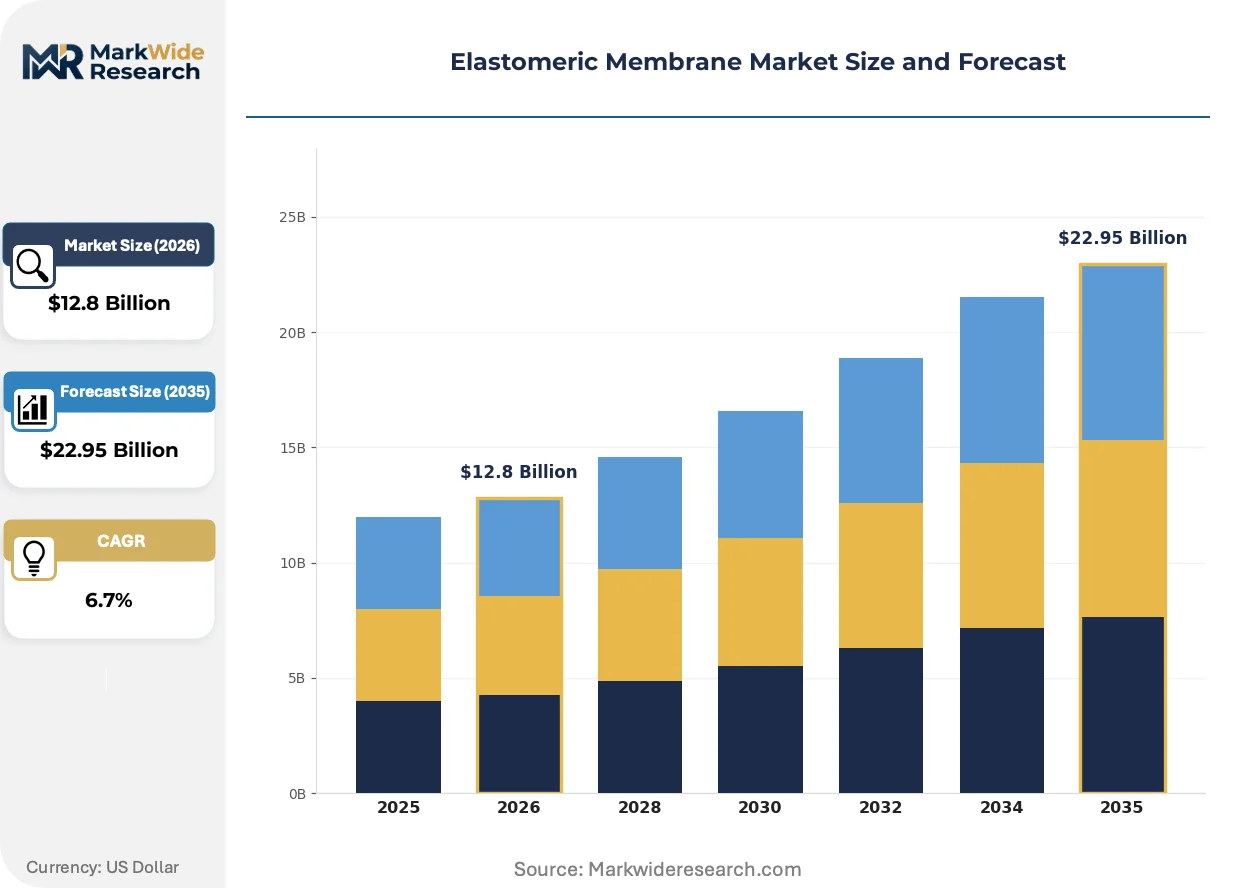
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
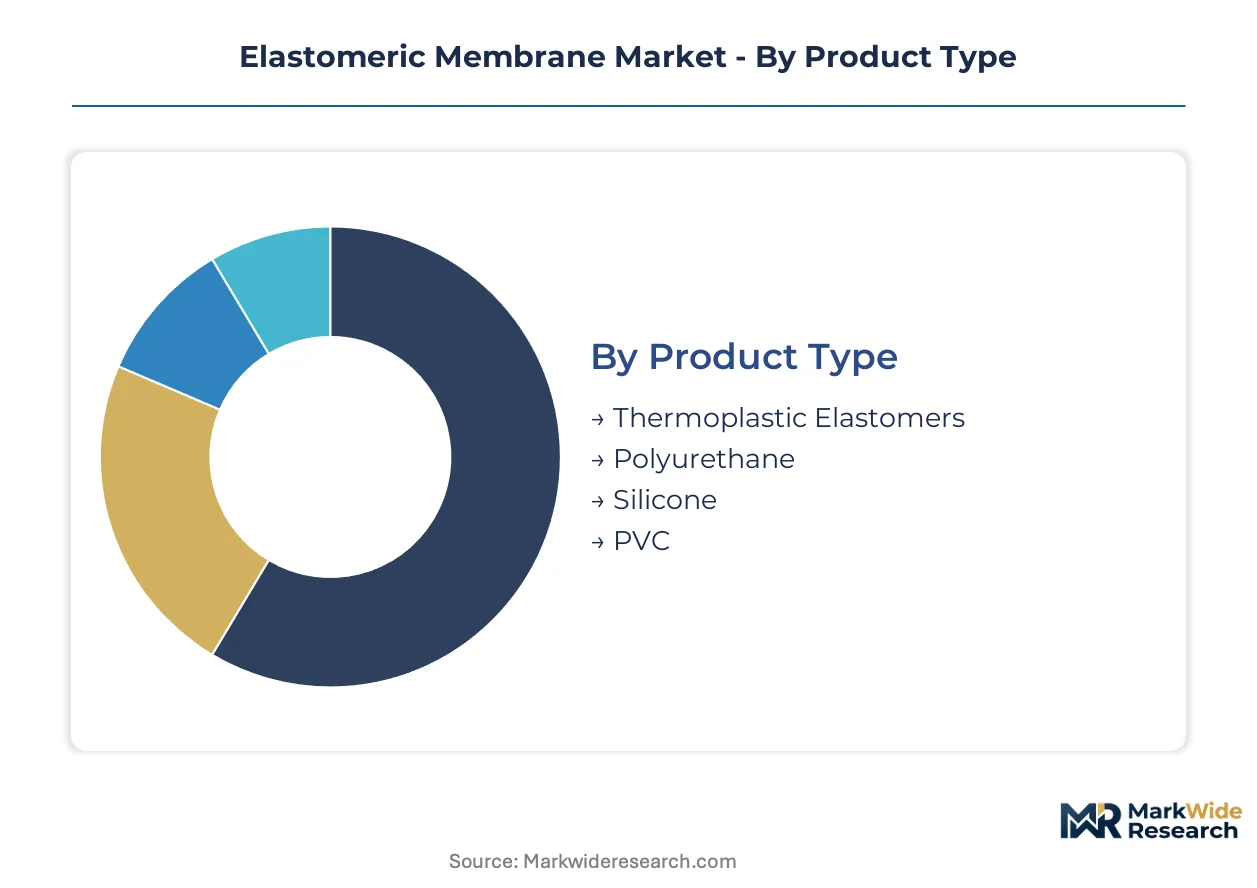
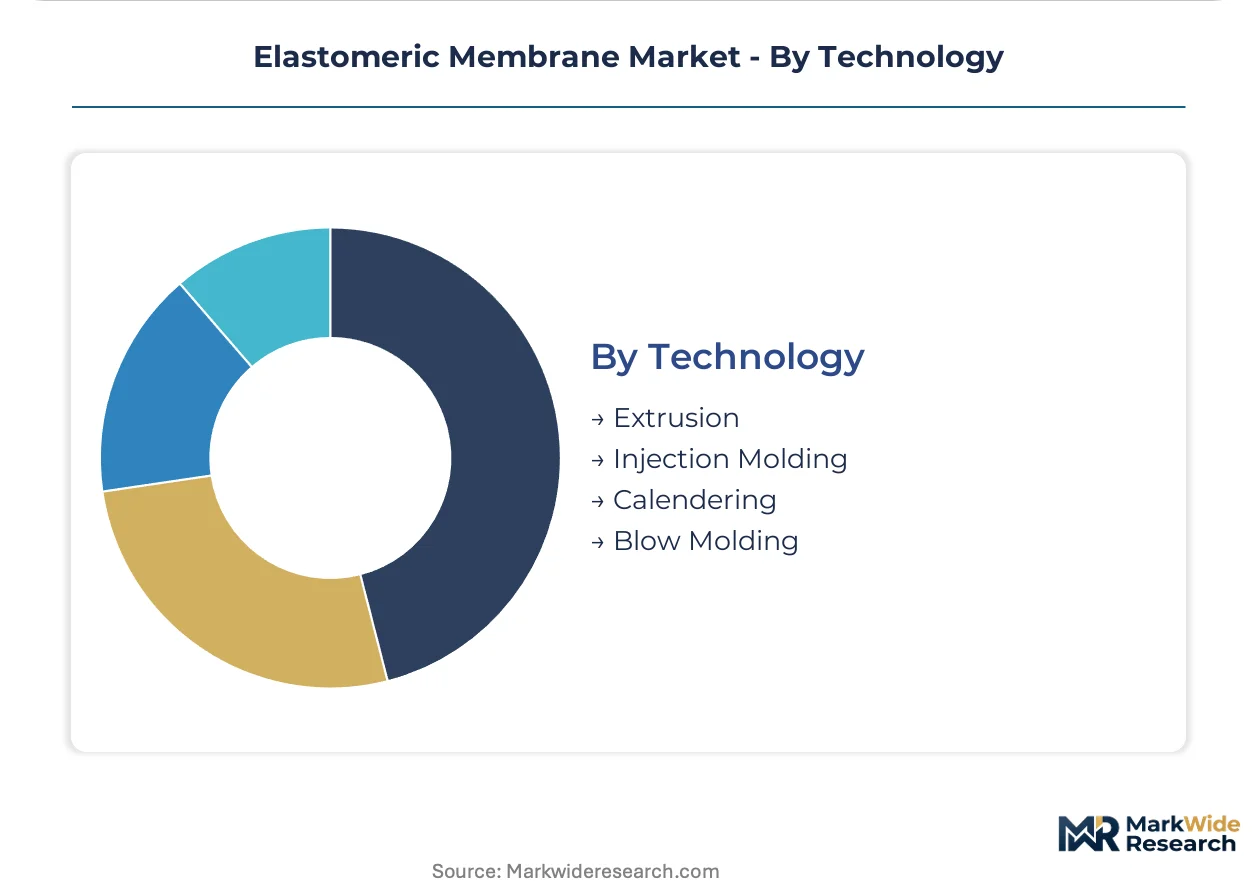
| Segmentation | Product Type: Thermoplastic Elastomers, Polyurethane, Silicone, PVC End User: Construction, Automotive, Aerospace, Medical Application: Waterproofing, Coatings, Seals, Membranes Technology: Extrusion, Injection Molding, Calendering, Blow Molding |
| Companies Covered | Soprema Group, Dow, Sika AG, GAF, Owens Corning, Carlisle Companies Inc., Johns Manville Corporation, Firestone Building Products, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elastomeric Membrane Market Emerging Trajectories
Membrane chemistry is diverging into performance-specialized tracks as building codes tighten and building owners prioritize total lifecycle cost over first-cost procurement.
Self-adhering membrane technology is bifurcating the commercial roofing installation market. Factory-applied adhesive layers eliminate field welding and solvent-based bonding, cutting labor hours by half on large flat-roof projects. General contractors and national roofing service providers are specifying these systems for accelerated project schedules. The technology is compressing demand for traditional hot-air welding equipment and certified welder labor pools.
REACH restrictions on persistent organic pollutants and the EU F-Gas Regulation are forcing reformulation of certain membrane blowing agents and fire-retardant additives used in European commercial construction. Membrane producers serving EU markets must validate alternative chemistries through ECHA notification processes. TPO formulations with reduced halogen content are gaining specification share in German and French public infrastructure tenders.
Building owners now bundle membrane procurement with predictive maintenance monitoring, displacing traditional material-only purchasing. Sensor-enabled roof systems that track moisture intrusion and thermal performance are being specified through facilities management contracts rather than capital expenditure channels. This shift is most pronounced in US healthcare and data center verticals where unplanned downtime carries severe operational penalties.
Elastomeric Membrane Market Segmentation
Elastomeric membrane manufacturers must align product portfolios with divergent regulatory requirements across construction, automotive, and medical end uses. Each segment demands distinct certification pathways and performance specifications that reshape formulation priorities and production investments.
Product Type:
REACH restrictions on persistent organic pollutants and EPA PFAS scrutiny are fragmenting competitive positioning across polymer chemistries, with regulatory compliance costs now determining viable market entry.
- Thermoplastic Elastomers:TPO formulations dominate commercial roofing specifications where California Title 24 cool-roof mandates and US Department of Energy solar reflectance thresholds drive white-reflective membrane demand. TPO absorbs the majority of waterproofing volume in North American commercial construction due to seam strength and UV stability.
- Polyurethane:Spray-applied and liquid-cast systems command industrial cold-storage and foundation waterproofing applications where thermal shock resistance and substrate adhesion flexibility prove critical. Polyurethane is gaining specification share in restorative overlay projects as building owners prioritize service-life extension over full replacement.
- Silicone:High-temperature stability and chemical resistance position silicone membranes in aerospace engine seals and industrial exhaust containment where standard elastomers degrade.
- PVC:Halogen-containing formulations face reformulation pressure under EU F-Gas Regulation and emerging state-level restrictions, though PVC retains cost advantage in specific commercial roofing segments.
Thermoplastic elastomers handle the majority of throughput; polyurethane is expanding most quickly on specification share.
End User:
Customer procurement patterns concentrate volume in capital-intensive construction verticals while medical and aerospace segments command premium pricing through qualification barriers.
- Construction:Commercial roofing, foundation waterproofing, and building envelope applications absorb membrane volume as infrastructure renewal programs and energy code tightening accelerate replacement cycles. FM Global 4470 approval requirements filter supplier participation in specification-grade commercial projects.
- Automotive:Underhood seals, gaskets, and NVH dampening components utilize EPDM and TPV formulations where OEM durability specifications exceed 150,000-mile service life. Automotive demand concentrates in platforms serving electric vehicle battery enclosure sealing.
- Aerospace:Fuel tank seals, engine gaskets, and environmental control system components require FAA-compliant materials with extreme temperature cycling performance. Qualification timelines and traceability requirements sustain incumbent supplier positions.
- Medical:Biocompatible silicone and thermoplastic elastomer films serve wound care, drug delivery, and device sealing applications where FDA 510(k) or EU MDR clearance governs market access.
Construction commands the dominant share of volume; medical represents the steepest expansion trajectory on per-unit value growth.
Application:
Application selection determines installation methodology, warranty structure, and contractor certification requirements that shape go-to-market economics.
- Waterproofing:Roofing membranes, below-grade barriers, and plaza deck systems constitute the foundational application where building code compliance and insurer approval requirements dominate specification. Waterproofing absorbs the majority of membrane square footage in commercial and institutional construction.
- Coatings:Liquid-applied elastomeric overlays enable restorative roof renewal without tear-off, cutting project cost and landfill burden. Coatings are climbing the fastest as facilities management contracts displace capital expenditure procurement channels.
- Seals:Compression seals, expansion joints, and gasket applications serve structural movement accommodation in bridges, parking structures, and industrial facilities.
- Membranes:Sheet goods for controlled environment agriculture, pond liners, and secondary containment represent specialized volume with distinct distribution channels.
Waterproofing handles the majority of throughput; coatings are gaining share fastest on building owner preference for overlay strategies.
Technology:
Processing technology selection locks manufacturers into specific capital equipment bases and labor skill requirements that constrain product line flexibility.
- Extrusion:Continuous sheet production for roofing membranes and geomembranes achieves economies of scale in high-volume TPO and EPDM product lines. Extrusion dominates waterproofing sheet goods manufacturing.
- Injection Molding:Complex three-dimensional seals, gaskets, and medical components require precision tooling and automated part removal systems. Injection molding serves automotive and medical end uses where dimensional tolerance is critical.
- Calendering:Textured sheet production and fabric-reinforced membrane manufacturing utilize calendering lines for built-up roofing and single-ply systems with embedded scrim reinforcement.
- Blow Molding:Hollow profile seals and inflatable gasket applications employ blow molding for specific aerospace and industrial sealing geometries.
Extrusion handles the majority of throughput; injection molding is climbing fastest on medical and automotive specification growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cool-roof mandates and energy code tightening are redrawing procurement geography across construction markets. The United States, Germany, China, Japan, and India concentrate specification-grade membrane demand through divergent regulatory pathways.
United States
California Title 24 solar reflectance thresholds and US Department of Energy tax credit extensions accelerate white-reflective TPO and EPDM specifications. Federal building envelope upgrade programs drive membrane replacement cycles in aging institutional facilities. Chicago and Dallas-Fort Worth metropolitan construction markets absorb substantial waterproofing sheet volume through commercial roofing contractors.
Germany
Public infrastructure tenders increasingly specify reduced-halogen TPO formulations under EU F-Gas Regulation pressure. ECHA notification processes for alternative blowing agents extend product development timelines for membrane producers. The Rhine-Ruhr industrial corridor hosts concentrated manufacturing capacity for European specification-grade roofing systems.
China
Dual carbon goals and building energy efficiency standards expand cool-roof membrane demand in commercial construction. MEE enforcement of industrial emission controls raises production compliance costs for domestic formulators. Yangtze River Delta megacity clusters drive waterproofing volume through high-rise residential and logistics facility construction.
Japan
METI building energy conservation standards tighten thermal performance requirements for commercial envelopes. JIS certification mandates filter supplier participation in public works membrane specifications. Kanto region reconstruction and seismic retrofit programs sustain demand for high-elongation waterproofing systems.
India
Bureau of Indian Standards certification requirements and state-level green building codes expand specification-grade membrane penetration. PLI scheme incentives for construction materials attract domestic manufacturing investment. Maharashtra and Gujarat industrial corridors concentrate waterproofing demand through pharmaceutical and data center facility construction.
Elastomeric Membrane Market Vendor Landscape
Listed leaders compete with private specialists across certification infrastructure and installer network scale. The supplier base compresses around FM Global 4470 approval requirements while fragmenting across regional formulators lacking fire-performance testing capabilities. Three archetypes dominate: integrated petrochemical players with captive polymer supply, specialized roofing system providers with certified installer networks, and diversified construction chemical conglomerates with cross-selling infrastructure. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms seek geographic coverage and specification-grade certification density.
Within the integrated chemical tier, Dow and BASF SE anchor positions through upstream control over siloxane and polyurethane precursor supply. Among specialized roofing providers, Soprema Group and GAF exemplify divergent channel strategies—Soprema through integrated bitumen-polymer supply chain dominance in commercial specification, GAF through contractor network scale in residential and light commercial segments. Sika AG occupies a position bridging construction chemical breadth with membrane-specific formulation expertise.
| Leading Market Players |
|---|
| Soprema Group |
| Dow |
| Sika AG |
| GAF |
| Owens Corning |
| Carlisle Companies Inc. |
| Johns Manville Corporation |
| Firestone Building Products |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at integrated TPO and EPDM sheet extrusion facilities in the United States and Germany shapes both supply concentration and price floors, as regional formulators lacking FM Global 4470 testing infrastructure are filtered from specification-grade markets. This scale-driven consolidation compresses margin predictability for smaller players while anchoring pricing power among petrochemical-backed producers with captive polymer supply.
Pricing Analysis
Certification level creates the primary spread across membrane pricing tiers, with FM Global 4470 and UL 2218 approvals commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium specification-grade, standard commercial, and economy retrofit tiers reflects differentiation by fire-performance testing, warranty length, and installer network density. Cost compression in standard commercial tiers is intensifying because petrochemical feedstock volatility erodes margin buffers for non-integrated formulators. Building envelope contractors serving federal and institutional projects exhibit lowest price sensitivity, while residential roofing distributors face acute pressure from spot-market commodity alternatives.
Supply Chain Analysis
Inventory cycles for ethylene and propylene monomers extend lead times by four to eight weeks during cracker maintenance seasons, forcing membrane producers to hold buffer stocks of polymer resins. Geographic supply concentration centers on the United States, Germany, and China, where integrated petrochemical complexes feed extrusion and calendering lines. Raw material dependencies include ethylene-propylene rubber, thermoplastic polyolefin pellets, and siloxane precursors for silicone formulations. Single-source vulnerability in siloxane feedstock from China and Germany creates geographic concentration risk for high-temperature membrane specialists. Distribution runs through certified contractor networks and roofing distributor channels rather than direct-to-owner sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane incumbents face sustained substitution pressure from liquid-applied coating systems that bypass full tear-off replacement cycles, requiring defensive positioning around service-life extension value propositions.
For Market Incumbents: Fortify specification-grade positioning by deepening captive supply of polymer resins and expanding FM Global 4470 certification density across contractor networks. Acquire or partner with predictive maintenance sensor providers to bundle membrane procurement with facilities management contracts, countering coating substitution in healthcare and data center verticals. For New Entrants and Emerging Players: Differentiate on restorative overlay specialization by targeting building owners in aging commercial stock with liquid-applied polyurethane systems that avoid full roof replacement. Penetrate industrial cold-storage facilities in the United States and Germany where thermal shock resistance requirements filter out standard membrane competitors, leveraging spray-applied application expertise as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized roofing system providers with certified installer networks over diversified construction chemical conglomerates with cross-selling breadth but membrane-weak positioning. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than formulation novelty alone. Target acquisition archetypes include regional formulators with FM Global 4470 approval but limited geographic coverage. The signal to watch is EPA PFAS restriction enforcement timelines that will force reformulation costs and consolidate viable supplier bases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resins | Captive ethylene-propylene supply secures margin stability against crude-linked feedstock volatility. |
| FM Global 4470 Certification Expansion | Fire-performance testing infrastructure filters regional competitors from commercial specification access. |
| Predictive Maintenance Sensor Partnership | Facilities management contract bundling displaces capital expenditure procurement channels in healthcare. |
| Restorative Overlay Coating Development | Liquid-applied systems capture building owner preference for service-life extension over full replacement. |
| Industrial Cold-Storage Specialization | Thermal shock resistance requirements in refrigerated warehouses favor polyurethane hybrid system providers. |
Methodological Framework
A spread of perspectives from membrane manufacturing executives, commercial roofing contractors, facilities management directors, and building envelope specifiers converged on the working assumptions underlying volume and value estimates. Primary fieldwork combined structured interviews with secondary validation through customs trade data, ACC industry reports, SEC 10-K filings of listed chemical producers, and FM Global approval registries. Bottom-up triangulation across polymer throughput at extrusion facilities and top-down cross-checks against construction spending data anchored the analytical framework.
Segmentation dimensions modeled include product chemistry, application methodology, end-use vertical, and regional regulatory cluster across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves that incorporate building code tightening trajectories and infrastructure renewal program allocations. Forecast inputs incorporated California Title 24 solar reflectance threshold enforcement and US Department of Energy tax credit extension patterns alongside EU F-Gas Regulation reformulation timelines.
Material uncertainties — polymer feedstock price spikes, EPA PFAS restriction scope expansion, and certified installer network capacity constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and construction cycle timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Bio-Based Elastomers Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Elastomeric Foam Insulation Market
Elastomeric Membrane
Industrial PU Elastomer Market
Elastomeric Membrane
Global Acrylic Elastomers Market
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Asia-Pacific Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Global Fluoroelastomers Market
Elastomeric Membrane
Modified Silicone Fluids Market
Elastomeric Membrane
Middle-East and Africa Fluoroelastomers Market
Elastomeric Membrane
North America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Styrene Ethylene Butylene Styrene (SEBS) Market
Elastomeric Membrane
Hot Cast Elastomers Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market
Elastomeric Membrane
Ethylene Propylene Diene Monomer(EPDM) Market
Elastomeric Membrane
Water Soluble Elastomers Market