
 Micro Thermoelectric Modules Market | 2026-2036
Micro Thermoelectric Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Thermoelectric Modules Market Foresight
Medical device OEMs is bifurcating from consumer electronics brands as the dominant buyer archetype in micro thermoelectric procurement. Ferrotec Holdings Corporation leverages its bismuth telluride material capabilities to anchor supply for precision thermal management. Laird Thermal Systems competes through integrated thermal subsystem design for implantable and wearable medical applications. TEC Microsystems differentiates via miniaturized multi-stage modules targeting spectroscopy and PCR instrumentation.
Micro thermoelectric modules are solid-state heat pump devices constructed from alternating p-type and n-type semiconductor pellets, typically bismuth telluride alloys, that achieve temperature differentials of 40–70°C across footprints below 10 mm² for spot cooling and precision temperature stabilization. Single-stage modules occupy the volume baseline in consumer and industrial applications where moderate ΔT requirements suffice, while multi-stage modules command margin pools in medical imaging and laser systems demanding sub-ambient precision below 0.01°C stability. Flexible modules represent the fastest-growing product configuration as conformable substrates enable thermal management in curved wearable electronics and miniaturized automotive sensor housings.
The EU F-Gas Regulation and REACH restrict hydrofluorocarbon refrigerants in instruments under 50 kW cooling capacity, directly expanding addressable market for solid-state alternatives in European laboratory and clinical equipment. FDA 21 CFR Part 820 quality system requirements for active medical devices shape thermal validation protocols that module suppliers must document for OEM qualification. Stakeholders should monitor evolving IEC 60749 reliability standards for semiconductor thermal cycling as these test methods increasingly determine supplier selection in automotive LiDAR and autonomous sensor platforms.
Market Dynamics
Medical device OEM procurement of solid-state cooling assemblies is compressing qualification timelines from 18 months to under 9 months as portable diagnostic equipment volumes accelerate. This demand compression is restructuring supplier-OEM relationships around thermal subsystem co-design rather than component sales.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants in instruments below 50 kW cooling capacity mandates substitution with thermoelectric alternatives across European laboratory and clinical equipment procurement.
- Bismuth telluride pellet miniaturization:Advanced doping processes now achieve 40–70°C temperature differentials across sub-10 mm² footprints, enabling spot cooling in wearable and implantable medical devices previously unreachable by conventional cooling.
- Germany's medical technology cluster:Concentrated OEM engineering activity around Freiburg and Tuttlingen generates localized demand pull for precision thermal management in spectroscopy and PCR instrumentation.
Market Restraints
- Tellurium supply concentration:Over 90 percent of refined tellurium originates as a copper refining byproduct from a limited number of smelter complexes, creating raw material vulnerability for bismuth telluride alloy production.
- Coefficient of performance ceiling:Single-stage thermoelectric modules max out at 5–8 percent efficiency versus 40–60 percent for compressor-based systems, restricting addressable applications to precision cooling below 100W thermal loads.
- FDA 21 CFR Part 820 validation burden:Active medical device quality system requirements impose documentation protocols that extend supplier qualification cycles and elevate compliance costs for thermal subsystem vendors.
Strategic Opportunities
- Flexible module substrates:Conformable thermoelectric arrays enable thermal management in curved wearable electronics and miniaturized automotive sensor housings where rigid ceramic substrates fail.
- Multi-stage cascade architectures:Stacked p-n junction configurations targeting sub-ambient precision below 0.01°C stability command premium positioning in medical imaging and laser system applications.
- Automotive LiDAR thermal stabilization:IEC 60749 reliability standards for semiconductor thermal cycling are emerging as supplier selection criteria in autonomous sensor platforms, opening new qualification pathways for module vendors.
Industry Challenges
- Thermoelectric materials engineering talent:The intersection of semiconductor physics and thermal systems design requires specialized expertise that concentrates in a small number of academic and industrial research centers.
- Multi-stage module assembly precision:Achieving thermal interface consistency across cascaded junction layers demands capital-intensive bonding and testing equipment that elevates manufacturing scale-up costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Thermoelectric Modules Market |
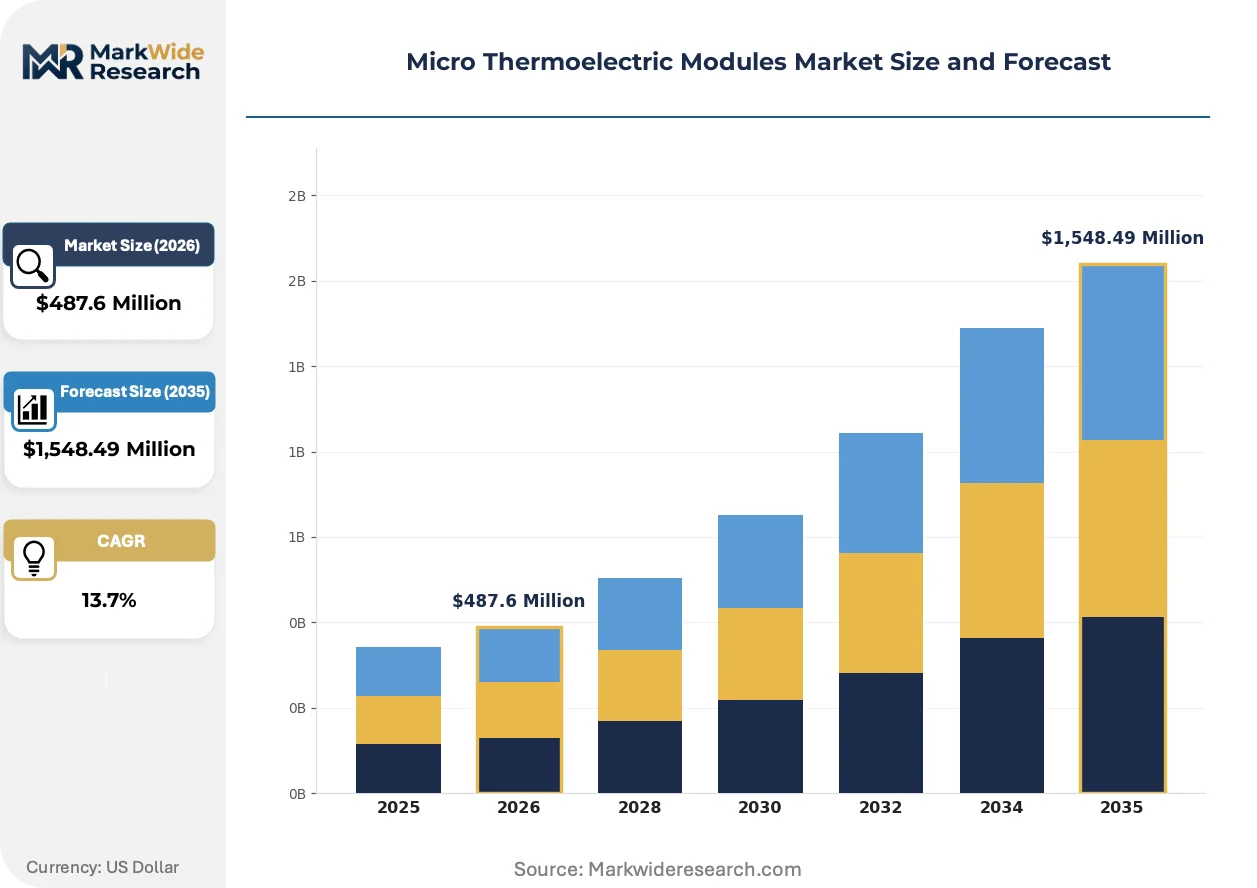
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,548.49 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-stage Modules, Multi-stage Modules, Flexible Modules, Surface-mount Modules Application: Consumer Electronics, Automotive, Medical Devices, Industrial Automation End User: OEMs, Research Institutions, Energy Harvesting Companies, Military Applications Installation: On-board, Standalone, Integrated, Modular |
| Companies Covered | CUI Devices, TEC Microsystems, KELK Ltd., Thermonamic Electronics (Jiangxi) Corp., Ltd., Guangdong Fuxin Technology Co., Ltd., Ferrotec Holdings Corporation, Laird Thermal Systems, Crystal Ltd., II-VI Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Thermoelectric Modules Market Shifts & Advancements
Solid-state cooling technology is fragmenting into application-specific configurations as end-use requirements diverge between medical precision, automotive ruggedization, and consumer miniaturization. This specialization is driving material and architectural innovation at the module level.
Thin-film thermoelectric generators fabricated via electrochemical deposition are decomposing the traditional pellet-and-ceramic substrate architecture. Medical wearable manufacturers in Switzerland and South Korea are piloting these conformable arrays for continuous glucose monitor thermal compensation. The technology is decomposing established supply relationships by enabling foundry-style production at semiconductor fabrication facilities rather than dedicated thermoelectric plants.
REACH substance restrictions on lead-containing solders are forcing thermal interface material reformulation across European-sourced modules. Module suppliers are migrating to bismuth-tin-silver alloys and transient liquid phase bonding to maintain thermal conductivity while satisfying ECHA authorization requirements. Laboratory equipment OEMs in Germany and France are now specifying RoHS-REACH dual compliance as a procurement gate, compressing qualified supplier pools.
Diagnostic equipment buyers are consolidating thermal subsystem procurement under single-source subsystem contracts rather than multi-vendor component sourcing. This concentration is displacing spot-market module purchasing in favor of multi-year thermal platform agreements with integrated design support. The shift is most pronounced in Germany's Freiburg-Tuttlingen medical device corridor, where OEMs now require suppliers to co-locate application engineering resources.
Micro Thermoelectric Modules Market Segmentation
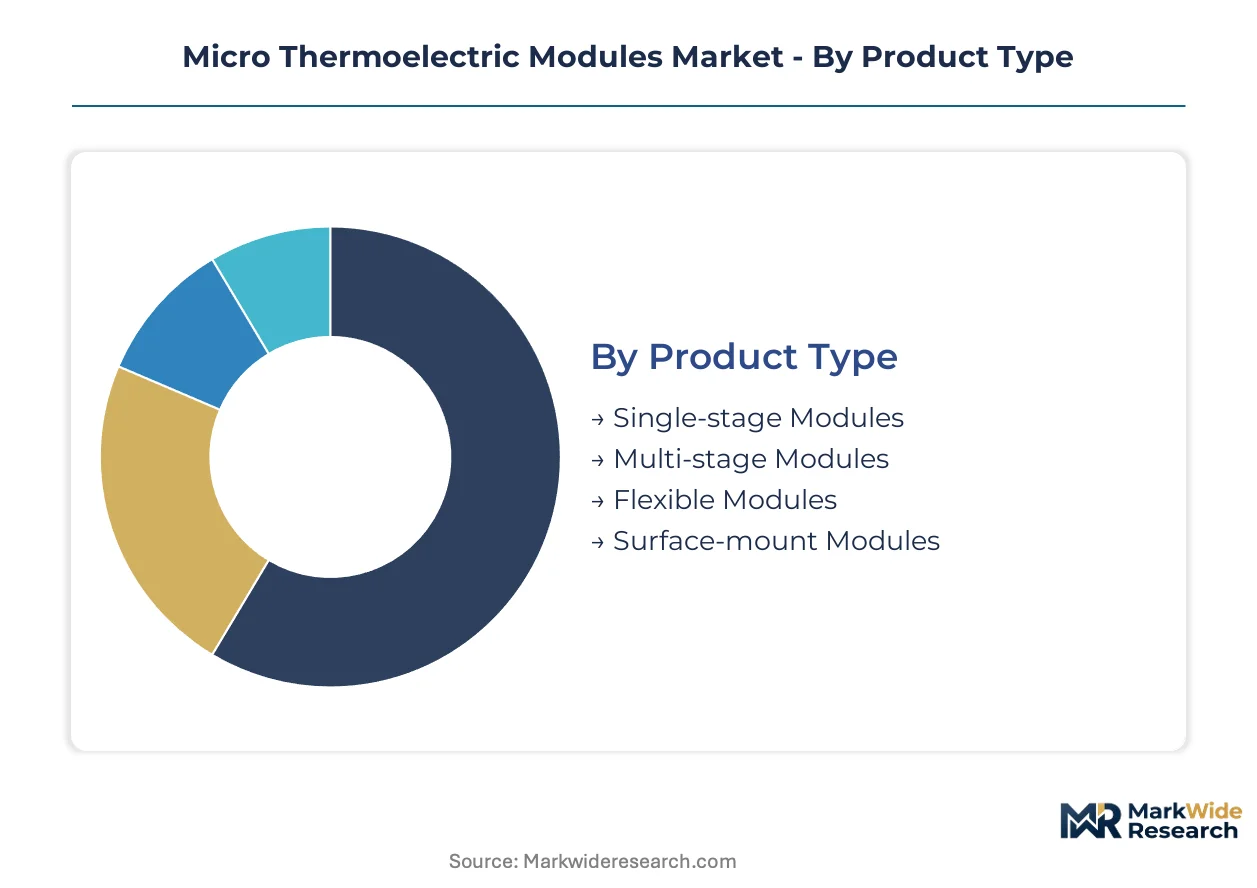
Thermoelectric module architectures diverge sharply across end-use thermal loads, with medical and automotive qualification protocols forcing distinct material and bonding specifications. Segmentation by product type, application, end user, and installation method reveals where margin pools concentrate versus where volume manufacturing scales.
Product Type:
EU F-Gas Regulation compliance timelines favor solid-state alternatives that eliminate hydrofluorocarbon refrigerants in sub-50 kW instruments, directly shaping module architecture selection.
- Single-stage Modules:These devices achieve 40–70°C temperature differentials across bismuth telluride pellet arrays on ceramic substrates. Demand concentrates in consumer electronics spot cooling and industrial sensor stabilization where moderate ΔT requirements suffice and cost sensitivity dominates procurement decisions in Germany and South Korea.
- Multi-stage Modules:Stacked p-n junction configurations deliver sub-ambient precision below 0.01°C stability through cascaded thermal interfaces. Medical imaging OEMs in Freiburg and Tuttlingen specify these for PCR instrumentation and laser system thermal management where FDA 21 CFR Part 820 validation protocols apply.
- Flexible Modules:Conformable substrates enable thermal management on curved surfaces.
- Surface-mount Modules:Pick-and-place compatible footprints serve miniaturized electronics assembly.
Single-stage modules handle the majority of throughput; flexible modules are gaining share fastest as wearable form factors proliferate.
Application:
Cost tier differentiation separates precision medical applications from price-sensitive consumer segments.
- Medical Devices:Portable diagnostic equipment procurement is compressing supplier qualification timelines from 18 months to under 9 months. OEMs in Switzerland and Germany now mandate thermal subsystem co-design agreements rather than component spot purchasing, with REACH substance restrictions on lead-containing solders forcing bismuth-tin-silver alloy migration.
- Automotive:LiDAR thermal stabilization demands IEC 60749 reliability standard compliance for semiconductor thermal cycling. Autonomous sensor platforms in Germany and Japan are embedding multi-stage modules for sub-zero operational stability where NHTSA and KBA automotive safety frameworks intersect.
- Consumer Electronics:Spot cooling for smartphones and wearables drives volume.
- Industrial Automation:Precision temperature control for process instrumentation.
Medical devices command premium positioning; automotive applications are expanding most quickly on regulatory tailwinds.
End User:
Customer type determines validation burden depth and contract structure.
- OEMs:Medical device OEMs bifurcate from consumer electronics brands through thermal subsystem consolidation under single-source contracts. German laboratory equipment buyers now require co-located application engineering resources, displacing multi-vendor component sourcing in favor of multi-year platform agreements with integrated design support.
- Research Institutions:Spectroscopy and PCR instrumentation demand in academic and national laboratory settings.
- Energy Harvesting Companies:Thin-film thermoelectric generator pilots for waste heat recovery.
- Military Applications:Ruggedized thermal management for field-deployable equipment.
OEMs dominate procurement value; research institutions are climbing the fastest on instrumentation upgrade cycles.
Installation:
Supply concentration in ceramic substrate manufacturing favors certain mounting configurations.
- Integrated:Subsystem-level thermal management embedded within medical device enclosures. German diagnostic equipment manufacturers specify these configurations to satisfy FDA 21 CFR Part 820 quality system documentation requirements through pre-validated thermal platform agreements.
- Modular:Field-replaceable thermal units for industrial maintenance cycles.
- On-board:Direct PCB attachment for space-constrained electronics.
- Standalone:External cooling assemblies for benchtop instrumentation.
Integrated installations capture the steepest expansion trajectory; standalone units retain legacy instrument retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in precision medical device exports, while Shenzhen's Yantian Port anchors Chinese electronics manufacturing for consumer thermoelectric applications. These logistics arteries shape regional competitive positioning across the micro thermoelectric modules supply chain.
Germany
Freiburg and Tuttlingen host Europe's densest medical technology cluster, with OEMs procuring multi-stage modules for PCR instrumentation. The EU F-Gas Regulation mandates hydrofluorocarbon phaseout in sub-50 kW instruments, accelerating thermoelectric substitution in laboratory equipment. REACH substance restrictions on lead-containing solders force bismuth-tin-silver alloy migration across Baden-Württemberg's supplier base.
United States
FDA 21 CFR Part 820 quality system requirements compress supplier qualification timelines to under nine months for portable diagnostic equipment. The EPA's SNAP program restrictions on high-GWP refrigerants expand addressable market for solid-state cooling in clinical instruments. Boston's Route 128 corridor concentrates wearable medical device development driving flexible module demand.
China
Guangdong Province's electronics manufacturing base generates volume demand for single-stage modules in consumer spot cooling applications. MIIT's dual carbon goals incentivize energy-efficient thermal management in industrial automation. Shenzhen's Nanshan district anchors thin-film thermoelectric pilot production for smartphone thermal compensation.
Japan
METI's semiconductor equipment subsidies support precision thermal management in lithography systems. Automotive LiDAR thermal stabilization demands IEC 60749 reliability compliance for autonomous sensor platforms. Nagoya's Chubu region concentrates automotive electronics engineering requiring sub-zero operational stability modules.
South Korea
MFDS medical device approval pathways shape thermal validation protocols for export-oriented manufacturers. Seoul's Pangyo Techno Valley hosts wearable health monitor developers piloting conformable thermoelectric arrays. Samsung and LG supply chain proximity drives integrated thermal subsystem procurement consolidation.
Micro Thermoelectric Modules Market Competitive Landscape
Concentration sits with diversified materials conglomerates and specialized thermal subsystem designers. The vendor base spans three tiers: integrated thermal platform providers commanding premium positioning in medical applications, component-scale manufacturers serving cost-sensitive consumer electronics, and emerging thin-film specialists disrupting traditional pellet-and-ceramic architectures. Strategic moves center on thermal subsystem co-design partnerships with OEMs and backward integration into bismuth telluride material supply.
Among Japan- and China-based fabricators, Ferrotec Holdings Corporation and Thermonamic Electronics (Jiangxi) Corp., Ltd. exemplify materials-anchored competitive positioning. Laird Thermal Systems occupies a position within the integrated thermal subsystem tier alongside TEC Microsystems, which represents specialized multi-stage module architecture. These three companies anchor distinct competitive vectors: materials control, subsystem integration, and miniaturized cascade design.
| Leading Market Players |
|---|
| CUI Devices |
| TEC Microsystems |
| KELK Ltd. |
| Thermonamic Electronics (Jiangxi) Corp., Ltd. |
| Guangdong Fuxin Technology Co., Ltd. |
| Ferrotec Holdings Corporation |
| Laird Thermal Systems |
| Crystal Ltd. |
| II-VI Incorporated |
| Others |
Supply & Pricing Matrix
FDA 21 CFR Part 820 quality system requirements simultaneously gate supplier qualification and stratify price tiers by validation burden depth. Medical device OEMs now demand pre-validated thermal platforms, compressing qualified supplier pools and amplifying margin capture for certified vendors against uncertified competitors.
Pricing Analysis
Volume-discount tiering separates multi-year thermal platform agreements from spot-market module purchasing. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and thermal stability precision. Cost compression in consumer-grade single-stage modules intensifies because Chinese electronics manufacturers consolidate procurement under annual volume commitments. Research institutions exhibit highest price sensitivity; medical imaging OEMs show least sensitivity due to FDA-mandated validation documentation requirements.
Supply Chain Analysis
Strategic stockpiling of refined tellurium concentrates in Japan and Germany contrasts with just-in-time ceramic substrate procurement in China. Bismuth telluride pellet production draws from copper smelter byproduct streams concentrated in China, Japan, and Canada. Single-source vulnerability sits with tellurium refining capacity controlled by a limited smelter complex network. Distribution runs through integrated thermal subsystem contracts rather than component spot markets for medical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Application-specific thermal requirements fragment procurement into discrete niches. Portable diagnostic equipment volumes accelerate qualification timeline compression, creating entry points for specialized subsystem designers.
For Market Incumbents: Consolidate backward integration into bismuth telluride material supply to secure tellurium access against copper smelter concentration risk. Expand captive production of multi-stage cascade architectures in Germany's Freiburg-Tuttlingen corridor to defend against thin-film thermoelectric disruptors piloting foundry-style semiconductor fabrication.
For New Entrants and Emerging Players: Thermal subsystem co-design services represent a service-layer gap where incumbents under-serve mid-tier diagnostic OEMs. Target Switzerland's wearable health monitor developers with conformable flexible module prototypes. Pursue foundry partnerships with existing semiconductor fabrication facilities to bypass capital-intensive pellet-and-ceramic substrate manufacturing.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across thin-film thermoelectric pilot production lines. Long-term viability favors acquisition targets with validated FDA 21 CFR Part 820 quality systems and existing thermal platform agreements with German laboratory equipment OEMs. Watch IEC 60749 reliability standard adoption rates in automotive LiDAR procurement as inflection indicator for multi-stage module demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tellurium Supply | Captive bismuth telluride production secures raw material access against copper smelter concentration. |
| Thermal Subsystem Co-Design Partnership | Multi-year platform agreements with Freiburg-Tuttlingen OEMs displace spot-market component purchasing. |
| Thin-Film Foundry Production Scale-Up | Electrochemical deposition at semiconductor fabs decomposes traditional pellet-and-ceramic architecture. |
| Flexible Module Substrate Development | Conformable arrays enable thermal management in curved wearables and automotive sensor housings. |
| Multi-Stage Cascade Architecture Investment | Stacked p-n junction configurations command premium positioning in PCR instrumentation and laser systems. |
Research Methodology
A standing panel of biomedical engineers, thermal subsystem procurement managers at medical device OEMs, GPO contracts managers, and semiconductor fabrication facility planners provided ongoing calibration. Primary interviews combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation, IEC standard revision records, and customs trade data for bismuth telluride alloys. Bottom-up module shipment tracking and top-down thermal subsystem revenue triangulation anchored volume estimates.
Consistency checks validated outputs against external benchmarks including MIIT industrial automation equipment statistics, METI semiconductor equipment production indices, and MFDS medical device approval pathway disclosures. Segmentation modeling spanned product architecture, application thermal load, end-user validation burden, and installation integration depth across the projection horizon. CAGRs derived from regression analysis of historical qualification timeline compression and substitution elasticity against compressor-based cooling systems.
Forecasts assume regulatory continuity in FDA 21 CFR Part 820, EU F-Gas Regulation phasedown schedules, and REACH substance restriction timelines; material policy shifts would require re-modeling. Revision becomes warranted when tellurium spot price volatility or IEC 60749 standard adoption rates in automotive procurement cross thresholds that alter substitution economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Automotive Mosfets Market
Semiconductor Devices
Advanced HDI PCB Market
Semiconductor Devices
Gallium Oxide Transistor Market
Semiconductor Devices
Underfill Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Superconductor Wire Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
5G Automotive Grade Product Market
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
Rad-Hard Mosfets Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
China Power Transistor Market
Semiconductor Devices
Americas Semiconductor Diode Market
Semiconductor Devices
Americas Microcontroller (MCU) Market
Semiconductor Devices
Polymer Core Solder Ball Market
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market