
 China MLCC Market | 2026-2036
China MLCC Market Size, Share, and Industry Trends Forecast 2026-2036
China MLCC Market Insights
Market Context
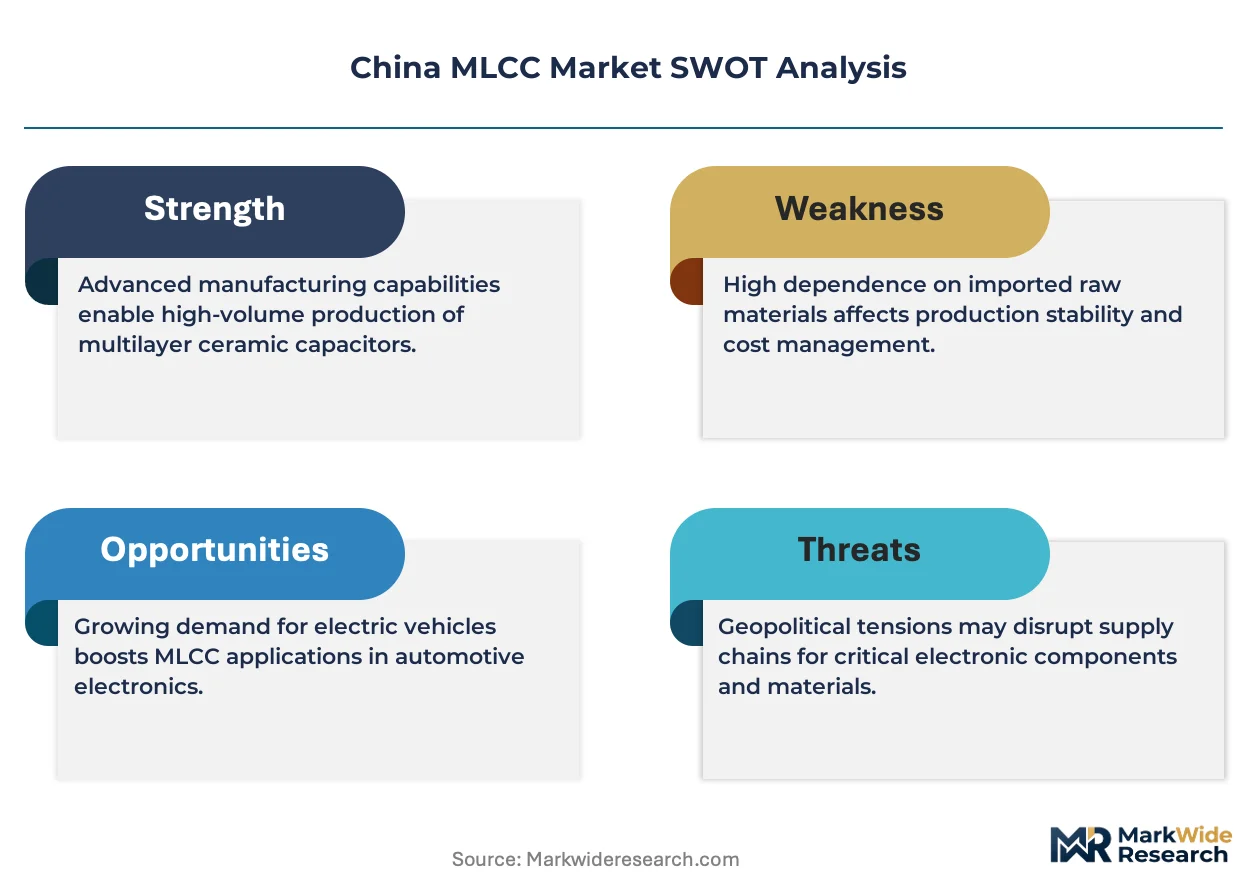
Nickel-based inner electrodes is rebalancing cost structures across high-capacitance MLCC grades. Guangdong Fenghua Advanced Technology leverages integrated ferrite and ceramic powder operations to control raw material costs. Samsung Electro-Mechanics anchors its China position through dedicated automotive-grade production lines in Tianjin. Chaozhou Three-Circle Group specializes in ultra-high-voltage MLCCs for industrial inverter applications.
Technical Definition and Segment Structure
Multi-layer ceramic capacitors stack alternating layers of dielectric ceramic and metal electrodes to store charge in compact surface-mount packages, with capacitance values spanning picofarads to hundreds of microfarads for decoupling, filtering, and energy storage in electronic circuits. High-capacitance MLCCs dominate value pools as automotive electrification and 5G base stations drive demand for bulk capacitance in tight form factors. Passive-type MLCCs lead volume shipments across consumer electronics and telecommunications end users, while active-integrated variants capture premium positioning in smart power modules.
Regulatory Environment and Outlook
MIIT's GB standards for electronic component reliability and SAMR's quality certification requirements shape product entry and domestic procurement preferences for China-based MLCC suppliers. MEE enforcement of dual carbon goals pressures manufacturers to reduce sintering energy intensity and transition to cleaner electrode metallization processes. Stakeholders must monitor how evolving national semiconductor self-sufficiency targets redirect capacitor procurement toward qualified domestic vendors versus import-dependent supply relationships.
Market Dynamics
China's dual carbon goals from MEE are compressing sintering energy intensity requirements while automotive electrification pulls high-capacitance grades into volume production, creating simultaneous cost and capacity pressures across Guangdong manufacturing clusters.
Growth Catalysts
- Automotive Electrification:Electric vehicle powertrain systems demand bulk capacitance in compact surface-mount packages, pulling high-voltage MLCC grades into dedicated automotive production lines.
- GB Standards Compliance:MIIT reliability mandates for electronic components redirect domestic procurement toward qualified China-based suppliers versus import-dependent relationships.
- 5G Infrastructure Deployment:Base station rollouts across Guangdong province concentrate demand for microwave-grade MLCCs with tight temperature coefficients.
Market Restraints
- Nickel Electrode Cost Volatility:Base metal price swings for inner electrode materials compress margins across high-capacitance grades where nickel content dominates stack construction.
- Guangdong Supply Concentration:Manufacturing cluster dependency on Pearl River Delta ceramic powder and ferrite operations creates geographic vulnerability to regional energy rationing or logistics disruption.
- Barium Titanate Technical Ceiling:Dielectric constant limitations in Class 2 ceramic formulations constrain volumetric efficiency gains for automotive-grade bulk capacitance requirements.
Strategic Opportunities
- Western China Expansion:Underpenetrated production capacity in Sichuan and Shaanxi provinces offers lower energy costs and proximity to inland automotive assembly plants.
- Active-Integrated Modules:Convergence of MLCC dielectric stacks with smart power semiconductor packaging creates premium positioning in industrial inverter applications.
- Dual Carbon Incentives:MEE clean metallization transition subsidies reward early adopters of low-temperature co-fired ceramic processes with reduced sintering energy profiles.
Industry Challenges
- Thin-Layer Deposition Expertise Gap:Talent scarcity in sub-micron dielectric tape casting and precision electrode printing constrains yield ramp for automotive-grade high-capacitance stacks.
- Automotive Certification Timelines:AEC-Q200 qualification cycles extending 18-24 months delay revenue recognition for new high-reliability grade introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China MLCC Market |
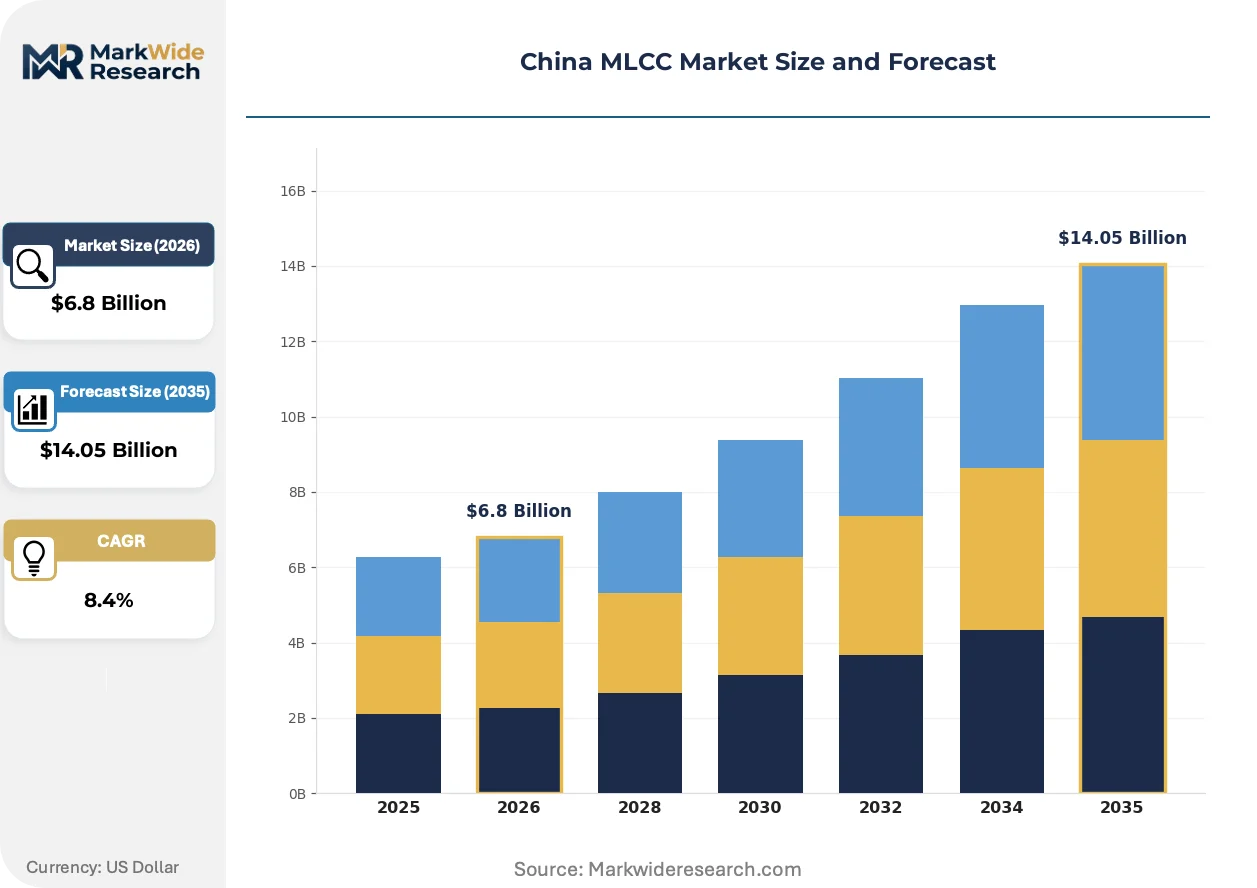
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Multi-layer, Single-layer, Active, Passive End User: Telecommunications, Consumer Electronics, Automotive, Industrial Electronics Capacitance: Low, Medium, High, Ultra-high Form Factor: Surface Mount, Through Hole, Chip, Radial |
| Companies Covered | Guangdong Fenghua Advanced Technology, Chaozhou Three-Circle Group, Eyang Technology, Murata Manufacturing, Samsung Electro-Mechanics, TDK, Yageo, Taiyo Yuden, Walsin Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China MLCC Market Trends and Innovations
Material science breakthroughs and regulatory energy mandates are compressing traditional process boundaries while reshaping procurement specifications across automotive and telecommunications verticals.
High-capacitance Class 2 ceramic formulations with nickel inner electrodes are unifying cost-performance tradeoffs that previously forced buyers to choose between tantalum electrolytics for density or aluminum polymer for price. Automotive Tier 1 suppliers are adopting these grades at accelerated qualification paces for onboard charger modules. The technology is unifying bulk capacitance supply chains previously split between ceramic and electrolytic technologies.
MEE enforcement of dual carbon goals is tightening sintering furnace energy intensity standards and mandating transition timelines for cleaner electrode metallization chemistries. Manufacturers face capital reallocation toward hydrogen-fired kilns or electric sintering systems. Guangdong-based suppliers with integrated ferrite operations bear disproportionate compliance burdens due to energy-intensive calcination stages.
Telecommunications OEMs are consolidating MLCC procurement specifications around AEC-Q200 qualified grades even for non-automotive applications, compressing supplier qualification overhead but raising entry barriers for non-automotive-certified vendors. This specification convergence is displacing traditional consumer-grade procurement tiers. The pattern is most visible in 5G base station deployments across coastal provinces where equipment reliability targets match automotive severity levels.
China MLCC Market Segmentation
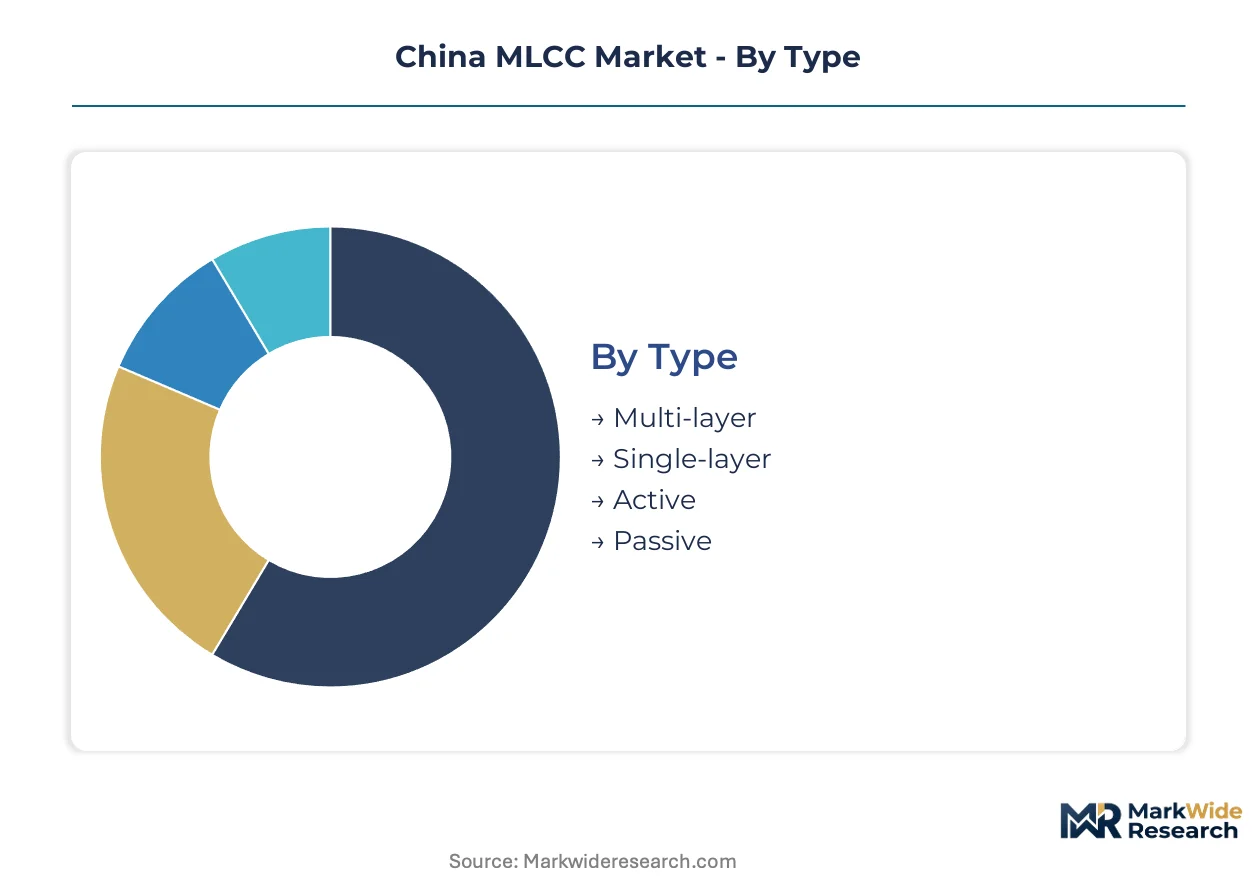
MLCC segmentation in China reflects divergent technical requirements across standalone decoupling applications versus embedded power module integration. Procurement patterns split sharply between cost-optimized consumer grades and reliability-certified automotive tiers.
Type:
Integration depth varies dramatically, with passive configurations dominating standalone board-mount applications while active-integrated variants embed directly into semiconductor power modules.
- Multi-layer:Stacks of alternating dielectric ceramic and nickel electrode layers achieve capacitance density exceeding single-layer alternatives by orders of magnitude. Guangdong automotive clusters pull these grades into dedicated EV powertrain production lines where volumetric efficiency commands premium positioning.
- Passive:Standalone surface-mount devices without semiconductor integration serve decoupling and filtering functions across telecommunications base stations and consumer electronics. MIIT GB standards compliance redirects domestic procurement toward China-qualified suppliers versus import-dependent relationships for these high-volume grades.
- Single-layer:Basic ceramic disc construction limits capacitance range but retains cost advantage in legacy industrial equipment.
- Active:Embedded dielectric stacks within smart power modules capture premium positioning in industrial inverter applications.
Passive configurations lead volumes today; active-integrated variants are gaining share fastest.
End User:
Cost tier stratification separates military-grade reliability premiums from consumer electronics price sensitivity, with automotive electrification compressing traditional tier boundaries.
- Automotive:AEC-Q200 qualification mandates 18-24 month certification cycles for high-reliability grades serving onboard charger modules. Tianjin production lines anchor Samsung Electro-Mechanics' China position as EV powertrain systems accelerate ceramic capacitor adoption.
- Telecommunications:5G base station rollouts across Guangdong province concentrate demand for microwave-grade MLCCs with tight temperature coefficients. Equipment reliability targets now match automotive severity levels, displacing traditional consumer-grade procurement tiers.
- Consumer Electronics:Smartphone and wearable applications drive volume shipments of compact surface-mount packages.
- Industrial Electronics:Ultra-high-voltage grades from Chaozhou Three-Circle Group specialize in inverter applications.
Telecommunications leads volumes today; automotive is climbing the fastest.
Capacitance:
Application maturity separates established low-capacitance filtering functions from emerging bulk energy storage requirements in electrified powertrains.
- High:Class 2 ceramic formulations with nickel inner electrodes unify cost-performance tradeoffs previously forcing buyers toward tantalum electrolytics. Automotive Tier 1 suppliers adopt these grades at accelerated qualification paces for onboard charger modules.
- Ultra-high:Dielectric constant limitations in barium titanate formulations constrain volumetric efficiency gains, creating technical ceiling pressure for automotive-grade bulk capacitance requirements.
- Low:Picofarad-range devices dominate RF signal conditioning in telecommunications infrastructure.
- Medium:Mid-range capacitance serves general-purpose decoupling across industrial control systems.
Medium capacitance leads volumes today; high capacitance is expanding most quickly.
Form Factor:
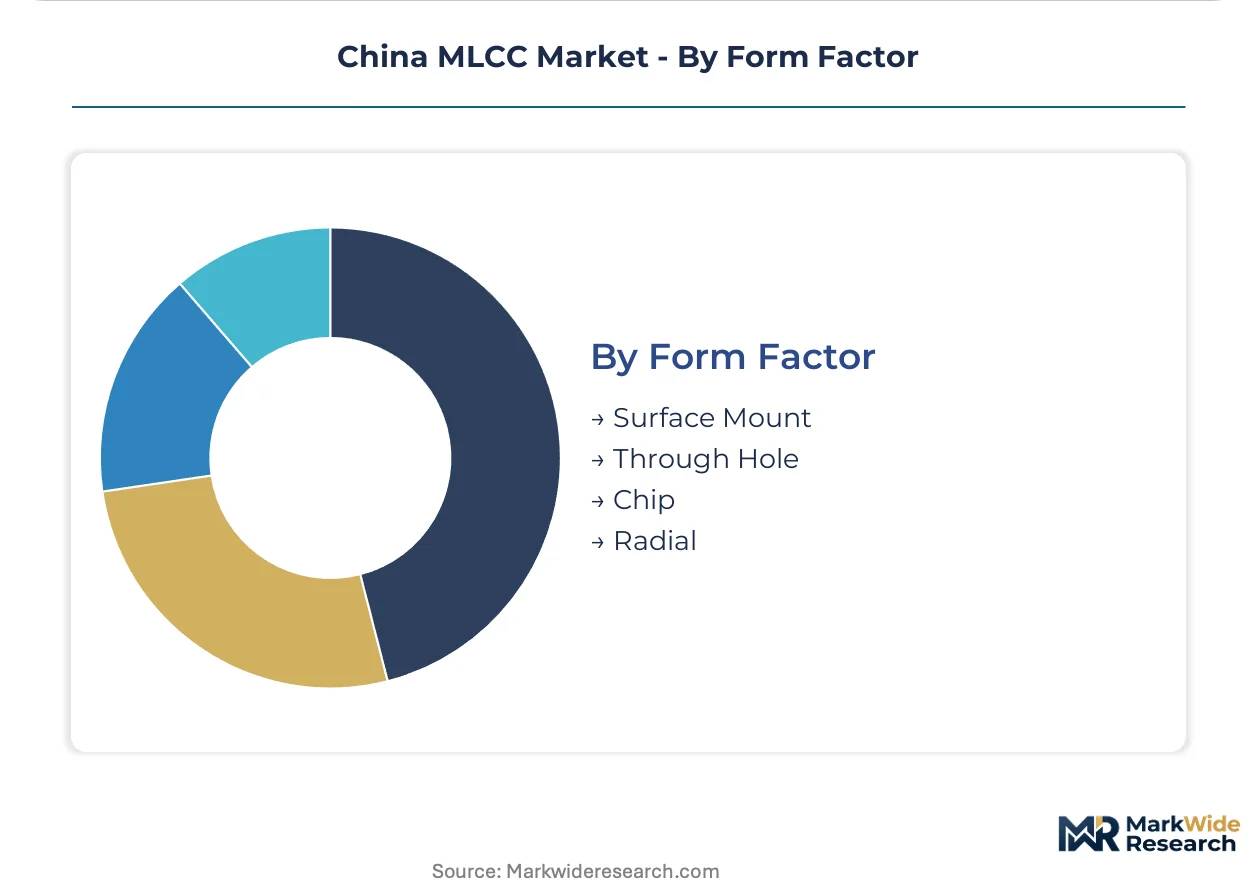
Supply concentration in surface-mount packaging reflects Guangdong manufacturing cluster specialization, while through-hole formats serve legacy equipment replacement cycles.
- Surface Mount:Compact rectangular packages dominate automotive and telecommunications applications where board space constraints intersect with high-reliability requirements. Guangdong Fenghua Advanced Technology leverages integrated ferrite and ceramic powder operations to control raw material costs for these high-volume formats.
- Chip:Miniaturized case sizes below 0402 metric enable smartphone and wearable integration.
- Through Hole:Radial leaded construction persists in industrial equipment with extended service life requirements.
- Radial:Cylindrical leaded formats serve power supply filtering in legacy infrastructure.
Surface mount leads volumes today; chip-scale formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta anchors China's MLCC production capacity, with Guangdong province manufacturing clusters serving domestic automotive and telecommunications OEMs under tightening MEE dual carbon enforcement.
Guangdong Province
Electric vehicle powertrain systems and 5G base station rollouts concentrate demand for high-capacitance and microwave-grade MLCCs. MEE energy-efficiency mandates compress sintering intensity requirements across ceramic powder operations. Shenzhen and Dongguan manufacturing corridors host integrated ferrite and electrode material facilities serving Samsung Electro-Mechanics and domestic suppliers.
Tianjin Municipality
Automotive-grade MLCC production lines anchor foreign-invested capacity serving northern China EV assembly plants. MIIT GB standards compliance redirects procurement toward qualified domestic suppliers versus import-dependent relationships. Binhai New Area industrial zones concentrate AEC-Q200 certified production for onboard charger modules.
Jiangsu Province
Yangtze River Delta electronics corridors pull MLCC demand from semiconductor packaging and industrial control system manufacturers. SAMR quality certification requirements shape product entry for suppliers targeting telecommunications infrastructure. Suzhou and Wuxi precision component clusters specialize in sub-micron dielectric tape casting for high-reliability grades.
Sichuan Province
Underpenetrated production capacity offers lower energy costs and proximity to inland automotive assembly plants. Dual carbon incentives reward early adopters of low-temperature co-fired ceramic processes with reduced sintering profiles. Chengdu-Chongqing economic circle development programs attract capacity relocation from coastal energy-constrained zones.
Zhejiang Province
Hangzhou and Ningbo electronics manufacturing bases consume medium-capacitance grades for consumer electronics and general-purpose industrial applications. Provincial industrial policies support ceramic powder localization to reduce barium titanate import dependency. Ningbo material science parks host dielectric formulation R&D aligned with automotive electrification requirements.
China MLCC Market Competitive Landscape
Global majors compete with regional champions across certification tiers and end-use specializations, creating a bifurcated structure where Japanese and Korean firms anchor premium automotive grades while domestic Chinese suppliers capture volume telecommunications and consumer electronics contracts. Market concentration splits between AEC-Q200 qualified premium tiers and cost-optimized standard grades. Three archetypes dominate: integrated material-to-component manufacturers controlling ceramic powder supply, dedicated automotive-grade specialists with extended qualification capabilities, and scale-driven consumer electronics suppliers. Competitive dynamics center on backward integration into electrode metallization processes and geographic capacity relocation to western provinces under energy cost pressures.
Among domestic integrated manufacturers, Guangdong Fenghua Advanced Technology exemplifies the material-captive archetype through in-house ferrite and ceramic powder operations. Chaozhou Three-Circle Group occupies a position within ultra-high-voltage specialists serving industrial inverter applications. Samsung Electro-Mechanics represents the foreign-invested premium tier with dedicated automotive production lines in northern China. These three anchors illustrate the competitive spectrum from domestic vertical integration to foreign technology licensing.
| Leading Market Players |
|---|
| Guangdong Fenghua Advanced Technology |
| Chaozhou Three-Circle Group |
| Eyang Technology |
| Murata Manufacturing |
| Samsung Electro-Mechanics |
| TDK |
| Yageo |
| Taiyo Yuden |
| Walsin Technology |
| Others |
Pricing and Supply Chain Analysis
Backward integration into ceramic powder and electrode metallization operations anchors Guangdong Fenghua Advanced Technology's cost position while compressing pricing power for non-integrated competitors serving MIIT GB-standard procurement channels. This captive supply structure simultaneously insulates margins against nickel price volatility and creates tiered pricing separation between automotive-certified and consumer-grade MLCC shipments.
Pricing Analysis
Input-cost pass-through from nickel electrode metallization and barium titanate ceramic formulations dominates pricing structure across high-capacitance grades. Price differentiation rests on AEC-Q200 certification tier and volume scale, with automotive OEMs absorbing reliability premiums while consumer electronics buyers squeeze standard-grade margins. Pricing pressure stems from MEE dual carbon compliance costs accelerating through sintering-intensive production lines. Consumer electronics OEMs exhibit highest price sensitivity; automotive Tier 1 suppliers prioritize qualification stability over unit cost.
Supply Chain Analysis
MIIT GB standards and SAMR quality certification requirements reshape sourcing toward qualified domestic suppliers versus import-dependent relationships. Geographic supply concentration centers on China, Japan, and South Korea, with raw material dependencies spanning nickel powder from Russia and Australia, barium titanate from domestic Sichuan deposits, and palladium for specialty electrodes. Single-source vulnerability concentrates in sub-micron dielectric tape casting equipment. Distribution runs through direct OEM contracts for automotive grades and electronics distributors for consumer volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in high-capacitance automotive grades where AEC-Q200 certification barriers protect pricing power against nickel cost volatility.
For Market Incumbents: Anchor Tianjin and Guangdong production capacity against western China relocation incentives by securing MEE clean metallization transition subsidies ahead of hydrogen-fired kiln mandates. Defend position by deepening captive ceramic powder supply and accelerating AEC-Q200 qualification pipelines for onboard charger modules before emerging domestic competitors close certification gaps. For New Entrants and Emerging Players: MEE dual carbon goals in Sichuan and Shaanxi provinces open a window for greenfield low-temperature co-fired ceramic capacity with reduced sintering energy profiles. Target underpenetrated western China automotive assembly corridors with medium-capacitance grades for industrial control systems, bypassing Guangdong certification bottlenecks through SAMR quality certification fast-tracks for non-automotive applications. For Investors and Strategic Acquirers: Consolidation pressure builds where thin-layer deposition expertise gaps constrain yield ramp for automotive-grade high-capacitance stacks. Long-term viability favors integrated material-to-component manufacturers with captive ferrite operations and established MIIT GB standards compliance. Watch AEC-Q200 qualification cycle compression as inflection signal for premium tier accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder | Guangdong Fenghua's captive barium titanate operations insulate margins against import dependency. |
| Automotive Certification Acceleration | Samsung Electro-Mechanics' Tianjin lines compress AEC-Q200 timelines for EV powertrain modules. |
| Western China Capacity Relocation | Sichuan's lower energy costs attract production from MEE-constrained Pearl River Delta clusters. |
| Low-Temperature Co-Fired Ceramic Transition | MEE clean metallization subsidies reward early hydrogen-fired kiln adopters with compliance advantage. |
| Active-Integrated Module Development | Embedded dielectric stacks in smart power modules capture premium industrial inverter positioning. |
Research Methodology
Coverage spans Guangdong, Tianjin, Jiangsu, Sichuan, and Zhejiang provinces, with primary inputs from each manufacturing cluster triangulated against secondary validation. Interviews with MLCC plant managers, automotive Tier 1 procurement leads, telecommunications equipment OEMs, and SAMR certification officers combined with MIIT GB standards documentation, customs trade data, and AEC-Q200 qualification databases. Bottom-up capacity assessments and top-down end-use demand modeling cross-validated segment outputs.
Rate-of-change decomposition separates volume growth from value mix shifts across the projection horizon. Segmentation dimensions include integration depth, end-user certification tier, capacitance grade, and form factor scale. CAGRs derived from production capacity buildout schedules, EV powertrain content per vehicle trajectories, and 5G base station deployment pipelines. Nickel price scenario modeling and MEE energy-intensity compliance cost curves informed sensitivity bounds.
Revisions become necessary when MEE enforcement timelines accelerate, automotive qualification standards tighten unilaterally, or western China infrastructure buildouts lag relocation incentives. Forecasts reflect assumptions about ceramic powder localization rates and clean metallization technology maturation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market
Semiconductor Devices
Gallium Oxide Transistor Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
T-Con Board Market
Semiconductor Devices
Global Bipolar Power Transistor Market
Semiconductor Devices
Silicon-Based Anode Market
Semiconductor Devices
Power Transistor Market
Semiconductor Devices
Pcie Switches Market
Semiconductor Devices
Smart Gate Driver Market
Semiconductor Devices
Middle East and Africa Silicon Carbide Wafers Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market
Semiconductor Devices
Americas Semiconductor Diode Market
Semiconductor Devices
Semiconductor Memory IP Market
Semiconductor Devices
Digital Transistor Market