
 Home Appliance MCU Market | 2026-2036
Home Appliance MCU Market Size, Share, and Industry Trends Forecast 2026-2036
Home Appliance MCU Market Insights
Embedded firmware engineering talent scarcity is unwinding production timelines for smart appliance programs across Asia. Renesas Electronics Corporation leverages its RX and RA families to dominate motor-control applications in washing machines and air conditioners. NXP Semiconductors sustains design-win momentum through automotive-grade process migration into home appliance safety systems. STMicroelectronics anchors its position with integrated touch-sensing and motor-control peripherals that reduce BOM counts for OEMs.
A home appliance microcontroller unit is a compact integrated circuit that embeds a processor core, volatile and non-volatile memory, and programmable input-output peripherals on a single die, typically operating at clock speeds from 16 MHz to 480 MHz with flash densities spanning 32 KB to 2 MB to execute real-time control algorithms in refrigerators, HVAC systems, and laundry equipment. Microcontrollers remain the dominant product category, absorbing the majority of unit volume as appliance OEMs prioritize deterministic motor control and sensor interfacing over digital signal processing. Connectivity-enabled MCUs are expanding fastest as Wi-Fi and Bluetooth integration shifts from premium to mid-tier washing machines and dishwashers, while mixed-signal microcontrollers capture margin pools in precision temperature and humidity sensing nodes.
The EU Ecodesign Directive and REACH constrain material selection and standby power budgets for appliances sold in Europe, while the EPA ENERGY STAR program shapes efficiency benchmarks in the United States. China's GB standards and MIIT circular economy mandates enforce domestic recyclability and power-consumption thresholds that influence MCU specification sheets for export-bound manufacturers. Stakeholders must weigh the cost of integrating multi-protocol wireless stacks against the risk of fragmented smart-home ecosystem compatibility.
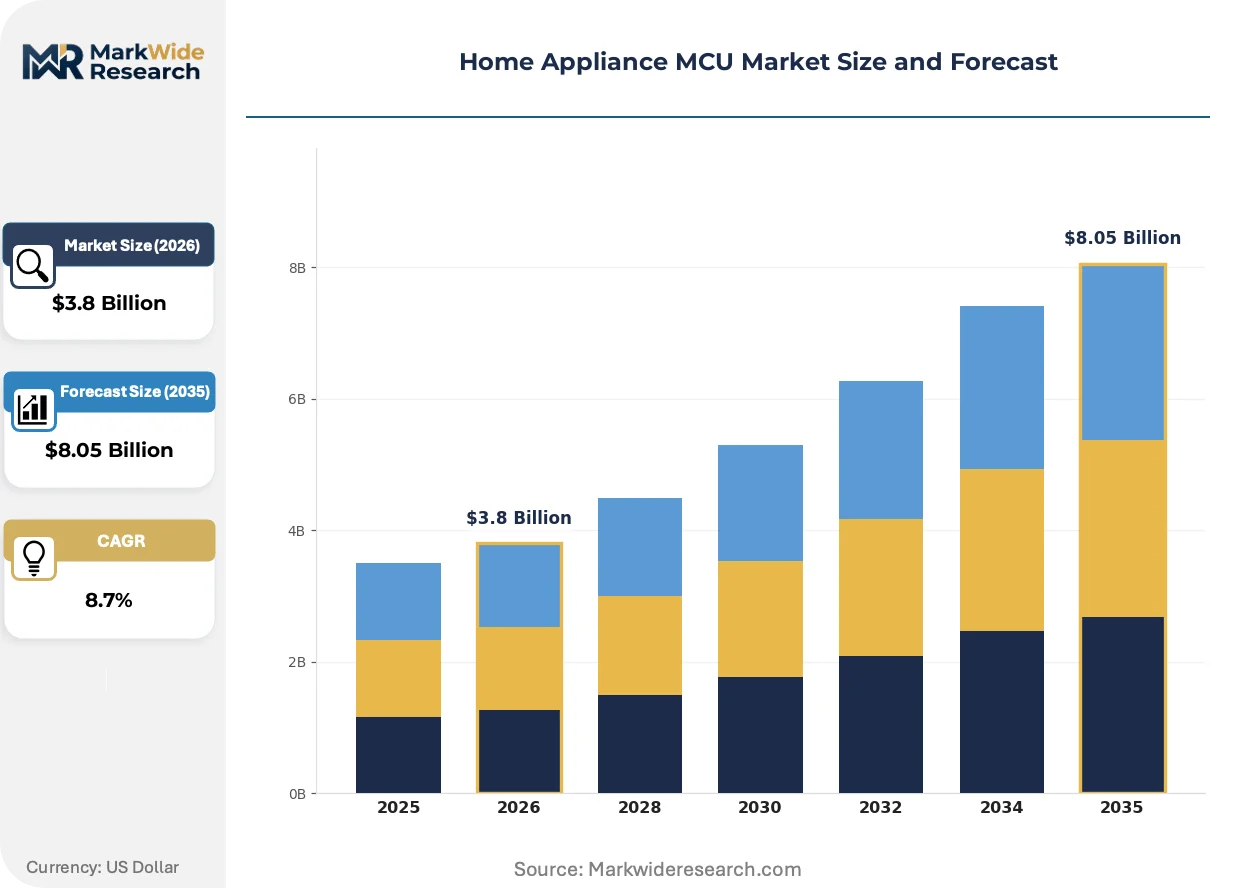
Market Dynamics
Connectivity integration is compressing BOM consolidation timelines as appliance OEMs race to embed Wi-Fi and Bluetooth stacks before the EU Ecodesign Directive's standby power limits tighten in 2027.
Growth Catalysts
- EU Ecodesign Directive:Tightening standby power limits for household equipment are forcing MCU vendors to develop sub-100-mW sleep modes, creating upgrade cycles across refrigerator and dishwasher platforms.
- Guangdong and Shandong clusters:Domestic white-goods production concentration in these Chinese provinces generates localized demand for 32-bit motor-control MCUs with integrated touch-sensing peripherals.
- Wi-Fi and Bluetooth integration:Wireless protocol migration from premium to mid-tier washing machines and dishwashers is expanding addressable unit volumes for connectivity-enabled MCUs.
Market Restraints
- Embedded firmware engineering scarcity:Talent shortages across Asia are unwinding production timelines for smart appliance programs, extending time-to-revenue for OEMs by 6-12 months.
- Silicon foundry concentration:Advanced node capacity constraints at Taiwan-based pure-play foundries are creating allocation bottlenecks for automotive-grade MCUs migrating into home appliance safety systems.
- Multi-protocol wireless cost:The expense of certifying and integrating Wi-Fi, Bluetooth, and emerging Matter stacks is compressing margins on sub-$5 MCU SKUs targeted at mass-market appliances.
Strategic Opportunities
- India's PLI scheme for white goods:Production-linked incentives for air conditioner and LED manufacturing are creating captive demand for motor-control MCUs with integrated power factor correction.
- Matter protocol convergence:The unification of smart home interoperability standards is collapsing fragmentation risk, enabling single-SKU wireless MCU designs to serve multiple ecosystem requirements.
- Precision sensing nodes:Mixed-signal MCUs capturing temperature, humidity, and vibration data are penetrating HVAC and refrigeration compressors, opening margin pools beyond basic motor control.
Industry Challenges
- REACH material compliance:The EU's substance restrictions on lead and halogenated flame retardants are forcing MCU packaging redesigns, extending qualification cycles by 8-10 months.
- Legacy 8-bit codebase migration:Appliance OEMs maintaining proprietary firmware stacks on discontinued architectures face porting costs that erode the economic case for platform upgrades.
- Functional safety certification:IEC 60730 Class B compliance for automatic electrical controls requires redundant clock and voltage monitoring, adding die area and test complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Appliance MCU Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Digital Signal Processors, Mixed-Signal Microcontrollers, Application-Specific Integrated Circuits Feature: Energy Efficiency, Connectivity, Processing Speed, Integration Capabilities End User: Manufacturers, OEMs, Retailers, Aftermarket, Repair Services Technology: Bluetooth, Wi-Fi, Zigbee, NFC |
| Companies Covered | Renesas Electronics Corporation, NXP Semiconductors, STMicroelectronics, Microchip Technology, Infineon Technologies, Texas Instruments, ON Semiconductor, Silicon Laboratories, Espressif Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Appliance MCU Market Trends and Innovations
Real-time control architectures are fragmenting across deterministic motor control and connectivity-heavy application processors, with appliance OEMs reassessing single-chip versus dual-MCU partitioning strategies.
Edge AI inference is bifurcating appliance MCU roadmaps. Predictive maintenance algorithms for compressor bearing wear and refrigerant leak detection demand vector DSP extensions and 512 KB+ SRAM pools. Premium refrigerator OEMs in South Korea and Japan are adopting these cores for localized anomaly detection. The technology is compressing cloud dependency for time-critical safety alerts while expanding software licensing revenue for MCU vendors.
REACH substance restrictions and the EU Green Deal's circular economy mandates are reshaping semiconductor packaging. Halogen-free mold compounds and lead-free solder ball arrays are becoming baseline requirements for MCUs exported to Europe. Chinese appliance manufacturers serving EU markets are now specifying green package qualifications at the RFQ stage, forcing die-level redesigns for legacy products.
Appliance OEM procurement is consolidating vendor relationships to reduce qualification overhead. Tier-one white-goods manufacturers in China and Mexico are shrinking approved MCU supplier lists from 6-8 vendors to 3-4 strategic partners. This concentration is most visible in washing machine inverter drives, where multi-year volume commitments are replacing spot-buying for commodity 32-bit MCUs.
Home Appliance MCU Market Segmentation
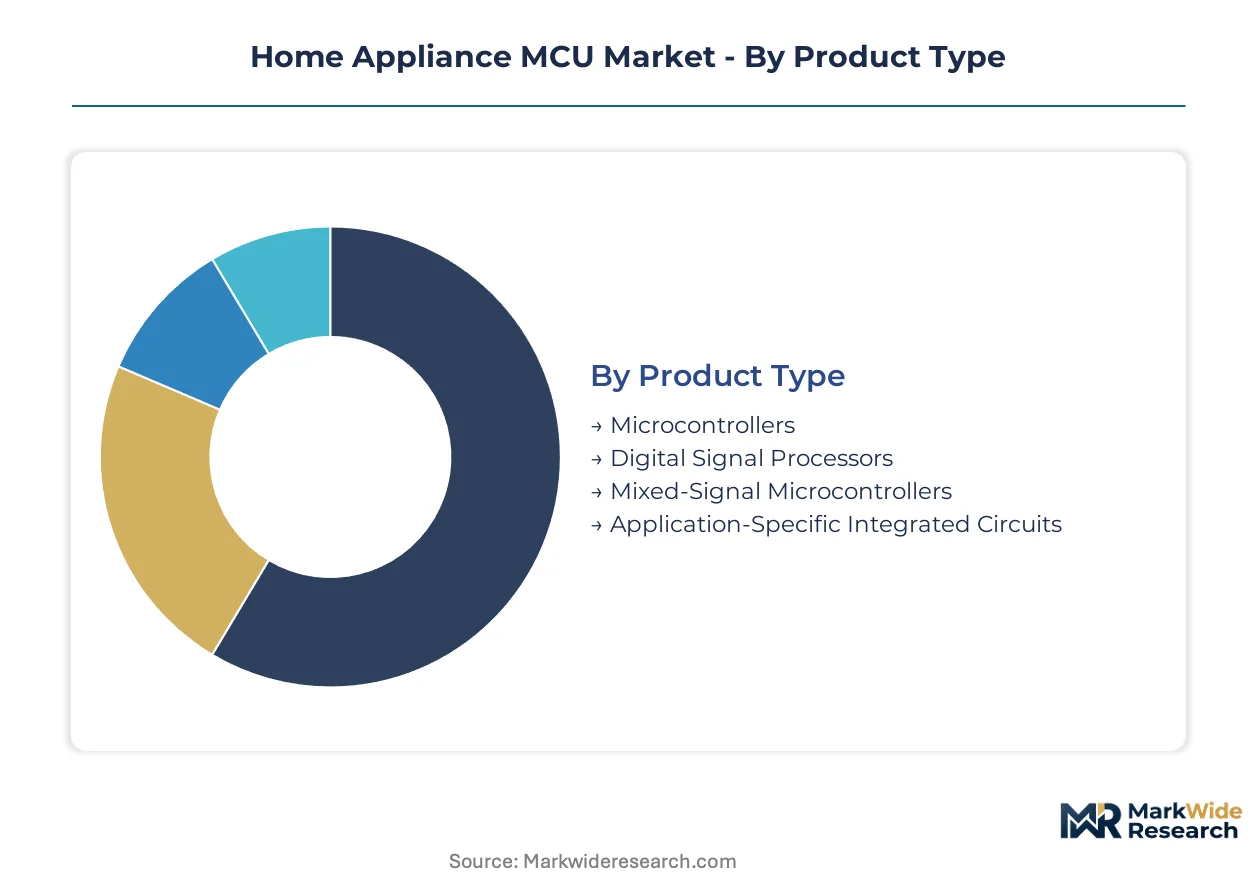
MCU segmentation in home appliances tracks how processing architectures map to distinct procurement channels and margin structures. Appliance OEMs source standard microcontrollers through consolidated vendor programs while reserving mixed-signal variants for specialized sensing subsystems.
Product Type:
Direct sales dominate high-volume microcontroller procurement for motor-control platforms, while distribution channels handle smaller-lot ASIC and DSP orders from mid-tier OEMs.
- Microcontrollers:These 16-480 MHz cores with 32 KB-2 MB flash execute deterministic motor-control algorithms in washing machines and HVAC compressors. Guangdong-based white-goods manufacturers specify 32-bit ARM Cortex-M4 variants with integrated touch-sensing for control panel consolidation.
- Mixed-Signal Microcontrollers:Combining analog front-ends with digital processing cores, these devices capture precision temperature and humidity data in refrigeration compressors. South Korean refrigerator OEMs deploy these for localized leak-detection nodes that reduce cloud dependency for safety alerts.
- Digital Signal Processors:Vector-optimized cores for complex audio processing and advanced motor-control algorithms in premium appliance tiers.
- Application-Specific Integrated Circuits:Custom-fabricated logic for proprietary inverter-drive architectures in high-efficiency air conditioners.
By volume, Microcontrollers leads. By growth pace, Mixed-Signal Microcontrollers is climbing the fastest.
Feature:
Cost-tier differentiation separates premium SKUs with full wireless stacks from economy variants where processing speed alone determines BOM allocation.
- Connectivity:Integrated Wi-Fi and Bluetooth stacks enable remote diagnostics and smart-home integration. Mid-tier washing machine and dishwasher platforms in China are absorbing these features as baseline specifications.
- Energy Efficiency:Sub-100-mW sleep modes address EU Ecodesign Directive standby power limits. Refrigerator and dishwasher MCU upgrades across European export programs center on this capability.
- Processing Speed:Clock-rate specifications differentiate real-time control responsiveness in inverter motor drives.
- Integration Capabilities:Peripheral consolidation reduces external component counts for cost-sensitive appliance categories.
By volume, Energy Efficiency leads. By margin expansion, Connectivity is gaining share fastest.
End User:
Volume concentration flows through OEM procurement offices, while aftermarket and repair channels fragment across distributor networks.
- Manufacturers:Captive MCU demand from integrated white-goods producers in Shandong province drives 32-bit motor-control specifications with multi-year volume commitments.
- OEMs:Contract manufacturers for global appliance brands specify certified MCUs with IEC 60730 Class B compliance for automatic electrical controls.
- Retailers:Private-label appliance programs source connectivity-enabled MCUs through consolidated vendor relationships.
- Aftermarket:Replacement control boards for legacy appliances sustain demand for discontinued 8-bit architectures.
- Repair Services:Technical service networks procure MCU-based subassemblies through authorized distributor channels.
By volume, Manufacturers leads. By specification influence, OEMs is expanding most quickly.
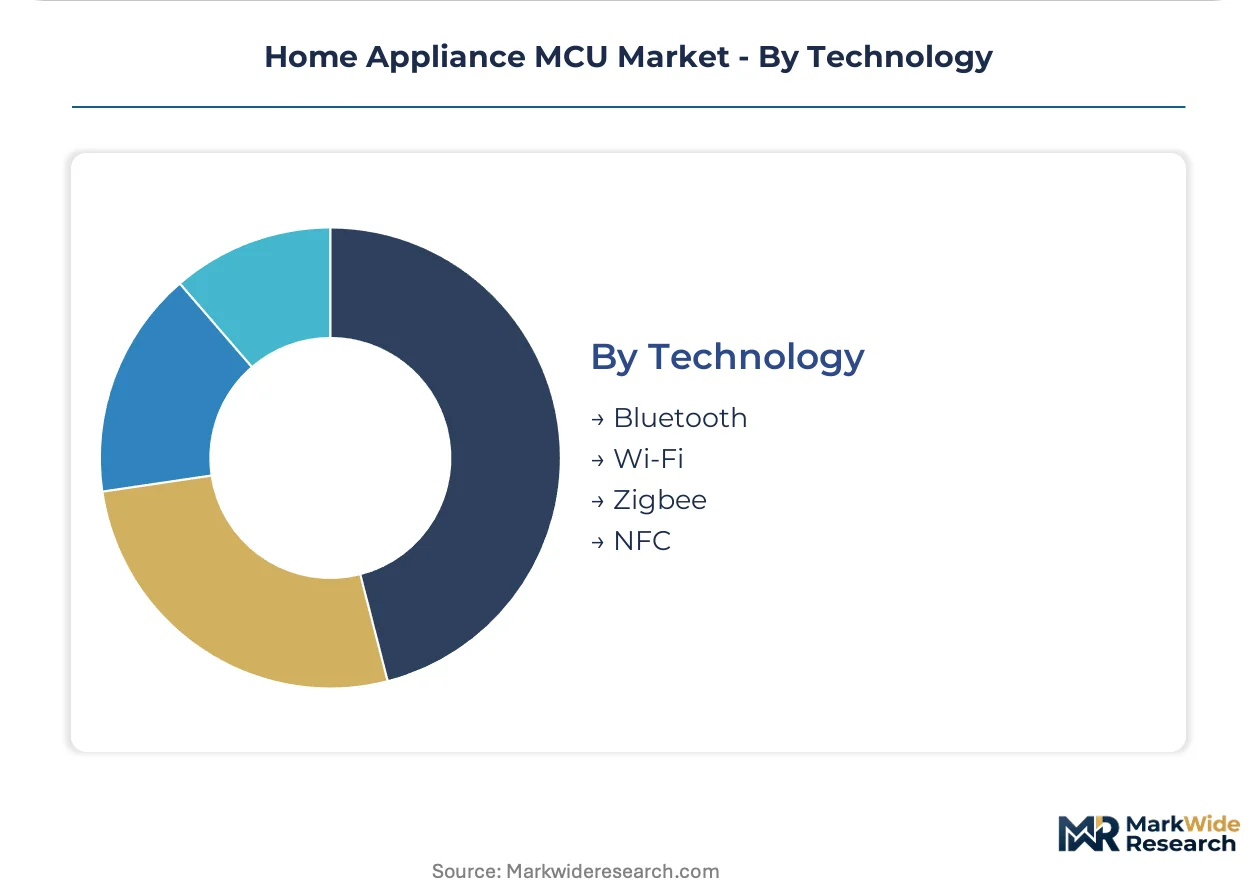
Technology:
Protocol selection determines geographic market access, with Matter-compatible Wi-Fi variants penetrating North American and European channels while Bluetooth dominates Asian smart-home ecosystems.
- Wi-Fi:TCP/IP-enabled MCUs support cloud-connected diagnostics and over-the-air firmware updates. The protocol is migrating from premium to mid-tier appliance tiers as module costs compress.
- Bluetooth:Low-energy variants enable smartphone pairing for localized appliance control. Japanese and South Korean refrigerator OEMs favor this for proximity-based user interfaces.
- Zigbee:Mesh-networking protocol for whole-home automation integration in European markets.
- NFC:Near-field commissioning for factory setup and service technician diagnostics.
By volume, Bluetooth leads. By ecosystem convergence, Wi-Fi shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. European OEMs prioritize sub-100-mW sleep modes for regulatory compliance, while Chinese manufacturers emphasize touch-integrated motor-control cores for cost consolidation. Indian procurement centers on power-factor-corrected inverters under production-linked incentive programs.
China
Guangdong and Shandong provinces concentrate domestic white-goods manufacturing, generating captive demand for 32-bit ARM Cortex-M4 MCUs with integrated touch-sensing peripherals. MIIT circular economy mandates enforce recyclability and power-consumption thresholds that shape MCU specification sheets for export-bound manufacturers. Shenzhen-based design houses are compressing BOM counts through peripheral consolidation.
Germany
Industrial appliance OEMs specify IEC 60730 Class B certified MCUs for automatic electrical controls in premium HVAC systems. The EU Ecodesign Directive's tightening standby power limits are forcing sub-100-mW sleep mode adoption across refrigerator and dishwasher platforms. Bavaria-based automation suppliers are migrating automotive-grade process technologies into home appliance safety systems.
United States
EPA ENERGY STAR program benchmarks shape efficiency specifications for washing machine and refrigerator control boards. Smart-home ecosystem fragmentation is collapsing as Matter protocol convergence enables single-SKU wireless MCU designs. Texas-based semiconductor distributors are consolidating vendor relationships to reduce qualification overhead for mid-tier appliance OEMs.
India
The PLI scheme for white goods is creating captive demand for motor-control MCUs with integrated power factor correction in air conditioner manufacturing. BIS standards enforce domestic efficiency thresholds that influence import substitution strategies for 32-bit control architectures. Gujarat and Maharashtra production clusters are absorbing multi-year volume commitments from global appliance brands.
South Korea
Premium refrigerator OEMs deploy edge AI inference cores with 512 KB+ SRAM pools for localized compressor anomaly detection. MFDS-equivalent safety regulations for electrical controls mandate redundant clock monitoring in smart appliance subsystems. Seoul Capital Area design centers are bifurcating MCU roadmaps between deterministic motor control and connectivity-heavy application processors.
Home Appliance MCU Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Home Appliance MCU Market. Renesas Electronics Corporation, NXP Semiconductors, and STMicroelectronics anchor the consolidated upper tier through multi-protocol wireless portfolios and automotive-grade process migration. Mid-scale specialists concentrate on mixed-signal integration for precision sensing nodes. Competitive dynamics center on strategic partnerships for Matter protocol certification and backward integration into captive foundry capacity.
Within the integrated tier, Renesas Electronics Corporation exemplifies the motor-control specialist archetype through its RX and RA product families. NXP Semiconductors occupies a position bridging automotive-grade reliability standards with home appliance safety system requirements. STMicroelectronics anchors the touch-sensing integration segment with peripheral consolidation strategies that reduce external component counts for OEMs.
| Leading Market Players |
|---|
| Renesas Electronics Corporation |
| NXP Semiconductors |
| STMicroelectronics |
| Microchip Technology |
| Infineon Technologies |
| Texas Instruments |
| ON Semiconductor |
| Silicon Laboratories |
| Espressif Systems |
| Others |
Pricing and Supply Chain Analysis
Long-term volume commitments from Guangdong and Shandong white-goods manufacturers lock in both foundry wafer allocation and price visibility for 32-bit motor-control MCUs, insulating tier-one OEMs from spot-market volatility while compressing margins for distributors serving fragmented mid-tier buyers.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement for washing machine and air conditioner platforms, with pricing stratifying across IEC 60730 Class B certified, automotive-grade qualified, and economy-tier SKUs. Certification grade and volume scale drive price differentiation, with multi-year commitments securing 15-20 point discounts over spot purchases. Cost compression in connectivity-enabled sub-$5 MCUs is intensifying because Wi-Fi and Bluetooth stack integration erodes margins without corresponding ASP recovery. Contract manufacturers serving private-label retailers exhibit highest price sensitivity, while premium refrigerator OEMs in South Korea and Japan prioritize edge AI feature sets over unit cost.
Supply Chain Analysis
Strategic stockpiling of legacy 8-bit and 16-bit MCUs persists among aftermarket repair networks, while tier-one OEMs pursue just-in-time delivery of 32-bit ARM Cortex-M4 variants from Taiwan-based pure-play foundries. Wafer fabrication concentrates in Taiwan, South Korea, and the United States, with advanced node capacity constraints creating allocation bottlenecks for automotive-grade MCUs migrating into appliance safety systems. Silicon feedstock, halogen-free mold compounds, and lead-free solder ball arrays constitute critical input dependencies. Single-source vulnerability at 300mm foundries represents the dominant structural risk. Distribution runs through authorized channels for certified MCUs and gray-market brokers for discontinued architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart-home ecosystem fragmentation is collapsing into Matter protocol convergence, creating specialized niches for mixed-signal integration and edge AI inference cores that incumbent broadline suppliers under-serve.
For Market Incumbents: Fortify captive foundry relationships through multi-year wafer agreements and backward integration into 40nm process nodes for motor-control ASICs. The automotive-grade MCU migration threat from NXP and Renesas demands accelerated IEC 60730 Class B certification pipelines. Channel control through consolidated vendor programs reduces qualification overhead and locks out specialist competitors. For New Entrants and Emerging Players: Precision sensing firmware customization gaps in HVAC compressor nodes offer white-space entry where STMicroelectronics and Microchip Technology maintain standardized catalog approaches. India's PLI scheme for air conditioner manufacturing represents the most penetrable geography for power-factor-corrected motor-control MCUs. A technical service partnership model with Gujarat and Maharashtra production clusters bypasses incumbent distribution lock-in. For Investors and Strategic Acquirers: Capital is best deployed toward mixed-signal specialists with integrated analog front-end IP and existing Matter protocol certifications, positioned for 5-10 year viability as edge AI inference expands beyond premium tiers. The inflection signal to watch is compressor OEM adoption of predictive maintenance algorithms requiring 512 KB+ SRAM pools, which would validate vector DSP extension roadmaps and expand addressable margins.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Single-SKU wireless MCU designs collapse fragmentation risk across North American and European smart-home ecosystems. |
| Backward Integration into 40nm Foundry Capacity | Captive wafer supply insulates against Taiwan-based pure-play allocation bottlenecks for automotive-grade safety MCUs. |
| Edge AI Inference Core Development | Vector DSP extensions with 512 KB SRAM pools enable localized compressor anomaly detection for South Korean refrigerator OEMs. |
| Halogen-Free Packaging Redesign | REACH-compliant mold compounds and lead-free solder ball arrays secure EU market access for export-bound Chinese manufacturers. |
| Technical Service Partnership Model | Direct engagement with Gujarat and Maharashtra air conditioner clusters bypasses consolidated distributor relationships. |
Research Methodology
Desk research of semiconductor trade databases, customs records, and IEC certification registries preceded structured interviews with MCU product managers at tier-one suppliers, appliance OEM procurement directors in Guangdong and Shandong provinces, and firmware engineering leads at white-goods design houses. Primary fieldwork captured design-win dynamics, foundry allocation practices, and regulatory compliance timelines. Secondary validation drew from MIIT circular economy filings, EPA ENERGY STAR specification sheets, and EU Ecodesign Directive implementation guidance. Bottom-up unit shipment estimates triangulated against top-down semiconductor revenue disclosures.
Variance decomposition across product type, feature tier, end-user channel, and wireless protocol technology shaped the analytical framework throughout the projection horizon. CAGRs derived from shipment growth curves indexed to appliance production forecasts and MCU content-per-unit expansion in connectivity-enabled platforms. Modeled inputs included motor-control algorithm complexity migration, standby power regulation thresholds, and smart-home interoperability standard adoption rates.
Forecasts assume regulatory continuity in EU Ecodesign Directive implementation, EPA ENERGY STAR program benchmarks, and China's GB standards enforcement; material policy shifts would require re-modeling. Revision becomes warranted when foundry capacity utilization crosses thresholds that trigger allocation rationing or when Matter protocol certification timelines compress competitive windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Japan Semiconductor Diode Market
Semiconductor Devices
Finfet Technology Market
Semiconductor Devices
Global Bipolar Small Signal Transistor Market
Semiconductor Devices
Spin Filters Market
Semiconductor Devices
Gan-On-Silicon Market
Semiconductor Devices
Middle East and Africa Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Die Spacer Market
Semiconductor Devices
Hybrid Microcircuits Market
Semiconductor Devices
Japan International CEP Market
Semiconductor Devices
Dual Voltage Comparator Market
Semiconductor Devices
Mosfet Power Transistors Market
Semiconductor Devices
APAC Semiconductor Device for Processing Applications Market
Semiconductor Devices
Superconductor Wire Market
Semiconductor Devices
TC-SAW Filter Market
Semiconductor Devices
China Semiconductor Diode Market
Semiconductor Devices
Semiconductor Device in Aerospace and Defense Industry Market