
 Advanced IC Substrates Market | 2026-2036
Advanced IC Substrates Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced IC Substrates Market Intelligence
The EU's Corporate Sustainability Reporting Directive (CSRD) is pivoting procurement strategies toward suppliers with transparent carbon footprints and documented material traceability. In this context, Unimicron leverages its manufacturing scale to supply high-volume smartphone and consumer electronics clients. Concurrently, AT&S specializes in high-reliability substrates for the automotive and medical device sectors, where long-term performance is critical. TTM Technologies competes by offering a broad portfolio across different substrate technologies for diverse end markets.
Advanced IC substrates are the critical interface connecting a semiconductor die to a printed circuit board, enabling electrical connectivity and providing mechanical support. These components are characterized by features like microvias and thin-film lamination, essential for managing the high input/output density of modern chips. Flip Chip product types dominate the market, favored for high-performance computing applications. The data centers segment represents the fastest-growing application, driven by the build-out of infrastructure for AI and cloud services.
Compliance with standards from the International Electrotechnical Commission (IEC) and ISO is fundamental for ensuring product reliability and global market access. Environmental regulations, including the EU's RoHS directive, directly influence material selection by restricting hazardous substances in substrate fabrication. For manufacturers, the central strategic challenge involves managing the trade-off between escalating performance demands from chip designers and the associated material and process costs.
Market Dynamics
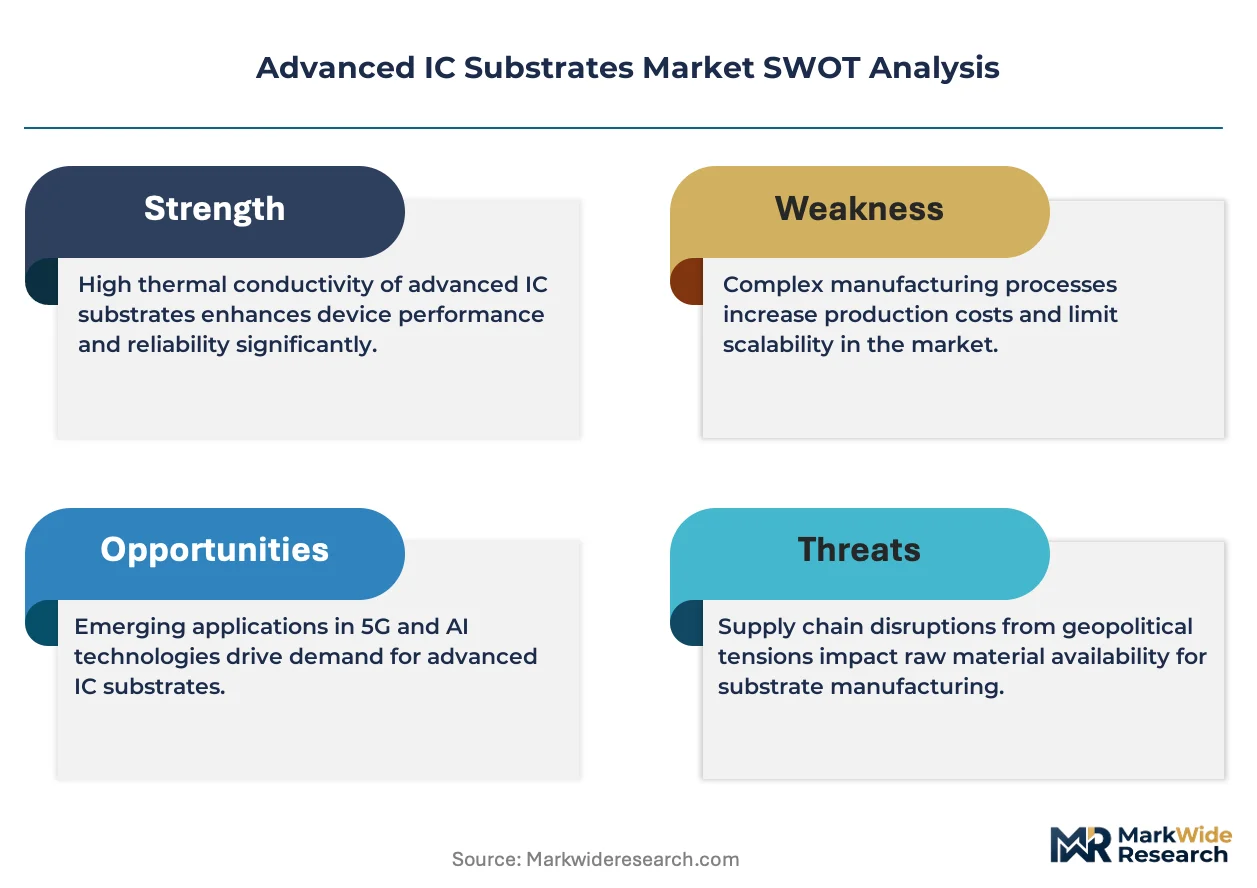
The central tension in the advanced IC substrate market is the escalating performance requirement from chip designers, driven by AI workloads, against the physical and cost limitations of substrate fabrication processes, materials, and capital-intensive manufacturing capacity.
Growth Catalysts
- Chiplet Architectures:The transition to chiplet designs for high-performance computing requires larger, more complex substrates, directly stimulating demand for advanced interconnects.
- Data Center Expansion:Hyperscale infrastructure build-outs for AI and cloud services generate sustained demand for flip-chip substrates capable of high power delivery.
- National Semiconductor Initiatives:Policies like the US CHIPS Act and EU Chips Act incentivize domestic investment in advanced packaging and substrate manufacturing capacity.
Market Restraints
- Material Cost Escalation:Rising costs for specialized materials like low-loss dielectrics and build-up films compress manufacturer margins and increase final component prices.
- Geographic Concentration:Heavy concentration of advanced substrate capacity in Taiwan and South Korea exposes the global supply chain to geopolitical and logistical risks.
- Manufacturing Yield Limits:Poor yield rates for large-bodied substrates, essential for complex AI accelerators, present a significant manufacturing and cost barrier.
Strategic Opportunities
- Co-Packaged Optics:Integrating optical I/O directly into substrate packages offers a path to overcome electrical interconnect bandwidth limits in high-performance computing.
- Automotive Central Compute:The automotive industry's shift to centralized architectures for autonomous driving creates a new high-reliability market for advanced substrates.
- Glass Core Substrates:Developing glass core substrates provides an opportunity to deliver superior dimensional stability and electrical performance over traditional organic materials.
Industry Challenges
- Capital Expenditure Intensity:Immense capex is required for new fabrication lines with advanced lithography tools, creating a high barrier to entry and expansion.
- Talent Scarcity:A shortage of process engineers experienced in fine-pitch lamination and microvia drilling hinders production ramp-up efforts across the industry.
- Compliance Timelines:Meeting stringent reliability qualifications from automotive and aerospace clients involves lengthy and costly testing cycles, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced IC Substrates Market |
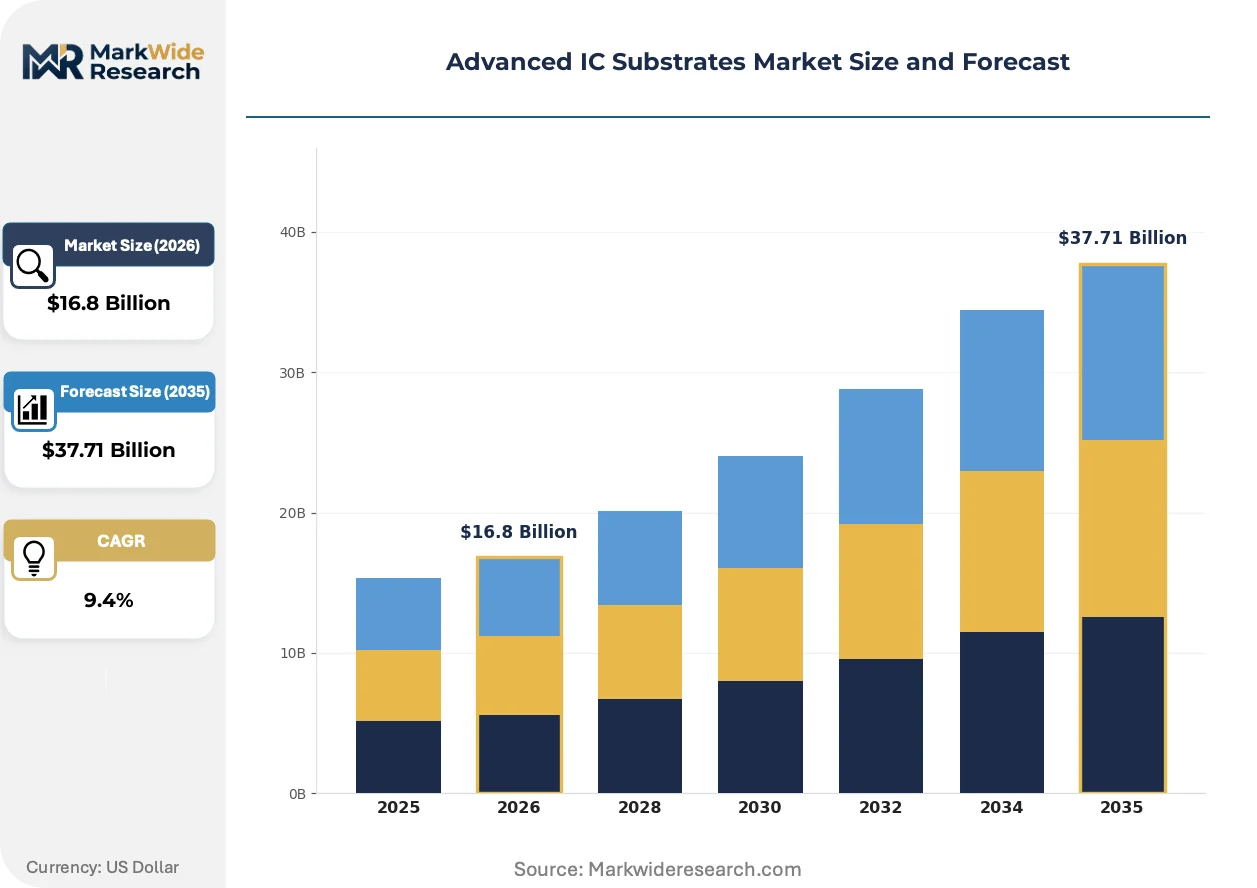
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $37.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Density Interconnect, Flip Chip, Embedded Die, Organic, Ceramic Technology: Through Silicon Via, Microvias, Laser Drilling, Thin-Film Lamination, Multi-Layer Lamination Application: Smartphones, Data Centers, Wearable Devices, Automotive Electronics, Telecommunication Equipment End User: Consumer Electronics OEMs, Cloud Service Providers, Medical Device Manufacturers, Semiconductor Foundries, Network Equipment Vendors |
| Companies Covered | ASE Group, TTM Technologies, Unimicron, Ibiden, AT&S, KYOCERA Corporation, Nan Ya PCB, Zhen Ding Technology, Shinko Electric Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced IC Substrates Market Strategic Shifts & Innovations
Material science advancements and new design methodologies are converging to meet unprecedented performance demands. Concurrently, sustainability mandates are beginning to influence material selection and supply chain transparency, altering competitive dynamics for substrate manufacturers.
Panel Level Packaging (PLP) processes substrates on large rectangular panels, significantly increasing manufacturing throughput compared to wafer-level methods. OSAT providers are adopting PLP to lower costs for high-volume mobile and consumer electronics applications. This technology is integrating fabrication-like efficiencies into the back-end process, enabling a lower cost-per-unit for certain chip designs.
The European Union's Corporate Sustainability Reporting Directive (CSRD) requires detailed disclosure of environmental impacts like carbon footprint and material provenance. This forces substrate manufacturers to implement robust traceability systems and report on supply chain emissions. Consequently, automotive and industrial clients are prioritizing suppliers with transparent CSRD-compliant reporting, making it a key selection criterion.
Hyperscale cloud providers and automotive OEMs are bringing chip design in-house, directly specifying substrate requirements to optimize system performance. This trend fosters a direct co-design relationship between the end-customer and the substrate manufacturer, bypassing some traditional intermediaries. This shift is most prominent within the data center market in the United States and Germany's automotive sector.
Advanced IC Substrates Market Segmentation
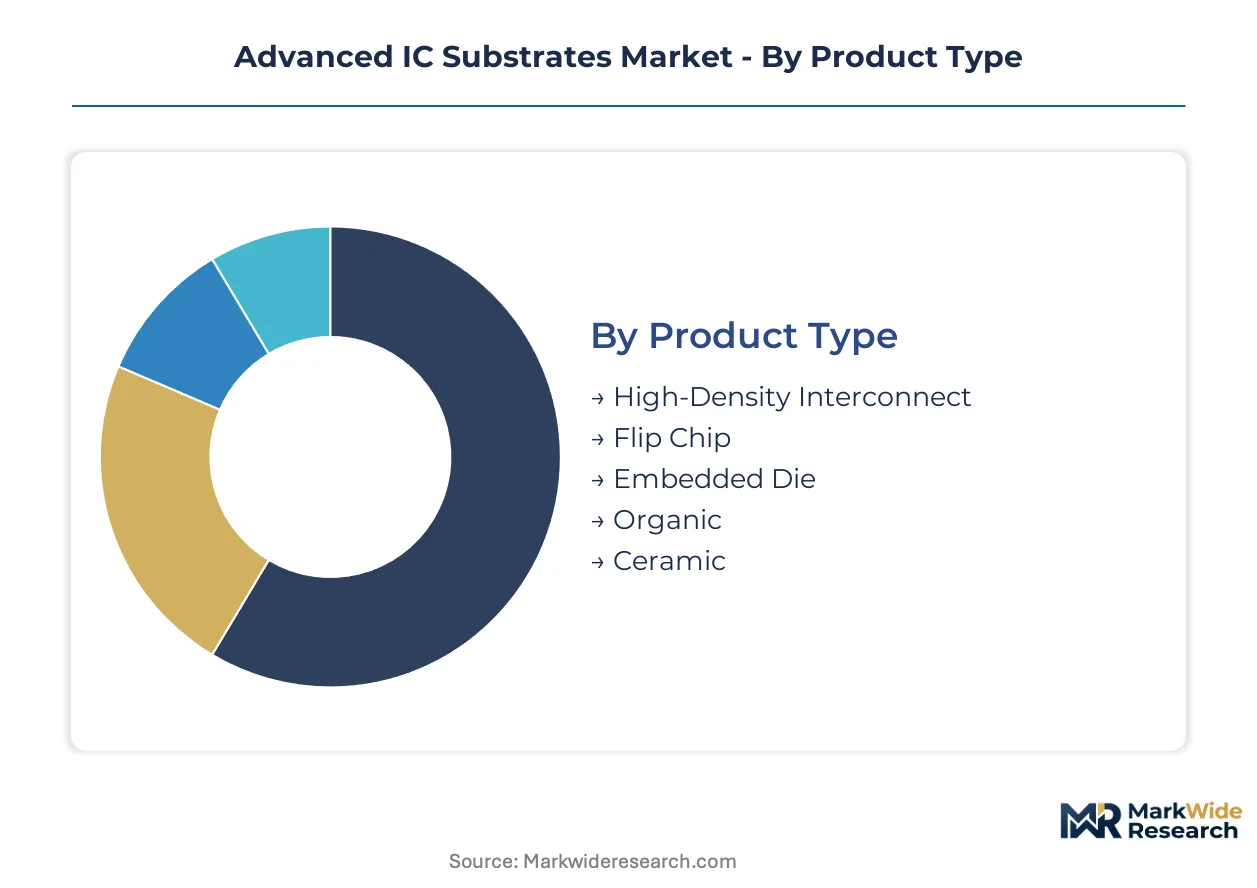
Advanced IC substrate market segmentation clarifies the diverse technical requirements and commercial priorities across its value chain. Different product types address specific performance envelopes for chip packaging. Technology variations reflect evolving integration demands and manufacturing capabilities, directly impacting end-product functionality and cost.
Product Type:
Buyers of advanced IC substrates prioritize specific electrical performance and form factor capabilities for their chip designs.
- Flip Chip:Flip Chip substrates facilitate direct electrical connection between the semiconductor die and the substrate via solder bumps, enabling superior signal integrity and thermal management. Demand concentrates in data centers for AI accelerators, driven by the need for high input/output density and efficient power distribution.
- High-Density Interconnect:High-Density Interconnect substrates feature fine line widths, spaces, and microvias, enabling compact designs for complex integrated circuits. These substrates find significant demand in high-volume smartphone manufacturing, supporting miniaturization and multi-functionality in consumer electronics.
- Embedded Die:These substrates integrate unpackaged semiconductor dies directly within the substrate layers, reducing package size and improving electrical performance.
- Organic:Organic substrates, typically made from epoxy resins and fiberglass, offer cost-effective solutions for a broad range of consumer electronics applications.
- Ceramic:Ceramic substrates provide excellent thermal conductivity and dimensional stability, making them suitable for high-power modules and harsh environment applications.
Volume sits with Organic; growth tilts toward Flip Chip.
Technology:
The choice of substrate technology directly impacts the achievable integration density and electrical performance of packaged chips.
- Microvias:Microvias are tiny, laser-drilled or photo-defined holes connecting different layers of a substrate, enabling high-density routing and reduced signal path lengths. Their application is critical in advanced packaging for AI accelerators, where high I/O counts necessitate extremely fine-pitch interconnections.
- Thin-Film Lamination:Thin-film lamination processes involve depositing dielectric and conductive layers with exceptional precision, creating ultra-fine circuit patterns on the substrate surface. This technology is increasingly vital for high-performance computing modules, supporting the miniaturization and increased functionality of advanced chiplet designs.
- Through Silicon Via:Through Silicon Via (TSV) creates vertical electrical connections through the silicon die itself, enabling 3D stacking and extremely short interconnects for memory and logic.
- Laser Drilling:Laser drilling precisely forms microvias and other intricate features in substrate materials, facilitating high-density interconnects in complex designs.
- Multi-Layer Lamination:This technique builds up multiple conductive and dielectric layers, providing complex routing capabilities for sophisticated semiconductor packages.
Microvias technology underpins most advanced substrate designs; Through Silicon Via is expanding most quickly for future 3D integration.
Application:
Different applications demand varying levels of performance, reliability, and cost-efficiency from advanced IC substrates.
- Data Centers:Data centers utilize advanced IC substrates for high-performance processors, memory modules, and AI accelerators, demanding exceptional power delivery and signal integrity. Hyperscale infrastructure build-outs for AI workloads generate sustained demand for flip-chip substrates in the United States and Germany.
- Automotive Electronics:Automotive electronics require advanced IC substrates that can withstand harsh operating environments, ensuring long-term reliability for critical safety and autonomous driving systems. The industry's shift to centralized architectures for autonomous driving creates a new high-reliability market for advanced substrates in Germany and Japan.
- Smartphones:Smartphones drive high-volume demand for compact, multi-functional substrates that enable miniaturization and integration of diverse components.
- Wearable Devices:Wearable devices require ultra-small and flexible substrates, prioritizing power efficiency and space optimization for portable applications.
- Telecommunication Equipment:Telecommunication equipment, including 5G infrastructure, demands high-frequency and high-speed substrates for efficient data transmission.
Data Centers provide the highest revenue contribution; Automotive Electronics exhibits the steepest expansion trajectory.
End User:
End users' procurement strategies and product development cycles significantly shape the demand for advanced IC substrates.
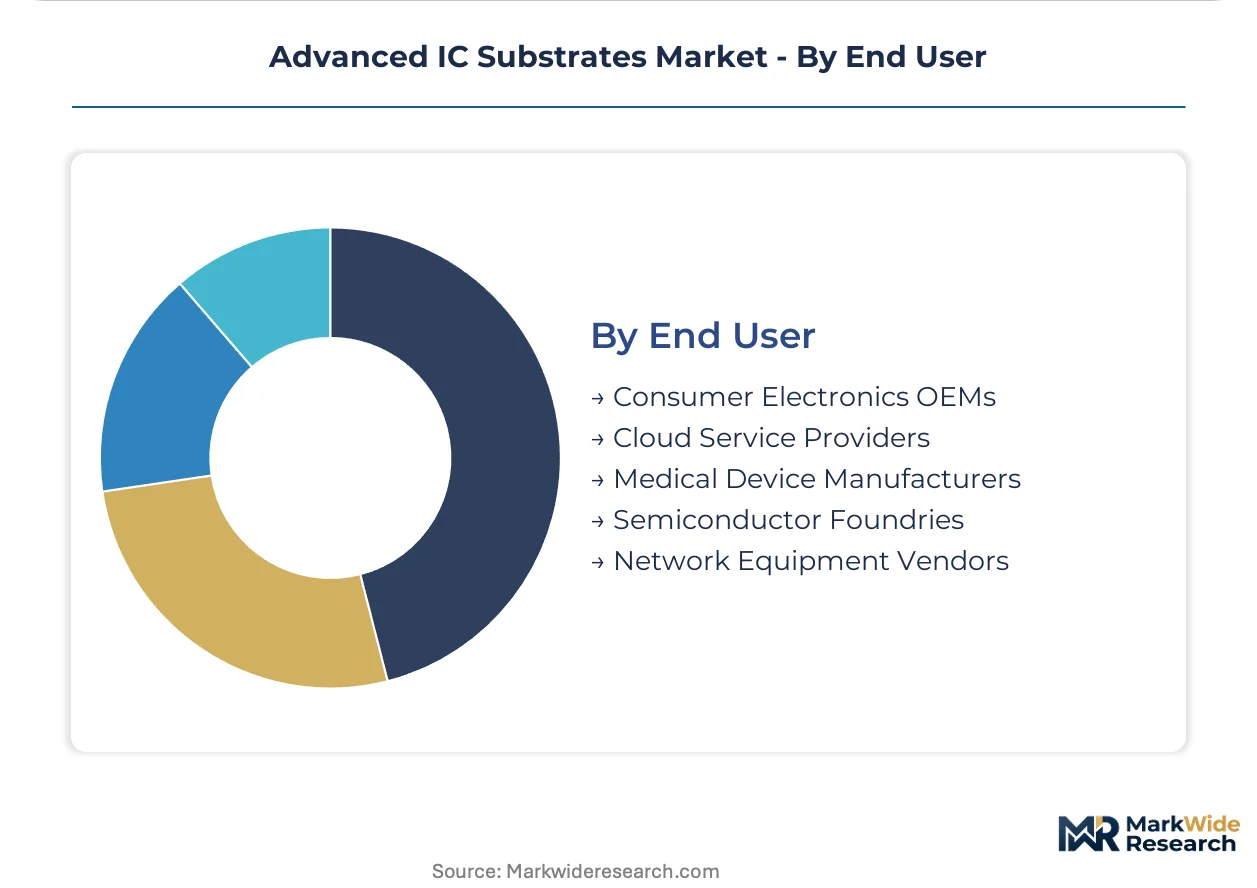
- Cloud Service Providers:Cloud Service Providers directly procure advanced IC substrates for their custom-designed AI accelerators and server processors, emphasizing performance optimization and supply chain control. This segment, particularly in the United States, drives co-design relationships with substrate manufacturers, bypassing traditional intermediaries for optimal system integration.
- Consumer Electronics OEMs:Consumer Electronics OEMs demand high-volume, cost-effective advanced IC substrates for products like smartphones and laptops, balancing performance with aggressive pricing targets. Procurement for this segment, concentrated in Taiwan and South Korea, focuses on suppliers capable of mass production and rapid turnaround times.
- Medical Device Manufacturers:Medical device manufacturers require highly reliable and often miniaturized substrates, adhering to stringent regulatory standards for patient safety.
- Semiconductor Foundries:Semiconductor foundries, while primarily chip producers, influence substrate demand by specifying packaging requirements for their advanced process nodes.
- Network Equipment Vendors:Network Equipment Vendors procure advanced substrates for high-speed routers, switches, and 5G base stations, prioritizing signal integrity and thermal performance.
Consumer Electronics OEMs dominate market share; Cloud Service Providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taipei's robust semiconductor ecosystem drives significant advanced IC substrate demand. Major foundries and packaging facilities in Taiwan and South Korea underpin global supply, supporting high-volume consumer electronics and advanced computing applications. United States and German markets also show strong growth for specialized, high-reliability substrates.
Taiwan
High-volume smartphone manufacturing and advanced chiplet designs drive substrate demand in Taiwan. The EU's RoHS directive influences material selection for substrates destined for European markets. Hsinchu Science Park in Taiwan anchors advanced packaging and foundry operations, attracting significant capital investment.
South Korea
High-density interconnects for consumer electronics and memory chip packaging fuel market expansion in South Korea. The country's national semiconductor initiatives support capacity expansion and technological innovation. Gyeonggi Province in South Korea hosts major memory and logic chip manufacturers, creating localized demand.
United States
Hyperscale data centers, AI accelerators, and co-packaged optics development generate substantial demand in the United States. The US CHIPS Act incentivizes domestic advanced packaging and substrate manufacturing capacity. Silicon Valley in California drives co-design relationships between cloud providers and substrate makers.
Germany
High-reliability substrates for automotive central compute and industrial applications define demand in Germany. The EU's CSRD mandates transparent carbon footprints for suppliers, influencing procurement decisions. Dresden in Germany focuses on specialized automotive and industrial electronics fabrication.
Japan
Advanced packaging for high-performance computing and medical devices drives demand in Japan. METI policies promote innovation in advanced materials and manufacturing processes. Kyushu Island in Japan specializes in advanced semiconductor material production and sophisticated packaging solutions.
Advanced IC Substrates Market Key Industry Players
The competitive structure tilts toward a tiered market, where specialized capabilities differentiate players. Three distinct archetypes include high-volume consumer electronics suppliers, high-reliability specialists, and broad portfolio providers. Competitive moves frequently involve capacity expansion to meet demand surges and technology diversification into emerging applications.
Specialists in high-volume consumer electronics packaging like Unimicron exemplify scale-driven manufacturing. AT&S occupies a position within the high-reliability segment, focusing on demanding automotive and medical applications. TTM Technologies represents the broad portfolio archetype, offering diverse substrate technologies across multiple end markets.
| Leading Market Players |
|---|
| ASE Group |
| TTM Technologies |
| Unimicron |
| Ibiden |
| AT&S |
| KYOCERA Corporation |
| Nan Ya PCB |
| Zhen Ding Technology |
| Shinko Electric Industries |
| Others |
Cost & Logistics Intelligence
Sovereign-backed producers in Asia shape advanced IC substrate pricing, reflecting their capital-intensive investments which influence supply availability and cost structures. The market navigates a complex interplay between high-performance demands and the economic realities of specialized material procurement.
Pricing Analysis
Outcome-based pricing anchors advanced IC substrates, reflecting their critical role in chip performance. Price differentiation stems from certification level for automotive clients and customization for AI accelerators. Pricing softness runs through high-volume consumer electronics due to intense competition. Cloud Service Providers exhibit the least price sensitivity, prioritizing performance and reliability for their hyperscale operations.
Supply Chain Analysis
Elevated logistics costs for advanced IC substrates impact global delivery timelines and final component prices. Supply concentrates in Taiwan and South Korea, drawing from specialized low-loss dielectrics and build-up films. Geopolitical risks in these regions present a significant supply chain vulnerability. Distribution runs through OSAT providers for high-volume applications and directly to hyperscale clients for custom designs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The advanced IC substrates market is a consolidation play, driven by immense capital expenditure intensity that pressures smaller firms. Larger players acquire specialized capabilities to meet evolving performance demands.
For Market Incumbents: Extend existing process engineering talent pools through targeted university partnerships to counter talent scarcity. Deepen co-design relationships with hyperscale cloud providers to mitigate competitive threats from emerging material science innovations. Invest in advanced lithography tools to maintain technological leadership against new entrants. Focus R&D on glass core substrates to address future performance demands.
For New Entrants and Emerging Players: Launch specialized, high-reliability substrates via direct sales to automotive OEMs in Germany, targeting central compute architectures. Focus on niche applications requiring advanced material science, like co-packaged optics, where established players may be slower to adapt. The medical device sector represents a penetrable segment due to its stringent, but less volume-driven, qualification cycles. Emphasize compliance with IEC and ISO standards as a key value proposition.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized substrate manufacturers in Taiwan with strong intellectual property in thin-film lamination for long-term growth. The market offers viable returns over a five to ten-year horizon, particularly for firms with established client relationships in data centers. Target mid-cap companies possessing unique material science capabilities or advanced packaging patents. The signal to watch is sustained capital expenditure by major foundries in advanced packaging facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Advanced Packaging | Ensures supply for increasing demand from data centers and chiplet architectures. |
| R&D Investment in Glass Core Substrates | Delivers superior dimensional stability and electrical performance for high-performance computing. |
| Strategic Partnerships with AI Chip Designers | Fosters co-design relationships, optimizing substrate requirements for next-generation AI accelerators. |
| Acquisition of Microvia Drilling Specialists | Addresses talent scarcity and improves manufacturing yield rates for complex substrate designs. |
| ESG Compliance and Traceability System Implementation | Meets EU's CSRD mandates, influencing procurement decisions from automotive and industrial clients. |
Research Approach
Independent corroboration across industry association reports, regulatory filings, and academic research underwrites the qualitative findings. This study integrated primary interviews with R&D directors, procurement managers, and process engineers from leading substrate manufacturers and end-users. Secondary data sources included financial reports, patent databases, and trade statistics from Taiwan and South Korea. Bottom-up and top-down triangulation validated market size estimations.
Rate-of-change decomposition modeled market evolution across the analysis window, considering technological advancements and application shifts. Segmentation dimensions included product type, technology, application, end-user, and regional manufacturing capacity. Compound Annual Growth Rates were derived from historical trends, industry expert consensus, and projected capital expenditure cycles. Data center expansion for AI workloads and chiplet architecture adoption served as key forecast inputs.
Geopolitical instability, material cost volatility, and rapid technological shifts are the dominant revision risks for advanced IC substrate forecasts. All projections reflect assumptions about future market dynamics and regulatory environments. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Europe Microcontroller (MCU) Market
Semiconductor Devices
DNA Chip Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Japan MLCC Market
Semiconductor Devices
Programmable Logic Device (PLD) Market
Semiconductor Devices
Europe Microcontroller Market
Semiconductor Devices
Plastic Transistors Market
Semiconductor Devices
Asia-Pacific Semiconductor Diode Market
Semiconductor Devices
Global Gan Semiconductor Device Market
Semiconductor Devices
Global Semiconductor Lead Frame Market
Semiconductor Devices
Global Trench Gate Power MOSFET Market
Semiconductor Devices
Bipolar Junction Transistors Market
Semiconductor Devices
Asia-Pacific MLCC Market
Semiconductor Devices
Gallium Oxide Transistor Market
Semiconductor Devices
TC-SAW Filter Market
Semiconductor Devices
Global Semiconductor Device Market